
 Autonomous Aircraft Market | 2026-2036
Autonomous Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Aircraft Market Analysis
The EU Green Deal's emissions targets for aviation is realigning R&D priorities toward electric and hydrogen-powered autonomous platforms. Boeing anchors its position through integrated defense-commercial development pipelines for next-generation uncrewed systems. Lockheed Martin leverages Skunk Works capabilities to sustain technology leadership in high-altitude, long-endurance platforms. Northrop Grumman dominates the Global Hawk segment with established manufacturing scale and channel control into NATO procurement frameworks.
An autonomous aircraft operates without onboard human pilots, relying on sensor fusion, artificial intelligence flight control, and redundant communication links to execute predefined or adaptive missions. These systems typically integrate LiDAR, radar, and electro-optical payloads to navigate complex airspace and deliver cargo, intelligence, or passengers with minimal ground operator intervention. Cargo Delivery applications lead current revenue generation, while Passenger Transport represents the fastest-growing segment as VTOL technology matures and urban air mobility infrastructure develops. Multi-Rotor systems occupy the dominant technology position for short-range missions, though Hybrid configurations are gaining structural importance for extended range and payload flexibility requirements.
The FAA's Part 107 waiver system and emerging type certification standards for uncrewed aircraft are shaping market access timelines and product development roadmaps for U.S. manufacturers. EASA's regulatory framework for drone operations and the EU AI Act's algorithmic transparency requirements are creating parallel compliance obligations for European market entry. Stakeholders must monitor certification harmonization between FAA and EASA frameworks, as divergence in pilot-equivalent safety standards will fragment development costs and deployment timelines across jurisdictions.
Market Dynamics
Defense procurement concentration in the United States is compressing development timelines for dual-use autonomous platforms, while FAA certification bottlenecks for beyond-visual-line-of-sight operations are forcing manufacturers to sequence commercial deployment behind military validation.
Growth Catalysts
- FAA Part 107 waiver expansion:The FAA's evolving framework for uncrewed aircraft system operations is opening controlled airspace access for logistics operators in Texas and California corridors.
- Urban air mobility infrastructure:Vertiport construction in Dallas-Fort Worth and Los Angeles is creating dedicated landing zones for autonomous passenger transport trials.
- LiDAR cost deflation:Solid-state sensor manufacturing scale-up is reducing per-unit navigation system costs for last-mile delivery platforms.
Market Restraints
- High-altitude platform supply concentration:Stratospheric endurance aircraft rely on a limited supplier base for lightweight composite airframes, creating procurement vulnerability.
- Electro-optical payload import dependency:Advanced gimbal systems for ISR missions face sourcing constraints from concentrated Asian manufacturing clusters.
- Algorithmic validation costs:FAA pilot-equivalent safety standards require extensive simulation hours and flight testing, extending development burn rates.
Strategic Opportunities
- Middle East defense modernization:Saudi Arabia and UAE procurement frameworks are creating demand for autonomous surveillance platforms outside NATO supply chains.
- Hydrogen propulsion convergence:Fuel cell integration with electric vertical take-off systems is unlocking extended-range cargo missions previously reserved for fixed-wing aircraft.
- EASA regulatory harmonization:Alignment between FAA and European type certification pathways would reduce dual-compliance costs for manufacturers seeking transatlantic deployment.
Industry Challenges
- Autonomous systems engineering talent scarcity:Flight control algorithm development requires specialized expertise in sensor fusion and fail-safe architectures that outpaces university pipeline output.
- Ground control station integration complexity:Legacy military command networks demand custom interface development, fragmenting software architecture across customer deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Aircraft Market |
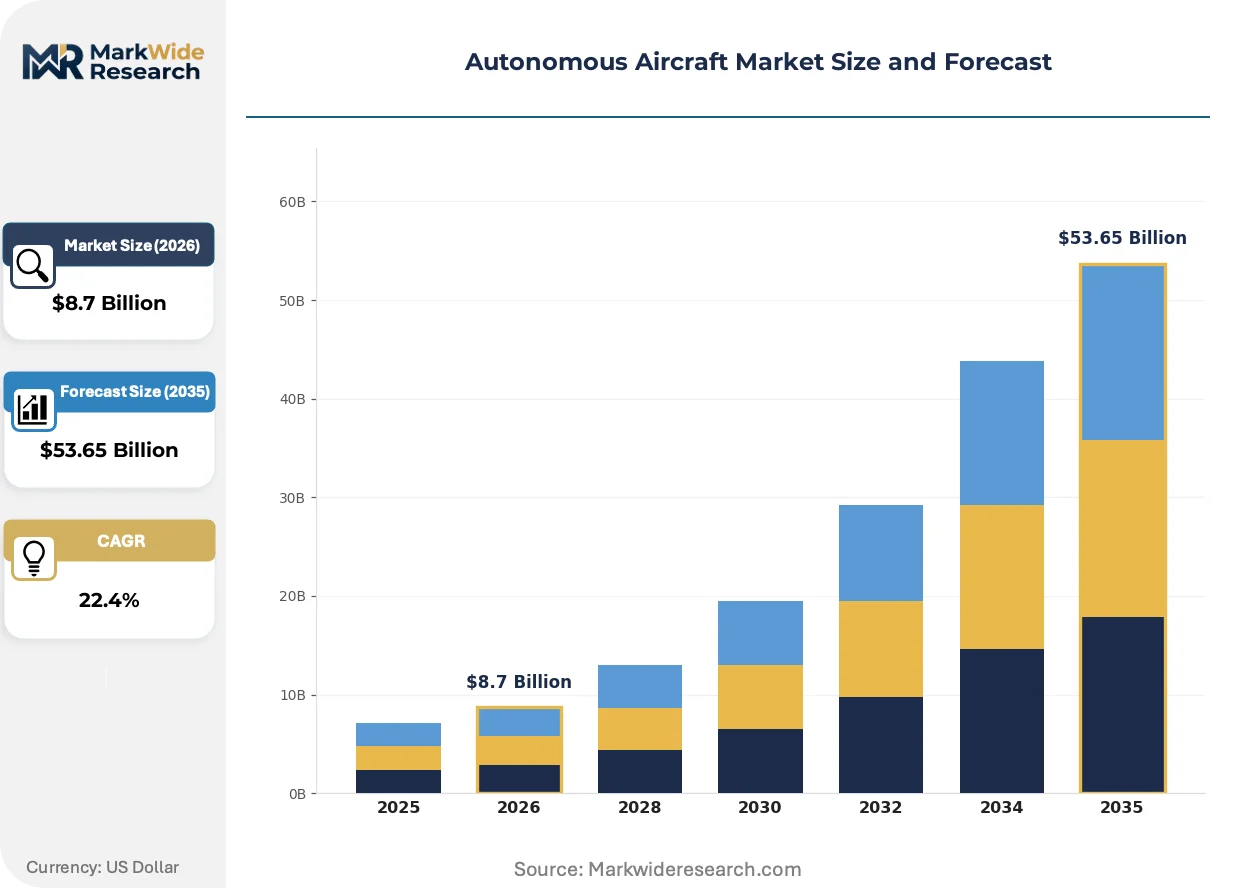
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Cargo Delivery, Surveillance, Agricultural Spraying, Passenger Transport Technology: Fixed-Wing, Multi-Rotor, Hybrid, VTOL End User: Government, Commercial, Research Institutions, Private Operators Payload Capacity: Less than 100 kg, 100-500 kg, 500-1000 kg, Above 1000 kg |
| Companies Covered | BAE Systems, General Atomics Aeronautical Systems, Boeing, AeroVironment, Shield AI, Lockheed Martin, Airbus, Anduril Industries, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Aircraft Market Emerging Trajectories
Artificial intelligence flight control architectures are displacing rule-based autopilot systems across both defense and commercial segments, compressing the gap between remotely piloted and fully autonomous operations.
Sensor fusion architectures combining LiDAR, millimeter-wave radar, and electro-optical feeds are unifying navigation and collision-avoidance functions into single computational stacks. Defense contractors are adopting these integrated systems for contested electromagnetic environments where GPS denial is probable. This convergence is unifying previously separate payload and avionics supplier tiers, forcing component vendors to broaden capability portfolios or exit the market.
EASA's regulatory framework for drone operations and the EU AI Act's algorithmic transparency requirements are creating parallel compliance obligations for European market entry. Manufacturers must document decision-tree logic for autonomous flight systems, extending certification documentation timelines. Cargo operators targeting German and French urban corridors are responding by establishing dedicated regulatory affairs functions in Brussels to pre-empt enforcement divergence.
Defense procurement agencies are compressing vendor qualification cycles through modular contracting vehicles that separate airframe, payload, and software awards. This disaggregation is fragmenting previously integrated platform supply relationships and enabling specialized subsystem vendors to capture direct contract flow. The United States Department of Defense is most aggressively deploying this model, with Air Force Research Laboratory programs leading the structural shift away from prime-locked development pipelines.
Autonomous Aircraft Market Segmentation
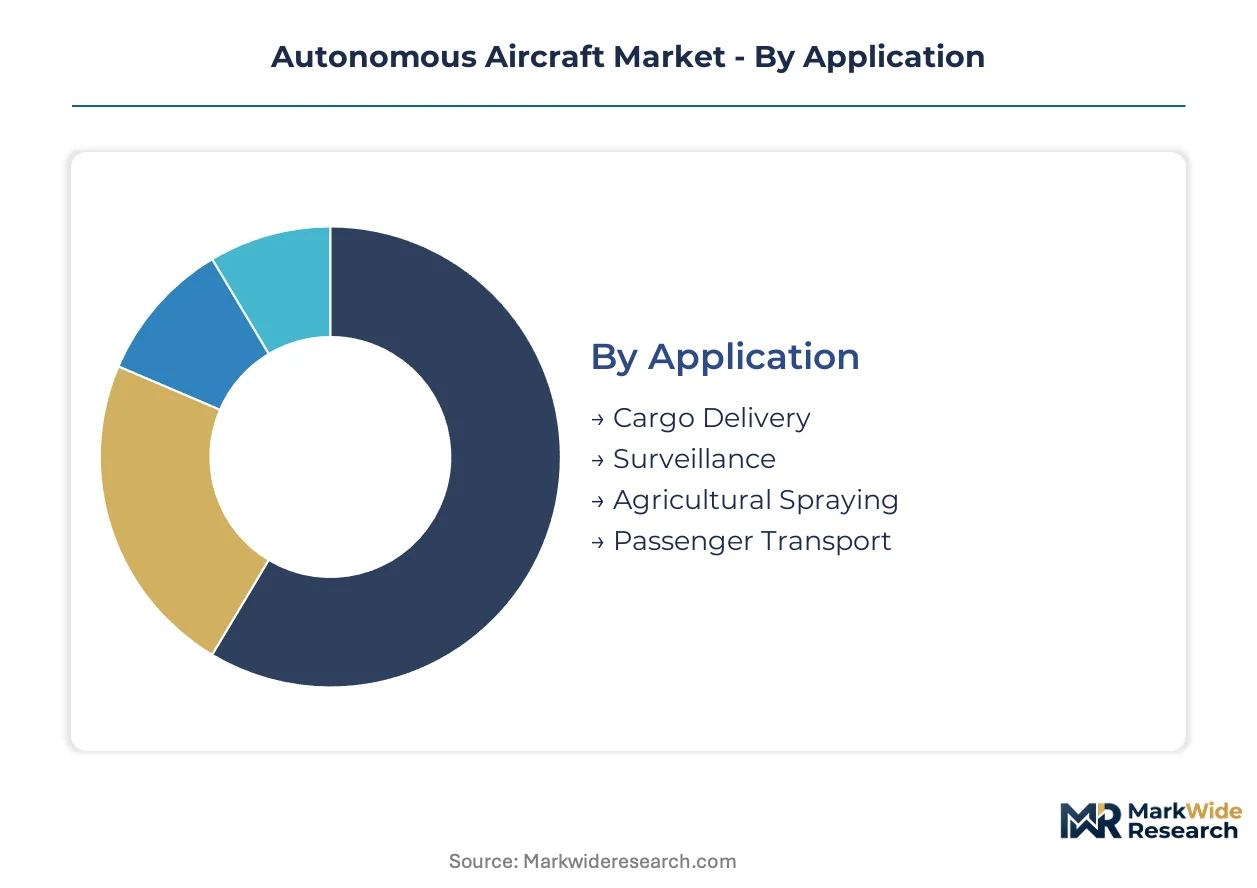
Segmentation in autonomous aircraft reveals how mission requirements dictate platform architecture. Payload constraints, endurance demands, and regulatory pathways fragment development roadmaps across distinct operational envelopes.
Application:
Replacement cycles in commercial logistics are compressing as operators retire pilot-dependent fleets for autonomous alternatives.
- Cargo Delivery:Fixed-wing and hybrid platforms dominate last-mile and middle-mile logistics with payload-optimized designs. Demand concentrates in Texas and California corridors where FAA Part 107 waivers enable beyond-visual-line-of-sight operations for retail fulfillment networks.
- Passenger Transport:Electric VTOL configurations prioritize urban air mobility with noise-reduced propulsion for vertiport compatibility. Trials in Dallas-Fort Worth and Los Angeles are validating autonomous flight control architectures before regulatory clearance expansion.
- Surveillance:High-altitude long-endurance systems serve defense ISR missions with multi-sensor persistence.
- Agricultural Spraying:Multi-rotor platforms execute precision crop treatment with variable-rate chemical dispersal.
Volume placements concentrate in Cargo Delivery; the faster expansion belongs to Passenger Transport.
Technology:
Platform architecture selection hinges on range-payload tradeoffs and infrastructure availability at destination zones.
- Multi-Rotor:Quadcopter and hexacopter designs dominate short-range missions with vertical landing precision. Commercial operators in California agricultural zones deploy these for crop monitoring where runway access is absent.
- Hybrid:Combined lift-cruise systems merge VTOL flexibility with fixed-wing efficiency for extended range. Logistics providers testing hydrogen fuel cell integration are targeting routes previously uneconomical for pure electric platforms.
- Fixed-Wing:Conventional aerodynamic profiles maximize endurance for surveillance and cargo missions.
- VTOL:Dedicated tilt-rotor and ducted fan architectures optimize urban passenger density.
Multi-Rotor systems anchor current fleet deployments; Hybrid configurations are climbing the fastest as range requirements intensify.
End User:
Procurement authority fragmentation is reshaping vendor engagement models across distinct buyer organizations.
- Government:Defense agencies and civil authorities specify hardened communication links and electromagnetic resilience. U.S. Department of Defense programs compress development timelines through modular contracting that separates airframe, payload, and software awards.
- Commercial:Logistics operators and air taxi services prioritize total cost of ownership and certification pathway clarity. FAA type certification bottlenecks are forcing commercial deployment sequencing behind military validation.
- Research Institutions:Universities and national laboratories test edge-case autonomy algorithms.
- Private Operators:Individual owners and small fleets serve specialized photography and inspection niches.
Government procurement commands the largest contract values; Commercial adoption is gaining share fastest as certification frameworks mature.
Payload Capacity:
Weight-class stratification determines propulsion architecture and regulatory classification thresholds.
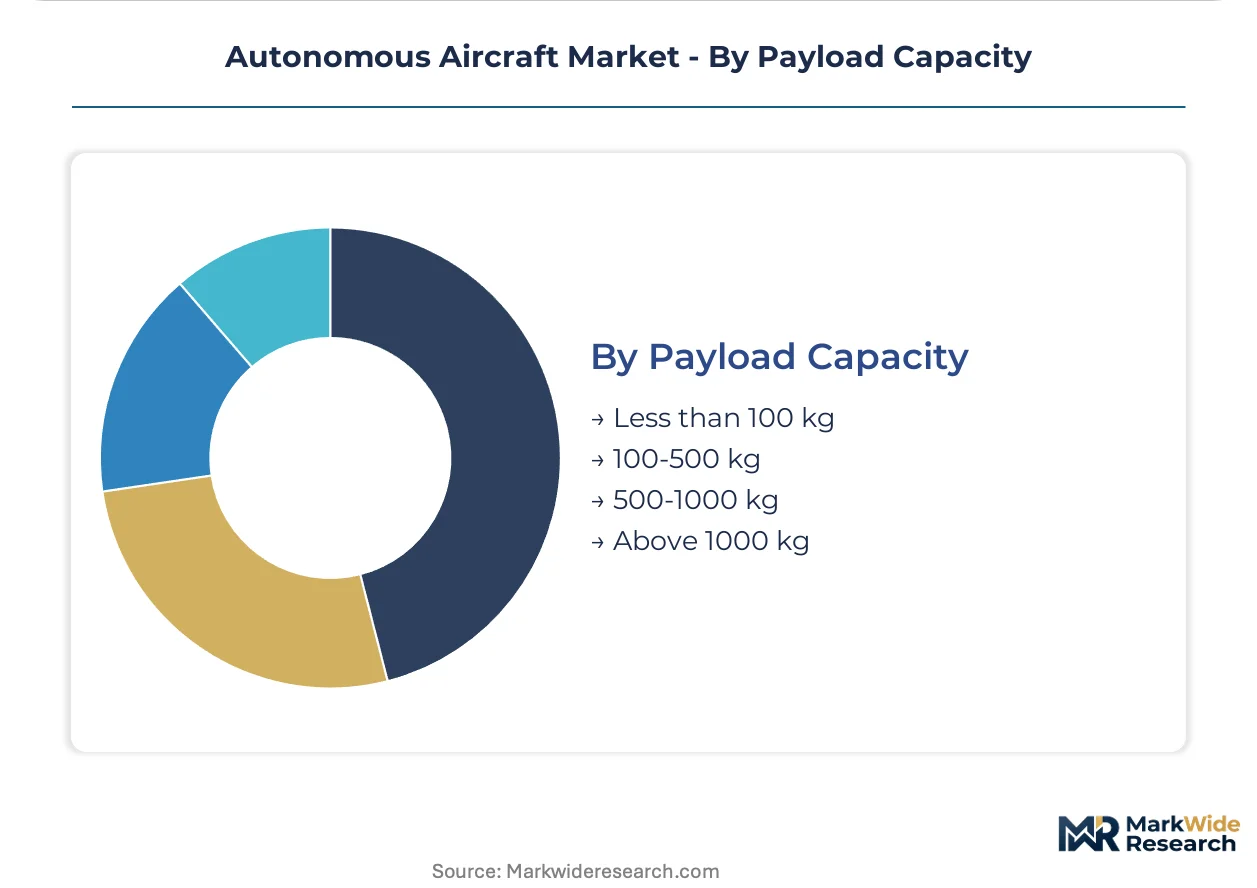
- Less than 100 kg:Lightweight platforms dominate consumer and light commercial inspection missions with minimal regulatory burden.
- 100-500 kg:Mid-weight systems serve agricultural spraying and regional cargo with battery-electric propulsion viability.
- 500-1000 kg:Heavy-lift platforms enable urban passenger transport and critical supply delivery with hybrid or hydrogen powertrains.
- Above 1000 kg:Large autonomous systems replicate traditional cargo aircraft capacity for defense logistics and inter-city freight.
Deployments stratify across the 100-500 kg band; the steepest expansion trajectory sits in 500-1000 kg as passenger transport scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentrates manufacturing capacity in the United States, while commercial deployment trials cluster in jurisdictions with progressive airspace regulations. Consumption patterns split between military ISR demand and emerging logistics networks.
United States
The Department of Defense accelerates uncrewed system acquisitions through Air Force Research Laboratory programs. FAA Part 107 waivers enable beyond-visual-line-of-sight operations in designated corridors. Dallas-Fort Worth and Los Angeles host vertiport construction for urban air mobility validation.
Germany
Industrial automation demand drives cargo platform testing for last-mile logistics integration. EASA drone operation frameworks and EU AI Act algorithmic transparency requirements shape certification documentation. Munich and Hamburg clusters concentrate avionics subsystem development for European market entry.
China
Domestic logistics operators trial autonomous delivery networks across dense urban corridors. MIIT standards for uncrewed aircraft and GB certification protocols govern commercial deployment timelines. Shenzhen and Beijing manufacturing bases supply solid-state LiDAR and sensor fusion components.
United Arab Emirates
NEOM and Dubai infrastructure projects specify autonomous aerial mobility for smart city integration. General Civil Aviation Authority frameworks for drone operations enable commercial trials ahead of European clearance. Abu Dhabi defense procurement channels demand surveillance platforms outside NATO supply chains.
Israel
Defense export requirements sustain high-altitude long-endurance platform development for contested electromagnetic environments. National regulator certification for autonomous flight systems supports dual-use technology transition. Tel Aviv metropolitan engineering clusters specialize in sensor fusion and fail-safe flight control architectures.
Autonomous Aircraft Market Vendor Landscape
The competitive structure tilts toward defense-anchored primes with established manufacturing scale and channel control. Tier-one contractors dominate high-altitude endurance segments through integrated payload-airframe development. Mid-tier specialists capture modular software and subsystem awards under disaggregated contracting vehicles. Strategic moves center on M&A for sensor fusion capabilities and strategic partnerships for hydrogen propulsion integration.
Within the defense prime tier, Lockheed Martin and Northrop Grumman exemplify high-altitude platform leadership through established Skunk Works and Global Hawk manufacturing pipelines. Boeing occupies a position spanning integrated defense-commercial development. Among emerging specialists, Shield AI and Anduril Industries represent software-centric entrants capturing modular algorithm awards under Air Force Research Laboratory programs.
| Leading Market Players |
|---|
| BAE Systems |
| General Atomics Aeronautical Systems |
| Boeing |
| AeroVironment |
| Shield AI |
| Lockheed Martin |
| Airbus |
| Anduril Industries |
| Northrop Grumman |
| Others |
Supply Flow & Price Mechanics
Flight control algorithm specialists clustering in Tel Aviv and California command compensation premiums that widen pricing spreads between defense-grade autonomous platforms and commercial alternatives. Labor-cost differentials in sensor fusion engineering propagate through tiered procurement structures, compressing margins on standardized cargo delivery systems while sustaining premiums on hardened military configurations.
Pricing Analysis
Cost-down pressure on mid-weight cargo platforms accelerates because solid-state LiDAR manufacturing scale-up erodes sensor cost advantages. Three-tier pricing structure across FAA-certified, waiver-dependent, and experimental configurations separates buyers by regulatory risk tolerance. Certification grade and volume scale drive price differentiation, with retail fulfillment networks exhibiting highest price sensitivity and defense agencies showing lowest. Pricing pressure stems from modular contracting vehicles fragmenting previously integrated platform awards.
Supply Chain Analysis
Single-source vulnerability sits with lightweight composite airframe suppliers concentrated in Japan and Germany for stratospheric endurance platforms. Electro-optical gimbal systems draw from manufacturing clusters in China and South Korea, while solid-state LiDAR feeds from Shenzhen and Beijing production bases. Tariff exposure on electro-optical payloads creates procurement risk for ISR mission operators. Distribution runs through prime contractor integration facilities before reaching defense procurement channels and commercial logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous aircraft manufacturing operates under supply-constrained conditions where flight control engineering talent scarcity props platform pricing across all tiers. Capacity bottlenecks in sensor fusion algorithm development sustain margin structures despite component cost deflation.
For Market Incumbents: Cement technology leadership through captive supply of solid-state LiDAR subsystems and expanded Skunk Works-style rapid prototyping facilities in Texas. Lockheed Martin and Northrop Grumman face emerging software-centric entrants capturing modular algorithm awards under Air Force Research Laboratory programs; vertical integration into sensor fusion stacks defends position. For New Entrants and Emerging Players: Enter via hydrogen propulsion integration partnerships for extended-range cargo missions previously reserved for fixed-wing platforms. Agricultural spraying in California corridors offers lowest regulatory barrier among commercial applications. White-space capture in Middle East defense procurement outside NATO supply chains accelerates revenue traction before FAA certification convergence. For Investors and Strategic Acquirers: Re-rating potential sits with software-centric autonomy specialists given Air Force Research Laboratory modular contracting expansion. Long-term viability hinges on dual-use technology transition capacity spanning defense ISR validation and commercial logistics deployment. Acquisition targets with established FAA Part 107 waiver track records signal certification pathway de-risking.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Capability Acquisition | Consolidates navigation and collision-avoidance functions for contested electromagnetic environments. |
| Hydrogen Propulsion Partnership | Unlocks extended-range cargo missions for electric vertical take-off platforms. |
| FAA Certification Pre-Investment | Accelerates commercial deployment timelines behind military validation cycles. |
| Vertiport Infrastructure Alliance | Secures dedicated landing zones in Dallas-Fort Worth and Los Angeles corridors. |
| Regulatory Affairs Function Establishment | Pre-empts EASA and EU AI Act enforcement divergence for European market entry. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this autonomous aircraft market assessment. Primary interviews with flight control algorithm engineers, FAA certification specialists, defense procurement officers, and commercial logistics operators combined with bottom-up and top-down triangulation. Secondary sources encompassed FAA Part 107 waiver databases, EASA drone operation frameworks, Department of Defense contract announcements, and SEC filings from publicly traded primes. Customs records on electro-optical payload imports and LiDAR component trade flows validated regional supply chain concentration assumptions.
Granularity-level modeling deployed platform architecture by application segment, payload capacity tier, and end-user procurement authority across the projection horizon. Technology segmentation captured multi-rotor, hybrid, fixed-wing, and VTOL configurations with propulsion system differentiation. CAGRs derived from scenario-weighted demand curves incorporating FAA certification timeline probabilities and defense budget authorization patterns. Forecast inputs included vertiport construction permits, hydrogen fuel cell integration milestones, and modular contracting vehicle adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FAA-EASA regulatory divergence scenarios and electromagnetic warfare capability disruptions. Forecasts reflect assumptions on algorithmic validation cost trajectories and solid-state sensor manufacturing scale curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Rotary-Wing Lidar Drone Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Automated Weapon System Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
North America AUV Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
Global Remote Firing System Market