
 Aircraft Navigation System Market | 2026-2036
Aircraft Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Navigation System Market Insights
Operating lease structures for avionics retrofit programs is rewriting competitive access across the aftermarket. Honeywell International Inc. leverages its integrated flight deck ecosystem to capture multi-system upgrade contracts from global carriers. Thales Group anchors European demand through its Galileo-compatible navigation suites and military platform integrations. Safran SA specializes in hybrid inertial-GPS architectures that reduce dependency on single-source satellite constellations.
An aircraft navigation system comprises integrated sensor arrays, computational flight management units, and display interfaces that process position, velocity, and attitude data to guide aircraft along defined flight paths. These systems typically integrate inertial reference units with satellite receivers and ground-based radio aids to maintain sub-100-meter positional accuracy during all phases of flight. Satellite Navigation and Integrated Navigation systems command the largest installed base due to broad commercial aviation adoption, while ADS-B technology represents the fastest-growing segment as regulatory mandates force equipage across legacy fleets. Military Aviation applications sustain premium margin pools where encrypted anti-jam capabilities and terrain-referenced navigation justify specialized procurement cycles.
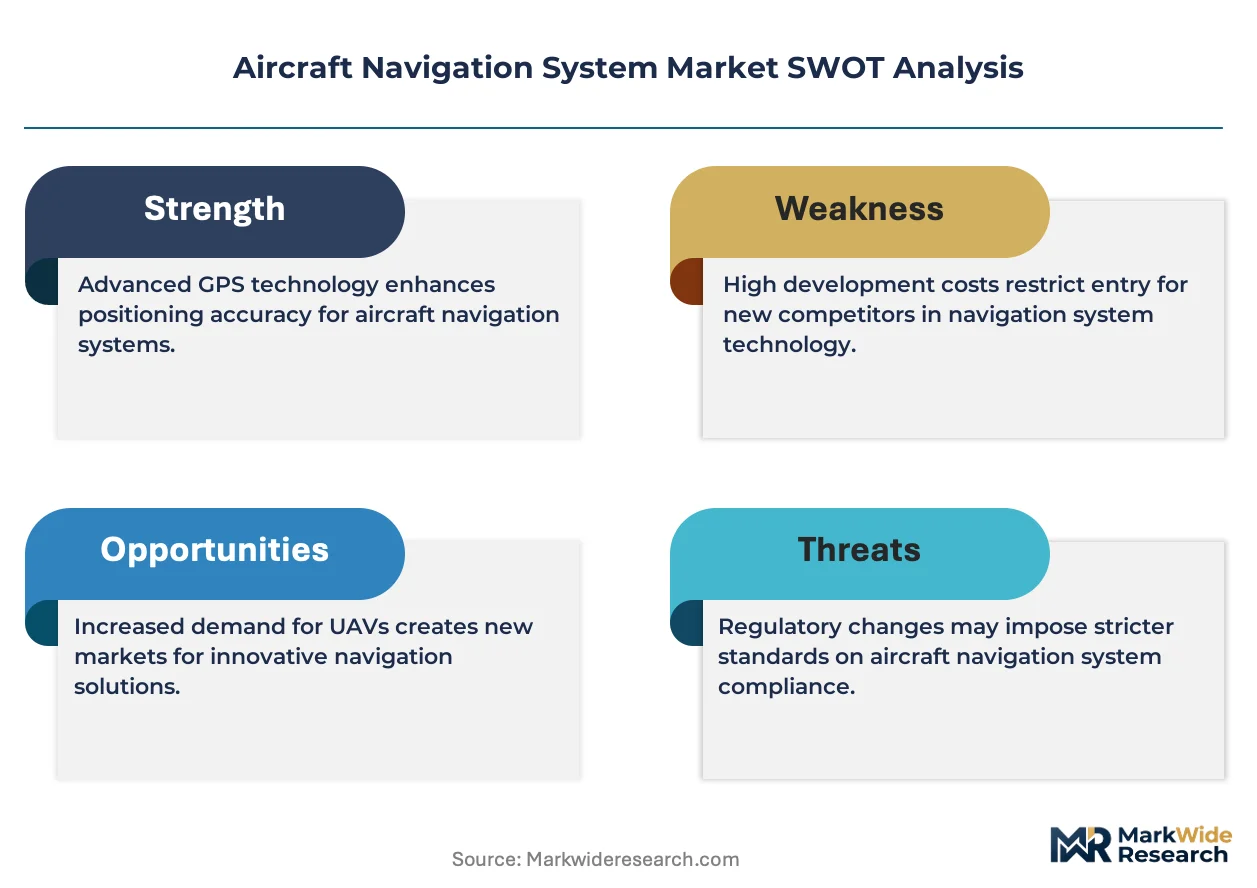
The FAA mandates ADS-B Out performance standards under 14 CFR 91.225, while EASA enforces equivalent requirements through its Acceptable Means of Compliance framework, collectively shaping product certification pathways for manufacturers. The EU AI Act and emerging CSRD disclosure rules are beginning to influence software validation protocols and supply chain transparency for navigation system vendors. Stakeholders must monitor evolving spectrum allocation decisions for GPS L5 and Galileo E5a signals that could obsolete current receiver architectures before planned refresh cycles conclude.
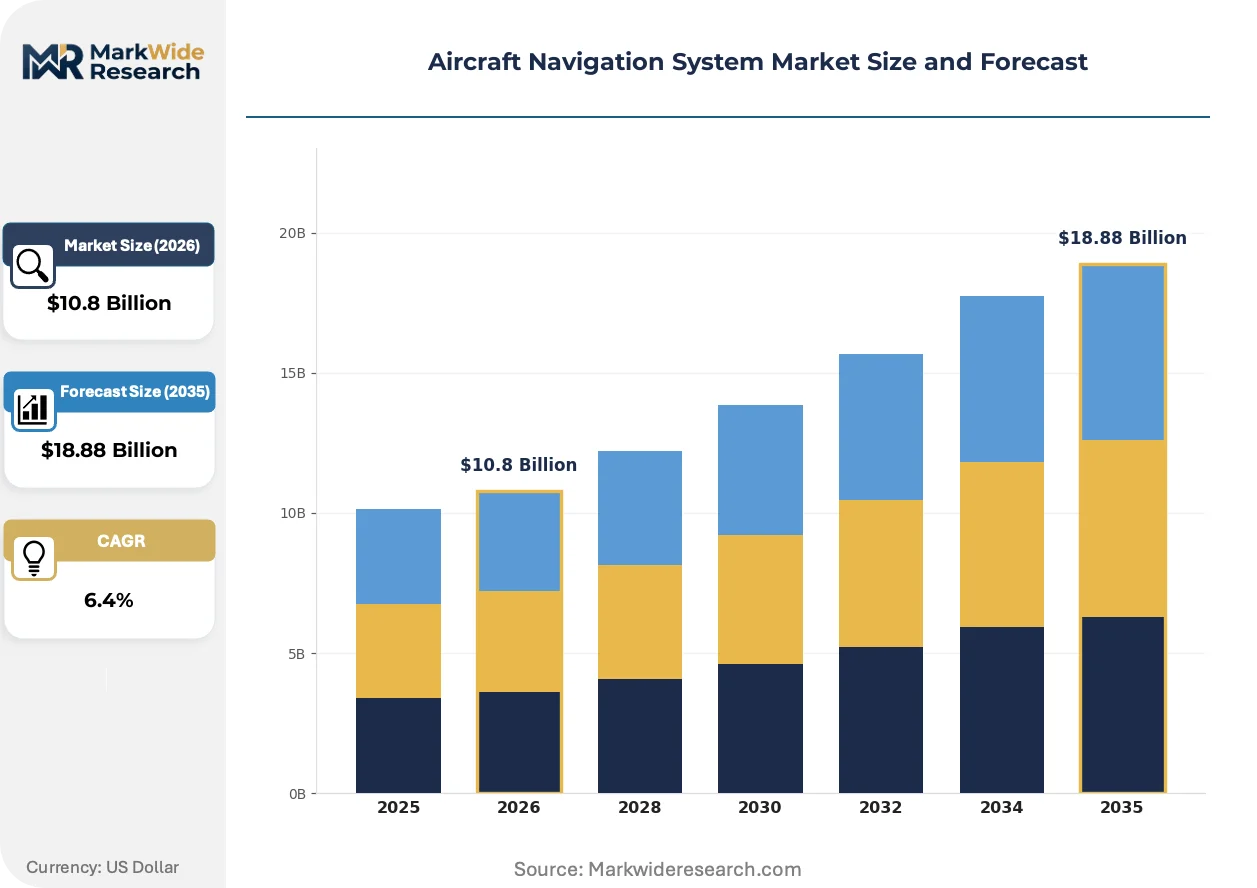
Market Dynamics
Mandatory ADS-B Out retrofit deadlines under FAA 14 CFR 91.225 and EASA AMC 20-24 are compressing upgrade cycles across aging commercial fleets, forcing simultaneous hardware replacement across multiple avionics domains.
Growth Catalysts
- FAA Equipage Mandates:The 14 CFR 91.225 deadline structure compels U.S. operators to complete ADS-B Out installations, sustaining retrofit demand across narrowbody and regional aircraft categories.
- Galileo E1/E5a Signal Deployment:European satellite constellation expansion enables multi-constellation receiver architectures that improve availability in high-latitude and urban canyon environments.
- Urban Air Mobility:Electric vertical takeoff and landing platforms require certifiable navigation solutions with sub-meter accuracy for autonomous operations in congested airspace.
Market Restraints
- Gallium Nitride Supply Concentration:Foundry capacity for high-frequency RF components concentrates in East Asian manufacturing clusters, creating single-source vulnerability for next-generation receivers.
- ITAR-Controlled Encryption Modules:U.S. export restrictions on military-grade anti-jam algorithms limit technology transfer to allied defense programs, fragmenting procurement pathways.
- GPS L1 C/A Vulnerability:Civilian signal susceptibility to spoofing and jamming degrades confidence for safety-critical applications without multi-constellation backup.
Strategic Opportunities
- India Defense Modernization:The country's offset requirements under DAP-2020 create local assembly mandates for foreign navigation system vendors seeking fighter and transport contracts.
- Software-Defined Radio Convergence:Reconfigurable RF frontends combining L-band and C-band reception reduce hardware obsolescence risk as spectrum allocations evolve.
- EU CSRD Disclosure Rules:Supply chain transparency mandates favor vendors with auditable component traceability, creating differentiation against opaque competitors.
Industry Challenges
- DO-178C Certification Backlog:Software verification for flight-critical navigation algorithms faces qualified engineer shortages, extending development timelines.
- Multi-Constellation Integration Complexity:Synchronizing GPS, Galileo, GLONASS, and BeiDou ephemeris data requires expanded ground monitoring infrastructure and receiver processing power.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Navigation System Market |
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Inertial Navigation, Satellite Navigation, Radio Navigation, Integrated Navigation, Visual Navigation Technology: Global Positioning System, Doppler Radar, VOR/DME, LORAN, INS, ADS-B Application: Commercial Aviation, Military Aviation, General Aviation, Unmanned Aerial Vehicles, Cargo Aircraft End User: Airlines, Defense Organizations, Private Operators, Government Agencies, Charter Services |
| Companies Covered | Garmin Ltd., L3Harris Technologies Inc., Honeywell International Inc., Safran SA, BAE Systems plc, RTX Corporation, Northrop Grumman Corporation, Leonardo S.p.A, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Navigation System Market Trends and Innovations
Navigation system architectures are converging toward modular, software-upgradable platforms that decouple hardware refresh cycles from functional capability expansion.
Multi-frequency multi-constellation receivers are digitizing signal processing chains previously implemented in analog hardware. Major carriers in the United States and European low-cost operators are mandating these configurations for new deliveries. This transition is digitizing maintenance workflows and enabling remote diagnostics that compress troubleshooting intervals.
EU AI Act risk classification rules are imposing documentation burdens on machine learning components in flight management systems. Manufacturers must now maintain algorithmic transparency records for trajectory prediction modules. European OEMs are responding by segregating deterministic navigation kernels from adaptive optimization layers.
Airline technical procurement teams are unbundling long-term service agreements from initial hardware purchases. Low-cost carriers in Southeast Asia and Middle Eastern hubs now favor time-and-materials support structures over bundled warranties. This pattern concentrates in regions with volatile fleet utilization rates and unpredictable route networks.
Aircraft Navigation System Market Segmentation
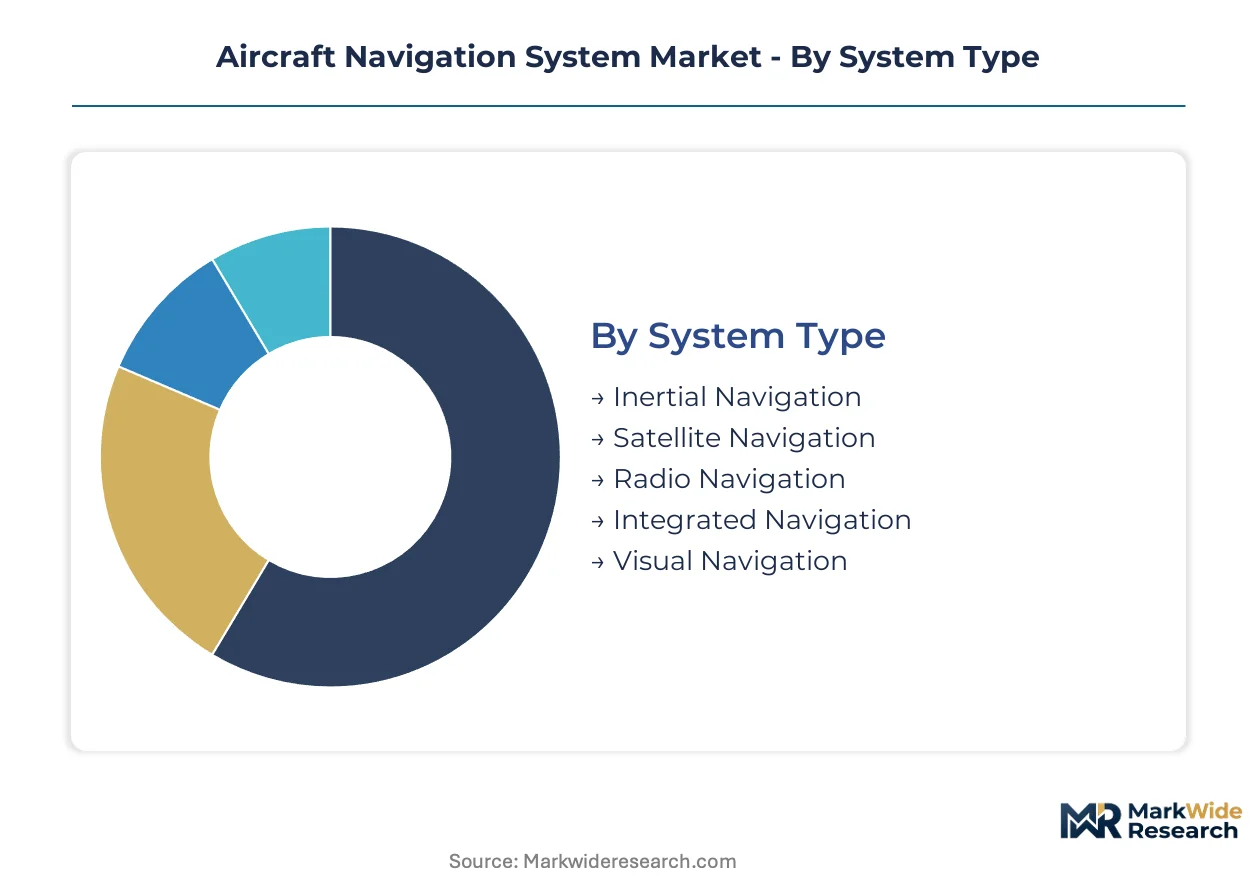
Navigation system procurement patterns diverge sharply across operational domains, with commercial carriers prioritizing multi-constellation redundancy while military buyers demand anti-jam resilience. Understanding these segment boundaries clarifies where technology roadmaps and regulatory mandates create divergent capability requirements.
System Type:
Mature architectures dominate current installed bases, yet emerging hybrid configurations are displacing single-sensor dependencies across new programs.
- Integrated Navigation:Fuses inertial reference data with satellite and ground-based radio inputs through Kalman filtering algorithms to maintain continuity during signal outages. Commercial airlines in the United States specify these architectures for oceanic and remote-area operations where sole-means GPS availability cannot be guaranteed.
- Satellite Navigation:Processes L-band signals from GPS, Galileo, GLONASS, and BeiDou constellations to provide absolute position fixes with meter-level accuracy. European low-cost carriers and Middle Eastern hubs are mandating multi-constellation receivers for new narrowbody deliveries to mitigate single-constellation vulnerability.
- Inertial Navigation:Self-contained gyroscopic and accelerometer-based systems that compute position through dead reckoning without external references.
- Radio Navigation:Ground-station-dependent systems including VOR, DME, and ILS that provide bearing and distance information within terrestrial coverage footprints.
- Visual Navigation:Camera-based and electro-optical systems for terminal-area operations and autonomous landing in GPS-denied environments.
Integrated Navigation handles the majority of throughput; Satellite Navigation is the fastest mover on share.
Technology:
Cost tiers separate legacy analog implementations from digital software-defined architectures that reduce hardware refresh frequency.
- ADS-B:Automatic Dependent Surveillance-Broadcast transponders transmit aircraft position, velocity, and identification to air traffic control and other aircraft without interrogation. FAA 14 CFR 91.225 mandates equipage across all U.S. controlled airspace, compressing retrofit demand for regional jets and turboprops that missed earlier upgrade cycles.
- Global Positioning System:Civilian L1 C/A and military P(Y) code receivers provide fundamental position, navigation, and timing services. Defense organizations in allied nations face ITAR restrictions on encrypted military-code modules, fragmenting procurement pathways between U.S.-controlled and indigenous alternatives.
- INS:Inertial Navigation Systems using ring laser or fiber-optic gyroscopes for high-integrity attitude and heading reference.
- Doppler Radar:Velocity-sensing systems primarily retained in military helicopters and legacy maritime patrol platforms.
- VOR/DME:VHF Omnidirectional Range and Distance Measuring Equipment ground stations for conventional airway navigation.
- LORAN:Long-range low-frequency hyperbolic navigation system maintained as a GPS backup by select coastal states.
GPS receivers anchor volume across civilian applications; ADS-B is expanding most quickly as regulatory deadlines force fleet-wide retrofit.
Application:
Customer type determines certification rigor, with military programs tolerating extended development cycles for specialized survivability features.
- Commercial Aviation:Scheduled passenger operations requiring DO-178C certified flight management systems with dual-redundant navigation inputs. Major U.S. carriers and European network airlines sustain the largest upgrade budgets as they modernize aging A320ceo and 737NG fleets ahead of next-generation traffic management mandates.
- Military Aviation:Fighter, transport, and rotary-wing platforms requiring encrypted anti-jam receivers and terrain-referenced navigation for low-level penetration. India's DAP-2020 offset requirements compel foreign vendors to establish local assembly partnerships for fighter and transport contracts.
- General Aviation:Private and business aircraft operating under Part 91 with lighter certification burdens and cost-sensitive equipment selections.
- Unmanned Aerial Vehicles:Remotely piloted and autonomous systems demanding sub-meter accuracy for beyond-visual-line-of-sight operations.
- Cargo Aircraft:Dedicated freighter fleets with high-utilization schedules that prioritize reliability and minimize dispatch delays.
Commercial Aviation commands the dominant revenue pool; Military Aviation sustains the steepest expansion trajectory through classified modernization programs.
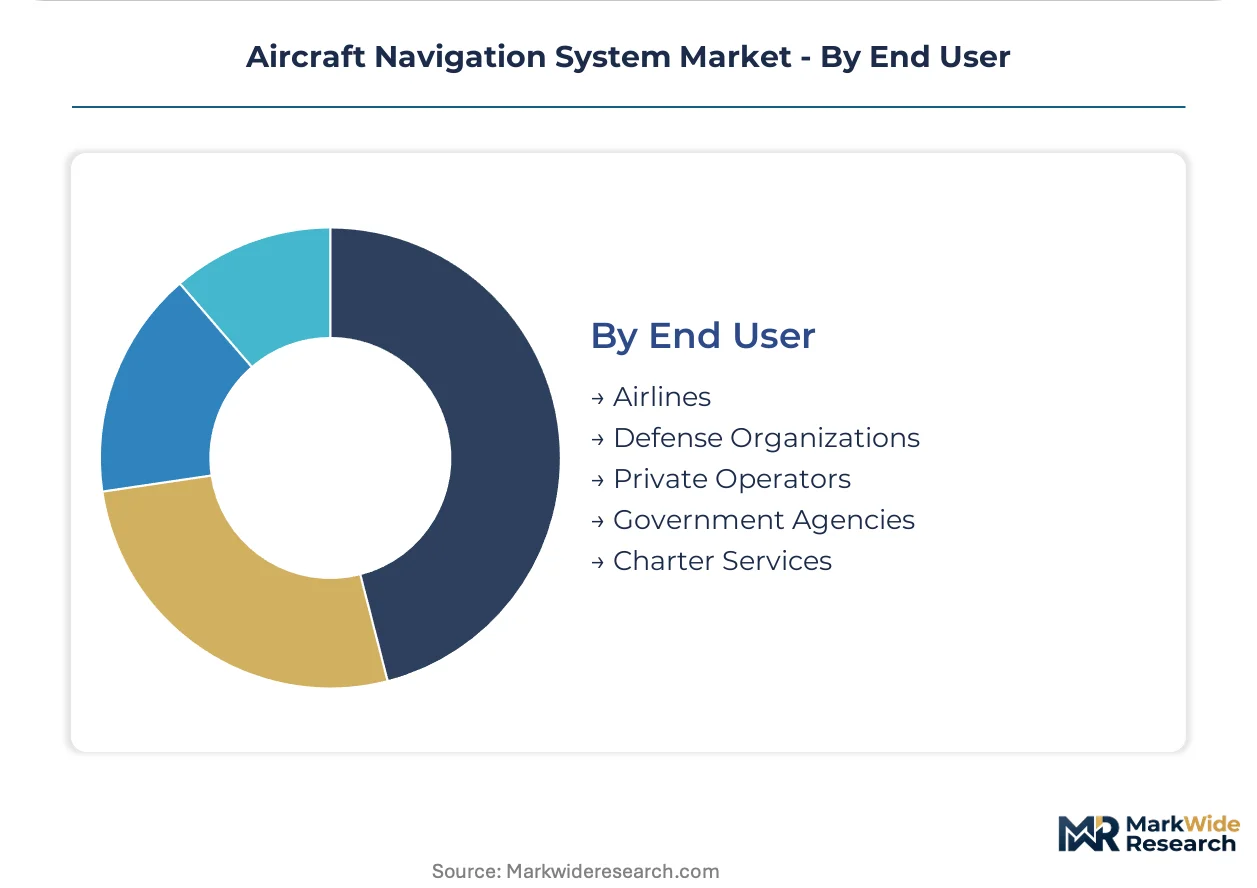
End User:
Procurement authority concentrates in fleet operators with centralized technical standards, while fragmented private ownership drives aftermarket price sensitivity.
- Airlines:Network and low-cost carriers with standardized fleet configurations that negotiate enterprise-wide avionics contracts. Southeast Asian and Middle Eastern technical procurement teams increasingly unbundle long-term service agreements from initial hardware purchases, favoring time-and-materials structures.
- Defense Organizations:National air forces and joint commands with classified requirements for electronic protection and mission-specific integration. U.S. export controls on ITAR-classified encryption modules limit technology transfer, forcing allied programs to develop indigenous alternatives or accept capability gaps.
- Private Operators:Individual owners and fractional programs with discretionary upgrade schedules and strong price elasticity.
- Government Agencies:Coast guard, border patrol, and scientific survey organizations with mixed civilian-mission profiles.
- Charter Services:On-demand operators with volatile utilization patterns that defer non-mandatory investments.
Airlines dominate procurement volume; Defense Organizations are gaining share fastest through classified multi-year acquisition programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA equipage mandates under 14 CFR 91.225 and EASA AMC 20-24 deadlines are compressing retrofit cycles across major aviation markets, forcing synchronized hardware replacement across aging commercial fleets.
United States
Major carriers sustain substantial upgrade budgets for fleet modernization programs targeting next-generation air traffic mandates. The FAA enforces ADS-B Out performance standards under 14 CFR 91.225, shaping product certification pathways for domestic manufacturers. Dallas-Fort Worth and Seattle-Tacoma aerospace clusters concentrate defense contractor activity alongside commercial avionics integration facilities.
France
Galileo-compatible navigation suites anchor European demand through multi-constellation receiver architectures. EASA enforces equivalent ADS-B requirements through its Acceptable Means of Compliance framework, harmonizing certification with FAA standards. Toulouse and Paris-Saclay industrial zones host integrated flight deck development centers serving global carrier contracts.
Germany
Low-cost operators mandate multi-constellation configurations for new narrowbody deliveries to mitigate single-constellation vulnerability. The EU AI Act imposes risk classification rules on machine learning components in flight management systems, requiring algorithmic transparency documentation. Munich and Hamburg metropolitan areas concentrate software-defined radio development for reconfigurable RF frontends.
India
Defense modernization programs create procurement opportunities under DAP-2020 offset requirements that compel foreign vendors to establish local assembly partnerships. The country's national aviation regulator mandates equipage standards aligned with ICAO Annex 10 provisions. Bangalore and Hyderabad defense corridors concentrate indigenous navigation system development for fighter and transport platforms.
United Kingdom
Network airlines modernize aging A320ceo and 737NG fleets ahead of traffic management mandates, sustaining enterprise-wide avionics contracts. Military platform integrations require encrypted anti-jam capabilities governed by national export control frameworks. Bristol and Stevenage aerospace clusters specialize in terrain-referenced navigation for low-level penetration missions.
Aircraft Navigation System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement structures. The vendor base clusters around three strategic archetypes: integrated flight deck ecosystem providers, multi-constellation receiver specialists, and military-grade encrypted module developers. Consolidation pressures intensify as fleet operators unbundle long-term service agreements from initial hardware purchases. Dominant competitive moves include strategic partnerships for local assembly mandates and technology licensing for software-defined architectures.
Within the integrated systems tier, Honeywell International Inc. and Thales Group exemplify full-stack navigation providers that span commercial and defense applications. Safran SA occupies a specialist position in hybrid inertial-GPS architectures. These three entities represent contrasting geographic anchors—American, French, and French respectively—while serving overlapping carrier and defense procurement channels.
| Leading Market Players |
|---|
| Garmin Ltd. |
| L3Harris Technologies Inc. |
| Honeywell International Inc. |
| Safran SA |
| BAE Systems plc |
| RTX Corporation |
| Northrop Grumman Corporation |
| Leonardo S.p.A |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
Foundry undercapacity for GaN RF components in East Asian manufacturing clusters is compressing supplier lead times and amplifying pricing power for qualified vendors serving avionics retrofit programs. This utilization squeeze propagates through tier-one integrators, forcing margin absorption or pass-through negotiations with airline technical procurement teams.
Pricing Analysis
Certification level under DO-178C and DO-254 standards creates the primary spread between premium flight-critical systems and general aviation alternatives. Three-tier pricing structure separates enterprise-wide fleet contracts from regional operator retrofits and aftermarket spot purchases. Pricing pressure stems from unbundled service agreements as low-cost carriers abandon bundled warranties for time-and-materials structures. Regional operators exhibit highest price sensitivity, while defense organizations tolerate premium positioning for ITAR-controlled encryption modules.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for navigation system vendors sourcing high-frequency RF substrates. Manufacturing concentrates in Taiwan, South Korea, and Japan for ring laser gyroscopes and precision accelerometers. Component sourcing draws from specialized foundries for gallium nitride wafers, ceramic packaging substrates, and radiation-hardened semiconductors. Single-source vulnerability concentrates in East Asian GaN foundry capacity. Distribution runs through authorized avionics distributors and direct OEM channels to airline technical procurement and defense acquisition offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat business where FAA and EASA certification entrenchment creates prohibitive switching costs for fleet operators facing mandatory retrofit deadlines. Network effects compound as multi-system upgrade contracts favor vendors with integrated flight deck ecosystems.
For Market Incumbents: Insulate installed base relationships by embedding software-defined radio architectures that extend hardware refresh cycles and reduce obsolescence risk from evolving spectrum allocations. Deepen backward integration into GaN RF component supply through captive foundry partnerships or long-term offtake agreements with Taiwanese and South Korean suppliers. Counter emerging modular platform entrants by bundling predictive maintenance analytics with navigation hardware, creating data-dependent switching costs that transcend pure price competition. For New Entrants and Emerging Players: Urban air mobility platforms in congested European and Middle Eastern airspace represent the most penetrable entry point for certifiable sub-meter navigation solutions. India's DAP-2020 offset requirements for fighter and transport contracts create mandatory local assembly partnerships that foreign vendors must satisfy, opening subcontractor roles for component specialists. Software-defined radio convergence enables reconfigurable RF frontends that reduce hardware obsolescence risk, offering a technical wedge against legacy analog architectures. Pursue regulatory sandbox participation with EASA and FAA to accelerate certification timelines for novel multi-constellation receiver designs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with unbundled long-term service agreements and predictive maintenance subscriptions, particularly those serving Southeast Asian low-cost carriers with volatile fleet utilization. Acquisition targets should display software-upgradable platform architectures, multi-constellation receiver certifications, and established relationships with at least two of the three major airline procurement hubs in United States, Europe, and Middle East. Monitor EASA and FAA spectrum allocation decisions for GPS L5 and Galileo E5a signals as the critical inflection indicator that could obsolete current receiver architectures before planned refresh cycles conclude.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Development | Reconfigurable architectures from Munich and Hamburg development centers reduce hardware refresh frequency amid evolving spectrum mandates. |
| Multi-Constellation Receiver Certification | Galileo E1/E5a compatibility from Toulouse integration facilities secures European carrier contracts and high-latitude operational approval. |
| Local Assembly Partnership Formation | Bangalore and Hyderabad defense corridor facilities satisfy India's DAP-2020 offset requirements for fighter platform navigation systems. |
| Predictive Maintenance Analytics Integration | Remote diagnostics capabilities compress troubleshooting intervals for Southeast Asian carriers with unpredictable route networks. |
| GaN Foundry Capacity Securement | Taiwanese and South Korean substrate supply agreements mitigate single-source vulnerability for next-generation RF frontends. |
Research Methodology
A spread of perspectives from airline fleet managers, defense procurement officers, avionics integration engineers, and regulatory certification specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with technical procurement teams at major carriers and defense contractors, validated against secondary sources including FAA 14 CFR documentation, EASA AMC submissions, ICAO Annex 10 provisions, and customs trade data for navigation system components. Bottom-up triangulation across system-type demand curves and top-down validation against fleet modernization program disclosures ensured methodological consistency.
Demand-supply balance modeling across the projection horizon integrated retrofit cycle compression from ADS-B mandates, Galileo constellation deployment timelines, and urban air mobility certification pathways. Segmentation dimensions included system architecture type, technology generation, application domain, and end-user procurement authority. CAGRs were derived from fitted adoption curves calibrated to regulatory deadline structures and fleet age distributions. Industry-specific inputs encompassed DO-178C certification backlog durations, GaN foundry utilization rates, and offset requirement compliance patterns under India's DAP-2020 framework.
Practitioners should monitor EASA spectrum allocation proceedings, FAA equipment authorization timelines, and ITAR regulatory amendments for early signals of forecast revision. Forecasts reflect assumptions regarding regulatory deadline adherence, foundry capacity expansion trajectories, and multi-constellation receiver adoption rates. Material shifts in GPS L5 or Galileo E5a signal deployment schedules, GaN supply concentration patterns, or defense offset policy modifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Global Aircraft Antenna Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Air Traffic Management Software Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
Military Navigation Systems Market
Aircraft Navigation and Communication
Airspace and Procedure Design Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
Global Flight Navigation System Market