
 Unmanned Composites Market | 2026-2036
Unmanned Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Unmanned Composites Market Intelligence
North American prepreg manufacturers is repositioning capacity toward automated fiber placement lines purpose-built for unmanned platform geometries. Solvay S.A. leverages its resin formulation portfolio to supply qualified material systems for defense UAV airframes. Hexcel Corporation sustains dominance in carbon fiber tape formats optimized for small-diameter fuselage sections. Toray Industries, Inc. anchors Asian supply security through vertically integrated precursor-to-prepreg operations serving Japanese and South Korean drone OEMs.
Unmanned composites encompass fiber-reinforced polymer structures engineered for unmanned aerial, ground, and maritime vehicles, typically manufactured through resin infusion or autoclave cure cycles achieving fiber volume fractions exceeding 60 percent for specific strength targets. These materials replace metallic assemblies to extend endurance and payload capacity in battery-powered platforms. Carbon fiber variants command premium positioning in aerospace and defense end user segments where fatigue resistance and radar signature management justify material cost. Filament winding processes gain traction in cylindrical payload housings and rocket-assisted drone boosters. Glass fiber formulations retain cost-driven penetration in marine surface vessels and select automotive prototyping applications.
FAA airworthiness standards under Part 23 and emerging unmanned aircraft type certification frameworks dictate laminate qualification protocols and damage tolerance thresholds for commercial composite airframes. EPA emissions controls on styrene-based resin systems constrain open-mold manufacturing economics and accelerate closed-infusion process adoption among North American fabricators. EASA design approval requirements for unmanned systems above 25 kilograms impose comparable material traceability burdens on European suppliers. Stakeholders must weigh certification pathway uncertainty against platform-specific performance requirements when selecting fiber-resin combinations and manufacturing processes.
Market Dynamics
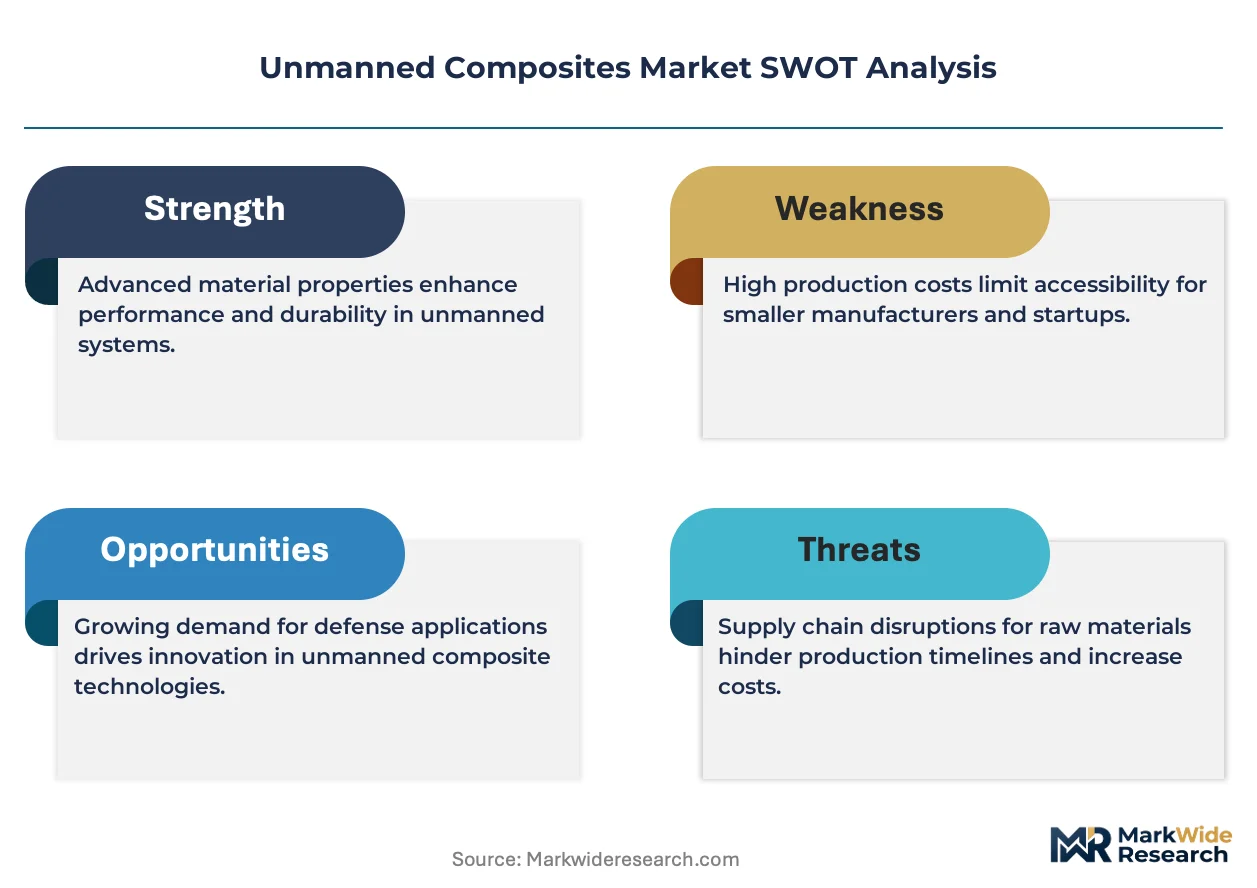
FAA airworthiness mandates for commercial drone certification are forcing composite manufacturers to retool for traceable, repeatable production systems. Defense procurement consolidation around lightweight UAV platforms simultaneously pulls capacity toward military-grade qualification protocols.
Growth Catalysts
- Automated Fiber Placement:Robotic layup systems reduce labor content in small-diameter fuselage manufacturing. Defense contractors in the United States accelerate adoption for scalable UAV production.
- EASA Design Approval Framework:European unmanned aircraft type certification above 25 kilograms creates qualified supplier demand. Material traceability requirements favor established prepreg manufacturers with existing audit infrastructure.
- Battery-Powered Platform Proliferation:Electric propulsion systems in urban air mobility vehicles require maximum specific strength. Carbon fiber laminates displace aluminum in lift-generating structures.
Market Restraints
- Acrylonitrile Price Volatility:Carbon fiber precursor costs fluctuate with petrochemical feedstock markets. Small-scale fabricators lack hedging instruments to stabilize input economics.
- Autoclave Capacity Concentration:Large-diameter cure ovens cluster in legacy aerospace corridors. New entrants face geographic barriers to qualified processing infrastructure.
- Styrene Emission Controls:EPA restrictions on open-mold resin systems constrain low-volume manufacturing. Closed-infusion equipment imposes capital thresholds that filter out regional suppliers.
Strategic Opportunities
- Urban Air Mobility Infrastructure:Vertiport networks in the United States and Germany require inspection-grade composite maintenance protocols. Service contracts for airframe repair create recurring revenue streams.
- Maritime Surface Vessel Expansion:Uncrewed naval platforms favor corrosion-resistant glass fiber hulls. Pacific Rim defense modernization programs specify composite durability standards.
- Dual-Use Technology Convergence:Satellite launch assist systems and high-altitude pseudo-satellite drones share filament-wound booster architectures. Common manufacturing cells serve adjacent aerospace segments.
Industry Challenges
- Composite Repair Technician Scarcity:Laminate damage assessment requires specialized non-destructive inspection certification. Training pipelines lag behind fleet expansion timelines.
- Qualification Timeline Compression:FAA Part 23 equivalency demonstrations for unmanned systems demand extensive coupon testing. Small OEMs struggle to fund parallel certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unmanned Composites Market |
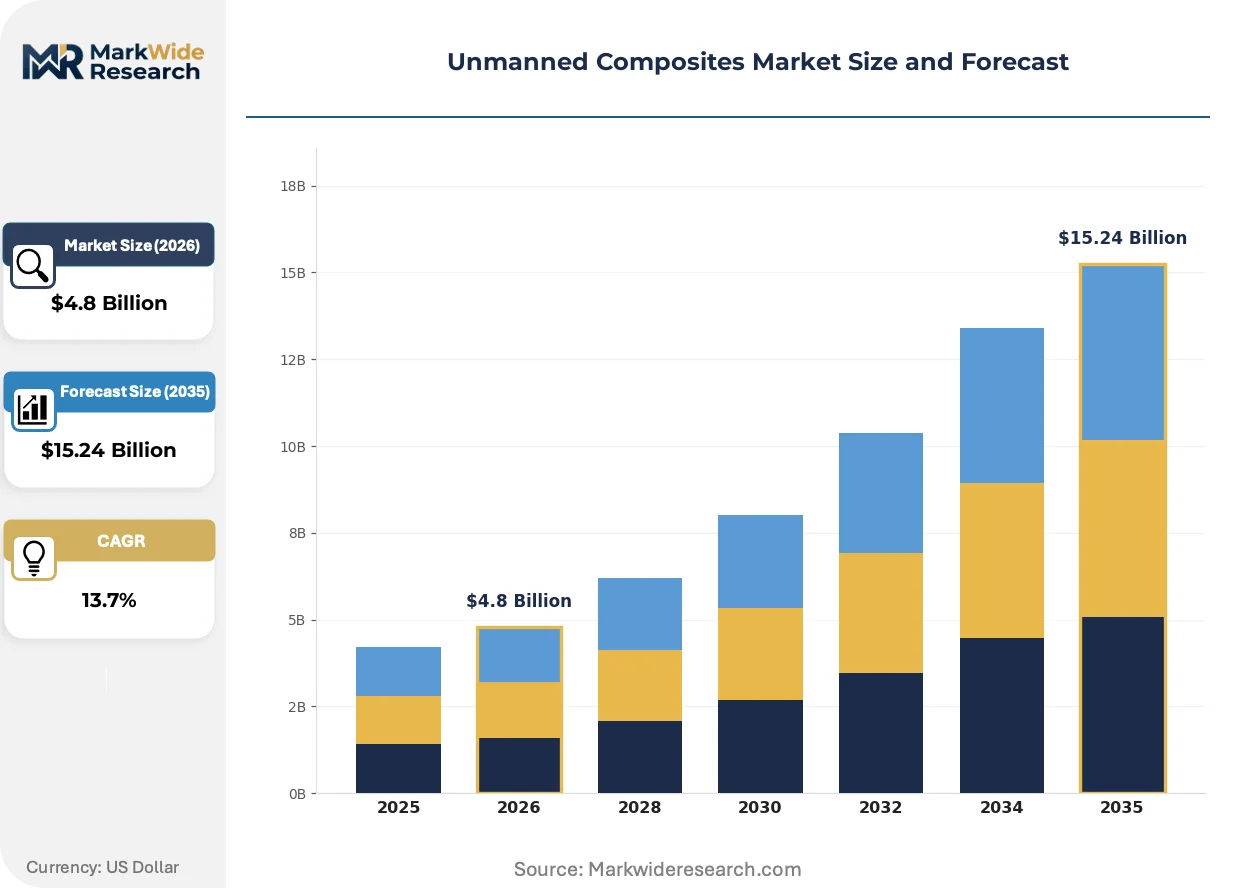
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerospace Components, Structural Parts, Payload Structures, Control Surfaces Manufacturing Process: Layup Process, Filament Winding, Resin Infusion, Autoclave End User Industry: Aerospace, Defense, Automotive, Marine Material Type: Carbon Fiber, Glass Fiber, Kevlar, Others |
| Companies Covered | Solvay S.A., Mitsubishi Chemical Corporation, Hexcel Corporation, Gurit Holding AG, SGL Carbon SE, Toray Industries, Inc., General Dynamics Corporation, Northrop Grumman, Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unmanned Composites Market Strategic Shifts & Innovations
Automated manufacturing systems and regulatory harmonization efforts are compressing the gap between defense and commercial composite qualification standards. Material suppliers must now serve dual certification pathways simultaneously.
Out-of-autoclave resin systems are consolidating process economics for medium-volume UAV manufacturers. Defense procurement agencies in NATO member states specify these cure cycles for rapid surge capacity. The technology is consolidating supplier tiers by eliminating capital-intensive autoclave investments.
REACH authorization requirements for epoxy hardeners are restricting formulation options in European manufacturing. EASA material qualification protocols now reference these chemical restrictions explicitly. Suppliers serving German and French drone OEMs reformulate resin systems to maintain market access.
Platform OEMs now bundle airframe supply with through-life support contracts rather than discrete component sales. Military procurement offices in the United States favor this arrangement for sustainment cost predictability. The model concentrates supplier relationships around firms with repair station certification.
Unmanned Composites Market Segmentation
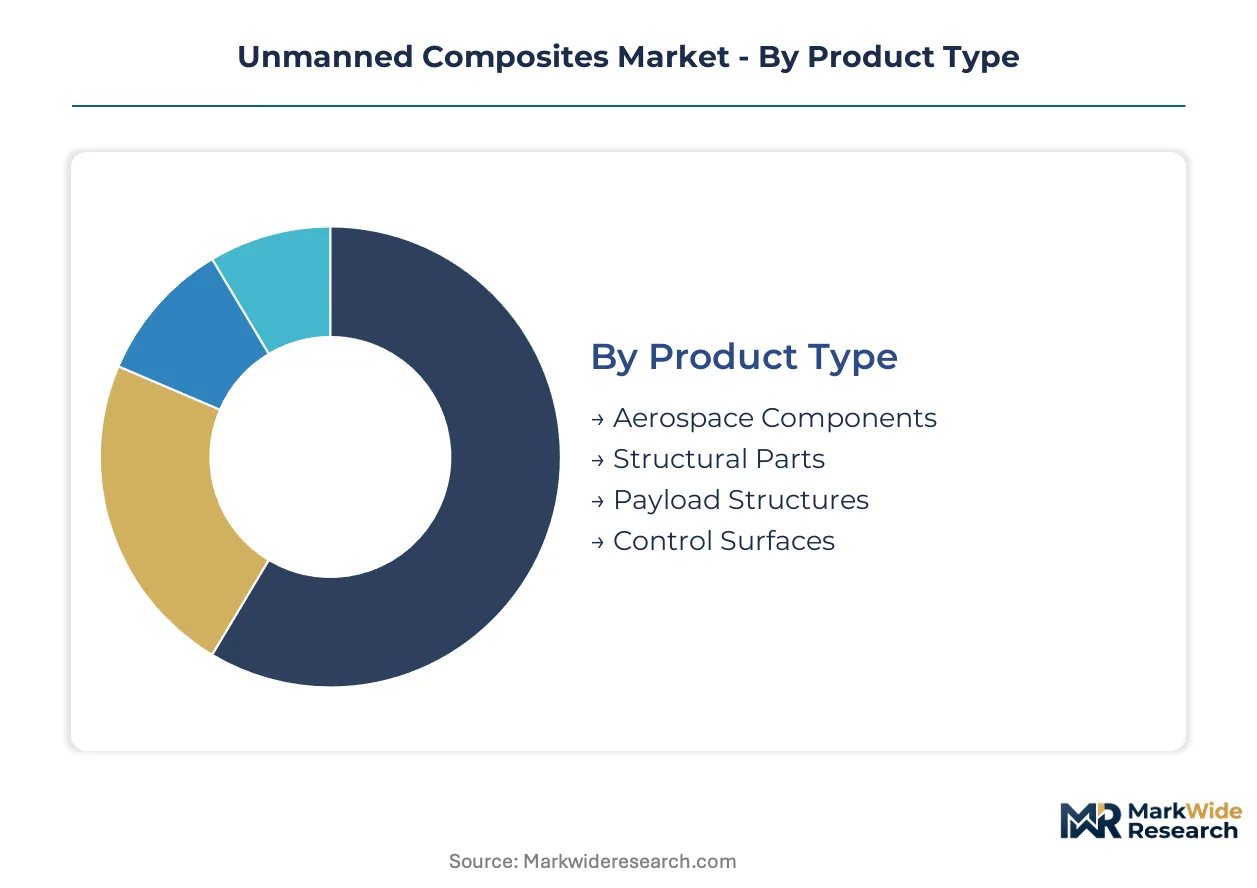
Unmanned composite procurement decisions pivot on certification burden, specific strength targets, and manufacturing scalability. Each segmentation dimension reveals distinct trade-offs between performance, cost, and regulatory compliance that shape supplier selection and capacity allocation.
Product Type:
Buyers prioritize damage tolerance thresholds and repair protocol maturity when selecting composite product categories for unmanned platforms.
- Aerospace Components:Engineered laminates for wing skins, nacelles, and empennage assemblies requiring FAA Part 23 equivalency demonstrations. Demand concentrates in United States defense UAV programs where fatigue resistance specifications exceed commercial thresholds.
- Structural Parts:Primary load-bearing elements including bulkheads, longerons, and joint fittings manufactured through automated fiber placement. United States urban air mobility startups specify these for electric vertical takeoff airframes where mass reduction directly extends battery endurance.
- Payload Structures:Sensor housings and mission equipment bays optimized for electromagnetic transparency.
- Control Surfaces:Ailerons, rudders, and elevators requiring precise stiffness-to-weight ratios for flight stability.
Aerospace Components leads on scale; Structural Parts leads on momentum.
Manufacturing Process:
Process selection hinges on capital availability, volume forecasts, and cure cycle qualification status with certifying authorities.
- Layup Process:Manual or robotic fiber deposition allowing geometric flexibility for prototype and low-rate initial production. United States Navy UAV contractors favor this approach for rapid design iteration before process freeze.
- Filament Winding:Automated fiber placement on rotating mandrels producing cylindrical pressure vessels and rocket motor cases. Japanese and South Korean drone OEMs specify this for high-altitude pseudo-satellite helium containment vessels.
- Resin Infusion:Vacuum-assisted resin transfer molding achieving consistent fiber volume fractions without autoclave investment.
- Autoclave:Pressure-cured laminates delivering aerospace-grade void content and mechanical properties for primary structures.
Layup Process dominates current capacity; Filament Winding gains share fastest in adjacent aerospace applications.
End User Industry:
Industry verticals impose divergent qualification protocols, with defense and commercial aerospace maintaining distinct material traceability standards.
- Aerospace:Commercial drone manufacturers pursuing FAA type certification for operations beyond visual line of sight. United States logistics operators specify composite airframes meeting ASTM F3061 standards for package delivery UAVs.
- Defense:Military procurement agencies requiring MIL-STD-810 environmental testing and ITAR-controlled supply chains. NATO member states concentrate orders for tactical UAV fuselages with radar signature management specifications.
- Automotive:Prototype autonomous ground vehicle panels leveraging composite crash energy absorption.
- Marine:Uncrewed surface vessel hulls exploiting corrosion-resistant glass fiber formulations.
Defense commands premium pricing; Aerospace climbs the fastest as commercial certification pathways mature.
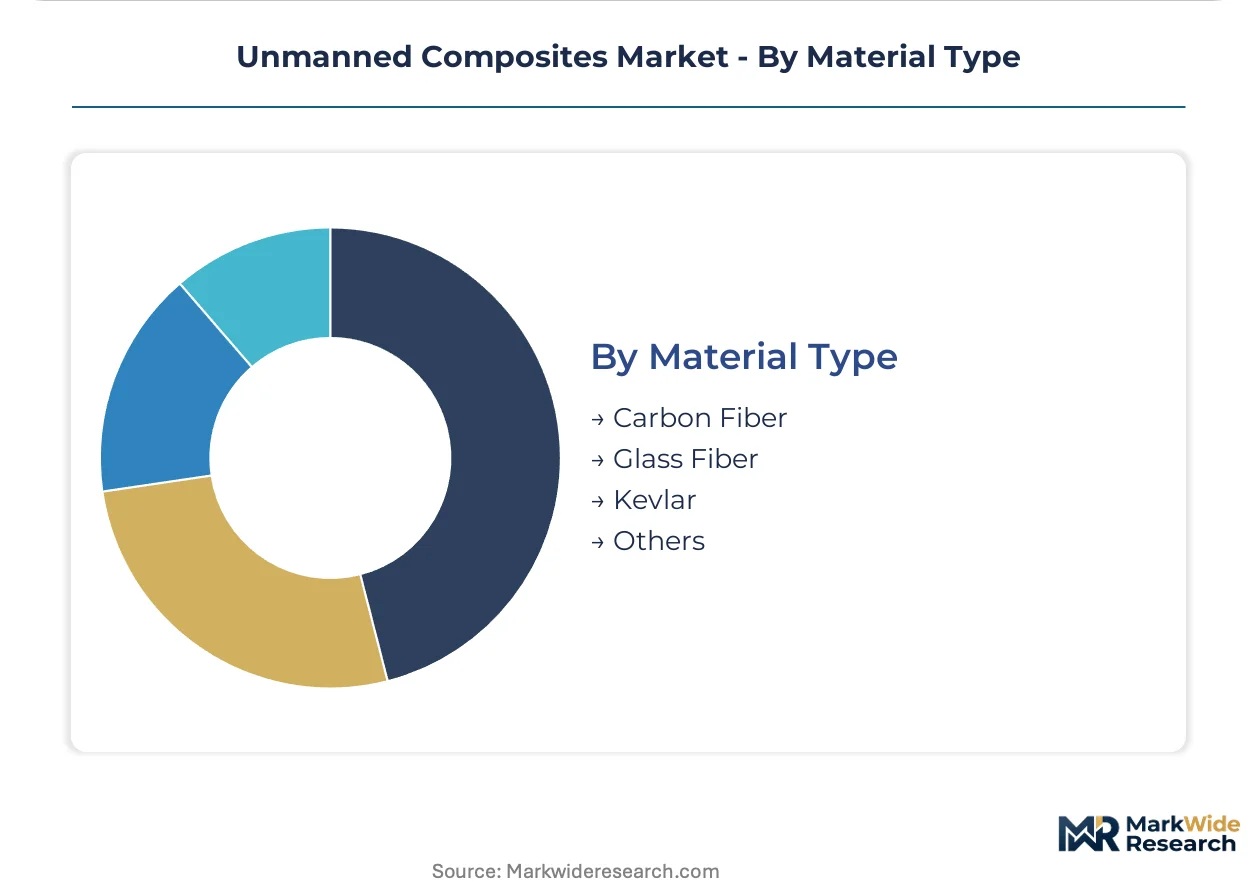
Material Type:
Material selection balances specific strength requirements against precursor cost volatility and supply security considerations.
- Carbon Fiber:PAN-based and pitch-based variants delivering exceptional stiffness-to-weight ratios for primary aerostructures. United States military UAV programs specify intermediate modulus grades for wing spars where fatigue life determines platform availability.
- Glass Fiber:E-glass and S-glass formulations offering cost-effective durability for secondary structures and marine applications. German maritime drone manufacturers specify these for Baltic Sea surveillance vessels requiring salt spray resistance.
- Kevlar:Aramid fiber laminates providing ballistic protection and vibration damping for critical subsystems.
- Others:Basalt fiber and natural fiber composites serving niche sustainability-driven prototyping.
Carbon Fiber leads on scale; Glass Fiber expands most quickly in cost-sensitive maritime segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping composite fabrication geography as manufacturers relocate toward jurisdictions with streamlined airworthiness certification and lower environmental compliance costs. FAA pathways in the United States and EASA frameworks in Germany impose divergent qualification timelines, pulling investment toward clusters with established audit infrastructure and defense procurement proximity.
United States
Defense UAV programs and urban air mobility startups concentrate demand for carbon fiber airframes in the aerospace corridors of California and Texas. FAA Part 23 equivalency demonstrations for commercial drone certification drive fabricators toward automated fiber placement investments. The Greater Los Angeles basin hosts prepreg manufacturers retooling for scalable unmanned platform production.
Germany
EASA design approval requirements above 25 kilograms create qualified supplier demand for European drone OEMs. REACH authorization constraints on epoxy hardeners force resin system reformulation among Bavarian chemical suppliers. The Munich-Stuttgart corridor anchors composite R&D facilities serving dual-use aerospace applications.
Japan
High-altitude pseudo-satellite programs specify filament-wound helium containment vessels from domestic drone OEMs. METI industrial standards for unmanned aircraft materials align with JIS certification protocols. The Nagoya aerospace cluster integrates precursor-to-prepreg operations for supply security.
South Korea
Defense modernization programs specify radar-signature-managed UAV fuselages from local system integrators. MFDS chemical registration requirements parallel EASA material traceability burdens. The Busan-Ulsan manufacturing belt concentrates glass fiber hull fabrication for maritime surface vessels.
United Kingdom
ITAR-controlled supply chain access draws defense contractors toward established aerospace clusters in the Midlands and Southwest. The Civil Aviation Authority's unmanned aircraft certification framework references EASA damage tolerance thresholds. Bristol and Basingstoke host composite repair stations qualified for military sustainment contracts.
Unmanned Composites Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue out-of-autoclave process specialization and regional certification shortcuts. The supplier base concentrates around vertically integrated resin-formulation specialists and carbon fiber precursor manufacturers with existing aerospace qualification infrastructure. Three archetypes dominate: defense-qualified legacy suppliers, commercial-drone-focused fabricators, and materials-science spinouts from university research parks. Competitive maneuvering centers on capacity expansion for automated fiber placement lines and strategic partnerships with urban air mobility platform OEMs.
Within the defense-qualified tier, Solvay S.A. and Hexcel Corporation represent established European and North American anchors respectively. Toray Industries, Inc. exemplifies Asian vertical integration from precursor through prepreg operations. These three occupy positions where material traceability infrastructure and existing audit relationships create qualification pathway advantages for dual-use technology convergence.
| Leading Market Players |
|---|
| Solvay S.A. |
| Mitsubishi Chemical Corporation |
| Hexcel Corporation |
| Gurit Holding AG |
| SGL Carbon SE |
| Toray Industries, Inc. |
| General Dynamics Corporation |
| Northrop Grumman |
| Teijin Limited |
| Others |
Cost & Logistics Intelligence
Automated fiber placement adoption simultaneously compresses labor content and concentrates supplier tiers around capital-intensive equipment holders, reshaping how composite airframe pricing power accrues to firms with qualified process infrastructure. Defense procurement consolidation toward scalable UAV production pulls capacity toward military-grade qualification protocols, while EPA styrene emission controls filter out regional fabricators unable to fund closed-infusion equipment.
Pricing Analysis
Direct-to-OEM contracts dominate pricing structures, with defense contractors negotiating long-term offtake agreements that bundle airframe supply with through-life support. Pricing stratifies across FAA-certified, EASA-qualified, and non-certified tiers, with certification investment creating margin differentiation. Cost compression in commercial drone segments intensifies because urban air mobility startups prioritize battery endurance over material grade, making automotive prototyping buyers most price-sensitive while defense agencies remain least sensitive due to radar signature specifications.
Supply Chain Analysis
Freight costs for carbon fiber precursor from Japan and South Korea to North American prepreg manufacturers anchor landed cost structures for defense UAV programs. The supply chain draws from acrylonitrile feedstock markets in the United States, precursor production in Japan, and autoclave cure capacity concentrated in California and Texas aerospace clusters. Single-source vulnerability sits with qualified resin formulators serving EASA traceability requirements. Distribution runs through defense procurement offices and urban air mobility platform OEMs rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where FAA Part 23 equivalency demonstrations and EASA design approval frameworks concentrate demand around firms with existing audit infrastructure. Defense procurement agencies and commercial drone OEMs alike now specify damage tolerance thresholds that filter out uncertified suppliers.
For Market Incumbents: Hedge against out-of-autoclave process disruption by qualifying alternative cure cycles before defense procurement agencies mandate rapid surge capacity specifications. Incumbents should anchor backward integration into precursor supply to stabilize acrylonitrile price volatility exposure, while reinforcing repair station certification to capture through-life support contract bundling.
For New Entrants and Emerging Players: Launch via filament-winding specialization for high-altitude pseudo-satellite helium containment vessels, where Japanese and South Korean drone OEMs specify domestic supply security over established brand preference. Maritime surface vessel hull fabrication for Pacific Rim defense modernization programs offers the most penetrable segment, with glass fiber formulations requiring lower capital thresholds than carbon fiber aerospace qualification.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with closed-infusion capability but lacking FAA audit relationships, as EPA emissions controls have stranded their open-mold capacity without certification pathway investment. Long-term viability favors firms with dual-use technology convergence potential across satellite launch assist and unmanned aerial segments. Watch EASA-REACH harmonization on epoxy hardener restrictions as the inflection signal for European supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Investment | Defense contractors in Texas and California accelerate robotic layup adoption for scalable UAV fuselage production. |
| Out-of-Autoclave Qualification | NATO procurement offices specify these cure cycles to enable rapid manufacturing surge capacity. |
| Repair Station Certification | Military sustainment contracts bundle airframe supply with through-life support, favoring qualified service networks. |
| Resin System Reformulation | REACH authorization constraints force Bavarian chemical suppliers to reformulate epoxy hardeners for EASA compliance. |
| Filament Winding Capacity Expansion | Japanese drone OEMs specify domestic helium containment vessel supply for high-altitude pseudo-satellite programs. |
Research Approach
Multiple input streams — primary interviews with defense procurement officers, composite plant managers, and urban air mobility CTOs, plus secondary validation through FAA certification databases, EASA design approval filings, and customs trade data — were reconciled to construct market estimates. Bottom-up triangulation across manufacturing process segments and top-down validation against defense budget allocations provided cross-checks. Input from prepreg technical directors, resin formulation R&D leads, and UAV platform engineers informed capacity and qualification timeline assumptions.
Data-stream reconciliation across product type, manufacturing process, end user industry, and material type dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by qualification burden and specific strength requirements. Carbon fiber precursor cost volatility, EPA emissions compliance thresholds, and FAA Part 23 equivalency demonstration timelines served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including ITAR-controlled supply chain disruptions, acrylonitrile price spikes beyond historical volatility bands, and accelerated EASA-REACH regulatory harmonization. Forecasts reflect assumptions about certification pathway maturation and defense procurement continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Vetronics Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Drone Parachute System Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Rotary-Wing Lidar Drone Market