
 High Altitude Platform Market | 2026-2036
High Altitude Platform Market Size, Share, and Industry Trends Forecast 2026-2036
High Altitude Platform Market Analysis
The capital-intensity divergence between stratospheric balloon specialists and legacy aerostat manufacturers is bifurcating competitive dynamics. Northrop Grumman leverages its defense contracting scale to anchor long-duration surveillance programs. Sceye Inc. differentiates through materials-science advances in superpressure envelope design. Israel Aerospace Industries sustains technology leadership in solar-electric propulsion for persistent station-keeping.
High altitude platforms operate at altitudes between 18 and 50 kilometers, employing aerostatic lift, aerodynamic flight, or hybrid systems to carry communications relays, remote sensing payloads, or surveillance equipment for weeks to months. HAPS and stratospheric balloons command the largest current deployment volumes due to lower operational complexity and established regulatory pathways. Surveillance and telecommunications applications are expanding fastest, driven by defense budgets and rural broadband mandates, while environmental monitoring retains stable government funding but slower procurement cycles.
The FAA governs U.S. airspace integration for HAPS through experimental certificates and spectrum coordination with the FCC, while EASA develops unified European certification standards under its U-space framework. The ITU allocates stratospheric spectrum bands, directly constraining which frequencies operators may use for relay services. Stakeholders must track evolving national airspace classifications and payload export-control lists to anticipate operational boundaries and partnership requirements.
Market Dynamics
The stratospheric platform sector is bifurcating between defense contractors optimizing for multi-month persistence and commercial operators racing to prove unit economics at scale. This tension between mission endurance and cost-per-flight-hour is restructuring supplier relationships and certification priorities across the value chain.
Growth Catalysts
- Rural broadband mandates:The FCC's Rural Digital Opportunity Fund is channeling subsidies toward stratospheric relay trials in unserved U.S. counties. Telecom operators are leveraging these funds to validate HAPS as backhaul alternatives to fiber builds.
- Defense surveillance modernization:Persistent ISR requirements from military end-users are accelerating solar-electric propulsion adoption. Programs in Israel and France are establishing operational precedents for multi-week station-keeping.
- REACH-aligned material standards:European envelope manufacturers are certifying superpressure films under updated chemical safety protocols. These materials reduce helium permeation rates and extend flight duration.
Market Restraints
- Helium supply concentration:The U.S. Federal Helium Reserve's phased drawdown has tightened global availability. Stratospheric balloon operators face input cost volatility and sourcing constraints from Qatar and Algeria.
- Airspace integration friction:FAA experimental certificates impose altitude reservation windows that limit operational flexibility. Certificate renewal timelines create planning uncertainty for commercial service launches.
- Geostationary satellite substitution:Low-Earth-orbit constellations from SpaceX and Amazon are compressing addressable market for stratospheric broadband relays in mid-latitude regions.
Strategic Opportunities
- Disaster response networks:Hurricane-prone U.S. states are pre-positioning HAPS contracts for cellular restoration. Florida and Puerto Rico procurement frameworks prioritize rapid-deployment platforms.
- Carbon monitoring payloads:Convergence of hyperspectral imaging and AI-driven analytics is opening environmental monitoring applications. European Space Agency funding supports methane detection trials.
- India's stratospheric corridor:The country's national aviation regulator is designating dedicated HAPS flight zones above Rajasthan and Gujarat. Early entrants gain operational data advantages for tropical station-keeping.
Industry Challenges
- Aerosystems engineering talent scarcity:Stratospheric envelope design and superpressure control systems require specialized skills. Competition with legacy aerospace and renewable energy sectors tightens hiring pipelines.
- Multi-agency certification complexity:Payload export-control classifications under U.S. ITAR and EAR regimes add compliance layers. Dual-use surveillance equipment triggers State Department licensing timelines that extend program schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Altitude Platform Market |
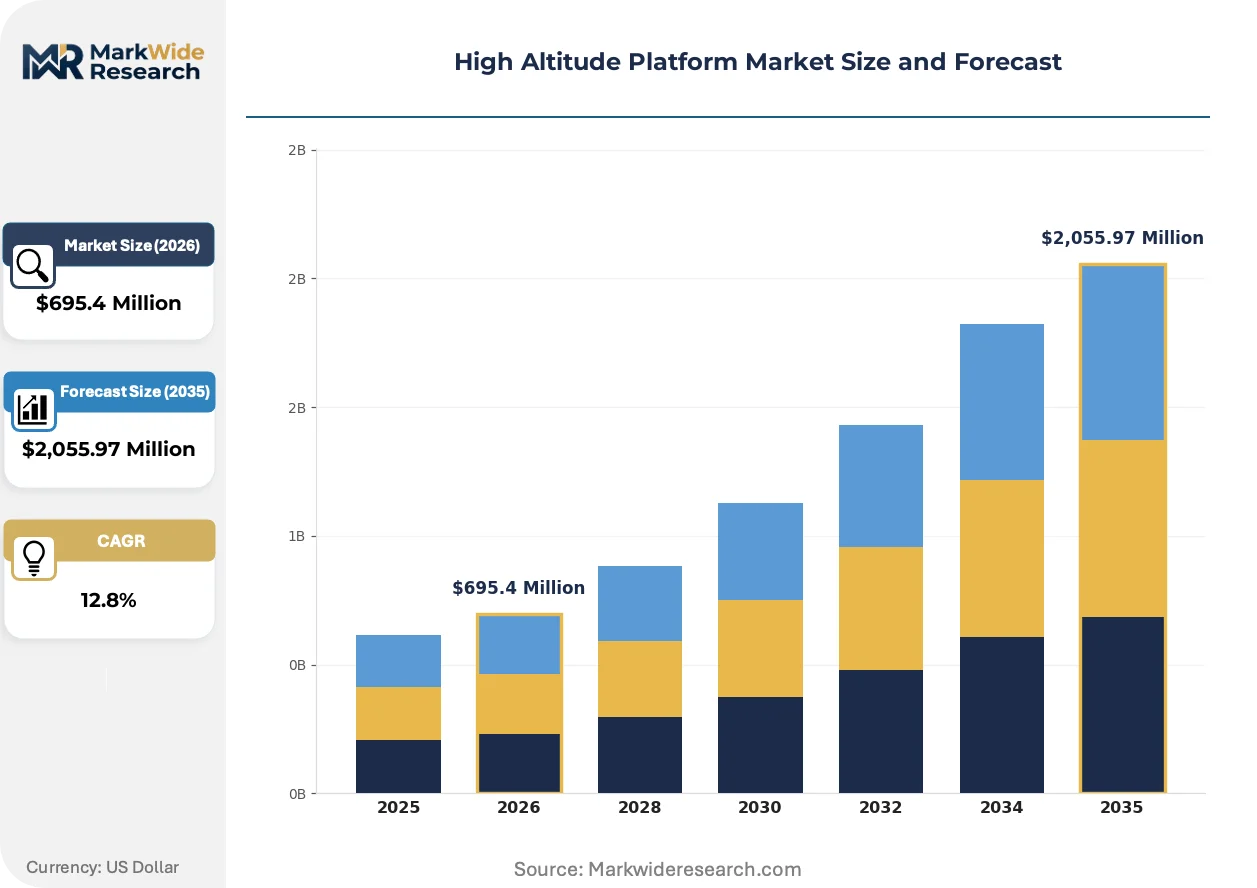
| Market Size in 2026 | $695.4 Million |
| Market Size in 2035 | $2,055.97 Million |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HAPS, UAVs, Airships, Stratospheric Balloons Technology: Fixed Wing, Rotary Wing, Launch Systems, Payload Technologies Application: Telecommunications, Environmental Monitoring, Disaster Management, Surveillance End User: Government, Defense, Research Institutions, Commercial Enterprises |
| Companies Covered | AeroVironment, Inc., Israel Aerospace Industries, Northrop Grumman, Lindstrand Technologies Limited, ILC Dover LP, AIRBUS, TCOM, L.P., Sceye Inc., Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Altitude Platform Market Emerging Trajectories
Materials science breakthroughs and regulatory sandbox expansions are compressing development cycles for stratospheric platforms. Operators are shifting from demonstration flights to revenue-generating service contracts.
Superpressure envelope polymers with ultra-low helium permeability are supplanting conventional zero-pressure balloon designs for missions exceeding thirty days. Defense agencies in the United States and Israel are adopting these systems for persistent border surveillance. The technology is enabling month-long station-keeping without altitude cycling, reducing operational crew requirements and ground infrastructure costs.
EASA's U-space framework for unmanned aircraft is establishing unified certification pathways for stratospheric operations above European airspace. The regulation mandates detect-and-avoid capabilities and spectrum coordination with terrestrial networks. Commercial operators are responding by integrating satellite-based ADS-B transponders and negotiating priority access to 2 GHz bands for relay services.
Telecom procurement teams are unbundling HAPS services from traditional satellite backhaul contracts. Rural network operators in the United States are signing availability-based agreements that tie payments to coverage uptime rather than asset ownership. This shift is most visible in Mountain West states where fiber economics remain unfavorable and terrain complicates tower construction.
High Altitude Platform Market Segmentation
Segmentation in the high altitude platform market reveals how platform economics diverge across mission profiles and customer procurement frameworks. Each category exposes distinct vulnerability to substitute technologies and regulatory friction.
Product Type:
Stratospheric balloons face the most acute substitution pressure from proliferating low-Earth-orbit constellations, while airships defend persistent station-keeping applications where satellite latency proves prohibitive.
- HAPS:Solar-electric platforms achieve multi-week endurance through regenerative power systems and lightweight composite structures. Israeli defense programs and French border surveillance contracts anchor near-term procurement volume.
- Stratospheric Balloons:Superpressure envelope designs extend flight duration beyond thirty days without altitude cycling. FCC Rural Digital Opportunity Fund trials in unserved U.S. counties validate commercial backhaul economics against fiber substitution.
- UAVs:Tactical platforms serve short-duration ISR missions below stratospheric altitudes. Military end-users in the United States prioritize rapid redeployment over persistence.
- Airships:Hybrid aerostatic-aerodynamic systems carry heavier payloads for maritime surveillance. EASA certification pathways under U-space frameworks constrain European deployment timelines.
Stratospheric balloons retain volume leadership; HAPS holds the steepest expansion curve.
Technology:
Cost tiers separate mature payload integration from emerging launch system investments that absorb disproportionate R&D allocation.
- Fixed Wing:Rigid structures with solar-electric propulsion dominate endurance benchmarks. Israel Aerospace Industries and French defense contractors anchor platform development.
- Launch Systems:High-altitude deployment mechanisms determine operational readiness windows. Sceye Inc. advances materials-science solutions for rapid ascent profiles.
- Rotary Wing:Vertical takeoff configurations suit contested terrain access. Payload weight penalties limit stratospheric applicability.
- Payload Technologies:Hyperspectral imaging and AI-driven analytics enable methane detection trials funded by the European Space Agency.
Fixed wing systems command the premium tier; launch systems attract the most concentrated venture investment.
Application:
Customer procurement maturity varies sharply, with telecommunications contracts advancing fastest toward availability-based service models.
- Telecommunications:Rural broadband mandates in the United States and India drive backhaul substitution trials. Mountain West operators sign uptime-guaranteed contracts decoupled from asset ownership.
- Surveillance:Persistent ISR requirements from Israeli and French defense agencies establish multi-week station-keeping precedents. Northrop Grumman leverages defense contracting scale for program anchoring.
- Environmental Monitoring:Carbon detection payloads converge with regulatory reporting obligations. Government funding remains stable but procurement cycles extend beyond commercial timelines.
- Disaster Management:Hurricane-prone U.S. states pre-position rapid-deployment contracts. Florida and Puerto Rico procurement frameworks prioritize cellular restoration speed.
Telecommunications captures the largest addressable demand pool; disaster management shows the most volatile procurement spikes.
End User:
Defense contracting concentration in Israel, France, and the United States shapes supplier qualification barriers and export control complexity.
- Defense:Multi-month persistence requirements favor solar-electric platforms with ITAR-classified payloads. State Department licensing timelines extend program schedules by quarters.
- Government:Civilian agencies fund environmental monitoring through stable but slow procurement cycles. FAA experimental certificates impose altitude reservation constraints.
- Commercial Enterprises:Telecom operators unbundle HAPS services from satellite backhaul contracts. Availability-based pricing models reduce capital deployment risk.
- Research Institutions:Atmospheric science missions validate platform performance in tropical station-keeping conditions. India's stratospheric corridor above Rajasthan provides operational data advantages.
Defense commands the highest contract values; commercial enterprises are expanding fastest into recurring service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Israel where defense contracting scales anchor premium platform economics, while cost-sensitive procurement in India and emerging European markets compresses margins for commercial operators.
United States
Defense surveillance modernization and rural broadband mandates drive procurement concentration. The FAA governs airspace integration through experimental certificates with altitude reservation windows. Stratospheric balloon trials funded by the FCC's Rural Digital Opportunity Fund validate commercial backhaul economics in Mountain West states where fiber builds remain uneconomic.
Israel
Persistent ISR requirements from military end-users accelerate solar-electric propulsion adoption for multi-week station-keeping. The country's national aviation regulator coordinates with defense agencies on operational precedents. Technology development clusters around Tel Aviv sustain leadership in lightweight composite structures and regenerative power systems.
France
Border surveillance contracts and EASA regulatory sandbox participation shape demand patterns. EASA's U-space framework establishes unified certification pathways for stratospheric operations above European airspace. Industrial activity concentrates in Toulouse and the aerospace corridor where hybrid aerostatic-aerodynamic systems undergo certification trials.
India
The national aviation regulator designates dedicated HAPS flight zones above Rajasthan and Gujarat for tropical station-keeping validation. TRAI spectrum coordination frameworks support backhaul substitution trials in unserved rural districts. Early entrants gain operational data advantages in high-temperature, high-radiation atmospheric conditions.
United Kingdom
Environmental monitoring applications and atmospheric science missions sustain government funding flows. The country's national aviation regulator processes experimental flight permissions under evolving unmanned aircraft frameworks. Research institutions in southern England collaborate with European Space Agency programs on methane detection payload trials.
High Altitude Platform Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. Defense contractors with decades of aerospace integration experience anchor the premium tier for multi-month persistence missions. Commercial specialists with materials-science backgrounds occupy the cost-optimized tier for rapid-deployment applications. Two strategic moves dominate competitive positioning: strategic partnerships with telecom operators for availability-based service contracts, and vertical integration into superpressure envelope manufacturing to control helium permeation rates.
Within the defense contractor tier, Northrop Grumman and Israel Aerospace Industries represent established program anchors with sustained government relationships. Sceye Inc. occupies a position among commercial specialists advancing rapid ascent profiles. These three companies exemplify the archetype separation between mission endurance optimization and unit economics validation.
| Leading Market Players |
|---|
| AeroVironment, Inc. |
| Israel Aerospace Industries |
| Northrop Grumman |
| Lindstrand Technologies Limited |
| ILC Dover LP |
| AIRBUS |
| TCOM, L.P. |
| Sceye Inc. |
| Thales |
| Others |
Supply Flow & Price Mechanics
Superpressure envelope polymers displacing conventional zero-pressure balloon designs are redrawing supply geography toward REACH-certified European manufacturers while compressing procurement economics for month-long endurance missions.
Pricing Analysis
The customization-premium spread between defense-configured solar-electric platforms and commercial stratospheric balloon services spans three performance tiers. Solar-electric HAPS with ITAR-classified payloads command substantial premiums over FCC-subsidized rural broadband trials, while standard aerostat leases for disaster response occupy mid-market positioning. Price differentiation hinges on station-keeping duration guarantees and helium permeation certification grades. Cost compression in commercial backhaul segments is intensifying because LEO constellation operators are compressing addressable demand for stratospheric relays. Telecom procurement teams in Mountain West states exhibit highest price sensitivity, whereas Israeli and French defense agencies prioritize mission persistence over unit economics.
Supply Chain Analysis
The United States and Israel anchor solar-electric propulsion system fabrication, while France and Germany concentrate superpressure envelope polymer production under REACH-aligned material standards. Stratospheric platform manufacturing draws from Qatar and Algeria for helium supply, South Korea and Japan for lightweight composite structures, and domestic U.S. facilities for payload integration. Single-source vulnerability permeates helium feedstock given the Federal Helium Reserve drawdown and concentration of global extraction in Middle Eastern and North African suppliers. Distribution runs through defense contracting channels for ISR programs and availability-based service contracts for commercial telecommunications deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against LEO constellation substitution by anchoring persistent station-keeping applications where satellite latency proves prohibitive.
For Market Incumbents: Compound technology leadership in multi-week endurance through captive supply of superpressure envelope manufacturing, securing helium sourcing agreements with Algerian and Qatari suppliers before drawdown constraints tighten further. Anchor defense contracting relationships in Israel and France against emerging solar-electric platform specialists. For New Entrants and Emerging Players: Lead with rapid-deployment stratospheric balloon services for disaster response procurement frameworks in hurricane-prone U.S. states, where cellular restoration speed outweighs persistence requirements. India's designated HAPS flight zones above Rajasthan and Gujarat present the most penetrable geography for tropical station-keeping validation without legacy defense contractor qualification barriers. For Investors and Strategic Acquirers: Capital is best deployed toward materials-science specialists with backward integration into envelope polymer production, positioned to capture margin expansion as REACH-certified films displace conventional designs. The inflection signal to watch is FAA experimental certificate streamlining that reduces altitude reservation friction for commercial service launches.| Strategic Initiative | Industry Significance |
|---|---|
| Superpressure Envelope Manufacturing Scale-Up | REACH-certified polymer production captures margin from helium permeation performance advantages. |
| Availability-Based Service Contract Structuring | Uptime-guaranteed telecom agreements decouple revenue from asset ownership in Mountain West states. |
| Helium Supply Agreement Diversification | Long-term offtake contracts with Algerian and Qatari suppliers mitigate Federal Reserve drawdown risk. |
| FAA Experimental Certificate Navigation | Regulatory sandbox participation accelerates commercial launch timelines in U.S. airspace. |
| EASA U-Space Certification Alignment | Unified European pathways enable detect-and-avoid capability deployment above member state airspace. |
Methodological Framework
Initial hypotheses were tested against primary input from stratospheric platform engineering directors, defense procurement officers at Israeli and French agencies, telecom network planning executives, and FAA certification specialists, then refined through secondary validation against EASA regulatory filings, FCC Rural Digital Opportunity Fund disbursement records, ITU spectrum allocation databases, and SEC filings from publicly traded aerospace contractors. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring across the analysis window.
Variance decomposition separated volume drivers from pricing dynamics across platform type, technology maturity, application procurement framework, and end-user contracting archetype. CAGRs were derived from segment-level growth rate reconciliation with aggregate market expansion. Forecast inputs incorporated helium supply elasticity parameters and experimental certificate approval velocity assumptions.
Forecasts assume regulatory continuity in FAA experimental certification regimes and EASA U-space implementation timelines; material policy shifts in stratospheric airspace classification or ITAR payload export controls would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
North America ROV Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
Dismounted Soldier Systems Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Global Submarine Payload Market