
 US Autonomous Navigation Market | 2026-2036
US Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
US Autonomous Navigation Market Insights
Software-defined navigation features is decoupling hardware sales from recurring revenue streams in the US autonomous navigation sector. Waymo leverages its extensive real-world mapping database to sustain competitive differentiation in urban autonomous driving. NVIDIA Corporation anchors the upstream compute layer through its DRIVE platform, while Lockheed Martin Corporation dominates defense-grade autonomous systems for military end users.
Autonomous navigation encompasses sensor fusion architectures that integrate LiDAR point clouds, visual odometry, and GNSS corrections to achieve sub-decimeter positioning accuracy for unmanned platforms. The technology serves commercial and defense applications requiring continuous localization without human intervention. Computer vision segments are capturing expanding margin pools as edge inference costs decline, while maritime vessel applications remain nascent relative to personal vehicle and drone deployments. LiDAR hardware faces pricing pressure as solid-state designs displace mechanical scanning units across industrial robot installations.
FAA regulations governing beyond-visual-line-of-sight drone operations and NHTSA autonomous vehicle testing protocols are tightening compliance thresholds for market participants. The Department of Defense's ethical AI frameworks and cybersecurity mandates from the Pentagon are reshaping product specifications for defense contractors. Stakeholders must monitor how federal preemption of state-level autonomous vehicle laws affects deployment timelines and liability structures.
Market Dynamics
Defense procurement of unmanned ground vehicles is accelerating adoption curves while the FAA's Remote ID mandate for drones reshapes compliance architectures across commercial and federal end uses.
Growth Catalysts
- Remote ID Mandate:The FAA's drone identification requirement is creating immediate retrofit demand across commercial UAV fleets and forcing navigation stack upgrades for compliance.
- Silicon Valley Testing Clusters:California's concentrated autonomous vehicle proving grounds generate knowledge spillovers that compress development cycles for participating firms.
- Sensor Fusion Architectures:Integration of LiDAR point clouds with visual odometry and GNSS corrections enables sub-decimeter positioning accuracy previously unattainable for unmanned platforms.
Market Restraints
- LiDAR Hardware Pricing Pressure:Solid-state designs are compressing margins for mechanical scanning unit suppliers serving industrial robot installations.
- Supply Concentration Risk:Upstream compute layer dependence on NVIDIA's DRIVE platform creates vulnerability for tier-one integrators lacking alternative chip architectures.
- Beyond-Visual-Line-of-Sight Friction:FAA operational waivers for BVLOS drone flights remain inconsistently granted, throttling commercial deployment timelines.
Strategic Opportunities
- Maritime Vessel Autonomy:Commercial shipping and offshore inspection applications remain nascent relative to personal vehicle and drone deployments, offering first-mover positioning.
- Defense Ethical AI Frameworks:The Department of Defense's emerging ethical guidelines create specification windows for contractors able to demonstrate transparent decision architectures.
- Edge Inference Cost Compression:Declining semiconductor costs for onboard processing enable computer vision segments to capture expanding margin pools from cloud-dependent alternatives.
Industry Challenges
- Cybersecurity Mandate Compliance:Pentagon cybersecurity specifications for autonomous defense systems require specialized engineering talent scarce in commercial navigation markets.
- Federal-State Preemption Uncertainty:Stakeholders face deployment timeline risk from unresolved liability structures where NHTSA protocols intersect with state-level autonomous vehicle laws.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Autonomous Navigation Market |
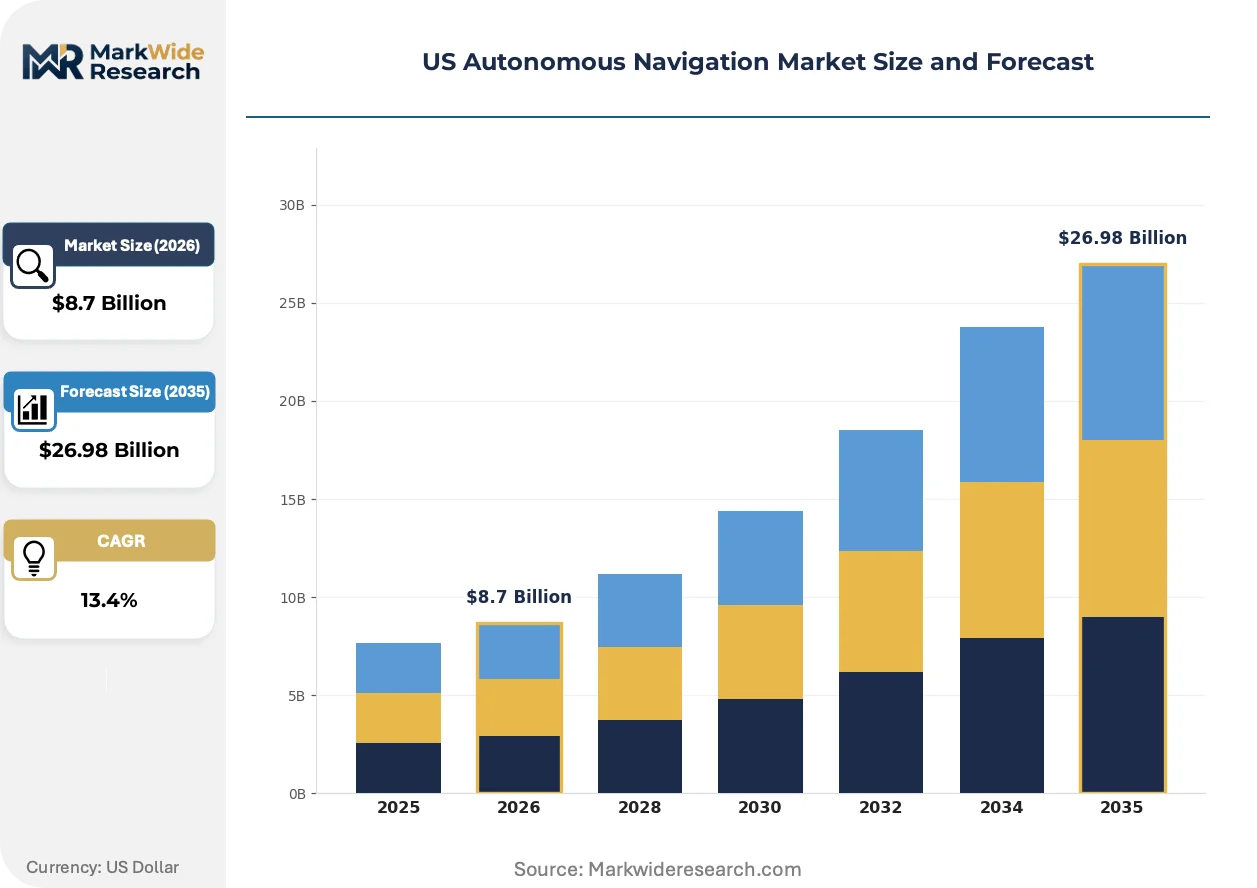
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Computer Vision, GPS, Ultrasonic Sensors Application: Personal Vehicles, Drones, Industrial Robots, Maritime Vessels End User: Logistics, Defense, Agriculture, Transportation Services Distribution Channel: Direct Sales, Partnerships, Online Sales, Distributors |
| Companies Covered | Waymo, Cruise, Mobileye Global Inc., NVIDIA Corporation, L3Harris Technologies Inc., Northrop Grumman Corporation, Lockheed Martin Corporation, BAE Systems, Aurora, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Autonomous Navigation Market Trends and Innovations
Software-defined navigation is decoupling hardware revenue from recurring service streams while regulatory mandates and procurement model evolution reshape competitive positioning.
Sensor fusion architectures are integrating LiDAR point clouds, visual odometry, and GNSS corrections into unified perception stacks. Defense contractors and commercial drone operators are adopting these systems at accelerated procurement cycles. The technology is integrating previously siloed positioning modalities into single-chip solutions that compress bill-of-materials costs for unmanned platform manufacturers.
NHTSA autonomous vehicle testing protocols are tightening validation thresholds for public road deployment. The industrial consequence is extended pre-commercialization timelines and elevated documentation burdens for developers. California's Department of Motor Vehicles and Arizona's autonomous vehicle programs are responding with streamlined permitting tracks that reward extensive simulation-based validation.
Software-defined navigation features are unbundling from hardware sales into subscription-based recurring revenue models. Fleet operators and defense procurement offices are displacing perpetual license purchases with per-mile or per-mission pricing structures. This shift concentrates most visibly among urban autonomous shuttle operators in Texas and Florida municipal transit pilots.
US Autonomous Navigation Market Segmentation
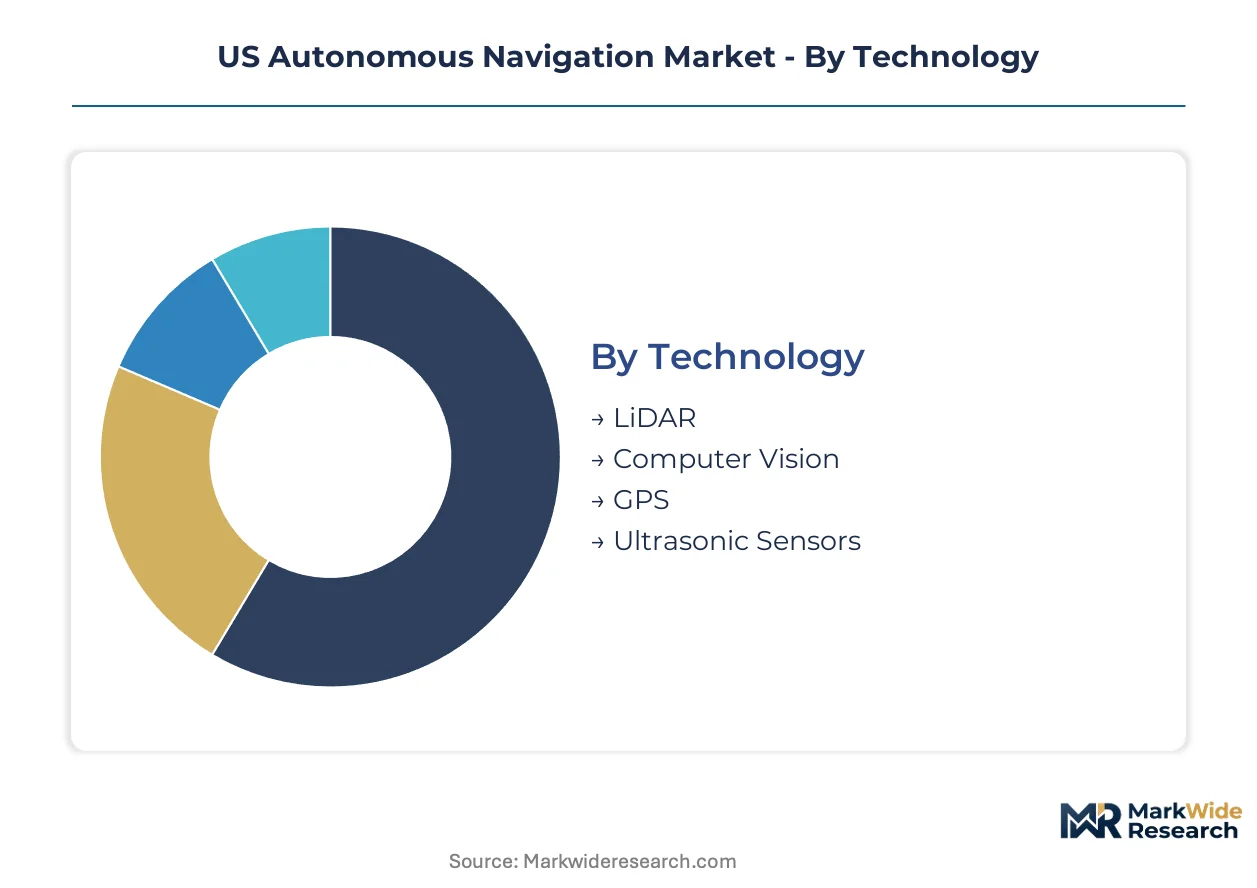
Segmentation reveals how autonomous navigation technology stacks diverge across performance requirements, regulatory exposure, and procurement models. Understanding these divisions exposes where upgrade cycles concentrate and which configurations face replacement pressure from solid-state alternatives.
Technology:
Upgrade cycles vary dramatically by sensor modality, with mechanical scanning units facing accelerated replacement timelines against solid-state architectures.
- LiDAR:Mechanical scanning units generate dense point clouds for sub-decimeter positioning but face margin compression as solid-state designs displace legacy hardware across industrial robot installations. Defense unmanned ground vehicle programs in California's testing corridors sustain procurement of high-specification units despite commercial price erosion.
- Computer Vision:Edge inference architectures process visual odometry streams through onboard neural accelerators, enabling real-time localization without cloud dependency. Texas and Florida municipal shuttle pilots are driving subscription-based feature unbundling that separates perception software from camera hardware sales.
- GPS:GNSS correction services integrate RTK and PPP-RTK signals to resolve carrier-phase ambiguities for centimeter-level accuracy in agricultural autosteer and drone surveying applications.
- Ultrasonic Sensors:Short-range proximity detection serves low-speed maneuvering in warehouse automation and parking assistance where cost constraints exclude LiDAR deployment.
Volume placements concentrate in Computer Vision; the faster expansion belongs to solid-state LiDAR as mechanical unit retrofits accelerate.
Application:
Application segmentation tracks how regulatory maturity shapes deployment velocity and hardware specification divergence across mobility platforms.
- Personal Vehicles:NHTSA testing protocols mandate extensive simulation validation before public road permits, compressing development timelines for firms with Arizona and California streamlined permitting access. Urban autonomous driving stacks require redundant sensor configurations that elevate bill-of-materials costs relative to highway-constrained systems.
- Drones:FAA Remote ID compliance is forcing navigation stack upgrades across commercial UAV fleets, creating immediate retrofit demand for identification transponders and firmware updates. Beyond-visual-line-of-sight waivers remain inconsistently granted, throttling commercial expansion in inspection and delivery segments.
- Industrial Robots:Warehouse automation and manufacturing line navigation demand robust localization in GPS-denied environments, favoring LiDAR-visual fusion over satellite-dependent alternatives.
- Maritime Vessels:Commercial shipping and offshore inspection applications remain nascent, offering first-mover positioning for sensor fusion stacks adapted to salt spray and dynamic sea state conditions.
Personal Vehicles capture dominant investment flows; Maritime Vessels are climbing the fastest as regulatory frameworks for autonomous shipping mature.
End User:
End user segmentation exposes how procurement authority and mission criticality reshape pricing power and contract structure across vertical markets.
- Logistics:Fleet operators are displacing perpetual licenses with per-mile pricing structures, concentrating subscription revenue among urban last-mile automation providers.
- Defense:Pentagon cybersecurity mandates and ethical AI frameworks require specialized engineering talent scarce in commercial markets, creating specification windows for contractors with transparent decision architectures. Unmanned ground vehicle procurement is accelerating adoption curves through multi-year program commitments.
- Agriculture:Autosteer and precision spraying applications depend on RTK-corrected GPS with seasonal utilization patterns that favor ruggedized hardware over software-defined feature subscriptions.
- Transportation Services:Municipal transit pilots in Texas and Florida are testing autonomous shuttles under public-private partnership structures that transfer operational risk to technology vendors.
Defense procurement commands premium pricing; Transportation Services are gaining share fastest as municipal pilot programs proliferate.
Distribution Channel:
Channel segmentation tracks how customer scale and technical sophistication determine sales motion economics and support burden allocation.
- Direct Sales:Defense contractors and large fleet operators negotiate bespoke integration contracts with dedicated field engineering support, capturing multi-year service attachments.
- Partnerships:Tier-one automotive and aerospace integrators embed navigation modules through co-development agreements that specify exclusive supply periods.
- Online Sales:Developer kits and evaluation platforms reach research institutions and startup ventures through self-service procurement with limited technical support.
- Distributors:Industrial automation channels serve mid-market robot manufacturers with standardized sensor packages and regional inventory positioning.
Direct Sales dominate contract value; Online Sales are expanding most quickly as developer ecosystem participation broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California produces the majority of autonomous navigation R&D while Texas and Arizona consume disproportionate deployment permits relative to their population. Defense procurement concentrates in Virginia and Maryland corridors. Testing infrastructure investments lag in the Midwest and Southeast despite agricultural automation demand.
California
Silicon Valley hosts the densest concentration of autonomous vehicle testing permits, with Waymo and Cruise maintaining operational fleets across San Francisco and Los Angeles metro areas. The California Department of Motor Vehicles mandates disengagement reporting that shapes competitive positioning through transparency requirements. San Jose-to-San Francisco corridors generate knowledge spillovers that compress development cycles for participating sensor fusion developers.
Arizona
Phoenix and Tucson municipal governments issue streamlined autonomous vehicle permits with reduced documentation burdens relative to coastal jurisdictions. The Arizona Department of Transportation maintains permissive testing protocols that reward extensive simulation-based validation. Scottsdale and Tempe host commercial robotaxi deployments that generate real-world mileage data for perception algorithm refinement.
Texas
Dallas-Fort Worth and Austin municipal transit pilots test autonomous shuttles under public-private partnership structures. The Texas Department of Transportation regulates mixed-traffic testing without requiring California-equivalent disengagement disclosures. Houston's energy corridor drives maritime autonomy R&D for offshore inspection applications.
Virginia
Defense contractors cluster in Northern Virginia to access Pentagon procurement offices and NRO satellite correction services. The Commonwealth's autonomous vehicle testing program emphasizes federal cybersecurity compliance over commercial deployment velocity. Arlington and Fairfax counties host unmanned ground vehicle integration facilities for Army Futures Command programs.
Florida
Orlando and Miami municipal pilots concentrate on tourism and last-mile logistics applications with lower regulatory scrutiny than California equivalents. The Florida Department of Transportation permits autonomous shuttle operations in designated innovation zones. Tampa Bay's maritime infrastructure supports nascent autonomous vessel testing for port security applications.
US Autonomous Navigation Market Competitive Landscape
Capital-heavy defense contractors compete with asset-light commercial autonomy developers across divergent procurement timelines. The vendor base separates into three tiers: primes with multi-year Pentagon commitments, venture-backed urban autonomy specialists, and component suppliers serving industrial robot integrators. Dominant competitive moves include strategic partnerships for sensor fusion integration and geographic expansion into permissive regulatory jurisdictions.
Within the defense prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify contractors navigating Pentagon ethical AI frameworks and cybersecurity mandates. Waymo occupies a position among commercial autonomy developers leveraging extensive real-world mapping databases for urban navigation differentiation. NVIDIA Corporation anchors the upstream compute layer through its DRIVE platform, representing the concentration risk facing tier-one integrators lacking alternative chip architectures.
| Leading Market Players |
|---|
| Waymo |
| Cruise |
| Mobileye Global Inc. |
| NVIDIA Corporation |
| L3Harris Technologies Inc. |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| BAE Systems |
| Aurora |
| Others |
Pricing and Supply Chain Analysis
Captive integration into NVIDIA's DRIVE platform anchors pricing power for tier-one automotive integrators while locking defense contractors into multi-year chip supply agreements that resist spot-market volatility. This vertical control over upstream compute layers enables premium positioning for perception software stacks even as sensor hardware commoditizes.
Pricing Analysis
Margin tightening in mechanical LiDAR reflects solid-state displacement across industrial robot installations, compressing legacy supplier returns. Three-tier pricing structure across defense-grade, automotive-qualified, and developer-evaluation levels segments buyer willingness-to-pay, with FAA certification tiers adding further differentiation. Pricing pressure stems from semiconductor cost compression enabling edge inference alternatives to cloud-dependent navigation stacks. Logistics fleet operators exhibit highest price sensitivity through per-mile subscription demands, while Pentagon programs tolerate premium hardware costs for cybersecurity-hardened configurations.
Supply Chain Analysis
Specialized photonics engineering talent scarcity in Taiwan and South Korea constrains solid-state LiDAR manufacturing expansion despite wafer fabrication capacity availability. The supply chain draws from German precision optics, Japanese MEMS foundries, and domestic US defense-certified packaging facilities for radiation-hardened components. Single-source vulnerability concentrates in NVIDIA's GPU architecture dominance for autonomous vehicle training workloads. Distribution runs through tier-one automotive integrators embedding navigation modules, direct defense procurement channels for unmanned ground vehicles, and industrial automation distributors serving mid-market robot manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with FAA certification infrastructure and Pentagon cybersecurity clearances, forcing capital-constrained challengers toward component supplier roles or exit.
For Market Incumbents: Lock in exclusive sensor fusion partnerships with Arizona and California permitting authorities to preempt challenger access to streamlined validation tracks. Deepen backward integration into solid-state LiDAR foundry capacity before Taiwanese MEMS capacity tightens. Acquire ethical AI engineering talent scarce in commercial markets to satisfy emerging Pentagon transparency mandates. For New Entrants and Emerging Players: Municipal transit authorities in Texas and Florida represent underserved buyer archetypes seeking risk-transfer partnership structures absent in California's vendor-consolidated corridors. Maritime vessel autonomy for Houston energy corridor offshore inspection offers regulatory whitespace with lower NHTSA exposure. Pursue developer kit distribution through online channels to bypass tier-one integrator gatekeeping. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime acquisition of ethical AI-compliant autonomy specialists facing commercial margin pressure. Five-to-ten year viability hinges on navigation stack unbundling into recurring revenue models displacing perpetual licenses. Monitor FAA beyond-visual-line-of-sight waiver approval velocity as inflection indicator for commercial drone segment commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Unifies LiDAR, visual odometry, and GNSS correction into single-chip solutions reducing bill-of-materials costs. |
| Defense Cybersecurity Certification Investment | Opens Pentagon unmanned ground vehicle procurement programs requiring specialized engineering talent. |
| Subscription Revenue Model Transition | Captures per-mile pricing from Texas and Florida municipal shuttle pilots displacing perpetual licenses. |
| Geographic Expansion to Permissive Jurisdictions | Arizona's streamlined permitting rewards simulation-based validation with reduced documentation burdens. |
| Acquisition of Solid-State LiDAR Specialist | Secures mechanical scanning unit replacement technology for industrial robot installation margins. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combined with primary interviews across autonomous vehicle platform engineers, defense procurement officers, FAA certification specialists, and industrial automation distributors. NHTSA testing protocol disclosures, Pentagon budget justification documents, California DMV permit databases, and semiconductor import records provided validation triangulation. Bottom-up sensor shipment estimates and top-down defense program appropriations were reconciled through iterative cross-checking.
Data-stream reconciliation across technology segmentation by sensor modality, application by regulatory maturity tier, end user by procurement authority, and geographic cluster by testing infrastructure availability generated volume and value outputs. CAGRs were derived from weighted scenario modeling across defense budget trajectory assumptions and commercial deployment permit issuance rates. Edge inference cost curves and solid-state LiDAR price decline trajectories informed technology adoption timing assumptions.
Revisions become necessary when FAA beyond-visual-line-of-sight waiver policy shifts, Pentagon ethical AI framework finalization, or state-level autonomous vehicle liability preemption rulings materialize outside baseline assumptions. Forecasts reflect documented assumptions on regulatory timeline progression and defense procurement cycle continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Armored Unmanned Underwater Vehicle Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
Maritime Drone Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Unattended Ground Sensors (UGS) Market