
 Global Military Robotics Autonomous Systems Market | 2026-2036
Global Military Robotics Autonomous Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Robotics Autonomous Systems Market Foresight
Special operations units is collapsing as the dominant buyer archetype for autonomous combat robots, while logistics support divisions gain procurement share for unmanned ground vehicles. Lockheed Martin Corporation leverages in-house production of sensor fusion architectures to dominate high-altitude surveillance drone programs. Northrop Grumman Corporation sustains technology leadership in autonomous maritime systems through concentrated R&D spending on underwater navigation.
Military robotics autonomous systems encompass self-directing platforms that integrate machine learning algorithms, multi-spectral sensor arrays, and real-time data processing to execute missions without continuous human operator control, primarily serving defense organizations requiring force multiplication in contested environments. Unmanned aerial vehicles anchor current revenue pools due to mature procurement pipelines for reconnaissance and electronic warfare missions, while autonomous combat robots represent the fastest-growing segment as rules of engagement frameworks evolve to permit greater machine decision authority. Lidar systems and computer vision technologies concentrate margin capture because hardware-software integration barriers limit vendor entry.
The United States Department of Defense, Israel's Ministry of Defense, and the United Kingdom's Defence Science and Technology Laboratory shape market access through classified procurement channels and end-use certification requirements for AI-enabled lethal systems. NATO standardization agreements and national export control regimes on autonomous weapons technologies restrict cross-border technology transfer and compel regional production footprints. Stakeholders must monitor shifting definitions of meaningful human control as regulatory bodies debate updated protocols for machine-initiated targeting decisions.
Market Dynamics
The NATO push for interoperable autonomous systems is compressing procurement timelines while fragmenting vendor qualification standards across member states. Defense ministries now demand cross-platform sensor fusion and encrypted mesh networking as baseline specifications, forcing hardware-software integration at deeper architectural layers.
Growth Catalysts
- Export Control Harmonization:Tightened EU dual-use technology frameworks are accelerating indigenous production capacity in member states, reducing dependency on external sensor suppliers.
- Machine Decision Authority:Evolving rules of engagement in Israel and the United Kingdom are permitting expanded autonomous targeting protocols for unmanned ground vehicles in contested zones.
- Force Multiplication Imperative:Special operations commands across NATO are prioritizing swarm-capable aerial platforms to reduce operator-to-vehicle ratios in denied-access environments.
Market Restraints
- Rare Earth Supply Concentration:Permanent magnet dependencies for precision motor systems concentrate in single-source supply chains, exposing production schedules to geopolitical disruption.
- Meaningful Human Control Mandates:The EU AI Act's prohibited practices clause for autonomous lethal systems creates compliance friction for vendors targeting European defense procurement channels.
- Technical Verification Gaps:Absence of standardized testing protocols for edge-case autonomous navigation in GPS-denied environments prolongs field certification cycles.
Strategic Opportunities
- Underwater Autonomy White Space:Australia's investment in autonomous underwater vehicle infrastructure for Indo-Pacific surveillance creates demand for extended-endurance maritime platforms.
- Logistics Automation Pivot:Army sustainment brigades in the United States are expanding unmanned ground vehicle procurement for contested logistics corridors, displacing manned convoy operations.
- Swarm Architecture Convergence:Integration of low-earth orbit satellite constellations with tactical datalinks enables beyond-line-of-sight coordination for distributed autonomous systems.
Industry Challenges
- AI Safety Engineering Talent Scarcity:Defense contractors face acute shortages of specialists capable of certifying neural network behavior in stochastic combat environments.
- Interoperability Certification Burden:NATO STANAG compliance testing for cross-platform communication protocols extends development timelines by 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Robotics Autonomous Systems Market |
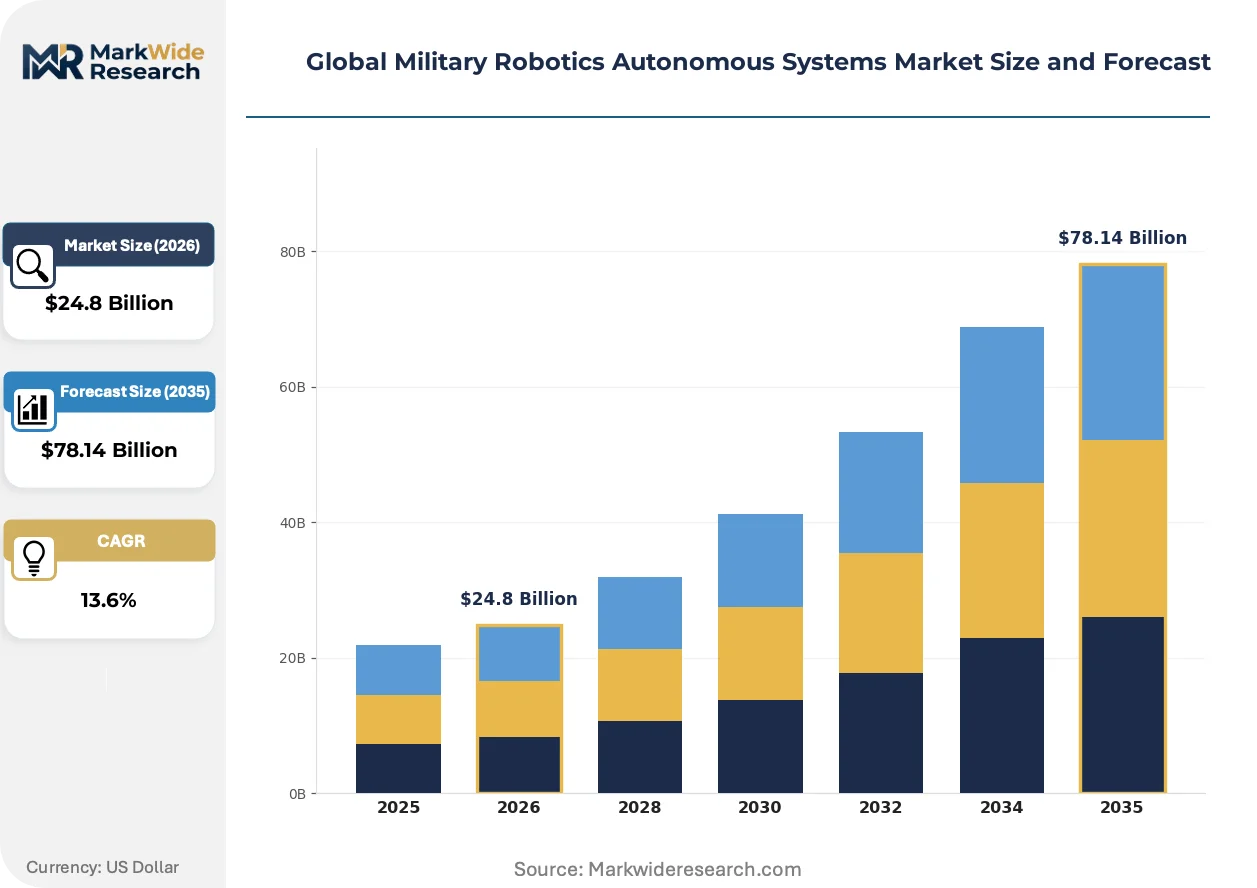
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $78.14 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
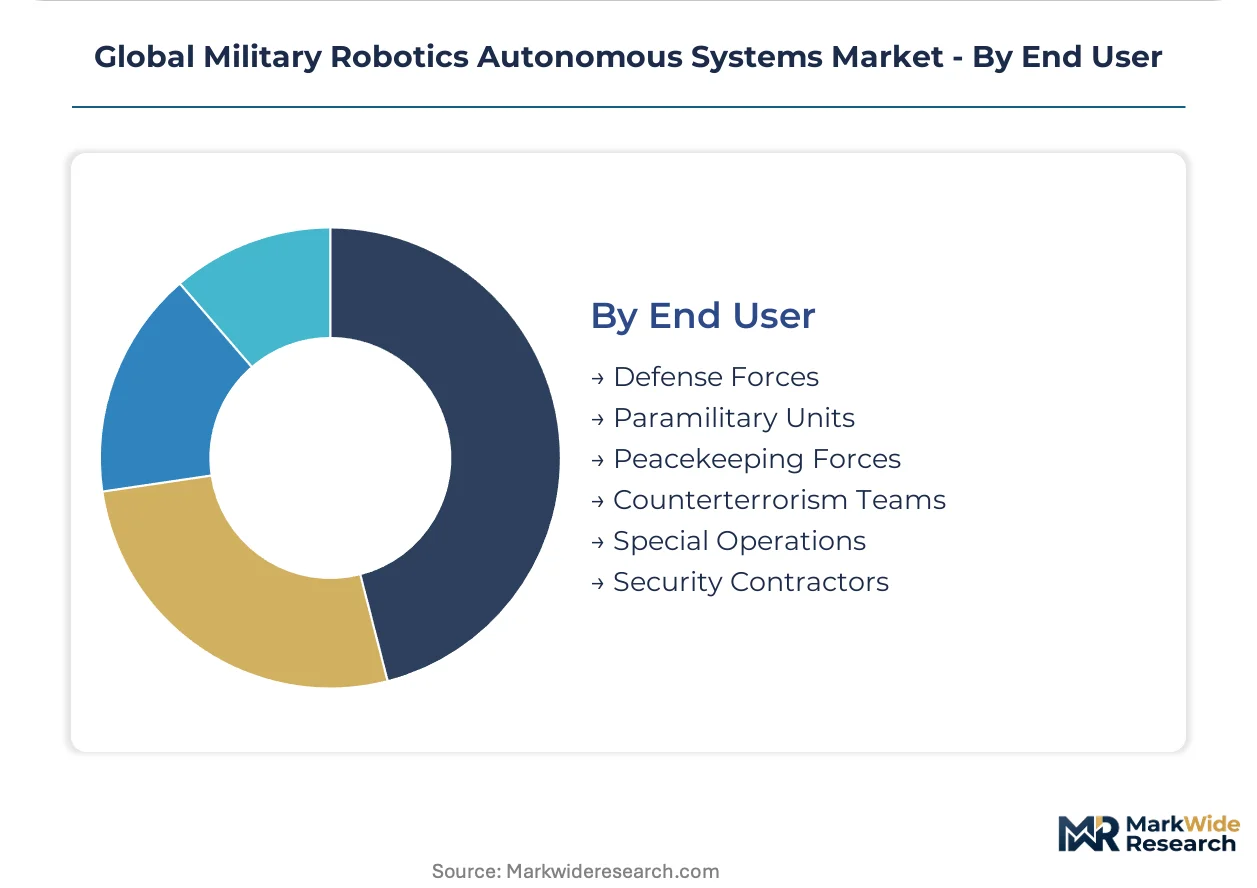
| Segmentation | Product Type: Unmanned Ground Vehicles, Unmanned Aerial Vehicles, Unmanned Underwater Vehicles, Autonomous Combat Robots, Surveillance Drones Technology: Machine Learning, Computer Vision, Sensor Fusion, Lidar Systems, Remote Control, Real-Time Data Processing Application: Reconnaissance, Target Acquisition, Logistics Support, Electronic Warfare, Border Patrol, Search & Rescue End User: Defense Forces, Paramilitary Units, Peacekeeping Forces, Counterterrorism Teams, Special Operations, Security Contractors |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems, Elbit Systems Ltd., AeroVironment, Inc., Thales Group, Israel Aerospace Industries, General Dynamics Corporation, Teledyne FLIR LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Robotics Autonomous Systems Market Shifts & Advancements
Autonomous platform development is accelerating along three vectors: modular hardware architectures enabling rapid mission reconfiguration, regulatory pressure on algorithmic transparency, and procurement consolidation around integrated system-of-systems contracts rather than discrete vehicle purchases.
Edge computing hardware is fragmenting traditional centralized processing architectures in unmanned aerial systems. Miniaturized tensor processing units now enable real-time target recognition aboard Group 1-2 drones without ground station dependency. Marine expeditionary units and forward-deployed special operations elements are fielding these platforms for contested communications environments, compressing sensor-to-shooter timelines from minutes to seconds.
The EU AI Act's risk-based classification framework is reshaping vendor access to European defense markets. High-risk autonomous systems must demonstrate conformity with fundamental rights impact assessments before procurement authorization. German and French defense ministries are requiring algorithmic audit trails for lethal autonomous platforms, compelling suppliers to reengineer decision-logging architectures.
Integrated system-of-systems contracting is displacing discrete platform purchases across major defense acquisition programs. The United States Army's Robotic Combat Vehicle program now bundles unmanned ground vehicles with tethered drones, counter-UAS modules, and predictive maintenance software under single-vendor responsibility. This consolidation favors primes with captive software development capacity and compresses margins for component specialists.
Global Military Robotics Autonomous Systems Market Segmentation
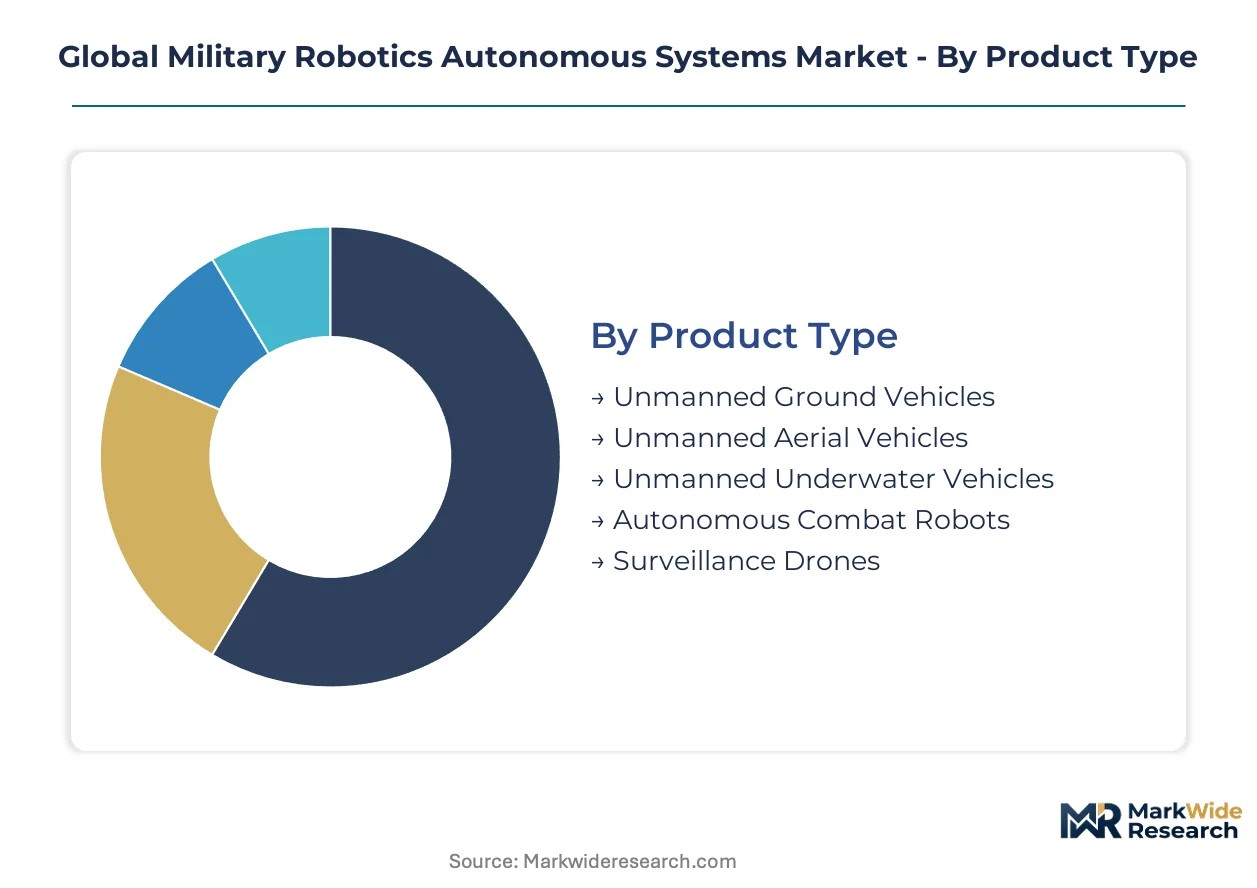
Military robotics autonomous systems fragment across four critical dimensions that determine procurement pathways and regulatory exposure. Product type and technology choices carry direct implications for meaningful human control compliance under divergent national frameworks.
Product Type:
EU AI Act prohibitions on autonomous lethal systems reshape procurement eligibility across unmanned platform categories, with member states diverging on interpretive enforcement.
- Unmanned Ground Vehicles:Tracked and wheeled platforms integrate terrain-mapping algorithms for contested logistics corridors. United States Army sustainment brigades prioritize these systems for manned convoy displacement in denied-access environments.
- Unmanned Aerial Vehicles:Fixed-wing and multi-rotor systems dominate current procurement pipelines through mature reconnaissance mission profiles. Israel's Ministry of Defense accelerates Group 1-2 acquisitions for special operations force multiplication.
- Unmanned Underwater Vehicles:Extended-endurance platforms address Indo-Pacific surveillance gaps with autonomous navigation below acoustic detection thresholds.
- Autonomous Combat Robots:Ground-based lethal platforms face contracting friction under EU AI Act prohibited practices clauses, compressing vendor access to European defense ministries.
- Surveillance Drones:High-altitude platforms with multi-spectral sensor arrays anchor NATO interoperability standardization efforts for cross-border intelligence sharing.
Established volume favors Unmanned Aerial Vehicles; emerging adoption favors Autonomous Combat Robots.
Technology:
Hardware-software integration barriers concentrate margin capture in sensor and processing architectures, with lidar and computer vision commanding premium positioning.
- Machine Learning:Neural network architectures enable adaptive threat recognition without pre-programmed target libraries. United Kingdom Defence Science and Technology Laboratory mandates algorithmic audit trails for procurement authorization.
- Computer Vision:Real-time object classification systems process electro-optical and infrared feeds for autonomous targeting decisions. Israeli rules of engagement evolution permits expanded machine authority in contested zones.
- Sensor Fusion:Multi-spectral data integration architectures combine radar, lidar, and acoustic inputs for navigation redundancy in GPS-denied environments.
- Lidar Systems:Solid-state and mechanical scanning variants enable precision mapping for obstacle avoidance and target geometry reconstruction.
- Remote Control:Tethered operator override protocols satisfy meaningful human control mandates under NATO standardization agreements.
- Real-Time Data Processing:Edge computing hardware miniaturization compresses sensor-to-shooter timelines aboard tactical platforms.
Defense procurement prioritizes Sensor Fusion for mission assurance; commercial technology transfer accelerates Real-Time Data Processing cost curves.
Application:
Mission profile determines platform specification intensity, with electronic warfare and target acquisition demanding hardened architectures against countermeasures.
- Reconnaissance:Persistent surveillance missions drive endurance specifications and low-observable signature requirements for penetration of contested airspace.
- Target Acquisition:Precision targeting systems integrate laser designators and coordinate generation for manned-unmanned teaming architectures.
- Logistics Support:Unmanned ground vehicle convoys reduce personnel exposure in improvised explosive device threat corridors.
- Electronic Warfare:Spectrum dominance platforms require rapid frequency hopping and cognitive jamming capabilities against adaptive adversaries.
- Border Patrol:Persistent perimeter monitoring applications favor cost-optimized platforms with simplified maintenance protocols.
- Search & Rescue:Disaster response configurations prioritize payload flexibility for medical supply delivery and casualty evacuation.
Operational tempo concentrates investment in Reconnaissance; autonomous capability maturation expands Electronic Warfare addressable scope.
End User:
Classification status determines technology access tier, with special operations commands bypassing standard acquisition timelines for field-responsive procurement.
- Defense Forces:National military services drive volume procurement through program-of-record funding with multi-year appropriations.
- Paramilitary Units:Gendarmerie and coast guard organizations seek dual-use platforms with civilian-military interoperability.
- Peacekeeping Forces:United Nations and regional stabilization missions require de-escalation protocols and strict rules of engagement compliance.
- Counterterrorism Teams:Specialized law enforcement units demand rapid deployment platforms for urban close-quarters operations.
- Special Operations:Special mission units procure swarm-capable systems through classified acquisition channels with compressed delivery schedules.
- Security Contractors:Private military companies face export control restrictions on AI-enabled lethal system transfers.
Budget scale favors Defense Forces; procurement velocity favors Special Operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel exports autonomous targeting systems to NATO member states through classified procurement channels, while the United Kingdom supplies maritime navigation architectures to Indo-Pacific defense ministries. This bilateral trade corridor concentrates high-value technology transfer between allied defense ecosystems.
United States
The Department of Defense accelerates swarm-capable aerial platform acquisitions through special operations command budgets. FAA regulations on beyond-visual-line-of-sight operations create compliance pathways for military exemption certifications. The Boston-Washington corridor hosts concentrated defense contractor R&D facilities developing sensor fusion architectures.
Israel
The Ministry of Defense expands autonomous targeting protocols for unmanned ground vehicles in contested zones under evolving rules of engagement. National export control frameworks on AI-enabled weapons restrict technology transfer to non-allied states. Haifa and Tel Aviv metropolitan areas anchor unmanned aerial vehicle manufacturing clusters with integrated software development.
United Kingdom
The Defence Science and Technology Laboratory mandates algorithmic audit trails for lethal autonomous platform procurement authorization. EU AI Act prohibited practices clauses create compliance friction for vendors targeting European defense channels. Bristol and Portsmouth harbor autonomous maritime system development concentrated in underwater navigation.
Australia
Investment in autonomous underwater vehicle infrastructure for Indo-Pacific surveillance generates demand for extended-endurance maritime platforms. The country's defense procurement framework prioritizes interoperability with United States and United Kingdom systems. Perth and Sydney anchor submarine drone development clusters serving regional surveillance requirements.
Germany
The Bundeswehr procurement office demands conformity with fundamental rights impact assessments for high-risk autonomous systems under EU AI Act classifications. KBA technical standards influence ground vehicle autonomous navigation certification requirements. Bavaria and Baden-Württemberg concentrate defense electronics manufacturing with embedded AI safety engineering capacity.
Global Military Robotics Autonomous Systems Market Competitive Landscape
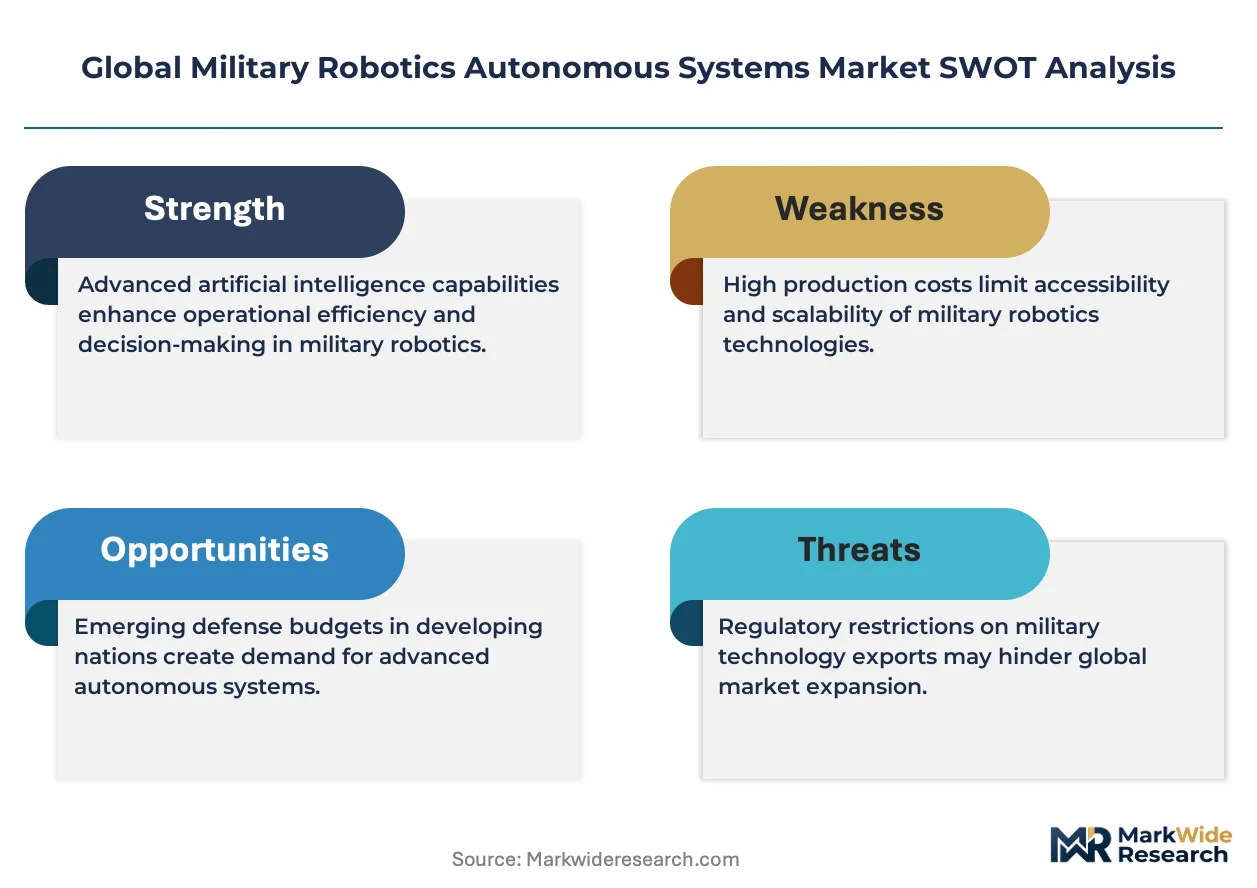
Listed leaders compete with private specialists across classified procurement channels, creating a tiered structure where prime contractors capture integrated system-of-systems contracts while component vendors face margin compression. Market concentration favors entities with captive software development capacity and established NATO STANAG certification histories. Two strategic archetypes dominate: vertically integrated primes controlling sensor-to-shooter architectures, and specialized autonomy software houses licensing navigation algorithms. Competitive moves center on strategic partnerships for mesh networking integration and portfolio diversification into predictive maintenance software bundles.
Within the prime contractor tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify vertically integrated market positions, while BAE Systems represents the European-based defense conglomerate archetype navigating EU AI Act compliance requirements.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Elbit Systems Ltd. |
| AeroVironment, Inc. |
| Thales Group |
| Israel Aerospace Industries |
| General Dynamics Corporation |
| Teledyne FLIR LLC |
| Others |
Supply & Pricing Matrix
Capacity utilization at solid-state lidar foundries in the United States and Israel shapes both component scarcity and price floors for military-grade sensor architectures, compressing margins for second-tier integrators while elevating procurement premiums for NATO-certified platforms.
Pricing Analysis
Technology-generation pricing gaps separate third-generation edge-computing platforms from legacy centralized processing architectures and emerging neuromorphic chip designs. Three-tier pricing structure across premium, standard, and economy levels reflects NATO STANAG certification grade and algorithmic audit trail completeness. Cost compression in standard-tier unmanned ground vehicles is intensifying because Israeli and United Kingdom defense ministries are consolidating procurement around integrated system-of-systems contracts. Logistics support divisions demonstrate highest price sensitivity due to volume scaling imperatives, while special operations commands accept premium positioning for compressed delivery schedules.
Supply Chain Analysis
Strategic stockpiling of rare earth permanent magnets and precision-grade optical components dominates inventory strategy over just-in-time approaches, reflecting single-source concentration risks in China's processing infrastructure. Manufacturing concentration centers on the United States, Israel, and the United Kingdom for finished autonomous platforms, with Taiwan and South Korea anchoring semiconductor fabrication for edge-computing tensor processing units. Permanent magnet dependencies for precision motor systems, indium phosphide substrates for electro-optical sensors, and high-purity helium for cryogenic cooling constitute critical input vulnerabilities. Tariff exposure on Chinese rare earth processed materials threatens production continuity. Distribution runs through classified procurement channels and defense ministry direct contracting rather than commercial intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from commercial autonomy software houses licensing navigation algorithms to defense primes, eroding captive technology advantages.
For Market Incumbents: Secure algorithmic audit trail architectures to satisfy United Kingdom Defence Science and Technology Laboratory procurement mandates before EU AI Act enforcement hardens. Deepen backward integration into solid-state lidar production to reduce dependency on external sensor suppliers facing capacity constraints. For New Entrants and Emerging Players: NATO STANAG certification fast-tracks for mesh networking protocols offer entry velocity into European defense procurement channels constrained by interoperability mandates. Underwater autonomy for Indo-Pacific surveillance presents the most penetrable white space, with Australia's investment infrastructure creating demand pull. Target army sustainment brigades in the United States through predictive maintenance software bundles rather than discrete vehicle competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized autonomy software houses with demonstrated neural network certification capabilities over hardware-commoditized platform integrators. Long-term viability hinges on regulatory compliance engineering capacity as meaningful human control mandates proliferate across NATO procurement frameworks. Acquisition targets should demonstrate algorithmic transparency architectures and established defense ministry relationships. Watch for EU AI Act prohibited practices clause enforcement thresholds as inflection indicator for European market access compression.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Audit Trail Development | United Kingdom Defence Science and Technology Laboratory mandates this architecture for lethal autonomous platform procurement authorization. |
| Backward Integration into Sensor Fusion | Lockheed Martin Corporation's in-house production of sensor fusion architectures dominates high-altitude surveillance drone programs. |
| Mesh Networking Certification Investment | NATO STANAG compliance testing extends development timelines by 18-24 months, creating barrier-protected revenue pools. |
| Underwater Navigation R&D Concentration | Australia's Indo-Pacific surveillance investment generates demand for extended-endurance autonomous underwater vehicles. |
| Predictive Maintenance Software Bundling | United States Army Robotic Combat Vehicle program consolidates unmanned ground vehicles with predictive maintenance under single-vendor responsibility. |
Research Methodology
A standing panel of special operations procurement officers, defense ministry program managers, sensor fusion architects, and export control compliance specialists provided ongoing calibration across primary interview phases, with secondary validation drawing from NATO standardization agreement documentation, EU AI Act regulatory filings, United States Department of Defense budget justification materials, and national export control regime updates. Bottom-up platform deployment estimates triangulated against top-down defense R&D appropriation analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical framework modeling platform type, technology architecture, mission application, and end-user classification dimensions. CAGRs derived from deployment trajectory analysis and procurement pipeline visibility. Neural network certification requirements and rare earth supply concentration served as industry-specific forecast sensitivity inputs.
Decision-makers should treat outputs as directional under assumptions of sustained NATO interoperability standardization and stable rare earth supply chain configuration; material deviation would warrant model refresh. Revision becomes warranted when EU AI Act enforcement interpretations or United States export control harmonization efforts cross thresholds that reshape vendor market access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Military Autonomous Robot Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Unattended Ground Sensors (UGS) Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Global Submarine Payload Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Armored Unmanned Underwater Vehicle Market
Unmanned Systems
Military Robots Market