
 Drone Detection Optical Systems Market | 2026-2036
Drone Detection Optical Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Detection Optical Systems Market Intelligence
Multi-sensor fusion architectures is reconfiguring how drone detection systems achieve target confirmation and reduce false-alarm rates in cluttered electromagnetic environments. Thales Group leverages its SPECTRA electronic warfare heritage to integrate infrared and radio-frequency cueing into unified threat displays. Elbit Systems anchors its competitive stance through persistent investment in uncooled thermal core miniaturization for man-portable deployments. Lockheed Martin dominates long-range aerospace applications with coherent LiDAR beam-steering derived from directed-energy programs.
Drone detection optical systems employ electro-optical and infrared sensors operating across visible, near-infrared, and thermal spectral bands to acquire, track, and classify unmanned aerial vehicles at standoff distances exceeding two kilometers. These systems serve critical infrastructure protection, military perimeter defense, and civilian airspace management by delivering passive, low-probability-of-intercept surveillance. Ground-based installations currently occupy the largest installed base due to fixed-site power and computational budgets, though portable systems represent the fastest-expanding category as battery energy density and edge-processing efficiency improve. Infrared technology leads revenue contribution among detection modalities because all-weather, day-night operational continuity commands premium procurement terms from defense and law enforcement end users.
The FAA's Part 89 remote identification mandate and the EU's U-space regulatory framework together shape product certification requirements and open procurement pathways for certified detection equipment. EASA's forthcoming counter-UAS technical standards will further constrain market access to systems demonstrating electromagnetic compatibility and frequency coordination compliance. Stakeholders must monitor how rapidly national security exemptions from civilian aviation rules fragment procurement specifications across jurisdictions.
Market Dynamics
Layered airspace defense architectures are compressing procurement cycles as NATO defense agencies mandate sensor fusion across electro-optical, radar, and electronic warfare domains. This structural shift forces vendors to engineer interoperable command interfaces rather than standalone detection boxes.
Growth Catalysts
- EU F-Gas Regulation:The European Union's tightening fluorinated gas restrictions are accelerating transitions toward solid-state infrared alternatives, creating replacement demand across installed thermal imaging bases.
- Critical infrastructure protection:Power generation facilities and transportation hubs are deploying perimeter optical systems as drone incursions against substations and airports multiply.
- Battery energy density gains:Advances in lithium-sulfur cell chemistry are extending mission endurance for portable detection units, opening man-portable deployments previously constrained by power budgets.
Market Restraints
- Indium antimonide supply concentration:Cryogenic infrared detector fabrication depends on refined indium supplies concentrated in Chinese smelting operations, exposing Western sensor manufacturers to export restriction risk.
- EASA electromagnetic compatibility standards:Pending counter-UAS technical specifications will require expensive recertification of existing fielded systems, freezing near-term procurement decisions.
- Synthetic aperture radar substitution:All-weather imaging radar systems are capturing budget share in maritime and alpine environments where optical systems suffer atmospheric attenuation.
Strategic Opportunities
- U-space regulatory framework:The European Union's unmanned traffic management mandate creates certified procurement pathways for detection equipment integrated into civilian airspace management infrastructure.
- LiDAR-RF convergence:Coherent beam-steering LiDAR fused with software-defined radio cueing enables positive identification at ranges exceeding thermal-only systems, opening long-range aerospace applications.
- India:The country's central electronics regulator is drafting counter-drone technical standards that will require localized detection system deployment around airports and nuclear facilities.
Industry Challenges
- Multispectral algorithm training:Machine learning model development requires classified drone signature libraries that defense agencies release only to cleared contractors, fragmenting competitive capability.
- Legacy C4ISR integration:New optical detection nodes must interface with decades-old command-and-control networks using proprietary protocols, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Detection Optical Systems Market |
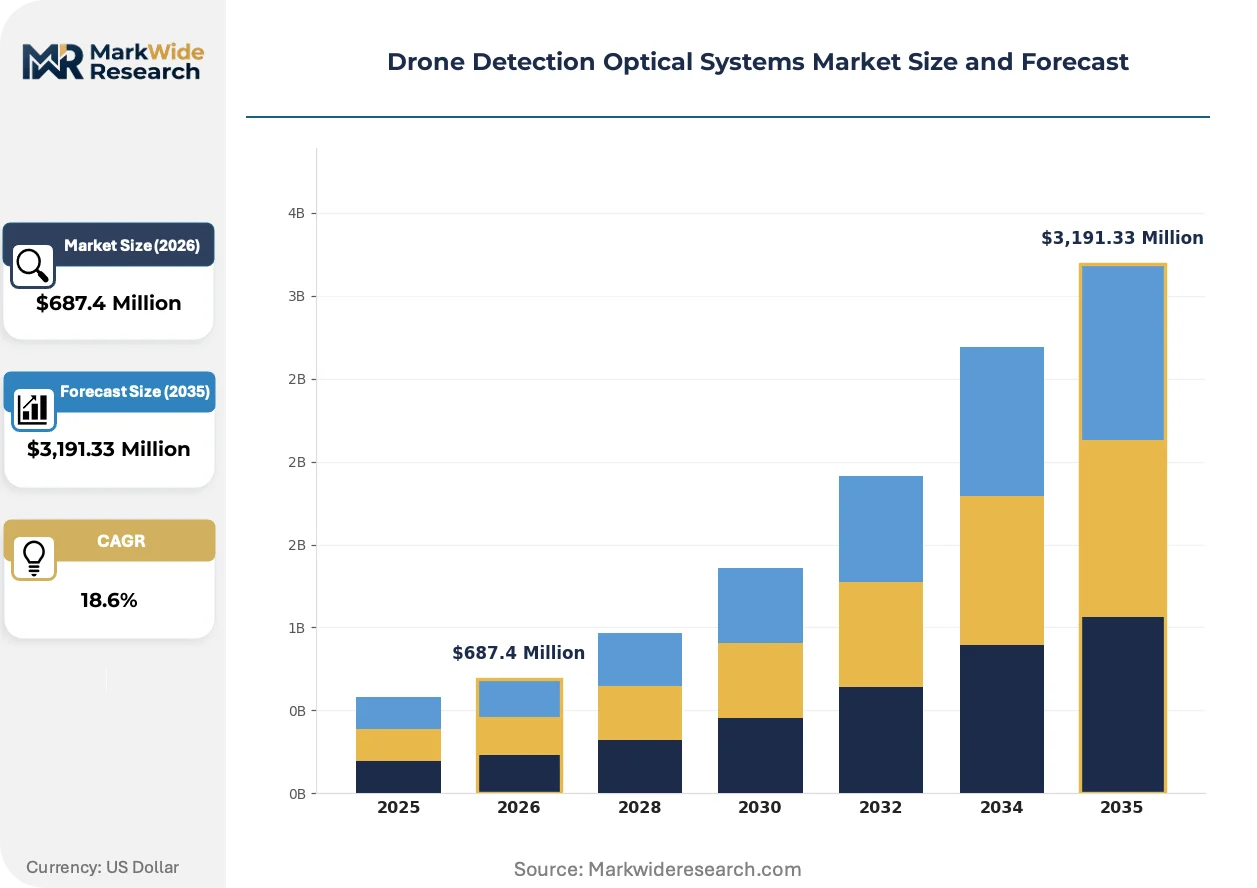
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $3,191.33 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground-Based Systems, Airborne Systems, Hybrid Systems, Portable Systems Technology: LiDAR, Infrared, Visible Light, Radio Frequency End User: Defense, Law Enforcement, Commercial, Research Institutions Application: Surveillance, Security, Environmental Monitoring, Traffic Management |
| Companies Covered | Thales Group, Elbit Systems, Lockheed Martin Corporation, Airbus SE, Leonardo S.p.A., Raytheon Technologies, Teledyne FLIR, Hensoldt, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Detection Optical Systems Market Strategic Shifts & Innovations
Edge-processing architectures are redistributing computational load from centralized servers to sensor-embedded GPUs, enabling real-time target classification without bandwidth-dependent cloud connectivity. This shift is compressing response latencies and expanding deployability to network-denied environments.
Solid-state infrared focal plane arrays are digitizing thermal detection by replacing mechanically scanned cryogenic coolers with uncooled microbolometer designs. Border security agencies in Germany and France are fielding these sensors at scale for persistent perimeter monitoring. The technology is digitizing supply chains by eliminating hermetic packaging expertise previously concentrated in aerospace-qualified facilities.
The FAA's Part 89 remote identification mandate is restructuring procurement specifications by requiring detection systems to correlate optical tracks with broadcast drone identity signals. System integrators must now engineer dual-mode receivers alongside infrared imagers. Military end users are responding by funding classified programs that spoof or intercept these identification broadcasts.
Defense procurement officers are unbundling detection hardware from multi-year sustainment contracts, forcing vendors to compete separately on sensor performance and lifecycle service pricing. This pattern is displacing single-source integrated system awards. The shift is most visible in Germany, where the federal procurement office now mandates competitive rebidding for maintenance services every thirty-six months.
Drone Detection Optical Systems Market Segmentation
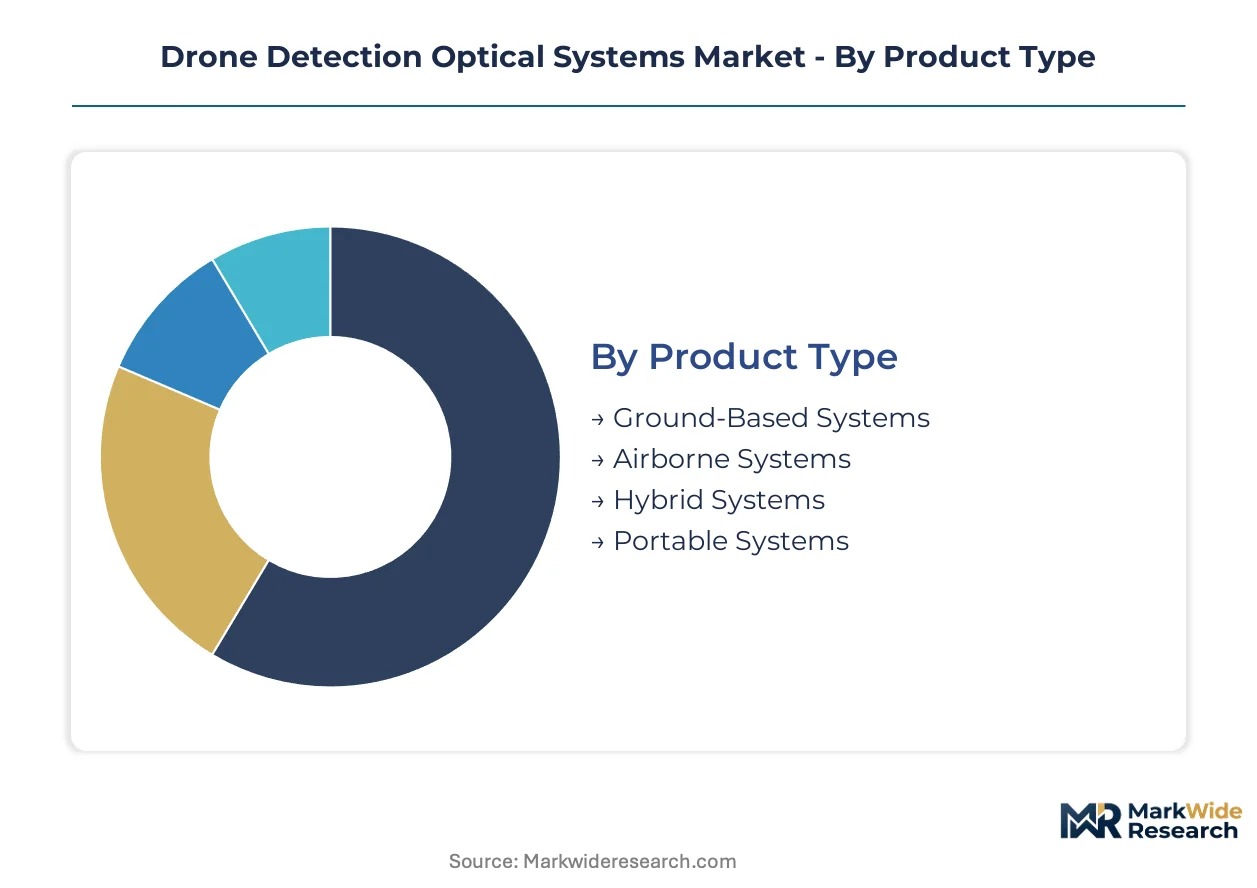
Drone detection optical systems fragment across four intersecting dimensions that determine procurement specifications and deployment economics. Product architecture dictates power budgets and mobility constraints. Technology modality governs detection range and environmental resilience. End-user requirements diverge sharply between classified military specifications and civilian regulatory compliance. Application context shapes sensor fusion requirements and integration depth with existing security infrastructure.
Product Type:
Cost tier separates stationary installations from deployable units, with capital intensity and operational flexibility trading off across the spectrum.
- Ground-Based Systems:Fixed-site installations leverage continuous power supply and rack-mounted processing for persistent perimeter monitoring. NATO member states concentrate procurement at critical infrastructure nodes including nuclear facilities and command headquarters, where detection range and classification accuracy override mobility requirements.
- Portable Systems:Battery-powered units with edge-processed target recognition are climbing the fastest as lithium-sulfur energy density improvements extend mission endurance. Rapid deployment scenarios including temporary event security and forward operating base protection drive demand concentration in Germany and France.
- Airborne Systems:Helicopter- and UAV-mounted optical payloads extend detection horizons beyond terrain-masked ground perspectives. Military end users in the United States employ these for convoy protection and area denial operations.
- Hybrid Systems:Modular architectures permitting rapid reconfiguration between fixed and mobile modes. Border security agencies value the operational flexibility for seasonal threat pattern adaptation.
Ground-Based Systems hold installed capacity. Portable Systems is rotating up the share rankings.
Technology:
Application environment dictates spectral band selection, with atmospheric conditions and target thermal signatures determining modality effectiveness.
- Infrared:Uncooled microbolometer arrays and cryogenically cooled indium antimonide detectors deliver day-night operational continuity across fog and light precipitation. Defense agencies command premium procurement terms for all-weather reliability, particularly in maritime and alpine environments where visible systems fail.
- LiDAR:Coherent beam-steering architectures derived from directed-energy programs enable precise range measurement and target dimensioning at extended standoff. Aerospace applications in the United States leverage this for positive identification beyond thermal-only detection limits.
- Visible Light:High-resolution CMOS sensors with adaptive optics provide cost-effective classification for daytime operations in clear atmospheric conditions. Commercial security deployments favor this modality for budget-constrained perimeter protection.
- Radio Frequency:Software-defined radio cueing complements optical detection by correlating visual tracks with broadcast remote identification signals. FAA Part 89 compliance mandates are accelerating dual-mode receiver integration.
Infrared dominates revenue contribution. LiDAR is expanding most quickly in long-range aerospace segments.
End User:
Customer type determines certification requirements, with classified programs operating under procurement rules distinct from civilian regulatory frameworks.
- Defense:Classified drone signature libraries and multi-sensor fusion architectures for electronic warfare integration. Layered airspace defense mandates across NATO compress procurement cycles and demand interoperable command interfaces.
- Law Enforcement:Civil liberties constraints and evidentiary standards shape system specifications. European agencies prioritize electromagnetic compatibility certification under forthcoming EASA counter-UAS technical standards.
- Commercial:Critical infrastructure operators including power utilities and airport authorities deploy perimeter optical systems as drone incursions against substations multiply. Procurement emphasizes total cost of ownership over peak performance.
- Research Institutions:Algorithm development and multispectral signature collection for machine learning training. Access to classified libraries fragments competitive capability among cleared contractors.
Defense holds installed capacity. Commercial is rotating up the share rankings.
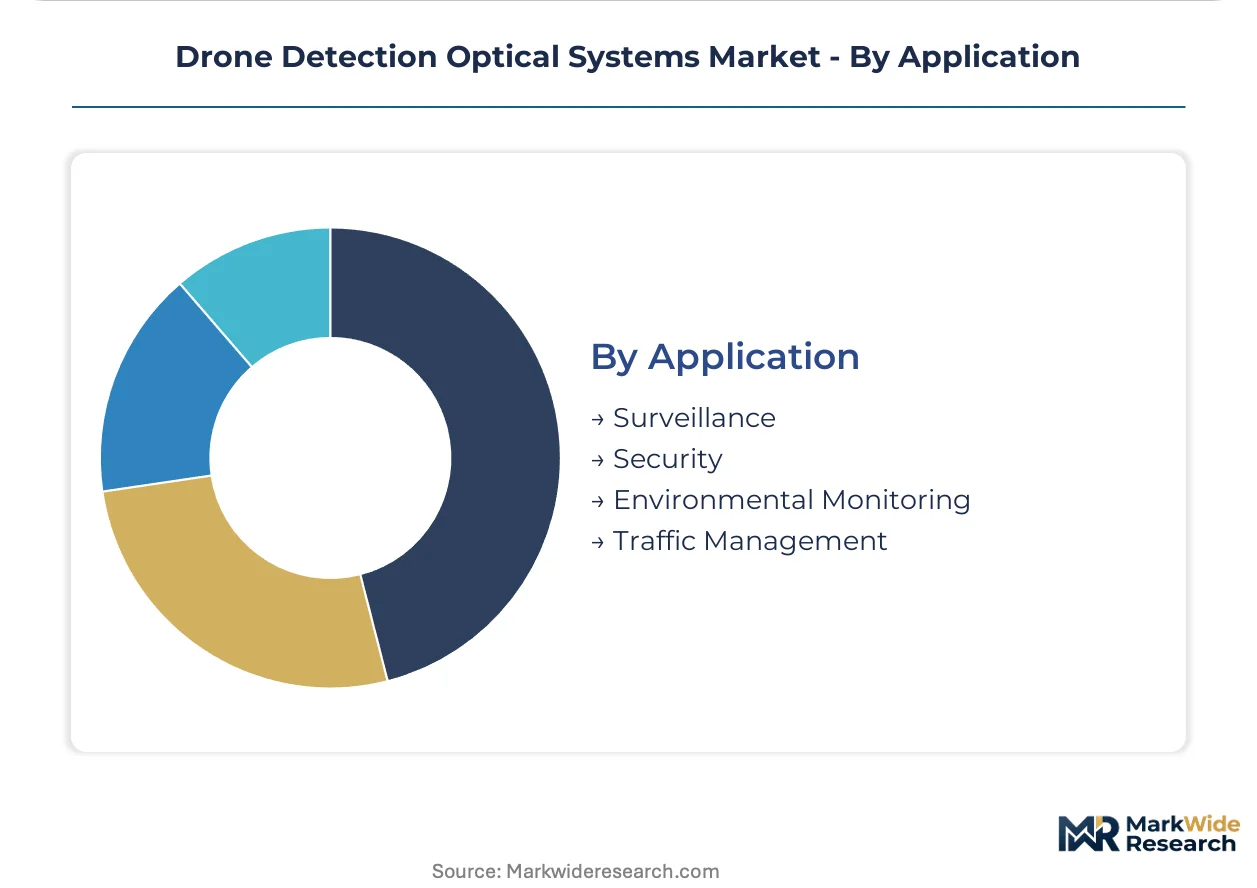
Application:
Volume concentration varies by threat model, with environmental and traffic management applications emerging from regulatory mandates rather than security incidents.
- Security:Perimeter defense for critical infrastructure and government facilities represents the dominant deployment volume. German federal procurement mandates competitive rebidding for maintenance services every thirty-six months, unbundling hardware from sustainment contracts.
- Surveillance:Persistent wide-area monitoring for border protection and coastal defense. French and German border security agencies field solid-state infrared focal plane arrays at scale.
- Environmental Monitoring:Wildlife tracking and pollution detection applications leveraging drone detection infrastructure for dual-use scenarios. Research institutions drive modest procurement volumes.
- Traffic Management:U-space regulatory framework integration for unmanned traffic management in civilian airspace. EU mandate creates certified procurement pathways for detection equipment integrated into airspace management infrastructure.
Security holds installed capacity. Traffic Management is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German electro-optical engineering clusters export detection subsystems to NATO defense agencies across Western Europe, while US aerospace primes supply long-range LiDAR architectures to allied military operators in the Pacific and Middle East.
United States
Defense procurement compresses sensor fusion timelines as layered airspace mandates require interoperable electro-optical, radar, and electronic warfare interfaces. FAA Part 89 remote identification rules reshape certification requirements for dual-mode optical-RF receivers. Lockheed Martin's directed-energy heritage anchors coherent LiDAR development in California and Texas aerospace corridors.
Germany
Hensoldt and Rheinmetall anchor dense electro-optical engineering competence serving NATO perimeter defense requirements. EU F-Gas Regulation accelerates transitions from cryogenic cooled detectors toward solid-state infrared alternatives. Bavaria and Baden-Württemberg host concentrated thermal imaging R&D facilities supplying border security agencies across the continent.
France
Thales Group leverages SPECTRA electronic warfare heritage to integrate infrared and radio-frequency cueing into unified threat displays. EASA counter-UAS technical standards pending approval will mandate electromagnetic compatibility recertification. Paris and Toulouse aerospace clusters develop man-portable uncooled thermal cores for rapid deployment scenarios.
United Kingdom
Critical infrastructure operators deploy perimeter optical systems as drone incursions against power substations multiply. Ministry of Defence procurement unbundles detection hardware from multi-year sustainment contracts. Greater London and Southeast England concentrate system integration facilities serving both domestic security and export markets.
India
Central electronics regulators draft counter-drone technical standards requiring localized detection deployment around airports and nuclear facilities. DGFT import substitution policies incentivize domestic electro-optical manufacturing partnerships. Maharashtra and Karnataka states attract joint ventures for uncooled microbolometer assembly serving South Asian security markets.
Drone Detection Optical Systems Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered procurement segments. Defense agencies unbundle hardware from sustainment contracts, forcing vendors to compete separately on sensor performance and lifecycle pricing. Three archetypes dominate: diversified aerospace primes with directed-energy heritage, electro-optical specialists with uncooled thermal core competence, and system integrators with electronic warfare fusion capabilities. Competitive moves concentrate on strategic partnerships for multi-sensor fusion and geographic licensing to satisfy local content requirements.
Within the diversified prime tier, Lockheed Martin Corporation and Raytheon Technologies occupy positions derived from long-range aerospace and directed-energy programs. Thales Group exemplifies the electronic warfare fusion archetype through its SPECTRA heritage integration. Hensoldt represents the electro-optical specialist model anchored in German defense engineering clusters. These three entities collectively illustrate how heritage capabilities in adjacent defense domains translate into drone detection market positioning.
| Leading Market Players |
|---|
| Thales Group |
| Elbit Systems |
| Lockheed Martin Corporation |
| Airbus SE |
| Leonardo S.p.A. |
| Raytheon Technologies |
| Teledyne FLIR |
| Hensoldt |
| Northrop Grumman |
| Others |
Cost & Logistics Intelligence
Undercapacity in cryogenic infrared detector fabrication is compressing supplier margins and amplifying pricing power for indium antimonide refiners, while defense procurement officers exploit this squeeze to unbundle hardware from sustainment contracts.
Pricing Analysis
The technology-generation pricing gap separates legacy cryogenically cooled systems from solid-state uncooled alternatives and emerging coherent LiDAR architectures. Pricing stratifies across military-specification, dual-use certified, and commercial-grade tiers, with certification under EASA counter-UAS standards commanding substantial premiums. Cost compression in commercial-grade visible-light systems is intensifying because CMOS sensor commoditization erodes differentiation. Law enforcement agencies exhibit highest price sensitivity due to civil liberties constraints on procurement budgets, while defense agencies prioritize all-weather reliability over unit cost.
Supply Chain Analysis
Extended payment terms from German defense procurement offices are cascading liquidity pressure onto electro-optical component suppliers. Manufacturing concentrates in Germany, the United States, and Israel, with indium refining anchored in Chinese smelting operations. Supply chains draw from refined indium, germanium substrates, and uncooled microbolometer wafers. Single-source vulnerability in cryogenic cooler hermetic packaging exposes Western sensor manufacturers to export restriction risk. Distribution runs through system integrators with NATO security clearance rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement unbundling across NATO defense agencies fragments vendor relationships and creates white-space openings for specialized electro-optical suppliers with rapid certification capabilities.
For Market Incumbents: Pre-empt synthetic aperture radar substitution in maritime and alpine environments by accelerating LiDAR-RF convergence roadmaps. Anchor defensive positioning through backward integration into uncooled microbolometer wafer supply, capturing margin that currently leaks to semiconductor foundries. Lockheed Martin's directed-energy heritage exemplifies how adjacent capability migration fortifies detection market share against pure-play thermal specialists. For New Entrants and Emerging Players: India's DGFT import substitution policies represent the most penetrable regulatory entry point for localized electro-optical assembly partnerships. Target airport perimeter security and nuclear facility protection as first-mover applications where technical standards are still drafting. Pursue joint venture structures with Maharashtra and Karnataka state industrial clusters to satisfy domestic content requirements while accessing South Asian demand. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across solid-state infrared focal plane array production as uncooled designs eliminate hermetic packaging infrastructure. Over the medium-term horizon, acquisition targets should emphasize electro-optical specialists with cleared contractor status and classified drone signature library access rather than hardware-agnostic system integrators. Monitor EASA electromagnetic compatibility standard finalization as the inflection signal for recertification-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Partnership | Thales Group's SPECTRA integration demonstrates how electronic warfare heritage accelerates unified threat display development. |
| Uncooled Thermal Core Miniaturization | Elbit Systems' persistent R&D investment anchors man-portable deployment competitiveness in rapid-response scenarios. |
| LiDAR Beam-Steering Licensing | Coherent architectures derived from directed-energy programs enable positive identification beyond thermal-only detection limits. |
| Localized Manufacturing Joint Venture | Maharashtra and Karnataka state partnerships satisfy India's DGFT import substitution policies for airport perimeter systems. |
| Competitive Sustainment Rebidding | German federal procurement mandates every thirty-six months force lifecycle service pricing transparency. |
Research Approach
Operator-level perspectives from defense procurement officers, electro-optical engineering directors, border security agency technical leads, and critical infrastructure protection managers anchored the qualitative base. Primary interview intelligence combined with secondary validation drawn from FAA Part 89 regulatory filings, EASA counter-UAS technical standard drafts, NATO procurement disclosure databases, and EU F-Gas Regulation implementation reports. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Scenario-bracketing around regulatory implementation timelines and indium supply disruption probability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, detection modality, end-user certification tier, and application context. CAGRs derived from installed base replacement cycles and portable system penetration curves. Industry-specific forecast inputs incorporated lithium-sulfur battery energy density improvement trajectories and solid-state infrared focal plane array yield curves.
Practitioners should monitor EASA electromagnetic compatibility standard finalization and indium export restriction announcements for early signals. Forecasts reflect assumptions regarding NATO layered airspace defense mandate continuity and EU F-Gas Regulation enforcement intensity. Macroeconomic defense budget contraction, regulatory exemption fragmentation, or breakthrough synthetic aperture radar cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Unattended Ground Sensors (UGS) Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
Europe Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Maritime Drone Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market