
 Autonomous Aircraft Software Market | 2026-2036
Autonomous Aircraft Software Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Aircraft Software Market Outlook
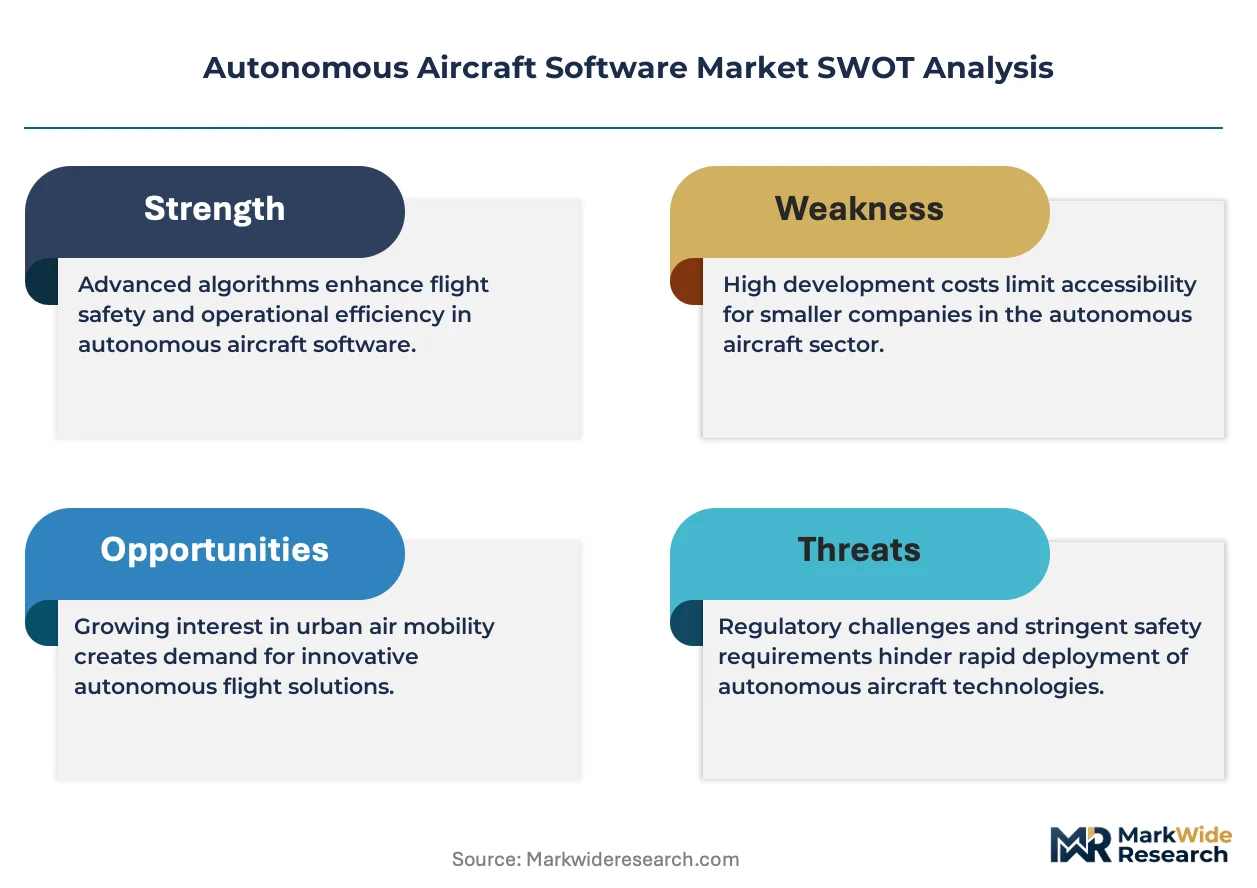
Project finance tied to eVTOL fleet leasing is tilting competitive access toward asset-light developers and away from pure software licensors. Shield AI leverages its defense contracts to sustain multi-domain autonomy development across fixed-wing and rotorcraft platforms. Joby Aviation anchors its vertical integration strategy through captive flight control software production. Wisk Aero competes via Boeing's balance sheet, which extends its runway for certifying autonomous navigation stacks under Part 23 standards.
Autonomous aircraft software encompasses the algorithmic and middleware layers that enable fixed-wing, rotorcraft, and eVTOL platforms to execute flight plans without human intervention, incorporating sensor fusion pipelines operating at sub-100-millisecond latency for obstacle detection and path replanning. Its primary purpose is to satisfy safety-critical aviation requirements while reducing crew cost and operational variability. Flight Management Systems occupy the largest margin pool due to their certification complexity and recurring retrofit cycles across existing fleets. Edge Computing deployment is gaining share fastest as latency requirements for detect-and-avoid functions outstrip cloud round-trip thresholds in contested airspace. Communication Systems face structural commoditization as open radio access interfaces proliferate among drone manufacturers.
The FAA's Part 23 rewrite and EASA's Special Condition for VTOL create dual-track certification burdens that filter out undercapitalized entrants. Military buyers reference NATO STANAG 4671 and DO-178C compliance as gatekeeping requirements for software procurement, concentrating vendor qualification among primes with existing airworthiness authority relationships. Stakeholders must monitor how type certification reciprocity agreements between the FAA and China's CAAC reshape market access for cross-border software licensing.
Market Dynamics
Certification compression timelines for eVTOL platforms are forcing software developers to front-load airworthiness validation costs, reshaping capital deployment across the autonomous flight stack ecosystem.
Growth Catalysts
- DO-178C Compliance Mandates:NATO defense procurement programs require software verification to this standard, filtering vendor pools toward qualified primes and sustaining multi-year development contracts.
- Urban Air Mobility Infrastructure:vertiport construction in Dallas, Los Angeles, and Miami creates captive demand for autonomous navigation systems tailored to low-altitude corridor management.
- Sensor Fusion Hardware Costs:solid-state lidar and mmWave radar price declines enable broader adoption of detect-and-avoid capabilities across mid-tier drone platforms.
Market Restraints
- Silicon Supply Concentration:advanced FPGA and AI accelerator fabrication concentrates in Taiwan, exposing flight computer developers to geopolitical supply disruption risks.
- Dual-Track Certification Burdens:FAA Part 23 rewrite and EASA Special Condition for VTOL impose parallel validation requirements that extend time-to-revenue for cross-Atlantic developers.
- Pilot Substitution Economics:unionized commercial aviation labor contracts in the United States and Germany delay crew cost savings realization, dampening airline adoption incentives.
Strategic Opportunities
- Brazil ANVISA Medical Cargo Corridors:regulatory frameworks for autonomous pharmaceutical delivery between São Paulo and remote Amazon clinics create first-mover positioning for cold-chain navigation software.
- AI-Edge Computing Convergence:onboard neural network inference chips enable real-time path replanning without ground station dependency, opening contested airspace applications.
- India PLI Scheme for Drones:production-linked incentives for domestic manufacturing attract software localization investments targeting agricultural spraying and infrastructure inspection verticals.
Industry Challenges
- DO-178C Talent Scarcity:qualified software verification engineers command premium compensation, constraining development velocity for undercapitalized entrants.
- Legacy Avionics Integration:retrofitting autonomous capabilities onto certified Part 25 aircraft requires extensive hardware-in-the-loop validation, extending program timelines.
- Intellectual Property Fragmentation:patent thickets around sense-and-avoid algorithms complicate licensing negotiations and increase litigation exposure for stack developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Aircraft Software Market |
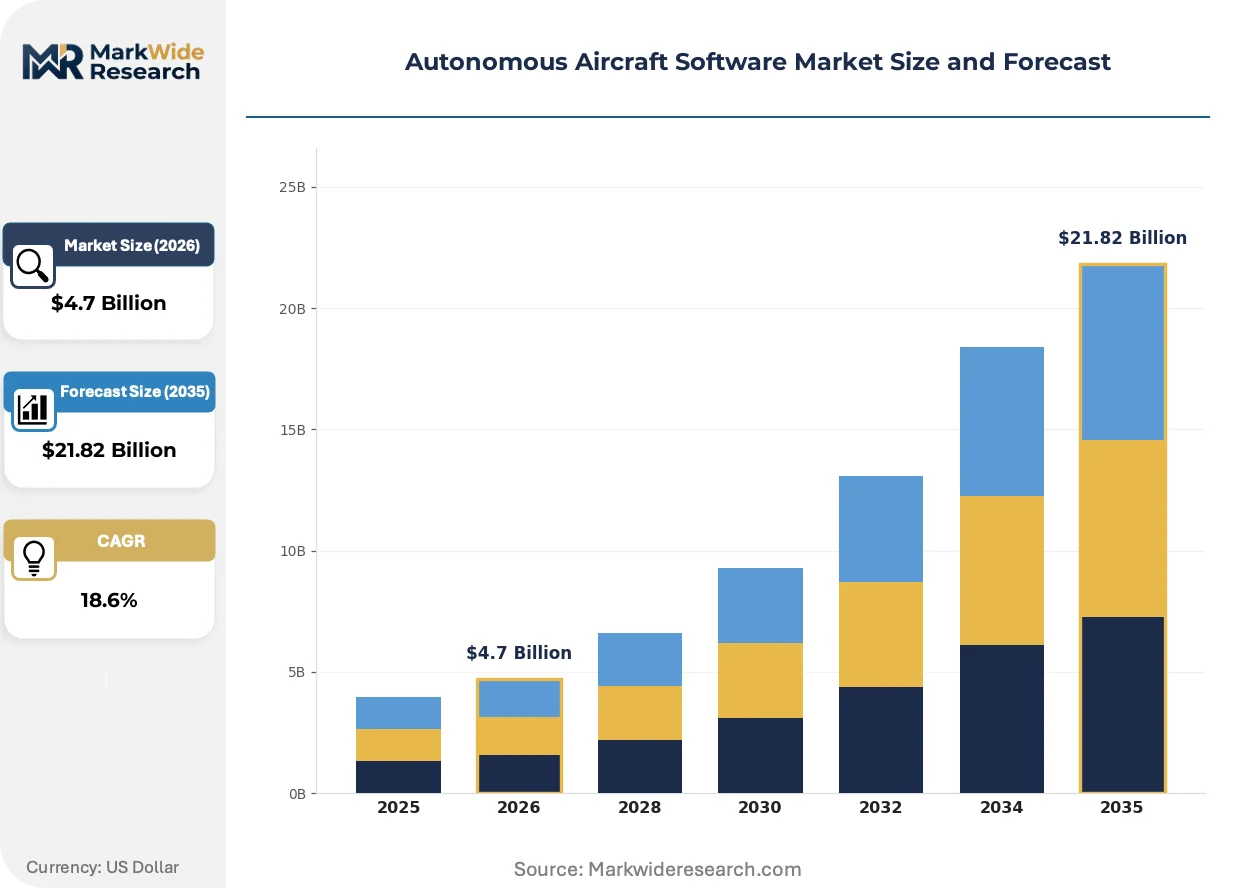
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Flight Management Systems, Navigation Software, Communication Systems, Data Processing Tools End User: Airlines, Cargo Operators, Military Aviation, Drone Manufacturers Deployment: Cloud-Based, On-Premise, Hybrid Systems, Edge Computing Application: Commercial Aviation, Military Operations, Cargo Delivery, Surveillance |
| Companies Covered | Astral, Archer Aviation, Shield AI, Percepto, Joby Aviation, Skydio, EHang, Dronzit Aerospace, Wisk Aero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Aircraft Software Market Strategic Shifts
Algorithmic architectures for autonomous flight are converging with semiconductor roadmaps, compressing the latency-performance tradeoff that has constrained real-time decision-making at the edge.
Deterministic AI inference engines are hybridizing traditional rule-based flight control with neural network perception layers. Military rotorcraft programs in the United States and Australia are piloting these stacks for degraded visual environment operations. The technology is hybridizing safety-critical software development practices, forcing vendors to reconcile formal verification methods with machine learning opacity.
EASA's AI Act implementation timeline imposes conformity assessment obligations on autonomous navigation systems deployed in European airspace. Developers must document algorithmic transparency and human oversight protocols prior to type certification. Urban air mobility platforms with beyond-visual-line-of-sight capabilities face the steepest compliance ramps, accelerating partnership formation with notified bodies.
Defense procurement offices are consolidating vendor relationships through multi-year software development agreements rather than discrete platform acquisitions. This shift displaces transactional licensing models in favor of recurring engineering retainers. The United States Army's Future Vertical Lift program exemplifies this pattern, embedding autonomy developers within prime contractor teams for sustained integration cycles.
Autonomous Aircraft Software Market Segmentation
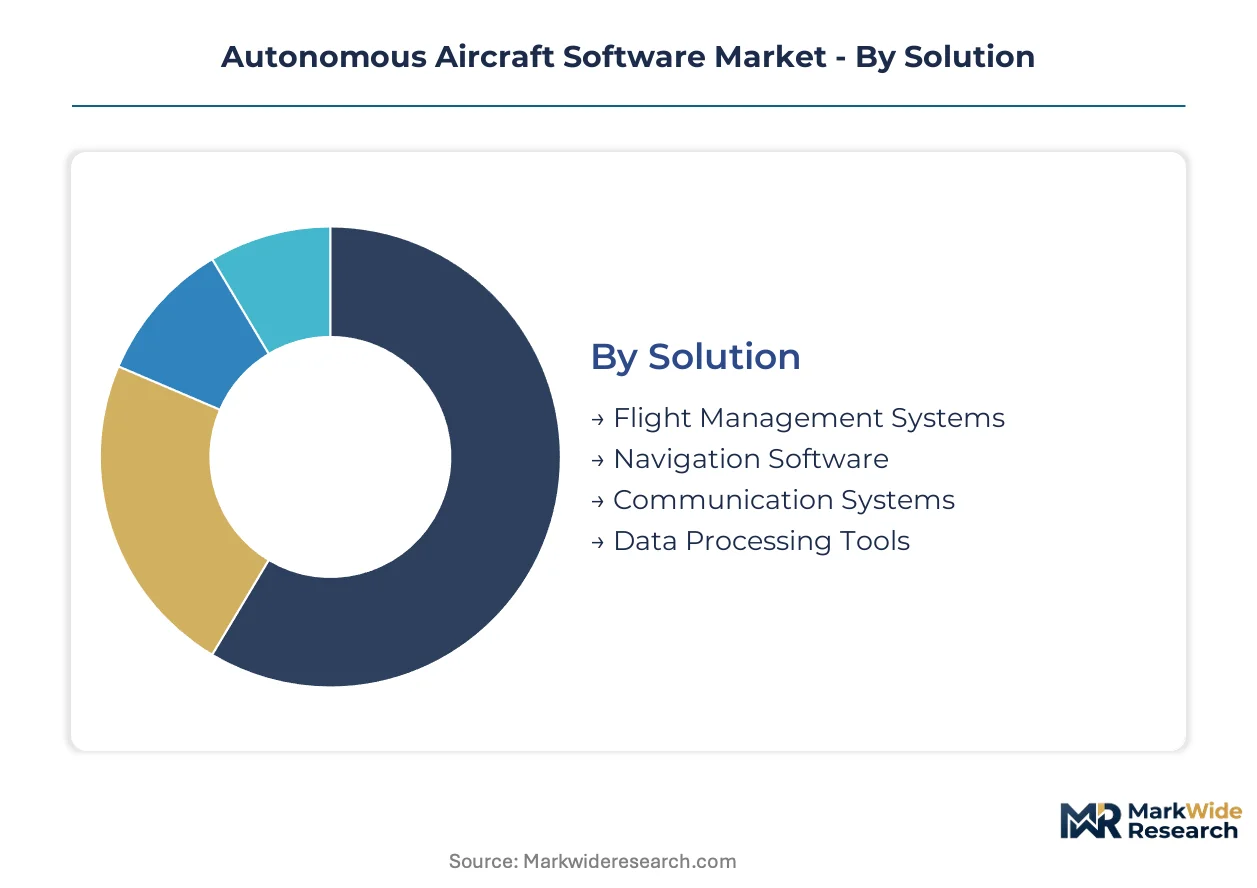
Segmentation in autonomous aircraft software reveals how certification complexity, latency requirements, and customer procurement patterns fragment revenue pools across the flight stack. Each dimension exposes distinct margin structures and vendor qualification barriers that shape competitive positioning.
Solution:
Cost tier stratification across the flight stack separates high-margin certified systems from commoditized middleware layers.
- Flight Management Systems:These integrate trajectory optimization, fuel calculations, and air traffic coordination into certified software modules. Demand concentrates among Part 25 retrofit programs and eVTOL type certification efforts where DO-178C compliance creates vendor stickiness.
- Navigation Software:Sensor fusion pipelines combining GNSS, inertial measurement, and visual odometry enable precision landing in GPS-denied environments. Military rotorcraft programs in Australia and the United States drive adoption for degraded visual environment operations.
- Communication Systems:Data link protocols for command-and-control and air traffic integration.
- Data Processing Tools:Middleware for log analysis, simulation replay, and fleet health monitoring.
Flight Management Systems hold installed capacity. Data Processing Tools is rotating up the share rankings.
End User:
Customer type determines procurement velocity, with defense programs sustaining multi-year development contracts while commercial operators demand transactional licensing.
- Military Aviation:NATO STANAG 4671 and DO-178C compliance requirements filter vendor pools toward primes with existing airworthiness authority relationships. The United States Army's Future Vertical Lift program exemplifies sustained integration cycles with embedded autonomy developers.
- Drone Manufacturers:Mid-tier platforms integrate solid-state lidar and mmWave radar as hardware costs decline, expanding detect-and-avoid capabilities beyond military budgets.
- Airlines:Unionized labor contracts in the United States and Germany delay crew substitution economics.
- Cargo Operators:Cold-chain pharmaceutical delivery creates first-mover demand for autonomous navigation in Brazil's Amazon corridors.
Military Aviation holds installed capacity. Drone Manufacturers is rotating up the share rankings.
Deployment:
Volume concentration shifts toward latency-sensitive architectures as contested airspace applications outstrip cloud round-trip thresholds.
- Edge Computing:Onboard neural network inference chips enable sub-100-millisecond obstacle detection and path replanning without ground station dependency. Urban air mobility platforms in Dallas, Los Angeles, and Miami deploy these for beyond-visual-line-of-sight corridor management.
- Cloud-Based:Fleet-wide analytics and non-time-critical mission planning leverage scalable compute resources.
- On-Premise:Sensitive military installations mandate air-gapped infrastructure for classified operations.
- Hybrid Systems:Partitioned architectures route safety-critical functions to edge nodes while offloading diagnostics to cloud backends.
Edge Computing holds installed capacity. Hybrid Systems is rotating up the share rankings.
Application:
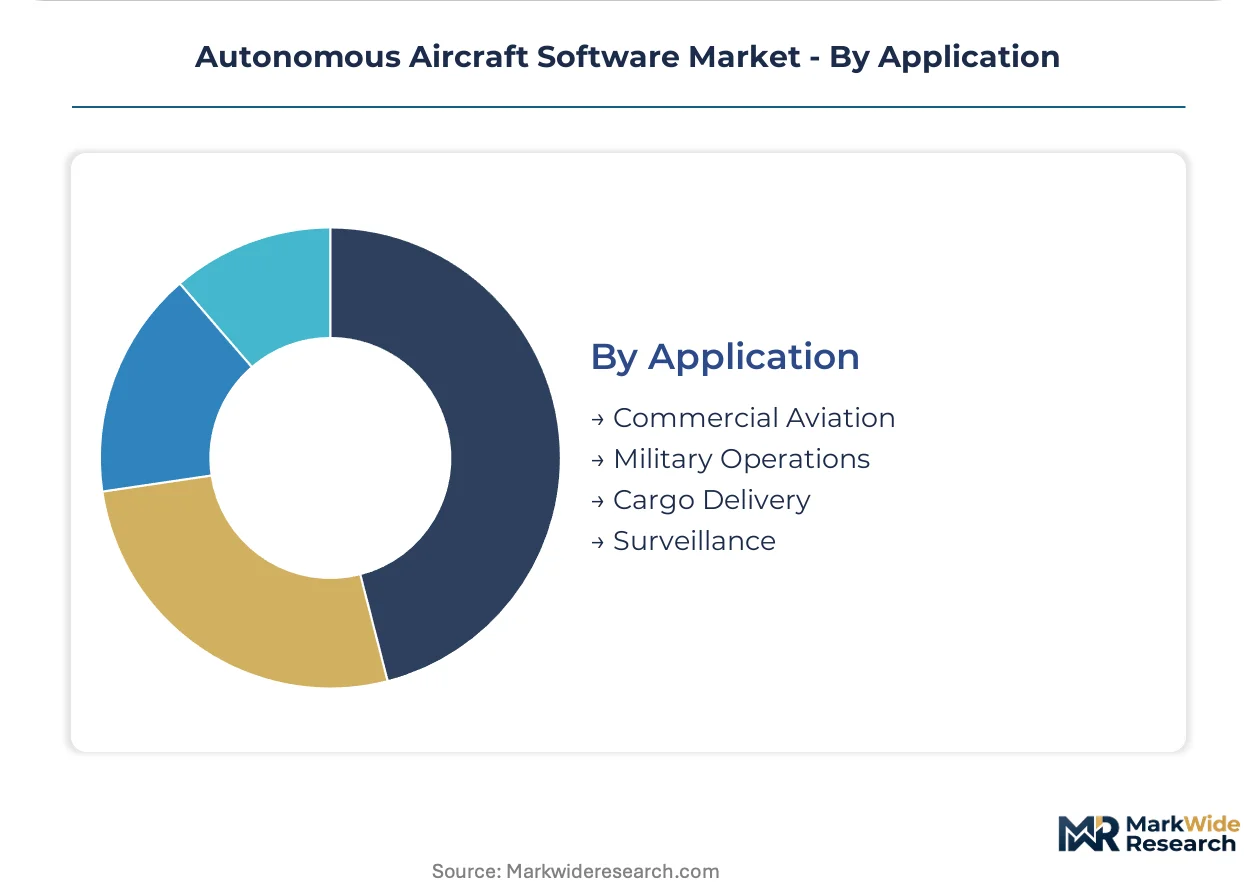
Application maturity separates revenue-stable surveillance markets from expansion-phase cargo networks and nascent commercial passenger services.
- Surveillance:Persistent area monitoring for border patrol and infrastructure inspection commands recurring software maintenance contracts. India's PLI scheme for drones attracts agricultural spraying and pipeline inspection localization investments.
- Cargo Delivery:Autonomous pharmaceutical corridors between São Paulo and remote Amazon clinics create regulatory sandbox opportunities under Brazil ANVISA frameworks.
- Military Operations:Degraded visual environment piloting stacks hybridize rule-based flight control with neural network perception.
- Commercial Aviation:eVTOL type certification under FAA Part 23 rewrite and EASA Special Condition for VTOL imposes parallel validation burdens.
Surveillance holds installed capacity. Cargo Delivery is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where defense primes extract premium engineering retainers, while European developers absorb dual-track certification costs that compress margins. This asymmetry shapes capital deployment across the autonomous flight stack ecosystem.
United States
Defense procurement through the Army's Future Vertical Lift program sustains multi-year autonomy development contracts. The FAA's Part 23 rewrite for eVTOL certification compresses timelines but front-loads validation costs. Engineering talent clusters in Dallas, Los Angeles, and Miami around vertiport infrastructure deployment.
Germany
Unionized commercial aviation labor contracts delay crew substitution economics for airlines. EASA's Special Condition for VTOL imposes conformity assessment obligations on navigation systems. Industrial activity concentrates in Bavaria and Baden-Württemberg, where automotive sensor suppliers pivot toward aviation applications.
China
Domestic eVTOL developers leverage GB standards and MIIT certification pathways for urban air mobility platforms. The NMPA framework for medical cargo drones creates regulatory sandbox opportunities. Manufacturing gravity centers on the Yangtze River Delta and Pearl River Delta, where solid-state lidar costs decline fastest.
Brazil
ANVISA medical cargo corridors between São Paulo and remote Amazon clinics generate first-mover demand for cold-chain navigation software. The country's national aviation regulator aligns autonomous pharmaceutical delivery frameworks with tropical operational requirements. São Paulo anchors software localization investments targeting agricultural spraying verticals.
Australia
Military rotorcraft programs pilot degraded visual environment stacks hybridizing rule-based control with neural perception. The TGA and national defense procurement office reference NATO STANAG 4671 for software verification. Brisbane and Melbourne host integration teams for contested airspace edge computing deployments.
Autonomous Aircraft Software Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream, supplying sensor fusion middleware and deterministic inference engines. The vendor base stratifies across three tiers: defense primes with airworthiness authority relationships, venture-backed eVTOL developers with captive software production, and asset-light licensors dependent on fleet leasing finance. Dominant competitive moves include multi-year embedded development agreements displacing transactional licensing, and backward integration into flight computer hardware to secure supply.
Within the defense prime tier, Shield AI and Wisk Aero exemplify sustained integration models. Shield AI occupies a position across fixed-wing and rotorcraft platforms, while Wisk Aero anchors Boeing-affiliated certification efforts under Part 23 standards. Among venture-backed developers, Joby Aviation represents vertical integration archetypes through captive flight control production, and Archer Aviation sits within the asset-light cluster dependent on external engineering partnerships. Skydio and Percepto exemplify specialists in detect-and-avoid middleware for mid-tier drone platforms.
| Leading Market Players |
|---|
| Astral |
| Archer Aviation |
| Shield AI |
| Percepto |
| Joby Aviation |
| Skydio |
| EHang |
| Dronzit Aerospace |
| Wisk Aero |
| Others |
Value Chain & Pricing Dynamics
Taipei-based FPGA and AI accelerator fabrication anchors cost structures for flight computer developers, with capacity constraints in advanced semiconductor nodes translating directly into premium pricing for certified avionics processors. Defense primes extract engineering retainer premiums by embedding software verification teams within multi-year procurement cycles, while commercial eVTOL developers absorb front-loaded airworthiness validation costs that compress early-stage margins.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with DO-178C certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in mid-tier drone middleware is intensifying because solid-state lidar and mmWave radar commoditization erodes sensor fusion software premiums. Drone manufacturers exhibit highest price sensitivity due to hardware margin pressure, while military aviation procurement teams prioritize certification pedigree over unit economics.
Supply Chain Analysis
TSMC and Samsung Foundry hold dominant capacity for advanced AI inference chips feeding flight computer developers, with supply chains drawing from Taiwan, South Korea, and the United States for semiconductor fabrication. Raw material dependencies center on silicon wafers, rare earth magnets for actuators, and high-reliability capacitors. Single-source vulnerability in Taiwan-based advanced node production exposes developers to geopolitical disruption. Distribution runs through prime contractor integration teams for defense programs and direct OEM licensing for commercial platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in autonomous aviation hinge on interoperability standards consolidation, with the FAA-EASA type certification reciprocity negotiation representing a decisive ecosystem inflection that will concentrate vendor pools around dual-compliant software stacks.
For Market Incumbents: Harden certification moats by accelerating DO-178C talent acquisition programs in Dallas and Los Angeles engineering clusters, while deepening backward integration into deterministic AI inference hardware to secure supply against Taiwan fab concentration. Emerging venture-backed eVTOL developers with captive software production threaten prime contractor margins through vertical integration plays. For New Entrants and Emerging Players: Brazil's Amazon medical cargo corridors offer underpenetrated regulatory sandbox positioning for cold-chain navigation software, with ANVISA frameworks creating first-mover advantages absent entrenched competition. India's PLI scheme for agricultural spraying drones presents a second white-space target. A certification-light partnership model with established airworthiness authorities accelerates time-to-revenue versus direct type certification pursuit. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor fusion middleware specialists with proven detect-and-avoid algorithms and existing NATO STANAG 4671 relationships. Long-term viability across the analysis window rests on algorithmic transparency documentation ahead of EASA AI Act implementation. The signal to monitor is FAA Part 23 rewrite finalization timing, which will compress or extend certification runway requirements for portfolio companies.| Strategic Initiative | Industry Significance |
|---|---|
| DO-178C Certification Investment | Unlocks NATO defense procurement pipelines and sustains multi-year engineering retainers. |
| Edge Computing Hardware Integration | Secures sub-100-millisecond latency supply for contested airspace applications. |
| Vertiport Infrastructure Partnership | Captures captive demand in Dallas, Los Angeles, and Miami corridor deployments. |
| AI-Edge Inference Chip Development | Enables real-time path replanning without ground station dependency in GPS-denied environments. |
| Dual-Track FAA-EASA Compliance | Accelerates cross-Atlantic market access and filters out undercapitalized competitors. |
Study Parameters
Initial hypotheses were tested against primary input from flight control software engineers, airworthiness certification leads, defense procurement officers, and eVTOL program directors and refined through secondary validation against FAA type certification filings, EASA special condition publications, NATO STANAG documentation, and Army Future Vertical Lift program disclosures. Bottom-up segment sizing triangulated with top-down macro demand modeling across solution, end user, deployment, and application dimensions.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeling spanning flight management systems, navigation software, communication systems, and data processing tools by military aviation, drone manufacturers, airlines, and cargo operators. CAGRs derived from installation base growth curves, retrofit cycle frequencies, and certification timeline compression rates. Forecast inputs incorporated vertiport infrastructure deployment schedules and solid-state lidar cost decline trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by venture-backed eVTOL developers with balance sheet runway would shift outcomes through accelerated captive software production. Regulatory reciprocity negotiations between the FAA and CAAC, plus Taiwan supply disruption scenarios, represent primary revision risks. Quarterly review of type certification award velocity and defense contract announcement flow is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Unattended Ground Sensors (UGS) Market
Unmanned Systems
Military Robots Market
Unmanned Systems
Drone Docking Station Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
Europe Military Unmanned Vehicles Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Automated Weapon System Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
North America Hyperloop Technology Market