
 Europe Aerospace Robotics Market | 2026-2036
Europe Aerospace Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aerospace Robotics Market Analytics
Commercial aviation manufacturing is decoupling from legacy fixed automation as flexible robotic systems penetrate final assembly lines. KUKA AG leverages its Stuttgart engineering base to dominate large-payload articulated systems for fuselage drilling and fastening. ABB Group sustains competitive intensity through R&D intensity in sensor fusion technologies for precision aerospace applications. FANUC Corporation anchors its European position with manufacturing scale across CNC-integrated robotic cells serving Airbus supplier networks.
Europe aerospace robotics encompasses programmable multi-axis manipulators, autonomous guided vehicles, and AI-enabled inspection systems engineered to tolerances below 0.1 millimeter for airframe and propulsion component production. These systems execute drilling, riveting, composite layup, and non-destructive testing in cleanroom environments where human access remains constrained. Collaborative robots capture expanding share in final assembly as safety-rated torque limiting enables human-robot coexistence on crowded production floors. Artificial Intelligence and machine learning segments attract disproportionate investment as predictive maintenance algorithms reduce unplanned downtime at Tier-1 supplier plants. Industrial robots retain volume leadership in high-throughput drilling and fastening operations where repeatability specifications exceed collaborative platform capabilities.
EMA medical device parallels inform aerospace robotics safety validation, while CE marking and EU AI Act compliance frameworks mandate documented risk assessment for autonomous systems deployed in production environments. REACH substance restrictions shape end-of-life robot disposal protocols and drive material substitution in gripper and cable assemblies. Stakeholders must monitor evolving CSRD disclosure requirements affecting capital allocation for automation retrofit programs across European aerospace manufacturing footprints.
Market Dynamics
Commercial aviation fleet modernization is forcing European OEMs to replace fixed automation with flexible robotic systems capable of handling mixed-model production on single assembly lines.
Growth Catalysts
- EU Green Deal:The framework mandates carbon-neutral manufacturing processes by 2050, compelling airframe producers to adopt energy-efficient robotic drilling and fastening systems that reduce material waste and power consumption.
- Composite airframe penetration:Next-generation aircraft designs utilize carbon fiber reinforced polymers at unprecedented scale, creating demand for specialized robotic layup and trimming systems that maintain fiber orientation tolerances below 0.5 degrees.
- German production concentration:Hamburg, Bremen, and Munich host Airbus final assembly and major Tier-1 supplier clusters, concentrating capital deployment for robotic system upgrades within a 500-kilometer radius.
Market Restraints
- Rare earth magnet supply concentration:High-performance servo motors in aerospace-grade robots depend on neodymium processed primarily through Chinese supply chains, exposing European manufacturers to export restriction risks and price volatility.
- REACH substance restrictions:ECHA's evolving candidate list for Substances of Very High Concern threatens availability of specialized lubricants and sealants used in precision gearboxes, forcing costly reformulation cycles.
- Technical limitation in force-controlled riveting:Current collaborative robot platforms cannot achieve the 15-kilonewton clamping forces required for certain titanium fastener applications, preserving demand for legacy hydraulic systems.
Strategic Opportunities
- Spain underpenetration:Seville and Getafe maintain significant Airbus manufacturing footprints with lower robotic density than German or French equivalents, presenting retrofit opportunities as A320 family production rates climb.
- AI-enabled predictive maintenance:Machine learning algorithms analyzing vibration signatures from robotic drilling spindles can forecast bearing failures 200 operating hours in advance, creating subscription revenue streams for system integrators.
- CSRD disclosure requirements:The Corporate Sustainability Reporting Directive mandates granular Scope 1-3 emissions disclosure, incentivizing aerospace manufacturers to document automation-driven efficiency gains for investor reporting.
Industry Challenges
- Mechatronics talent scarcity:European technical universities produce insufficient graduates combining mechanical engineering, control systems, and aerospace manufacturing process knowledge to support deployment timelines.
- CE marking and EU AI Act compliance:Autonomous inspection robots must complete documented risk assessments and conformity evaluation procedures that extend qualification cycles by 8-14 months.
- Legacy system integration:Brownfield final assembly lines operate programmable logic controllers from 1990s architectures, requiring custom gateway development for Industry 4.0 data exchange with modern robotic cells.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aerospace Robotics Market |
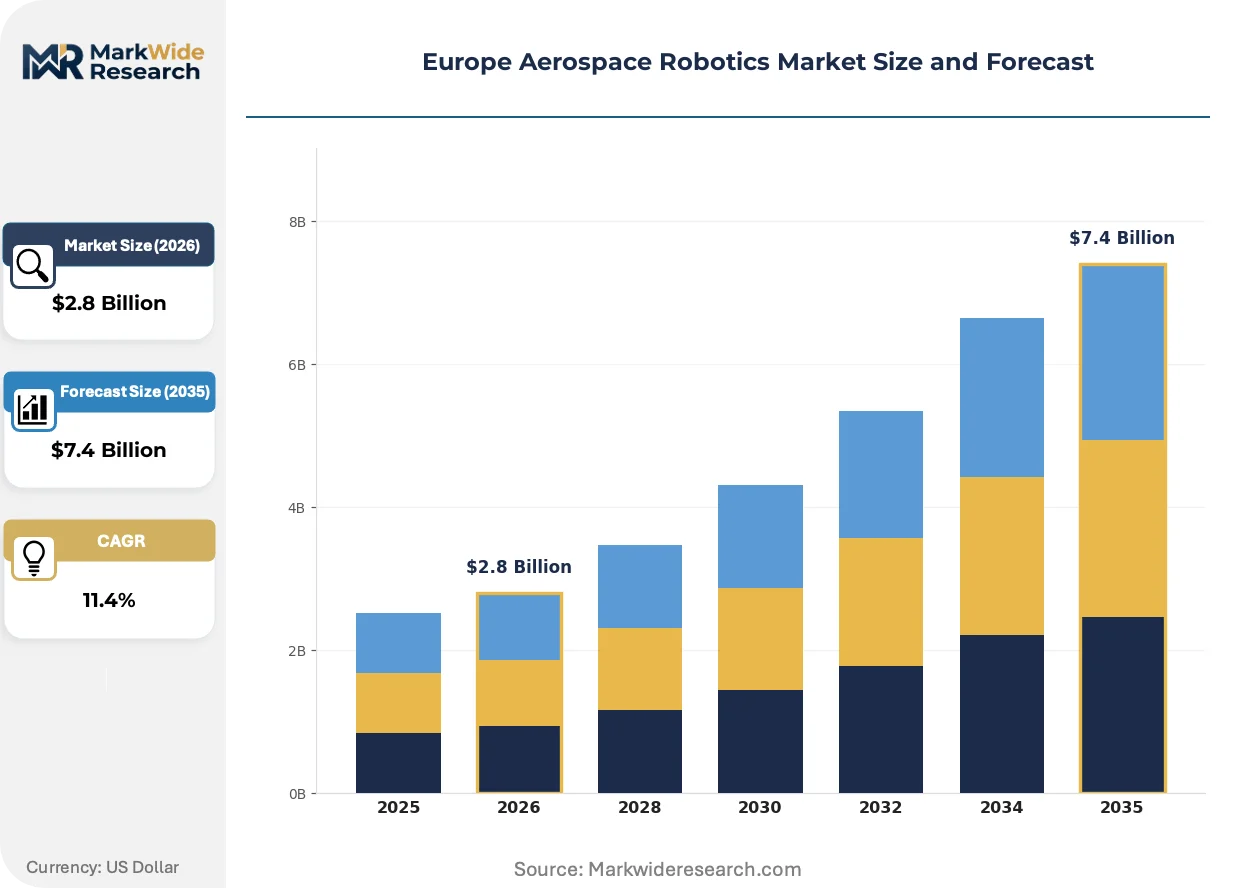
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collaborative Robots, Industrial Robots, Autonomous Mobile Robots, Articulated Robots Technology: Artificial Intelligence, Machine Learning, Sensor Fusion, Computer Vision Application: Manufacturing, Assembly, Inspection, Maintenance End User: OEMs, Tier-1 Suppliers, Service Providers, Research Institutions |
| Companies Covered | KUKA AG, ABB Group, FANUC Corporation, Yaskawa Electric Corporation, Universal Robots, Electroimpact, OCR Robotics, Kawasaki Heavy Industries, Comau Robotics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aerospace Robotics Market Evolving Landscape
Digital thread architectures are collapsing the boundary between engineering design and shop-floor execution, enabling real-time robotic path correction based on as-built metrology feedback rather than nominal CAD models.
Force-controlled end-effectors with integrated six-axis torque sensors are absorbing quality assurance functions previously performed by standalone coordinate measuring machines. Airbus Hamburg deploys these systems for automated wing-to-fuselage join operations, eliminating 40% of manual shimming labor while compressing final assembly station cycle times. The technology is absorbing capital allocation from fixed CMM infrastructure investments.
CSRD disclosure requirements are mandating granular carbon accounting across manufacturing footprints. Aerospace producers must now document energy consumption per robotic work cell for investor sustainability reports, driving demand for power-monitoring middleware and ISO 50001-aligned automation architectures. Tier-1 suppliers in France and Germany are responding by retrofitting legacy systems with energy-recuperating servo drives.
After-sales service unbundling is fragmenting traditional robot vendor relationships. Maintenance contracts now separate hardware availability guarantees from software update subscriptions and spare parts logistics, enabling third-party integrators to compete on diagnostic response times. This shift is most visible in the United Kingdom, where Rolls-Royce Derby and BAE Systems Warton operations have adopted multi-vendor service ecosystems for mixed-fleet robotic assets.
Europe Aerospace Robotics Market Segmentation
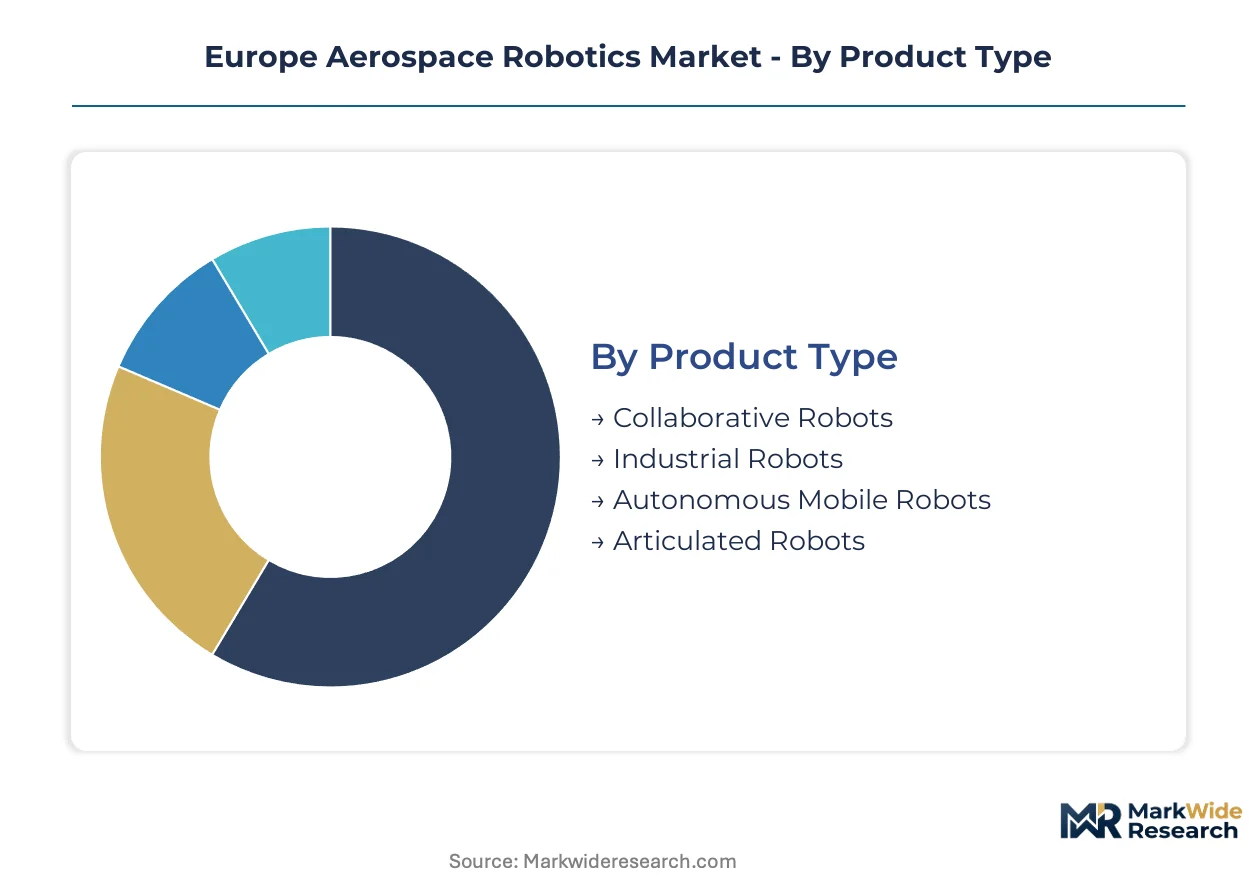
Segmentation reveals how certification burdens and performance specifications fragment procurement patterns across European aerospace manufacturing. Each dimension carries distinct compliance obligations under EU machinery directives and aerospace quality standards.
Product Type:
CE marking and EU AI Act compliance timelines vary sharply across robot categories, with force-limited collaborative platforms clearing conformity assessment faster than high-payload industrial systems.
- Collaborative Robots:Force-torque limited manipulators enable human-robot coexistence on crowded final assembly floors. Airbus Hamburg and Toulouse operations deploy these systems for wing-to-fuselage join tasks where safety-rated monitoring replaces physical guarding. Demand concentrates in France and Germany as OEMs retrofit brownfield lines without major facility reconfiguration.
- Industrial Robots:High-rigidity articulated systems deliver the repeatability and clamping force required for titanium fastener drilling and composite trimming. German Tier-1 suppliers in Bavaria and Baden-Württemberg anchor procurement volume for these systems, driven by A320 family production rate increases.
- Autonomous Mobile Robots:Fleet-managed transport platforms navigate cleanroom environments to deliver components to fixed robotic work cells. These systems require updated machinery safety validation under EN ISO 3691-4.
- Articulated Robots:Six-axis manipulators with payload capacities exceeding 500 kilograms dominate fuselage drilling operations. KUKA AG's Stuttgart engineering base supplies the majority of European aerospace-grade installations.
Industrial Robots sits at the top of the volume ranking, with Collaborative Robots climbing the fastest.
Technology:
Technology selection determines which EU regulatory frameworks apply, with AI-enabled systems triggering additional risk documentation under the EU AI Act's high-risk system category.
- Artificial Intelligence:Predictive maintenance algorithms analyzing vibration signatures from robotic drilling spindles forecast bearing failures 200 operating hours in advance. Tier-1 suppliers in the United Kingdom and Germany pilot subscription-based diagnostic services built on these capabilities.
- Machine Learning:Supervised learning models trained on historical metrology data enable real-time path correction during composite layup operations. These systems require documented training data governance under emerging EU AI Act obligations.
- Sensor Fusion:Integrated torque, vision, and proximity sensing enables force-controlled riveting without standalone quality assurance infrastructure.
- Computer Vision:High-resolution inspection systems detect subsurface defects in carbon fiber reinforced polymer components during automated non-destructive testing sequences.
Sensor Fusion commands the highest average system value, while Artificial Intelligence is gaining share fastest among new capital deployments.
Application:
Application type dictates cleanroom classification requirements and operator certification levels, with inspection and maintenance functions demanding more stringent personnel qualifications than manufacturing operations.
- Manufacturing:Automated drilling, riveting, and fastening operations in airframe production require ISO 14644-1 Class 7-8 cleanroom environments. German and French facilities concentrate procurement for these systems.
- Assembly:Final join operations for wing-to-fuselage attachment utilize force-controlled end-effectors with integrated metrology feedback, eliminating manual shimming labor at Airbus Hamburg and Toulouse.
- Inspection:Autonomous systems performing non-destructive testing must complete documented risk assessments extending qualification cycles by 8-14 months under CE marking procedures.
- Maintenance:Robotic systems for engine overhaul and component repair operate in lower-volume, higher-mix environments with less standardized programming requirements.
Manufacturing holds the largest installed base, with Inspection expanding most quickly as quality assurance functions migrate from standalone CMM infrastructure to integrated robotic platforms.
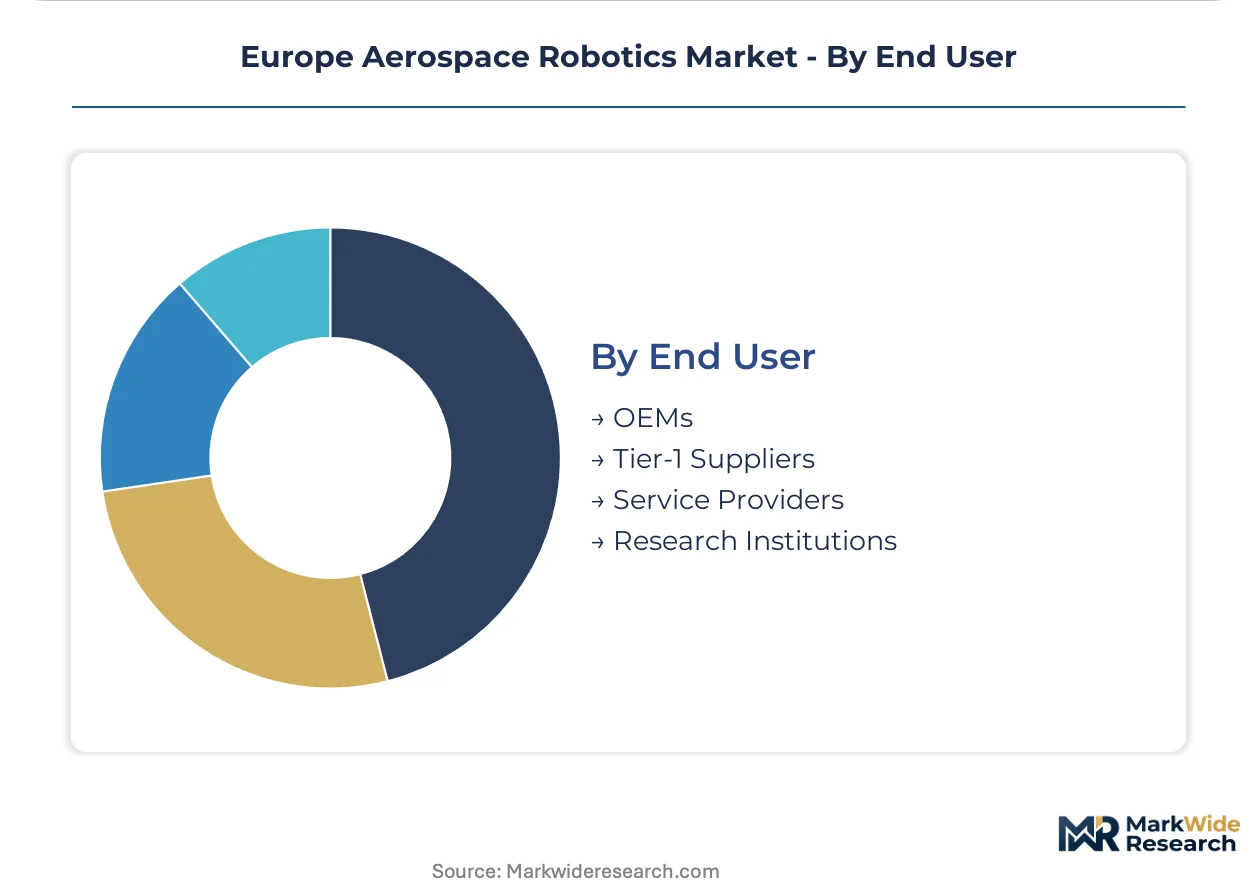
End User:
End user category determines procurement sophistication and service contract structures, with OEMs driving standardization while Tier-1 suppliers pursue multi-vendor flexibility.
- OEMs:Airbus and BAE Systems specify system architectures that propagate through supplier networks, creating de facto standards for robotic cell configurations across European manufacturing footprints.
- Tier-1 Suppliers:GKN Aerospace, Leonardo, and Safran operations adopt multi-vendor service ecosystems for mixed-fleet assets, unbundling hardware availability from software update subscriptions.
- Service Providers:Third-party integrators compete on diagnostic response times and retrofit expertise for legacy system upgrades.
- Research Institutions:Universities and national laboratories pilot next-generation capabilities including digital thread architectures and human-robot collaboration protocols.
Tier-1 Suppliers represent the deepest retrofit opportunity, with Service Providers recording the steepest expansion trajectory as after-sales unbundling fragments traditional vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where REACH compliance costs and CSRD disclosure burdens create competitive arbitrage for aerospace manufacturers. Germany and France absorb the highest regulatory compliance costs while Spain and Italy offer lower-cost automation retrofit environments. The EU AI Act's high-risk system documentation requirements further differentiate investment climates across member states.
Germany
Airbus final assembly in Hamburg and Bremen drives concentrated demand for large-payload articulated systems. The CSRD mandates granular Scope 1-3 emissions disclosure from 2024, forcing Bavarian Tier-1 suppliers to document automation-driven efficiency gains. Munich and Augsburg host KUKA AG engineering operations serving fuselage drilling applications.
France
Toulouse operations anchor European wide-body production with robotic wing-to-fuselage join deployments. ECHA's evolving SVHC candidate list threatens specialized lubricant availability, forcing reformulation cycles at Safran and Leonardo facilities. The EU Green Deal carbon-neutral manufacturing mandate accelerates energy-efficient servo drive adoption in Occitanie.
United Kingdom
Rolls-Royce Derby and BAE Systems Warton operations pilot multi-vendor service ecosystems for mixed-fleet assets. CE marking and EU AI Act risk assessment documentation extends autonomous inspection robot qualification cycles. Bristol and Filton maintain significant composite manufacturing footprints with expanding collaborative robot penetration.
Spain
Seville and Getafe Airbus facilities present underpenetrated retrofit opportunities as A320 family production rates climb. REACH substance restrictions on sealants and gear lubricants impose lower compliance costs than German or French equivalents. Andalusian operations increasingly attract automation investment seeking regulatory cost arbitrage.
Italy
Leonardo's helicopter and aerostructures production in Piedmont and Campania drives specialized robotic cell demand. The EU AI Act's high-risk system category triggers additional conformity evaluation for autonomous inspection platforms. Turin and Naples engineering clusters develop force-controlled end-effectors for composite trimming applications.
Europe Aerospace Robotics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with system integrators capturing service revenue as OEMs unbundle hardware from software subscriptions. The vendor base concentrates around three strategic tiers: Stuttgart-engineered large-payload specialists, Swiss-Japanese precision automation conglomerates, and Danish collaborative platform pioneers. M&A activity targets sensor fusion and AI-enabled predictive maintenance capabilities, while geographic expansion focuses on Spanish and Italian retrofit markets with lower robotic density.
Within the European-engineered tier, KUKA AG exemplifies large-payload system specialization for fuselage applications. ABB Group and FANUC Corporation occupy positions spanning industrial and collaborative platform portfolios, with the latter anchoring manufacturing scale across CNC-integrated supplier networks. Universal Robots represents the collaborative archetype, its force-limited platforms penetrating final assembly lines where safety-rated monitoring replaces physical guarding. These three entities collectively illustrate the competitive structure: European engineering heritage, Asian manufacturing scale, and Nordic collaborative innovation each command distinct procurement channels.
| Leading Market Players |
|---|
| KUKA AG |
| ABB Group |
| FANUC Corporation |
| Yaskawa Electric Corporation |
| Universal Robots |
| Electroimpact |
| OCR Robotics |
| Kawasaki Heavy Industries |
| Comau Robotics |
| Others |
Value Network & Pricing Analysis
Captive servo motor production in Baden-Württemberg and Bavaria anchors both supply security and pricing power for German system integrators serving Airbus networks. This vertical integration shields Tier-1 suppliers from rare earth magnet volatility while compressing channel margins for foreign competitors lacking equivalent upstream control.
Pricing Analysis
Direct-to-OEM discounts of 12-18 percent dominate large-payload articulated system procurement, with KUKA AG and ABB Group bypassing distributor layers for Hamburg and Toulouse final assembly contracts. Three-tier pricing structure across premium aerospace-grade, standard industrial, and economy retrofit levels separates systems by CE marking complexity and force-control precision. Pricing pressure stems from Spanish and Italian facilities demanding comparable capability at lower installed-base premiums. Tier-1 suppliers exhibit highest price sensitivity as multi-vendor service ecosystems fragment traditional hardware-software bundling.
Supply Chain Analysis
Mechatronics engineering talent scarcity in Stuttgart, Munich, and Hamburg production clusters forces reliance on Polish and Czech technical universities for control systems graduates. Neodymium permanent magnets draw from Chinese processing concentration, while precision gearboxes and torque sensors source from Swiss and Japanese component specialists. Single-source vulnerability in rare earth supply chains exposes European manufacturers to export restriction risks under geopolitical tension. Distribution runs through system integrator networks with hardware availability guarantees unbundled from predictive maintenance software subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Europe aerospace robotics rests on energy-recuperating servo drive adoption driven by CSRD disclosure mandates, with premium-tier shifts toward AI-enabled predictive maintenance creating recurring revenue streams.
For Market Incumbents: Anticipate force-controlled collaborative platforms displacing legacy hydraulic systems in titanium fastener applications by 2026. Defend position through backward integration into torque sensor manufacturing and CE marking pre-certification programs that compress qualification cycles. Prioritize sensor fusion R&D investments to absorb coordinate measuring machine functions into end-effector platforms. For New Entrants and Emerging Players: AI-enabled vibration signature analysis offers technology-first wedge into aftermarket service contracts for mixed-fleet robotic assets. Target Seville and Getafe Airbus facilities with lower robotic density than German equivalents, positioning predictive maintenance subscriptions as retrofit financing alternatives. Pursue multi-vendor diagnostic response time competition against incumbent hardware vendors. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators because CSRD disclosure requirements fragment service contracts and create acquisition targets with sticky software subscription revenue. Long-term viability centers on platforms combining hardware availability with ISO 50001-aligned energy monitoring middleware. Watch ECHA SVHC candidate list expansion as inflection indicator for lubricant reformulation cost shocks affecting gearbox specialist valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Recycling | Reduces Chinese supply chain exposure for Stuttgart-engineered servo motor production. |
| CE Marking Pre-Certification Programs | Compresses EU AI Act qualification cycles for autonomous inspection robot deployments. |
| Energy-Recuperating Servo Drive Retrofit | Documents Scope 1-3 efficiency gains for CSRD investor disclosure requirements. |
| AI-Enabled Predictive Maintenance Subscription | Captures recurring revenue from Tier-1 supplier mixed-fleet diagnostic contracts. |
| Force-Controlled End-Effector Development | Absorbs quality assurance functions from standalone CMM infrastructure at Airbus Hamburg. |
Research Methodology
Coverage spans Germany, France, the United Kingdom, Spain, and Italy, with primary inputs from each jurisdiction's aerospace manufacturing clusters. The analysis combines interviews with plant engineers at Airbus final assembly facilities, procurement leads at Tier-1 aerostructures suppliers, and aftermarket service heads at system integrator networks. Secondary validation draws from ECHA SVHC candidate list updates, CE marking conformity databases, and CSRD disclosure filings. Bottom-up robotic cell deployment counts triangulate against top-down OEM capital expenditure patterns.
Granularity-level modeling segments by product type, technology, application, and end user, with additional dimensioning by cleanroom classification tier and regulatory compliance burden. Value projections across the analysis window derive from unit economics of force-limited collaborative platforms versus high-payload industrial systems. CAGRs incorporate A320 family production rate trajectories and REACH substance restriction implementation timelines as industry-specific demand drivers.
The model holds under stable EU Green Deal carbon-neutral manufacturing mandates and ECHA regulatory timelines; deviation in rare earth export restrictions or EU AI Act enforcement intensity would shift deployment velocity assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
Drone Battery System Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
Aerostat System Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
Drone Parachute System Market
Unmanned Systems
Unmanned Systems Market