
 Europe Space Electronics Market | 2026-2036
Europe Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Space Electronics Market Analytics
Aerospace-qualified engineering talent is rotating toward radiation-hardened design centers in France and Germany, tightening labor availability for legacy analog programs. STMicroelectronics N.V. leverages its Grenoble-based R&D footprint to anchor European supply for power modules. Thales Group sustains long-term relationships with French government space programs through Alenia Space partnerships. BAE Systems PLC competes on military-grade radiation tolerance for sovereign satellite payloads.
Europe Space Electronics encompasses semiconductor devices, subsystems, and integrated circuits engineered to withstand ionizing radiation, extreme thermal cycling, and vacuum conditions across orbital and deep-space missions. These components typically operate across temperature ranges from minus 55 to 125 degrees Celsius and must survive total ionizing dose exposures exceeding 100 kilorads for geostationary applications. Power Modules command the largest revenue share due to their indispensable role in satellite bus architectures and electric propulsion systems. Communication Systems are expanding fastest as mega-constellation operators demand higher throughput transceivers and onboard processing units.
EMA's medical-device heritage informs traceability standards now migrating into space electronics via the EU Medical Device Regulation's quality-system precedents, while REACH restricts hazardous substances in soldering and substrate materials. The EU Green Deal's carbon-border adjustments are pressuring foundries to document embodied emissions across wafer fabrication. Stakeholders must weigh sovereign capability investments against the cost advantages of non-European foundry partnerships as qualification timelines lengthen.
Market Dynamics
Sovereign capability investments across France, Germany, and Italy are colliding with REACH material restrictions and carbon-border documentation requirements, forcing a reconfiguration of qualification timelines and foundry partnerships.
Growth Catalysts
- Satellite Constellation Deployment:Mega-constellation operators for broadband and Earth observation are pulling procurement volumes upward for radiation-hardened power modules and transceivers.
- REACH Compliance Migration:ECHA's substance restrictions are accelerating substitution of hazardous soldering materials with compliant alternatives in substrate fabrication.
- Electric Propulsion Adoption:Satellite bus architectures are integrating high-efficiency power electronics for station-keeping and orbital transfer maneuvers.
Market Restraints
- Wafer Supply Concentration:Non-European foundries control critical radiation-hardened process nodes, exposing European fabless designers to qualification timeline volatility.
- Technical Qualification Burden:Total ionizing dose testing exceeding 100 kilorads for geostationary missions extends development cycles by 18-24 months.
- Input Cost Pressure:Specialized ceramic substrates and gold-aluminum wire bonding materials face price instability from mining supply constraints.
Strategic Opportunities
- Eastern European Manufacturing:Poland and the Czech Republic offer untapped cleanroom capacity for backend assembly and test operations.
- Onboard Processing Convergence:Edge computing architectures are merging with communication payloads to reduce ground-segment dependency.
- EU Green Deal Incentives:Carbon-border adjustment documentation requirements favor foundries with verified low-emission wafer fabrication.
Industry Challenges
- Radiation-Hardened Design Talent Scarcity:Aerospace-qualified engineering pools in Grenoble and Munich cannot scale to match constellation procurement timelines.
- Dual-Use Certification Complexity:Military-grade radiation tolerance standards from national space agencies conflict with commercial mega-constellation cost targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Space Electronics Market |
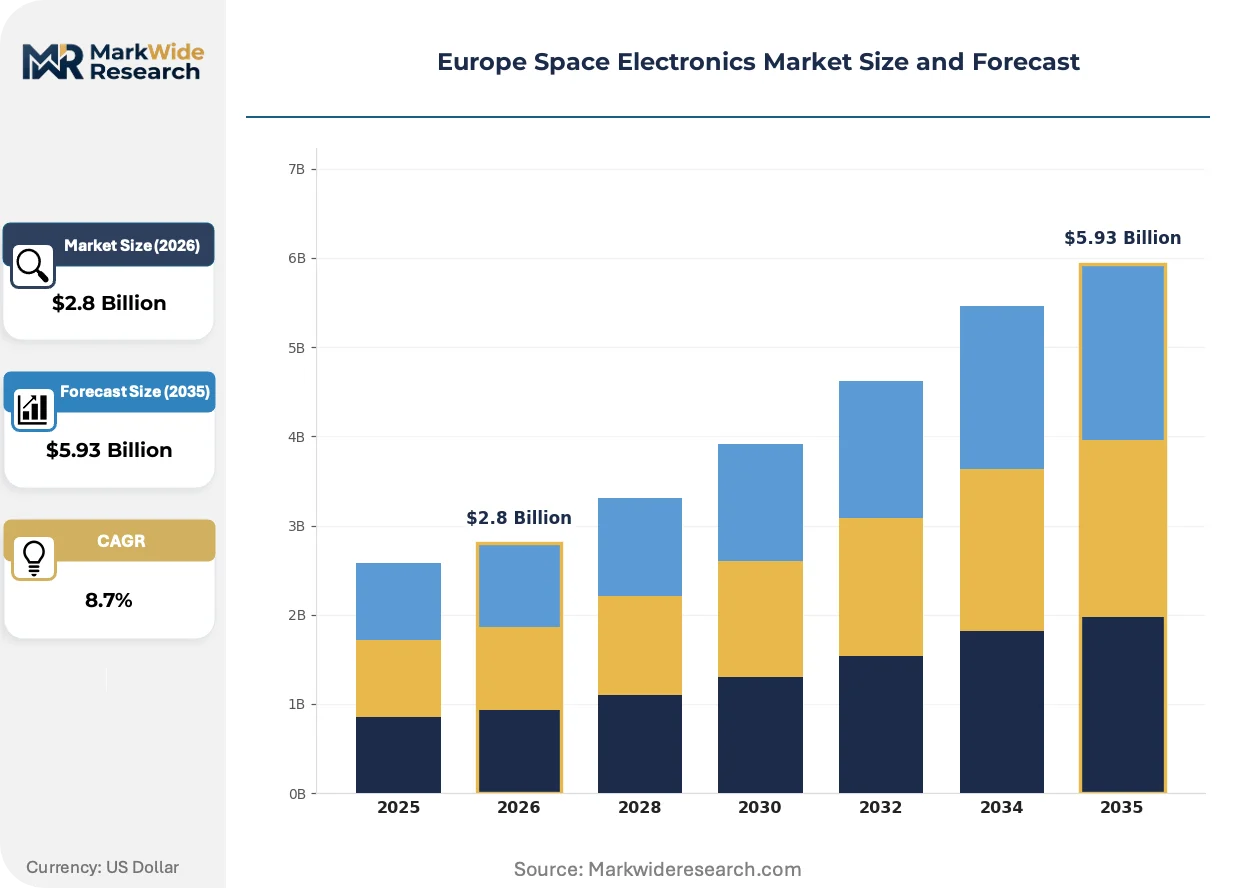
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Modules, Communication Systems, Control Units, Sensors Technology: Radiation-Hardened, Nanotechnology, FPGA, Analog Application: Satellite, Launch Vehicle, Space Science, Earth Observation End User: Government Agencies, Commercial Space, Research Institutions, Military |
| Companies Covered | STMicroelectronics N.V., Texas Instruments, Inc., Honeywell International, Inc., BAE Systems PLC, Thales Group, Airbus Defence and Space, Eaton Corporation PLC, Teledyne Technologies, Inc., TT Electronics PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Space Electronics Market Evolving Landscape
Three distinct vectors are compressing development cycles and rewiring competitive positioning: component miniaturization for payload density, regulatory documentation for embodied carbon, and procurement centralization among constellation operators.
System-in-package integration is miniaturizing discrete power management functions into single radiation-hardened modules. Satellite prime contractors in Toulouse and Friedrichshafen are adopting these stacked die configurations to reclaim payload volume for scientific instruments or additional transponders. The technology is miniaturizing traditional multi-chip power distribution networks into footprint-compatible replacements that survive thermal cycling from minus 55 to 125 degrees Celsius.
CSRD disclosure mandates are extending into space electronics supply chains. Large satellite manufacturers must now document Scope 3 emissions from semiconductor foundries, forcing tier-two component suppliers to install carbon accounting systems. French and German primes are responding by qualifying alternative European foundry partners with verified low-carbon wafer processes.
Constellation operators are consolidating procurement through dedicated supply programs rather than transactional component purchasing. This channel compression is eliminating traditional distributor margins and forcing direct engineering relationships between satellite bus designers and power module specialists. The shift is most visible in OneWeb and Amazon Kuiper supplier qualification activities targeting Grenoble-based R&D centers.
Europe Space Electronics Market Segmentation
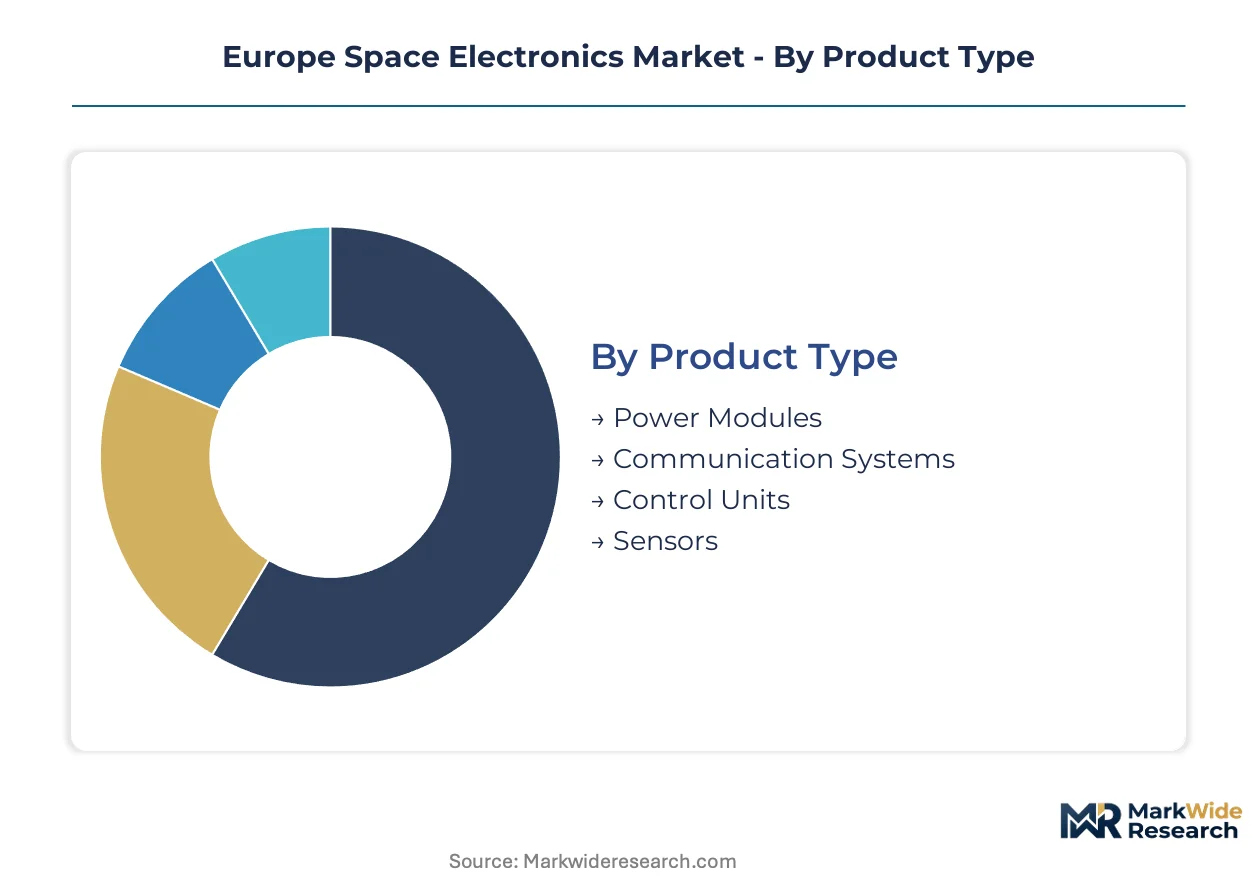
Segmentation in Europe Space Electronics reveals how procurement channels, qualification requirements, and end-use specifications fragment demand across distinct technical tiers. Understanding these divisions exposes where design resources concentrate and where margin structures diverge most sharply.
Product Type:
Channel flows split between prime contractor direct procurement for high-reliability power modules and distributor-mediated purchasing for lower-tier control units and sensors.
- Power Modules:These multi-chip assemblies manage voltage conversion and distribution across satellite bus architectures. Demand concentrates in geostationary and medium Earth orbit platforms where station-keeping electric propulsion systems require high-efficiency switching regulators. Toulouse-based primes source these directly from Grenoble R&D centers to compress qualification timelines.
- Communication Systems:Transceivers, modems, and onboard processing units handling RF signal chains. Mega-constellation operators in the UK and Germany are pulling procurement volumes upward for Ka-band and optical inter-satellite link hardware. REACH compliance for substrate materials extends development cycles by 8-12 months for these high-frequency assemblies.
- Control Units:Command and data handling modules executing flight software instructions. Italian satellite manufacturers in Rome and Milan represent the core demand cluster for these units.
- Sensors:Attitude determination, thermal monitoring, and radiation detection devices. Earth observation programs across France and Germany drive specialized orders for multi-spectral instrument packages.
Power Modules dominate installed base. Communication Systems are where expansion concentrates.
Technology:
Cost tiering separates radiation-hardened foundry processes at premium price points from commercial-off-the-shelf FPGA deployments in cost-constrained constellation programs.
- Radiation-Hardened:Process nodes specifically engineered to withstand total ionizing dose exposures exceeding 100 kilorads. These devices operate across minus 55 to 125 degrees Celsius thermal ranges. French and German government satellite programs mandate these components for mission-critical functions, with qualification protocols extending 18-24 months.
- Nanotechnology:Carbon nanotube interconnects and graphene-based thermal management layers. Research institutions in the Netherlands and Belgium are piloting these materials for next-generation payload miniaturization, though REACH substance restrictions complicate manufacturing scale-up.
- FPGA:Field-programmable gate arrays enabling post-launch reconfiguration of processing functions. Commercial space operators in the UK favor these for constellation flexibility.
- Analog:Discrete signal conditioning and power management circuits. Legacy programs in Italy maintain procurement streams for these mature technologies.
Radiation-Hardened commands premium pricing tiers. FPGA is climbing the fastest as constellation operators prioritize reconfigurability over maximum radiation tolerance.
Application:
Volume concentration tracks the satellite procurement boom, while margin structures favor specialized launch vehicle and deep-space science missions with lower production runs but higher unit values.
- Satellite:Encompasses geostationary communications platforms, navigation constellations, and low Earth orbit broadband arrays. Satellite applications absorb the majority of European power module and transceiver output, with procurement centralizing among three prime contractors in France, Germany, and Italy.
- Launch Vehicle:Avionics for upper-stage guidance, telemetry, and propulsion control. ArianeGroup operations in French Guiana and German manufacturing sites drive demand for these short-mission-duration electronics with severe vibration and acceleration requirements.
- Space Science:Deep-space probes, interplanetary orbiters, and heliophysics missions. ESA programs in the Netherlands coordinate procurement for these extreme-environment components requiring multi-decade operational lifetimes.
- Earth Observation:Dedicated platforms for climate monitoring, agricultural surveillance, and maritime tracking. Copernicus program participation spreads demand across Spanish, German, and Italian instrument manufacturers.
Satellite applications command the largest procurement volumes. Space Science missions represent the steepest expansion trajectory as ESA accelerates outer planets exploration.
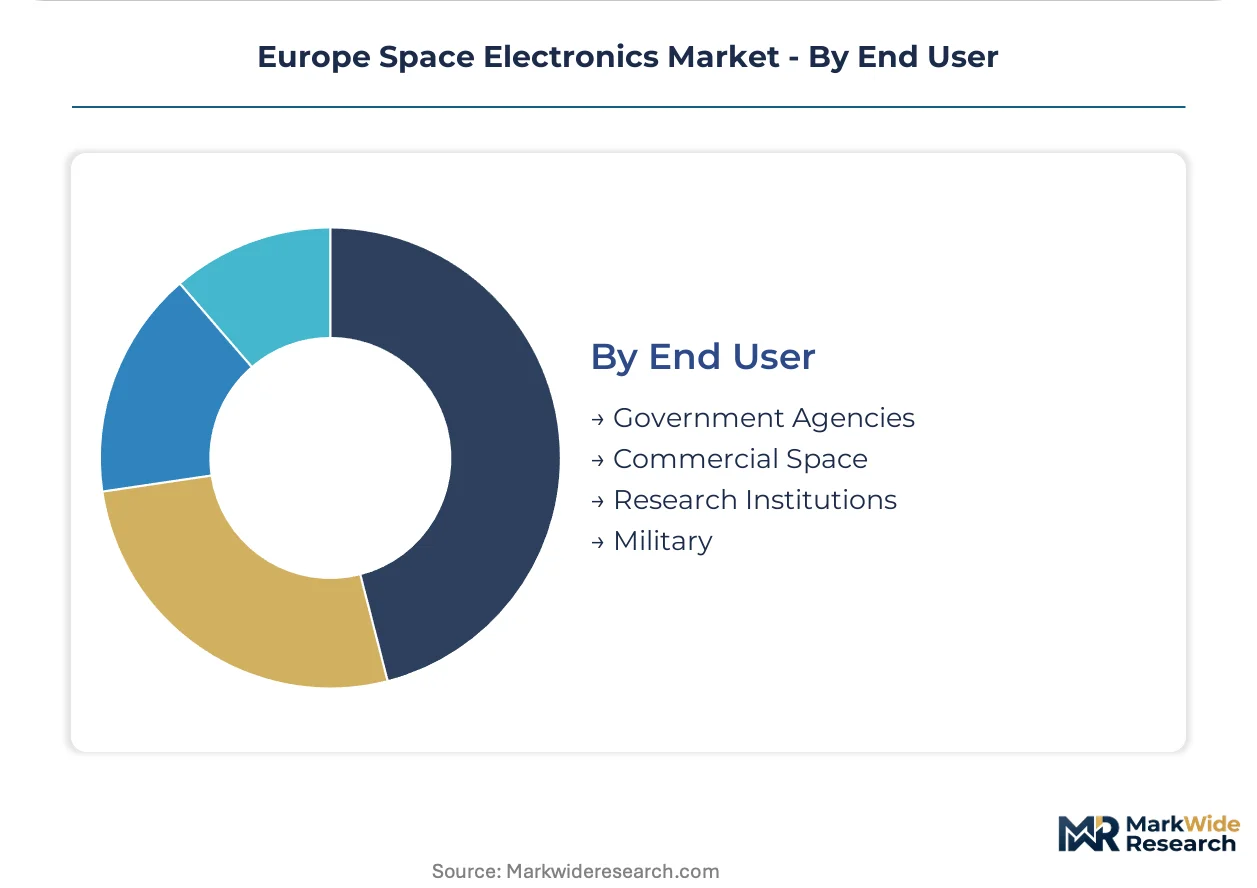
End User:
Customer type determines contracting mechanisms, with government agencies mandating sovereign supply chains and commercial operators optimizing for cost and schedule.
- Government Agencies:ESA member state space agencies and national programs in France, Germany, and Italy. These buyers enforce strict radiation-hardening standards and domestic content requirements, with procurement flowing through established prime contractor relationships.
- Commercial Space:Constellation operators, satellite service providers, and new launch ventures. UK-based broadband constellation developers and German Earth analytics firms are expanding procurement volumes, accepting commercial-grade components where mission profiles permit.
- Research Institutions:University laboratories and ESA technical centers. Dutch and Belgian research organizations drive demand for experimental nanotechnology and novel packaging approaches.
- Military:National defense ministries requiring military-grade radiation tolerance for sovereign satellite payloads. BAE Systems and Thales Alenia Space maintain dedicated supply channels for these classified programs.
Government Agencies anchor the installed base. Commercial Space is where procurement volumes are scaling fastest as constellation deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes space electronics through sovereign satellite programs and launcher avionics, while Germany channels demand toward commercial constellation hardware and automotive-derived power management. Italy maintains distinctive procurement patterns centered on Earth observation platforms and scientific instrumentation.
France
Toulouse-based prime contractors drive procurement for geostationary communications satellites and Ariane launch vehicle electronics. ESA programs administered through CNES enforce radiation-hardening standards exceeding 100 kilorads for mission-critical components. Grenoble anchors European power module R&D, with STMicroelectronics and Thales Alenia Space operating dedicated cleanroom facilities for satellite bus integration.
Germany
Friedrichshafen and Munich host satellite prime contractors procuring electric propulsion power electronics and optical inter-satellite link hardware. The EU Green Deal's carbon-border adjustments pressure Bavarian foundries to document embodied emissions across wafer fabrication. Ottobrunn concentrates design talent for radiation-hardened ASICs serving both government and commercial constellation programs.
Italy
Rome and Milan satellite manufacturers sustain demand for control units and Earth observation instrument electronics. Thales Alenia Space's Turin operations coordinate procurement for Copernicus program participation. REACH compliance timelines extend 8-12 months for high-frequency communication assemblies sourced through Italian supply chains.
United Kingdom
UK-based broadband constellation developers in London and Oxfordshire accept commercial-grade FPGA components where mission profiles permit lower radiation tolerance. The UK Space Agency's national programs maintain sovereign payload requirements through Harwell campus clusters. Scotland's Glasgow region hosts emerging launch vehicle electronics specialists serving European small-satellite markets.
Netherlands
ESA's ESTEC technical center in Noordwijk coordinates deep-space probe procurement requiring multi-decade operational lifetimes. Dutch research institutions pilot carbon nanotube interconnects for payload miniaturization, though ECHA substance restrictions complicate manufacturing scale-up. Delft's aerospace engineering programs feed design talent into radiation-hardened component development across the region.
Europe Space Electronics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer controlling prime contractor relationships and qualification protocols while mid-tier players compete on specific component categories. The structure rewards captive access to ESA and national space agency programs, with barriers rising for new entrants lacking heritage flight data. Two strategic archetypes dominate: vertically integrated European primes with in-house semiconductor capabilities, and fabless specialists relying on qualified foundry partnerships. Competitive moves center on M&A to secure radiation-hardened design talent and strategic partnerships to lock in wafer supply from non-European foundries.
Among Netherlands-based semiconductor specialists, STMicroelectronics N.V. occupies a position exemplifying the integrated archetype through its Grenoble R&D footprint. Thales Group and BAE Systems PLC represent the prime-contractor tier, with the former anchoring French government program relationships and the latter occupying a position within military-grade payload supply chains. These three entities collectively illustrate how geographic proximity to ESA member state agencies shapes competitive positioning across the European market.
| Leading Market Players |
|---|
| STMicroelectronics N.V. |
| Texas Instruments, Inc. |
| Honeywell International, Inc. |
| BAE Systems PLC |
| Thales Group |
| Airbus Defence and Space |
| Eaton Corporation PLC |
| Teledyne Technologies, Inc. |
| TT Electronics PLC |
| Others |
Value Network & Pricing Analysis
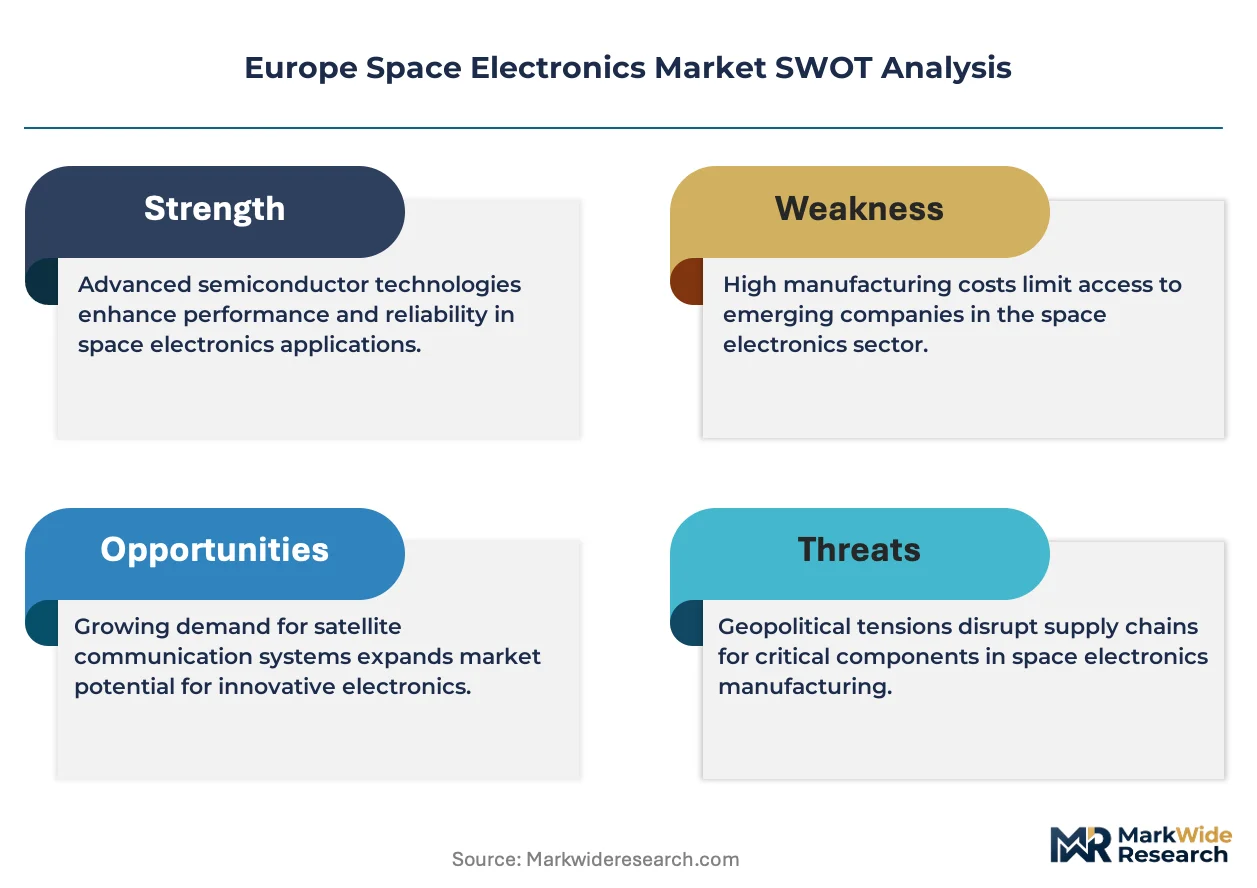
Eighteen-month qualification timelines for radiation-hardened components concentrate pricing power with established European primes holding heritage flight data, while REACH compliance extends development cycles and anchors cost premiums to regulatory documentation burdens rather than pure manufacturing economics.
Pricing Analysis
Long-term offtake agreements dominate procurement for geostationary power modules, with Toulouse-based primes locking multi-year supply commitments to compress qualification schedules. Price differentiation rests on radiation-tolerance certification tiers and sovereign content requirements mandated by CNES and ESA. Cost compression in commercial constellation tiers intensifies as mega-operators benchmark FPGA alternatives against hardened ASICs. Commercial space buyers exhibit highest price sensitivity, accepting commercial-grade components where mission profiles permit lower total ionizing dose thresholds.
Supply Chain Analysis
Strategic stockpiling of specialized ceramic substrates and gold-aluminum wire bonding materials characterizes inventory strategy, given mining supply constraints for these critical inputs. Wafer fabrication concentrates in Taiwan, South Korea, and the United States, with European fabless designers drawing from non-European foundries for radiation-hardened process nodes. Single-source vulnerability around 100-kilorad-qualified process nodes exposes qualification timeline volatility. Distribution runs through prime contractor direct channels for high-reliability tiers, bypassing traditional distributor margins as constellation operators consolidate procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: ESA and national space agency qualification protocols create switching costs measured in years of heritage flight data that new entrants cannot replicate.
For Market Incumbents: Secure radiation-hardened design talent pools in Grenoble and Munich through targeted acquisition of specialist engineering teams, as aerospace-qualified labor scarcity threatens constellation procurement timelines. Deepen backward integration into substrate fabrication to mitigate REACH-driven material substitution risks and capture margin from specialized ceramic supply chains. For New Entrants and Emerging Players: Onboard processing convergence for edge-computing payloads represents the most penetrable service-layer gap, with constellation operators demanding reconfigurable processing units that incumbents under-serve through legacy ASIC architectures. Target UK-based commercial constellation developers with FPGA-based solutions emphasizing post-launch reconfigurability and compressed qualification schedules. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because ESA member state content requirements and dual-use certification complexity erect structural barriers that favor incumbents with established agency relationships. Target acquisition archetypes include fabless specialists holding qualified foundry partnerships and heritage flight data for specific radiation-tolerance bands. The signal to watch is carbon-border adjustment enforcement intensity, which would accelerate foundry requalification toward verified low-emission European sources.| Strategic Initiative | Industry Significance |
|---|---|
| Radiation-Hardened ASIC Qualification | CNES and ESA protocols mandate 100-kilorad tolerance for mission-critical satellite bus functions. |
| System-in-Package Integration | Toulouse primes adopt stacked die configurations to reclaim payload volume for scientific instruments. |
| Carbon-Border Documentation | EU Green Deal pressures Bavarian foundries to verify embodied emissions across wafer fabrication. |
| Eastern European Backend Expansion | Poland and Czech Republic cleanroom capacity offers untapped assembly and test operations. |
| Constellation Procurement Centralization | OneWeb and Amazon Kuiper qualification activities compress distributor margins in power modules. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across satellite prime contractors in Toulouse, Friedrichshafen, and Rome; radiation-hardened component specialists in Grenoble and Ottobrunn; and ESA program managers at ESTEC Noordwijk. Secondary validation drew from ESA procurement databases, REACH substance restriction filings through ECHA, and customs records tracking semiconductor trade flows. Bottom-up segment sizing triangulated against top-down market aggregation across power module, communication system, and control unit categories.
Across the analysis window, projections modeled product type segmentation by qualification tier, technology segmentation by radiation-tolerance band, and application segmentation by mission duration and orbital regime. CAGRs derived from shipment volume trajectories weighted by average selling price evolution within each technical tier. Forecast inputs incorporated constellation deployment schedules from European mega-operator announcements and electric propulsion adoption curves for station-keeping power electronics.
Forecasts assume regulatory continuity in REACH substance restrictions and EU Green Deal carbon-border mechanisms; material policy shifts would require re-modeling foundry qualification economics and substrate material substitution timelines. Revision becomes warranted when non-European foundry capacity constraints for radiation-hardened nodes cross thresholds that extend qualification timelines beyond prime contractor mission schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Colonization Market
Space
Space As a Service Market
Space
Space Ground Station Equipment Market
Space
Spain Space Electronics Market
Space
North America Spacesuit Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space Radar Market
Space
Astronaut Spacesuit Market
Space
Space Ground System Market
Space
France Space Electronics Market
Space
Space in Orbit Refueling Market
Space
Space Transportation Market
Space
Germany Space Electronics Market
Space
Space Propulsion Systems Market
Space
Space-Based Smart Sensors Market
Space
Space Service Market