
 Veterinary Vaccines Market | 2026-2036
Veterinary Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Vaccines Market Intelligence
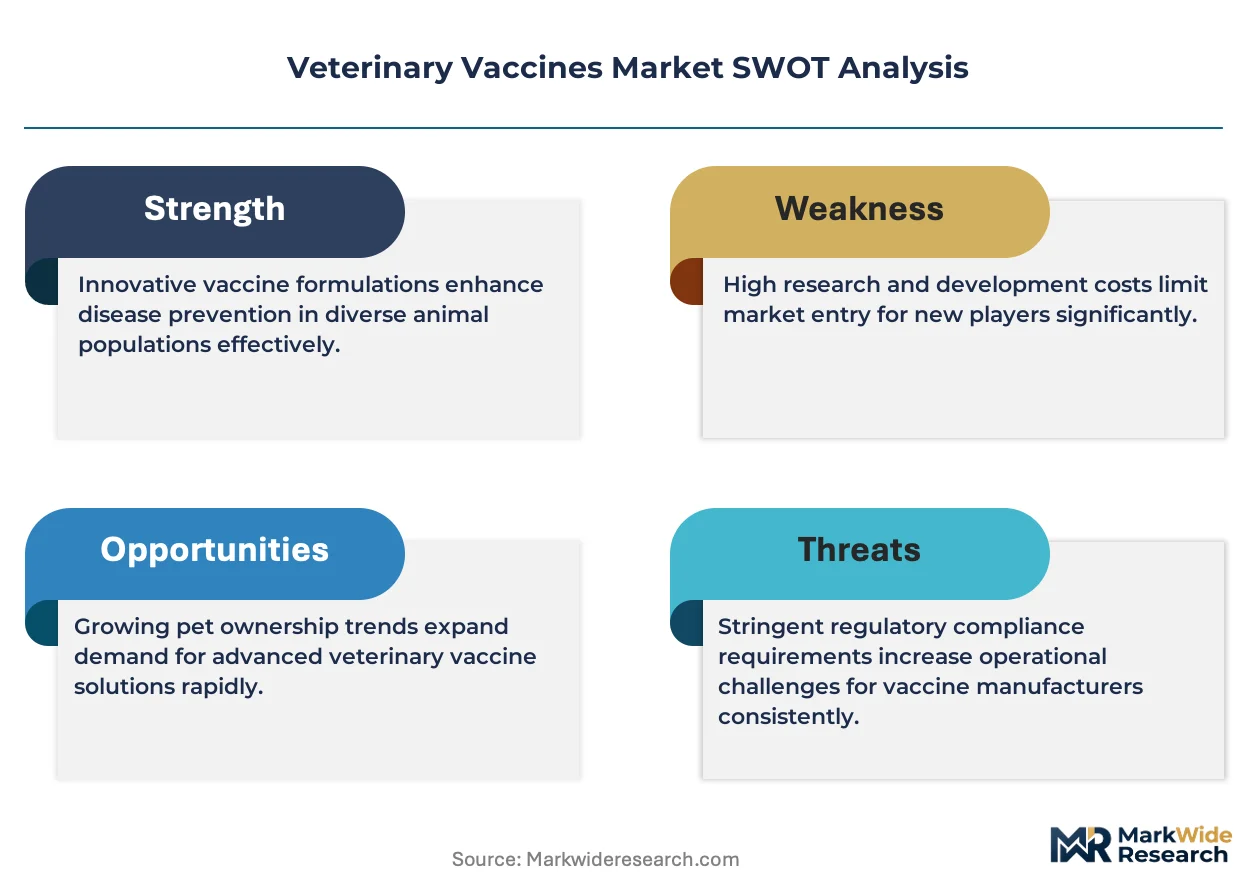
The high capital expenditure required for advanced bioreactors and cold-chain logistics is narrowing the field for new market entrants. Zoetis leverages its extensive global distribution network to reach diverse end-users from large-scale farms to individual clinics. Boehringer Ingelheim Animal Health sustains its competitive edge through substantial R&D investment in next-generation livestock biologics, particularly for swine and bovine health.
Veterinary vaccines are biological preparations that provide active acquired immunity against infectious diseases in animals. These products contain antigens, such as inactivated pathogens or specific subunits, to stimulate a protective immune response without causing disease. The product landscape shows live attenuated vaccines as a mature segment, while novel mRNA vaccines represent a high-growth frontier. Demand in the livestock protection application is high-volume, contrasting with the higher-margin companion animals market.
Market access is governed by stringent regulatory bodies that mandate extensive safety and efficacy trials. The USDA's Center for Veterinary Biologics, the European Medicines Agency (EMA), and Brazil's Ministry of Agriculture, Livestock, and Supply (MAPA) oversee approvals in their respective jurisdictions. Future success for manufacturers depends on navigating the evolving regulatory pathways for novel vaccine technologies like DNA and mRNA platforms.
Market Dynamics
The central dynamic shaping the veterinary vaccines market is the divergence between high-volume, cost-sensitive livestock protection and the high-margin, innovation-driven companion animal health sector. This split influences R&D priorities, distribution models, and regulatory engagement across the industry.
Growth Catalysts
- Food Security Policies:China's national strategy to ensure food self-sufficiency and herd health is mandating large-scale immunization programs for swine, poultry, and cattle, creating sustained, high-volume demand for livestock vaccines.
- Companion Animal Humanization:The increasing treatment of pets as family members drives owner willingness to pay for advanced preventative care, including novel vaccines for non-core diseases and lifestyle-related risks.
- mRNA Vaccine Platforms:The development of mRNA technology offers rapid platform-based vaccine creation, enabling faster responses to emerging infectious diseases in both livestock and companion animals compared to traditional methods.
Market Restraints
- High Capital Expenditure:The significant investment required for cGMP-compliant bioreactors, purification equipment, and uninterrupted cold-chain logistics creates a high barrier to entry for new manufacturers.
- Stringent Regulatory Hurdles:Extensive and costly safety and efficacy trials mandated by agencies like the USDA's Center for Veterinary Biologics and the EMA delay market entry and increase development costs.
- Antigenic Variability:The rapid mutation of pathogens, such as the virus causing avian influenza, requires constant vaccine reformulation and can limit the long-term efficacy of existing products, posing a persistent technical barrier.
Strategic Opportunities
- Aquaculture Biologics:The intensification of fish farming in Southeast Asia presents a largely underpenetrated market for developing vaccines against bacterial and viral diseases specific to aquaculture species like shrimp and tilapia.
- Therapeutic Cancer Vaccines:Advancements in immunology are opening opportunities for therapeutic vaccines that stimulate an animal's immune system to fight certain cancers, a new frontier in companion animal oncology.
- Autogenous Vaccine Services:Offering farm-specific autogenous vaccines, cultured from pathogens isolated directly from a client's herd, provides a high-value, customized solution for diseases not covered by commercial products.
Industry Challenges
- Veterinary Skill Gaps:A shortage of veterinarians and technicians with expertise in advanced immunology, molecular biology, and data analysis hinders the adoption and effective implementation of next-generation vaccine programs in the field.
- Cold-Chain Integrity:Maintaining the required temperature-controlled supply chain for live attenuated and mRNA vaccines to remote agricultural areas remains a significant logistical and financial challenge for distributors.
- Intellectual Property Complexity:Navigating the dense patent landscape surrounding novel adjuvants, viral vectors, and mRNA delivery systems creates legal risks and can complicate licensing agreements for new product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Vaccines Market |
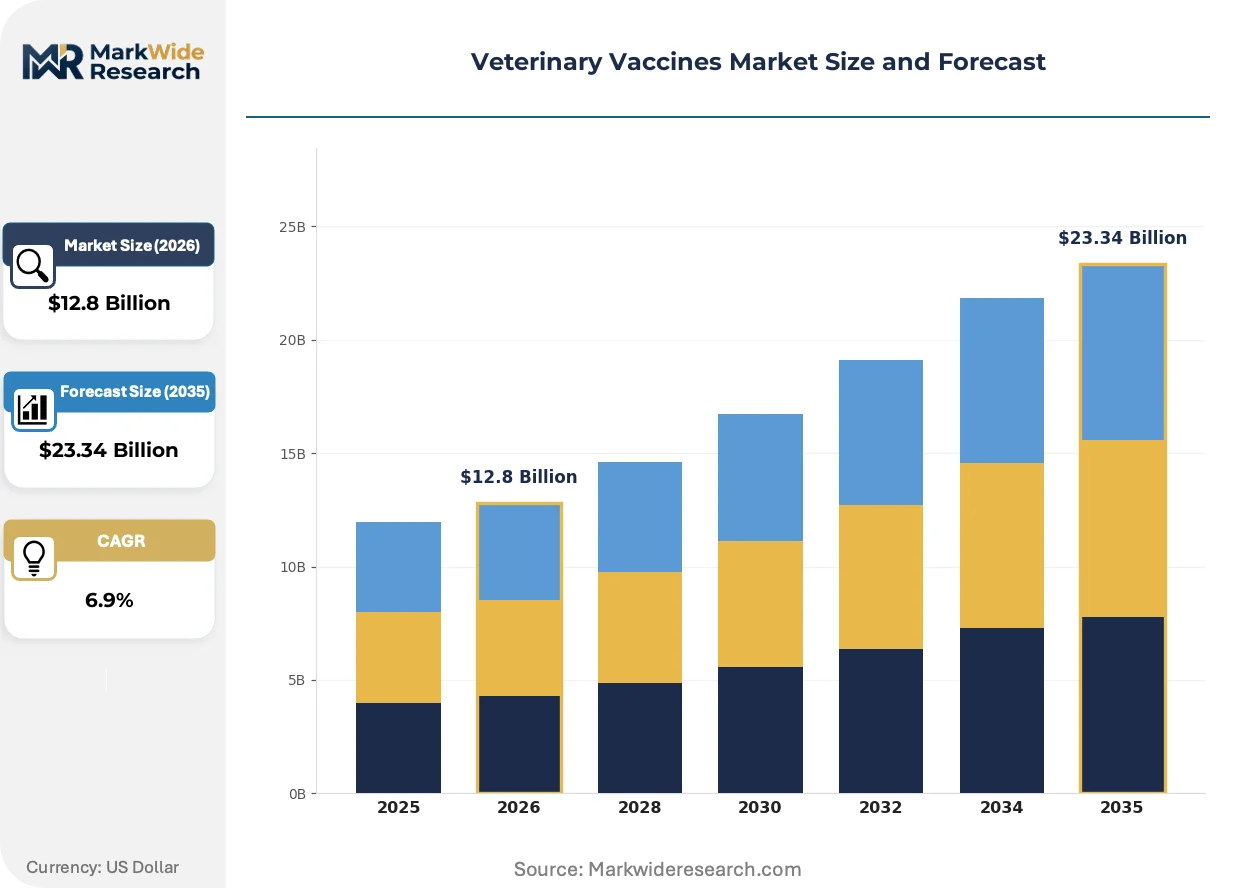
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $23.34 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Subunit, Toxoid, mRNA, DNA Application: Companion Animals, Livestock Protection, Aquaculture, Poultry Immunization, Equine Health End User: Veterinary Clinics, Animal Farms, Research Institutes, Zoos, Wildlife Reserves Delivery Method: Injectable, Oral, Intranasal, Immersion, Aerosol |
| Companies Covered | Zoetis, Boehringer Ingelheim Animal Health, Merck Animal Health, Elanco Animal Health, Ceva Santé Animale, Virbac, Vetoquinol, HIPRA, Phibro Animal Health Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Vaccines Market Strategic Shifts & Innovations
The market's evolution is defined by a shift toward precision and speed. The convergence of genomics, data analytics, and novel biologic platforms is enabling a move from one-size-fits-all prophylaxis to targeted, rapid-response animal health solutions.
Autogenous vaccines, which are derived from pathogens isolated on a specific farm, provide highly targeted immunity. Large-scale swine and poultry producers are increasingly adopting these custom biologics to manage diseases for which no commercial vaccine exists. This bespoke production is hybridizing with rapid genomic sequencing to accelerate pathogen identification, creating more precise and effective herd-specific immunizations.
The European Medicines Agency's (EMA) framework for novel therapies is establishing clearer regulatory pathways for next-generation veterinary biologics. These guidelines specify data requirements for DNA, RNA, and vector-based vaccines, which helps standardize the approval process. The companion animal segment is most impacted, as developers of advanced pet vaccines now have a more predictable and streamlined route to market authorization in Europe.
A transition from direct product sales to integrated health management services is altering vaccine procurement in the commercial livestock sector. Traditional purchasing decisions led by local veterinarians are being augmented by corporate-level agreements through herd management software. These platforms bundle diagnostics, vaccines, and data analytics, a trend most visible in the North American and European swine and dairy industries.
Veterinary Vaccines Market Segmentation
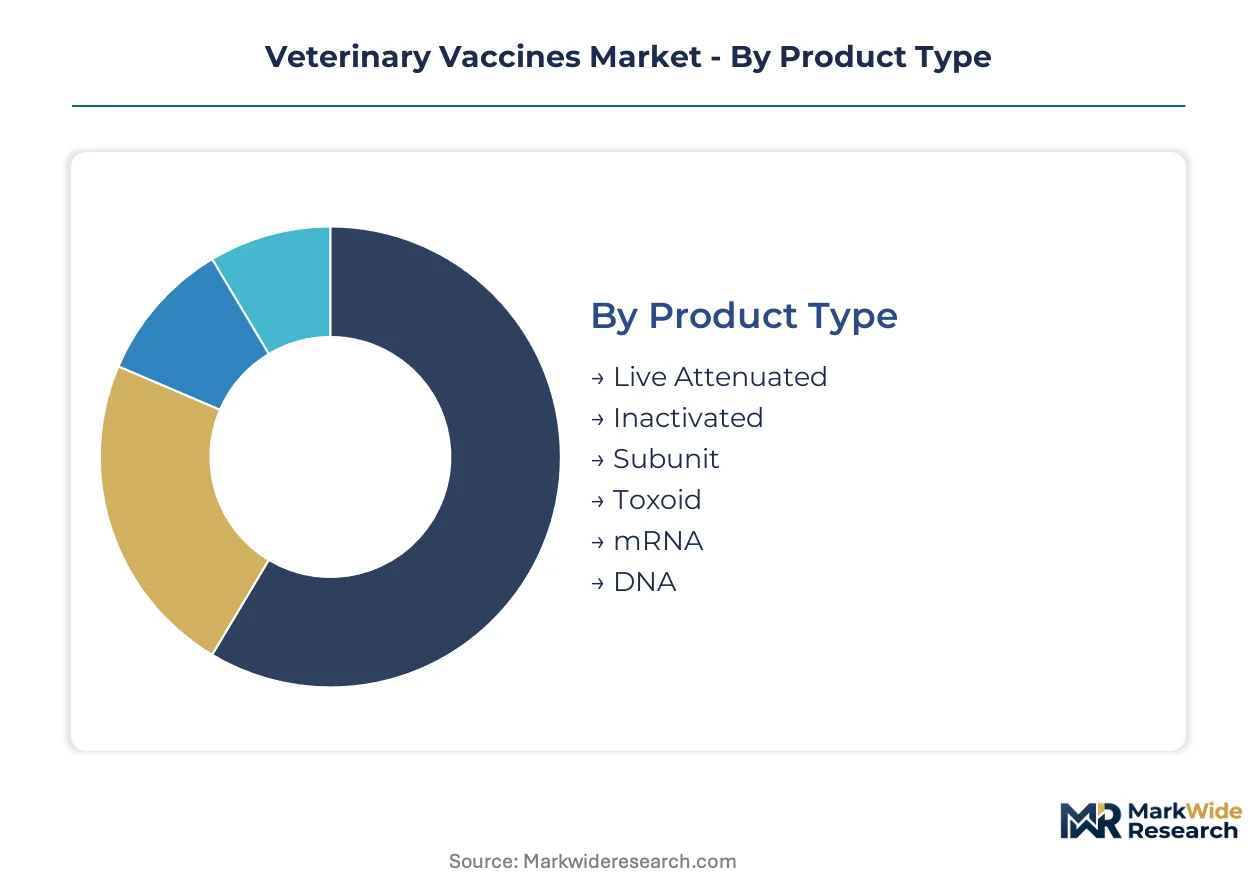
The veterinary vaccines market exhibits diverse segmentation, reflecting varied animal health needs, technological advancements, and operational requirements across different end-user groups. Understanding these segments is crucial for manufacturers to tailor product development, distribution strategies, and regulatory approaches effectively.
Product Type:
The after-sales service intensity varies significantly across vaccine product types, influencing logistics and technical support requirements for end-users.
- mRNA:These novel platforms utilize messenger RNA to instruct host cells to produce antigens, offering rapid development and high specificity for emerging pathogens. Cold-chain integrity and specialized storage are critical for maintaining the stability and efficacy of mRNA vaccines in the field.
- Live Attenuated:These vaccines contain weakened forms of pathogens that stimulate a strong, long-lasting immune response, often requiring fewer doses. Careful handling, refrigeration, and precise administration protocols are essential to ensure viability and prevent reversion to virulence.
- Inactivated:Inactivated vaccines consist of whole pathogens killed by chemical or physical means, providing a safer profile but often requiring booster doses.
- Subunit:Subunit vaccines contain only specific antigenic components of a pathogen, minimizing adverse reactions and simplifying production.
- Toxoid:Toxoid vaccines use inactivated bacterial toxins to induce immunity against the toxins themselves, protecting against diseases like tetanus.
- DNA:DNA vaccines deliver genetic material encoding antigens directly into animal cells, prompting an immune response with high stability and ease of manufacturing.
By volume, Live Attenuated vaccines lead. By growth pace, mRNA vaccines are ahead.
Application:
The volume of vaccine doses required differs significantly across these application areas, dictating production scale and pricing strategies.
- Livestock Protection:This segment includes vaccines for cattle, swine, and poultry, addressing diseases that impact food security and agricultural economics. Large-scale immunization programs, particularly in China, drive high-volume demand.
- Companion Animals:This segment covers vaccines for pets like dogs and cats, focusing on preventative care and emerging non-core diseases. Pet humanization trends in North America and Europe support higher-margin product development.
- Aquaculture:Vaccines for fish and shellfish target bacterial and viral diseases prevalent in intensive farming systems, particularly in Southeast Asia.
- Poultry Immunization:This application focuses on preventing diseases like avian influenza and Newcastle disease in commercial poultry flocks globally.
- Equine Health:Vaccines for horses target specific diseases such as equine influenza, tetanus, and West Nile virus, crucial for performance and leisure animals.
The Aquaculture segment exhibits the fastest expansion.
End User:
Each end user type employs distinct procurement strategies and requires tailored product formulations and support.
- Animal Farms:Large commercial farms, especially in swine and dairy, procure vaccines in bulk, often through corporate agreements that integrate diagnostics and health management software.
- Veterinary Clinics:These facilities serve individual pet owners and small farm operations, purchasing a diverse range of vaccines for companion animals and local livestock.
- Research Institutes:Academic and private research entities utilize veterinary vaccines for studies on immunology, disease models, and vaccine efficacy.
- Zoos:Zoos require specialized vaccines for a wide array of exotic and wild animal species, often involving customized formulations.
- Wildlife Reserves:These organizations use vaccines for population control and disease management in free-ranging wildlife, often via remote delivery methods.
Demand concentration for vaccines is highest within Animal Farms.
Delivery Method:
The choice of delivery method directly impacts vaccine efficacy, animal welfare, and administration logistics.
- Injectable:This traditional method involves administering vaccines via subcutaneous or intramuscular injection, allowing for precise dosing and individual animal treatment. It remains the most common and versatile delivery route across species.
- Oral:Oral vaccines are administered through drinking water or feed, enabling mass vaccination and reducing animal stress and handling requirements. This method is widely used in poultry and swine operations.
- Intranasal:Intranasal vaccines are administered directly into the nasal passages, stimulating local mucosal immunity and offering a needle-free option.
- Immersion:Immersion vaccination involves exposing aquatic animals to vaccine antigens in water, a common method in aquaculture for mass immunization.
- Aerosol:Aerosol delivery involves spraying vaccines into the air, allowing for rapid mass vaccination of large groups of animals, particularly in poultry houses.
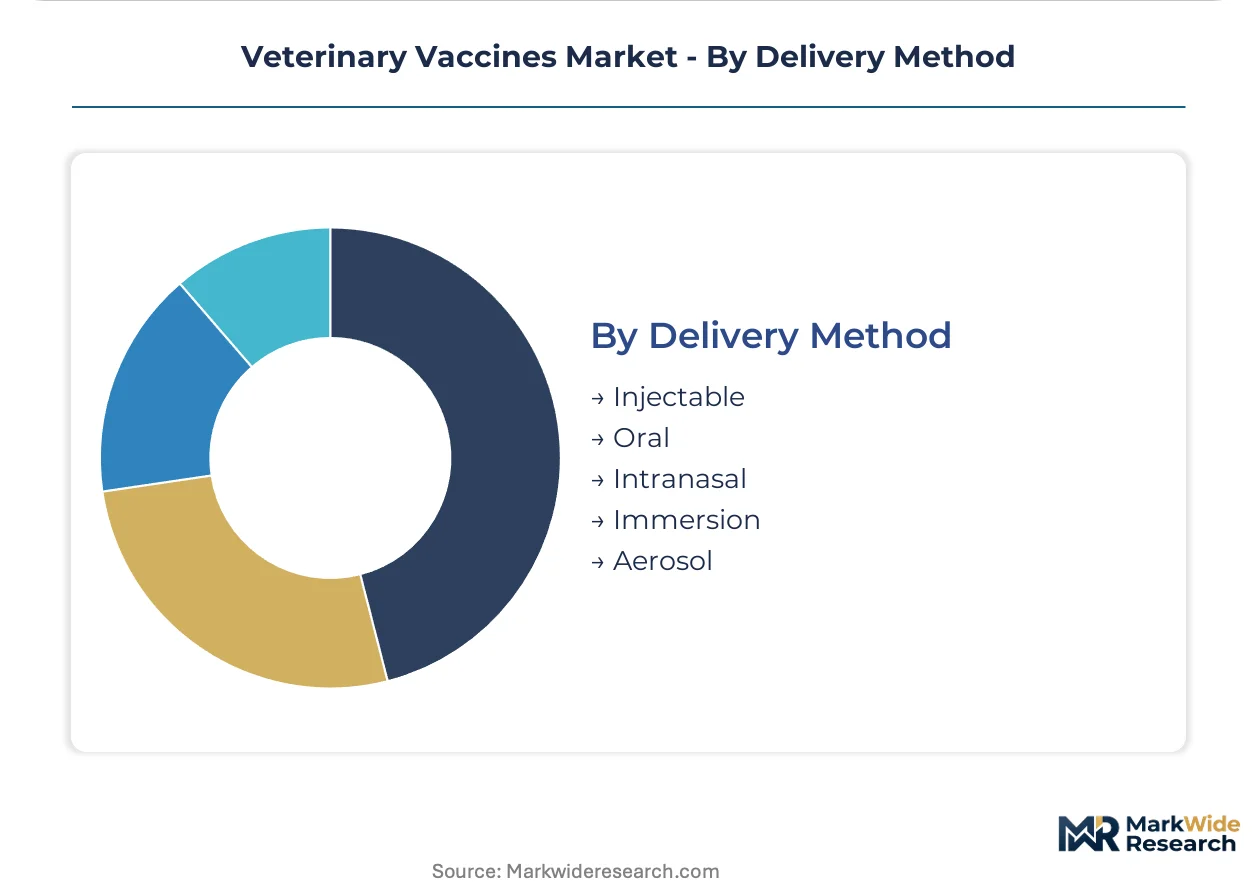
The Injectable method continues to dominate market share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The veterinary vaccines market exhibits diverse buyer-archetype concentrations across key global regions. Commercial animal farms drive high-volume procurement in agricultural powerhouses, while veterinary clinics cater to the high-margin companion animal segment. Research institutes and zoos represent specialized, niche demand for advanced biologics.
United States
United States demand for veterinary vaccines stems from increasing pet humanization and a strong focus on advanced preventative care. The USDA's Center for Veterinary Biologics rigorously regulates product approvals. Biotech clusters in regions like Boston and San Diego actively develop novel mRNA vaccine platforms for pets and livestock.
China
China's national strategy for food self-sufficiency drives immense demand for livestock vaccines, particularly for swine and poultry. The NMPA and national policies enforce large-scale immunization programs. Major agricultural provinces like Henan and Sichuan are central to implementing these extensive animal health initiatives.
Germany
German demand reflects substantial R&D investment in next-generation livestock biologics and advanced companion animal care. The European Medicines Agency (EMA) provides the regulatory framework for market authorization. Pharmaceutical research centers in regions like Bavaria actively develop innovative vaccines for bovine and swine health.
Brazil
Brazil's extensive livestock industry, especially cattle and poultry, generates significant demand for vaccines to control endemic diseases. The Ministry of Agriculture, Livestock, and Supply (MAPA) governs the approval and use of veterinary biologics. Key agricultural states such as Mato Grosso and Rio Grande do Sul serve as crucial hubs for large-scale vaccine procurement.
India
India experiences growing demand from its expanding dairy and poultry sectors, alongside increasing companion animal ownership. The Central Drugs Standard Control Organization (CDSCO) regulates the approval processes for veterinary vaccines. Pharmaceutical manufacturing clusters in Gujarat and Hyderabad are expanding capabilities to meet rising demand for animal health biologics.
Veterinary Vaccines Market Key Industry Players
Channel-controlling players compete with product-specialist players across the veterinary vaccines market. The industry exhibits a tiered structure, with large, diversified animal health companies offering broad portfolios alongside smaller, specialized biotechnology firms. Strategic partnerships for technology licensing and geographic expansion represent common competitive moves among market participants. Portfolio diversification into novel vaccine technologies also shapes competitive positioning.
Leading global players like Zoetis exemplify the integrated approach, leveraging extensive distribution networks to reach diverse end-users from large-scale farms to individual clinics worldwide. This company's global footprint allows for broad market penetration across both livestock and companion animal segments. Boehringer Ingelheim Animal Health occupies a strong position, sustaining its competitive edge through substantial R&D investment in next-generation livestock biologics, particularly for swine and bovine health. Merck Animal Health also represents a significant force within the market, contributing to the development and commercialization of a broad range of veterinary vaccine solutions across different animal segments globally.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim Animal Health |
| Merck Animal Health |
| Elanco Animal Health |
| Ceva Santé Animale |
| Virbac |
| Vetoquinol |
| HIPRA |
| Phibro Animal Health Corporation |
| Others |
Cost & Logistics Intelligence
Bioreactor underutilization in emerging markets creates pricing flexibility for generic vaccine manufacturers, influencing global procurement decisions. High capital expenditure requirements for cGMP facilities also shape the competitive landscape for novel vaccine platforms.
Pricing Analysis
Certification level (USDA, EMA) creates the primary spread in veterinary vaccine pricing. The market operates on a contract-based long-term offtake model for livestock, while companion animal vaccines exhibit value-based pricing. Pricing pressure stems from the high capital expenditure required for cGMP facilities, particularly for novel mRNA platforms. Animal farms are highly price-sensitive, contrasting with companion animal owners who prioritize advanced preventative care.
Supply Chain Analysis
Contract manufacturing concentration in regions like India and China holds significant vaccine production capacity. The supply chain draws from specific raw materials such as cell culture media, adjuvants, and specialized packaging for cold-chain integrity. Single-source vulnerability for certain specialized antigens presents a structural risk to production continuity. Distribution runs through established global networks for large players and regional distributors for smaller firms, often requiring temperature-controlled logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary vaccines market is an early-cycle expansion story, driven by the increasing integration of mRNA platforms for rapid disease response.
For Market Incumbents: Entrench existing market share by investing in cold-chain logistics for remote agricultural areas. Diversify R&D into therapeutic cancer vaccines for companion animals, mitigating the threat from novel biotech firms. Leverage global distribution networks to counter emerging regional players. Secure intellectual property surrounding novel adjuvants and delivery systems.
For New Entrants and Emerging Players: Establish a beachhead in aquaculture biologics, targeting Southeast Asia's underpenetrated fish farming sector. Focus on developing autogenous vaccine services for swine and poultry producers, offering customized solutions for specific farm pathogens. Penetrate the companion animal market with novel vaccines for non-core diseases. Offer high-value, customized solutions for niche applications.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms with integrated health management platforms that bundle diagnostics and vaccines. Long-term viability for this market spans beyond a decade, supported by pet humanization and food security mandates. Acquisition targets include specialized biotech firms with advanced mRNA or DNA vaccine platforms. Watch for regulatory pathway clarity for novel technologies as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop mRNA Vaccine Platforms | Accelerates response to emerging pathogens in livestock and companion animals. |
| Expand Cold-Chain Logistics | Ensures vaccine efficacy and market access to remote agricultural areas globally. |
| Invest in Aquaculture Biologics | Captures growth in the underpenetrated Southeast Asian fish farming sector. |
| Offer Autogenous Vaccine Services | Provides customized, high-value solutions for farm-specific disease challenges. |
| Strengthen Regulatory Affairs Teams | Navigates evolving approval pathways for novel vaccine technologies like DNA platforms. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and rigorous secondary validation. We engaged animal health executives, regulatory affairs leads, large-scale farm managers, and veterinary clinic owners. Secondary sources included USDA, EMA, and MAPA regulatory filings, as well as academic research papers. This bottom-up and top-down triangulation ensured data accuracy and comprehensive market understanding.
Forecast inputs considered historical market performance, technological adoption rates, and regulatory changes across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, delivery method, and regional demand patterns. Compound Annual Growth Rates were derived from a multi-factor regression analysis. Key inputs included pet humanization trends and food security policy impacts on immunization programs.
Macroeconomic conditions sit as an overlay; deviation in global meat consumption or pet ownership rates would shift the trajectory. Forecasts reflect current assumptions regarding pathogen evolution and vaccine efficacy. Quarterly review of disease outbreak patterns and regulatory approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Europe Veterinary Antibiotics Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Global Equine Supplement Products Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Veterinary Consumables Market
Veterinary
Veterinary Biomarkers Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
CBD Pet Market
Veterinary
Animal Drug Compounding Market
Veterinary
Vet Software Market
Veterinary
Otc Pet Medication Market
Veterinary
Global Avian Influenza Vaccines Market
Veterinary
Veterinary Antibiotics Market
Veterinary
Companion Animal Arthritis Market