
 Global Avian Influenza Vaccines Market | 2026-2036
Global Avian Influenza Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Avian Influenza Vaccines Market Foresight
Market Context
Buyer concentration among large integrated poultry producers is shifting procurement toward multi-year supply contracts with vaccine manufacturers. Boehringer Ingelheim International GmbH leverages its recombinant vector platform to serve contract growers across Brazil and Thailand. Zoetis anchors North American supply through dedicated poultry biologicals manufacturing in the US Midwest. Ceva competes in emerging markets with temperature-stable formulations designed for limited cold-chain infrastructure.
Technical and Segment Structure
Avian influenza vaccines are biological preparations containing inactivated or recombinant viral antigens that stimulate mucosal and systemic immunity in gallinaceous birds, with hemagglutinin inhibition titers serving as the standard efficacy correlate. These products primarily protect commercial poultry flocks against notifiable highly pathogenic avian influenza subtypes, thereby safeguarding protein supply chains and enabling trade continuity under OIE guidelines. Inactivated vaccines occupy the largest revenue share due to established regulatory pathways and broad strain coverage, while recombinant platforms represent the fastest-expanding category as vector technology permits DIVA-compatible differentiation between infected and vaccinated animals. Layer operations generate premium pricing relative to broiler applications because longer production cycles justify higher per-dose investment for sustained protection across multiple laying periods.
Regulatory Environment
USDA APHIS controls market access through strain-specific licensing and national stockpile procurement protocols, while OIE standards shape international trade acceptance of vaccinated-versus-infected serological distinctions. EMA and national regulators across France, Germany, and the Netherlands enforce batch-release testing that elevates manufacturing compliance costs for suppliers seeking European market entry. Stakeholders must monitor strain drift surveillance networks and preemptive regulatory pathway negotiations for pandemic preparedness stockpiling commitments.
Market Dynamics
Recombinant vector platforms are compressing qualification timelines for differentiated avian influenza vaccines, forcing manufacturers to reconfigure R&D pipelines around DIVA-compatible serological distinction capabilities demanded by trade authorities.
Growth Catalysts
- USDA APHIS Stockpile Mandates:National poultry reserve procurement protocols in the United States are creating guaranteed offtake volumes for licensed manufacturers, de-risking capacity investments.
- Layer Operation Cycle Extension:Extended production periods in egg-laying facilities across Vietnam and Indonesia justify premium per-dose spending for sustained hemagglutinin inhibition titers.
- CRISPR-Assisted Strain Surveillance:Genomic tracking networks are accelerating antigenic drift detection, enabling faster seed strain updates for vaccine matching.
Market Restraints
- Embryonated Egg Supply Concentration:Inactivated vaccine production remains tethered to specific-pathogen-free egg supply chains concentrated in the US Southeast and Brazil, creating input vulnerability.
- EMA Batch-Release Testing Burden:European Medicines Agency lot verification protocols add 4-6 weeks to release timelines, elevating working capital requirements for EU market entry.
- Antigenic Drift Uncertainty:H5N1 clade diversification outpaces regulatory approval cycles, forcing manufacturers to maintain parallel seed strain development programs.
Strategic Opportunities
- Bangladesh Backyard-to-Commercial Transition:Biosecurity investments in rapidly consolidating poultry operations create first-mover advantage for temperature-stable formulation suppliers.
- Cell Culture Platform Migration:Suspension-based production technologies are converging with recombinant platforms to eliminate embryonated egg dependencies entirely.
- OIE Trade Facilitation Standards:International harmonization of vaccinated-versus-infected animal serological protocols is opening previously restricted export markets for compliant products.
Industry Challenges
- Regulatory Pathway Parallelism:Manufacturers must simultaneously navigate strain-specific licensing with USDA APHIS, national equivalence determinations with OIE, and divergent batch-release standards with EMA and Health Canada.
- Cold-Chain Infrastructure Gaps:Last-mile distribution in Indonesian archipelago operations and Bangladesh rural networks requires reformulation investments or captive logistics buildout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Avian Influenza Vaccines Market |
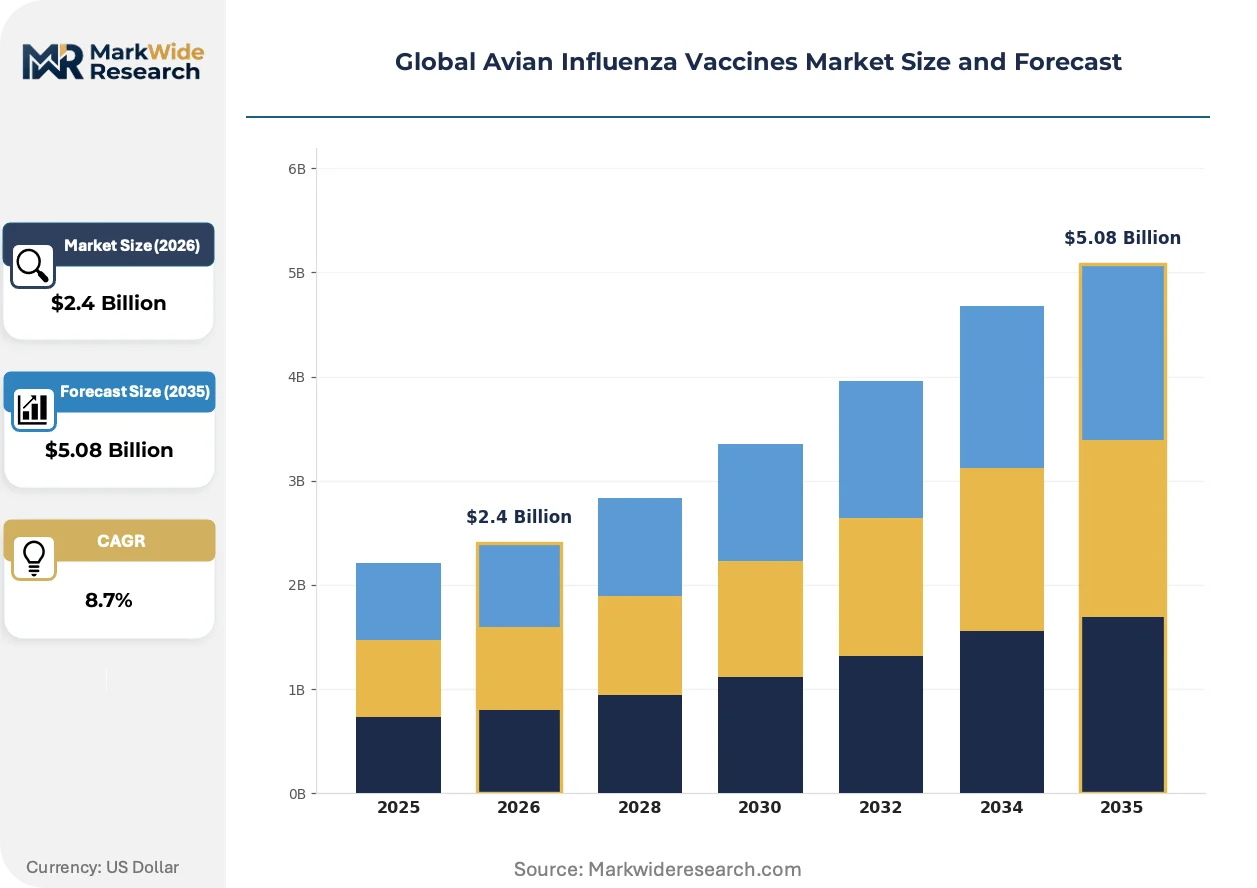
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Inactivated, Recombinant, Live Attenuated, Subunit, DNA Target Species: Broilers, Layers, Turkeys, Ducks, Quails Administration Route: Intramuscular, Subcutaneous, Oral, Intranasal, Spray End User: Poultry Farms, Veterinary Clinics, Research Institutes, Vaccine Manufacturers |
| Companies Covered | Sanofi, Boehringer Ingelheim International GmbH, Zoetis, Elanco, Ceva, HIPRA, Merck Animal Health, Phibro Animal Health Corporation, YEBIO BIOENGINEERING CO., LTD OF QINGDAO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Avian Influenza Vaccines Market Shifts & Advancements
Digital traceability systems and synthetic biology tools are converging to compress vaccine development cycles while enabling real-time antigenic matching against circulating field strains.
Recombinant herpesvirus of turkey vector technology is automating the insertion of multiple hemagglutinin genes into single-dose formulations. Large integrated producers in Thailand and Brazil are adopting these platforms at commercial scale during 2024-2025 production cycles. This automation is compressing the traditional multi-strain blending process into unified vector delivery, reducing manufacturing complexity and enabling faster response to clade emergence.
EU Green Deal sustainability disclosure requirements are mandating carbon footprint reporting across veterinary pharmaceutical supply chains. EMA guidance now requires lifecycle assessment documentation for manufacturing site licensing renewals. European poultry vaccine procurement specifications are beginning to incorporate environmental criteria, favoring suppliers with validated low-emission production processes.
Buyer consortium formation among Southeast Asian layer cooperatives is consolidating purchasing power and demanding multi-year supply guarantees with price ceilings. Traditional distributor networks in Vietnam and Indonesia are being disintermediated by direct manufacturer-to-farm contracts supported by technical service teams. This pattern is most visible in the Mekong Delta region, where integrated operations now account for majority procurement volume.
Global Avian Influenza Vaccines Market Segmentation
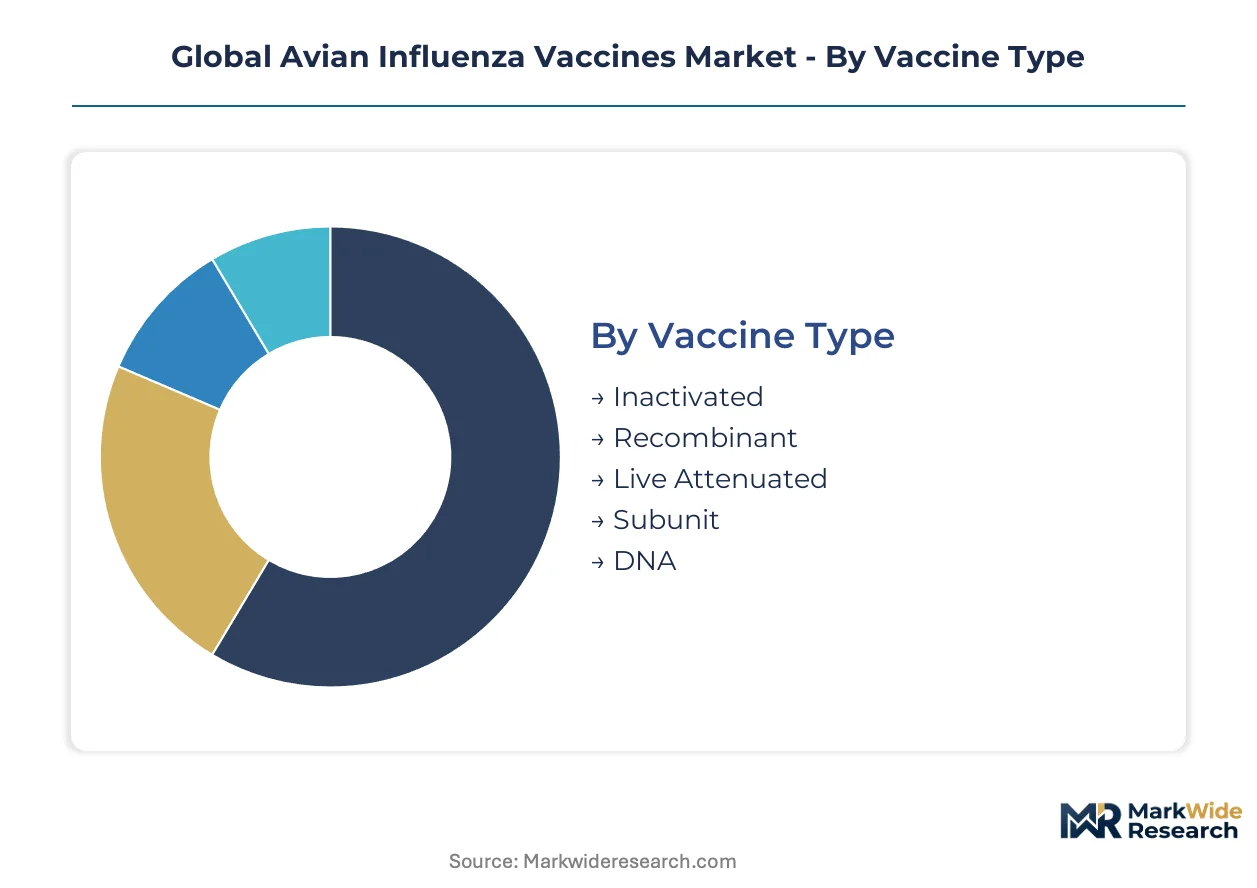
Avian influenza vaccine segmentation reveals distinct regulatory pathways and technical specifications that determine manufacturing investment priorities. Each dimension carries unique certification burdens from USDA APHIS, EMA, and OIE that shape commercial viability across production platforms.
Vaccine Type:
USDA APHIS licensing requirements vary sharply across platform technologies, with inactivated vaccines facing established strain-specific pathways while recombinant vectors navigate novel DIVA-compatible validation protocols.
- Inactivated:Whole-virus preparations inactivated by formalin or beta-propiolactone retain complete hemagglutinin and neuraminidase antigenicity. Demand concentrates in large integrated layer operations across Vietnam and Indonesia where extended production cycles justify premium dosing schedules amid H5N1 clade diversity.
- Recombinant:Viral vector platforms utilizing herpesvirus of turkey or fowlpox backbone enable serological differentiation between infected and vaccinated animals. Brazilian and Thai contract growers are accelerating procurement of these platforms to satisfy OIE trade facilitation standards for export-oriented production.
- Live Attenuated:Temperature-sensitive mutants with restricted replication capacity require specialized cold-chain infrastructure and carry heightened biosafety containment obligations.
- Subunit:Purified hemagglutinin protein formulations eliminate whole-virus safety concerns but demand adjuvant optimization for mucosal immunity induction.
- DNA:Plasmid-based nucleic acid vaccines remain experimental with limited regulatory precedent for avian applications outside research protocols.
Inactivated vaccines sit at the top of the volume ranking, with recombinant platforms climbing the fastest.
Target Species:
Species-specific formulation requirements drive antigen dose optimization and adjuvant selection, with layer and broiler applications commanding divergent per-dose economics based on production cycle duration.
- Layers:Extended 60-80 week production cycles in egg-laying facilities necessitate sustained hemagglutinin inhibition titers through multiple laying periods. Vietnamese Mekong Delta cooperatives are consolidating procurement power for multi-year supply contracts with technical service guarantees.
- Broilers:Short 35-42 day grow-out periods prioritize rapid onset of immunity with cost-minimized dosing schedules. Brazilian integrated producers favor mass administration methods compatible with high-throughput processing.
- Turkeys:Susceptibility to both H5 and H7 subtypes drives demand for broad-spectrum coverage in North American breeding operations.
- Ducks:Reservoir species status for influenza A viruses creates unique regulatory surveillance requirements in Southeast Asian wetland farming systems.
- Quails:Niche commercial scale limits dedicated formulation development, with off-label broiler adaptations filling supply gaps.
Layers command the highest per-dose price realization, with ducks representing the most constrained supply availability.
Administration Route:
Route selection determines equipment capital requirements and labor intensity, with mass administration methods favored in high-density operations and precision delivery reserved for breeding stock and research applications.
- Intramuscular:Needle-based injection into breast muscle ensures precise antigen deposition and reliable seroconversion. Indonesian commercial farms with trained vaccination crews maintain this as standard for parent stock and high-value layers.
- Subcutaneous:Neck region administration reduces muscle damage concerns in premium meat bird categories. Bangladesh backyard-to-commercial transition operations are adopting this route as biosecurity investments professionalize handling protocols.
- Oral:Drinking water or feed incorporation enables flock-scale administration without individual handling but suffers variable intake consistency.
- Intranasal:Drop or aerosol delivery targets mucosal immunity induction at virus entry portals, favored in challenge studies and experimental protocols.
- Spray:Cabinet or house-level aerosolization supports day-old chick priming in hatchery-integrated operations with controlled environment infrastructure.
Intramuscular delivery retains dominant procedure frequency, with spray administration gaining adoption fastest in hatchery-consolidated supply chains.
End User:
End-user category determines procurement scale, technical support expectations, and regulatory documentation requirements, with direct manufacturer relationships displacing traditional distributor networks in concentrated production regions.
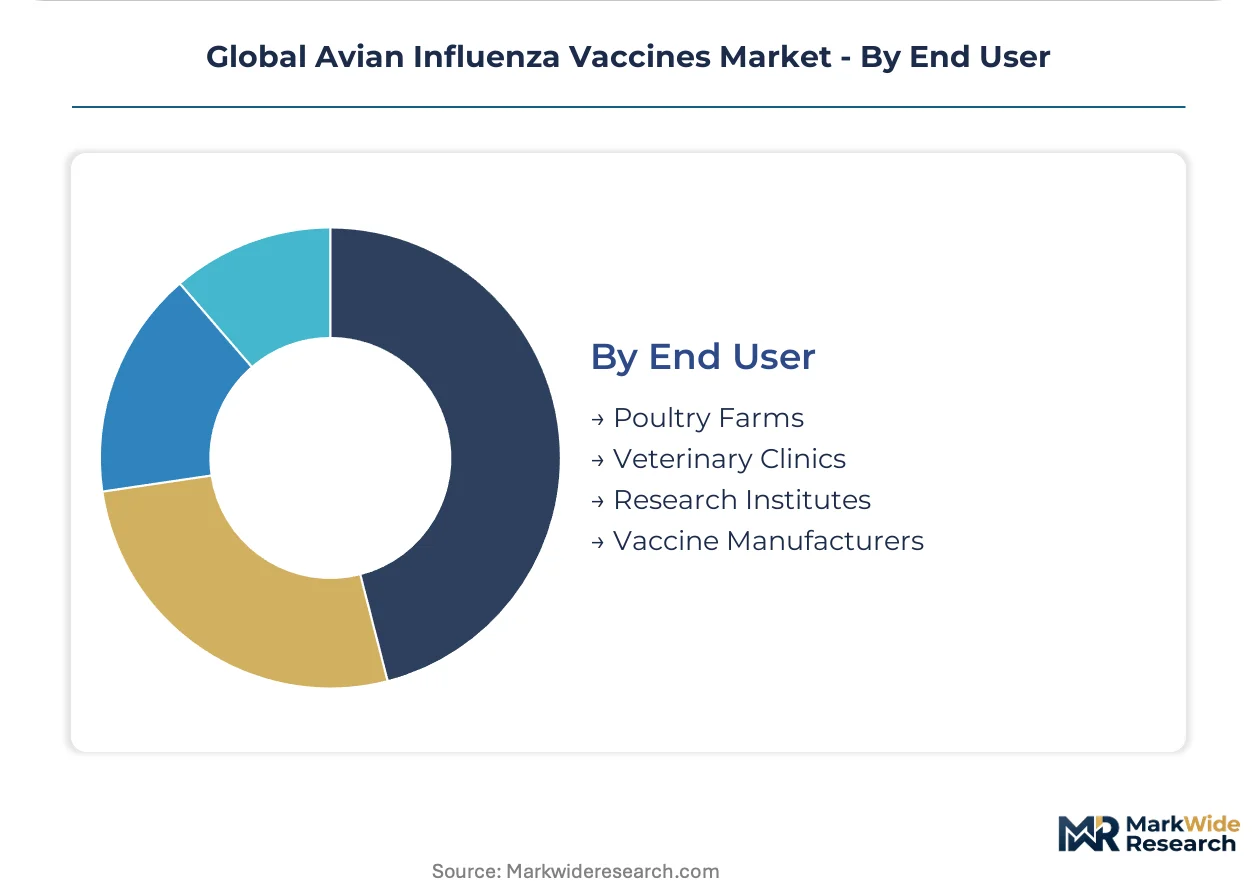
- Poultry Farms:Commercial operations from backyard transitions to integrated multinationals constitute primary demand volume. Direct manufacturer contracting with embedded technical service teams is disintermediating traditional distributors across Vietnam and Indonesia.
- Veterinary Clinics:Diagnostic and therapeutic service providers administer vaccines in smaller-scale or specialty operations requiring individualized health protocols.
- Research Institutes:Academic and government facilities drive seed strain development and challenge study validation for regulatory submission packages.
- Vaccine Manufacturers:Bulk antigen and adjuvant procurement for formulation blending and private-label production creates upstream supply relationships.
Poultry farms absorb the majority of procurement volume, with vaccine manufacturers representing the most concentrated buyer bargaining power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Mekong Delta layer cooperatives outspend Indonesian backyard operations on per-dose biosecurity investments, while Bangladesh's commercial transition creates divergent cold-chain infrastructure requirements across South Asian poultry belts.
United States
USDA APHIS stockpile procurement protocols guarantee offtake volumes for licensed recombinant vaccine manufacturers, de-risking capacity investments in the Midwest poultry biologicals corridor. National poultry reserve mandates accelerate qualification timelines for DIVA-compatible platforms. Georgia and Arkansas integrated operations anchor North American demand concentration.
Brazil
Contract growers across São Paulo and Paraná states prioritize export-oriented recombinant vector procurement to satisfy OIE trade facilitation standards. ANVISA regulatory alignment with international serological protocols enables vaccinated-versus-infected animal distinction for global protein shipments. Southern Brazil's hatchery-consolidated supply chains drive spray administration adoption at commercial scale.
Vietnam
Mekong Delta layer cooperatives consolidate multi-year supply contracts with embedded technical service guarantees, displacing traditional distributor networks. National biosecurity directives mandate enhanced surveillance protocols amid H5N1 clade diversification pressures. Commercial farm transitions in Long An and Tien Giang provinces intensify temperature-stable formulation demand.
Germany
EMA batch-release testing protocols add four to six weeks to vaccine lot verification timelines, elevating working capital requirements for EU market entry. EU Green Deal sustainability disclosure mandates now require lifecycle assessment documentation for manufacturing site licensing renewals. Lower Saxony's dense poultry production clusters face heightened environmental compliance integration in procurement specifications.
Bangladesh
Backyard-to-commercial farm transitions in Rajshahi and Khulna divisions create first-mover positioning for suppliers with limited cold-chain infrastructure capabilities. National poultry biosecurity investment programs professionalize handling protocols and subcutaneous administration adoption. Rural distribution networks demand reformulation investments or captive logistics buildout across deltaic wetland farming systems.
Global Avian Influenza Vaccines Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across platform technology boundaries, creating a tiered structure where recombinant vector capabilities separate premium positioning from commodity inactivated vaccine supply. Consolidation concentrates among entities with USDA APHIS strain-specific licensing and OIE equivalence determinations. Three archetypes dominate: integrated animal health conglomerates with multi-species biologicals portfolios, poultry-focused specialists with dedicated manufacturing infrastructure, and emerging platform technology licensors from Asia-Pacific markets. Capacity expansion and geographic direct-contracting displace traditional distribution networks as primary competitive moves.
Within the recombinant vector tier, Boehringer Ingelheim International GmbH exemplifies European-based platform specialization, while Zoetis anchors North American supply concentration through dedicated poultry biologicals manufacturing. Ceva occupies a position representing temperature-stable formulation capabilities designed for emerging market infrastructure constraints.
| Leading Market Players |
|---|
| Sanofi |
| Boehringer Ingelheim International GmbH |
| Zoetis |
| Elanco |
| Ceva |
| HIPRA |
| Merck Animal Health |
| Phibro Animal Health Corporation |
| YEBIO BIOENGINEERING CO., LTD OF QINGDAO |
| Others |
Supply & Pricing Matrix
Specific-pathogen-free egg costs cascade through inactivated vaccine manufacturing tiers, with embryonated egg supply concentration in the US Southeast and Brazil elevating input pricing floors for premium formulations while recombinant platforms escape this dependency through cell culture migration. Layer operations across Vietnam and Indonesia absorb elevated per-dose costs through multi-year contract structures, whereas Bangladesh backyard-to-commercial transitions face working capital constraints that compress procurement toward economy-tier options.
Pricing Analysis
Capacity additions in Brazil and Thailand are reshaping price floors for recombinant vector platforms as contract growers consolidate procurement power through direct manufacturer relationships. Pricing stratifies across premium DIVA-compatible formulations, standard inactivated multi-strain blends, and economy-tier single-clade options, with USDA APHIS licensing tier and OIE equivalence status serving as primary differentiation markers. Cost compression in standard-tier supply stems from buyer consortium formation among Southeast Asian cooperatives demanding price ceilings. Broiler operations in Brazil exhibit highest price sensitivity due to compressed grow-out cycles, while Vietnamese layer cooperatives tolerate premium positioning for sustained hemagglutinin inhibition coverage.
Supply Chain Analysis
Domestic-content mandates in Vietnam and Indonesia are reshaping sourcing patterns, with national biosecurity directives requiring local technical service embedding and cold-chain infrastructure investment as procurement conditions. Manufacturing concentration centers on the US Midwest, Germany, and Brazil, with upstream supply drawing from specific-pathogen-free egg farms, recombinant vector seed banks, and adjuvant chemical processors. Single-source vulnerability persists in embryonated egg supply chains concentrated in Georgia and Arkansas production clusters. Distribution runs through direct manufacturer-to-farm contracts in consolidated production regions, with traditional distributor networks retained only in fragmented backyard transition zones across Bangladesh and rural Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where USDA APHIS stockpile procurement protocols and OIE trade facilitation standards create demand ratchets that outpace pure volume growth, with each regulatory milestone expanding the addressable market for compliant manufacturers.
For Market Incumbents: To counter recombinant platform displacement of inactivated vaccine share, Boehringer Ingelheim and Zoetis should deepen backward integration into cell culture substrate production and secure captive supply of specific-pathogen-free egg alternatives. Priority defensive moves include capacity expansion in Brazil to serve ANVISA-aligned export demand and certification investment for EU Green Deal sustainability disclosure compliance.
For New Entrants and Emerging Players: The price-point gap between premium recombinant platforms and economy inactivated formulations creates white-space opportunity for mid-tier suppliers offering temperature-stable formulations with partial DIVA compatibility. Bangladesh backyard-to-commercial transition zones and Indonesian archipelago operations represent most penetrable geographies due to cold-chain infrastructure gaps. Go-to-market execution should emphasize technical service team embedding and direct farm contracting to disintermediate legacy distributor networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where USDA APHIS strain-specific licensing and OIE equivalence determinations create regulatory moats that favor scaled incumbents over fragmented regional suppliers. Long-term viability favors platform technology licensors with recombinant vector capabilities and emerging market formulation expertise. Acquisition target archetype: mid-tier manufacturers with temperature-stable portfolios and established direct-contracting relationships in Vietnam or Indonesia. Signal to watch: CRISPR-assisted strain surveillance network expansion accelerating antigenic drift detection and seed strain update frequency.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell Culture Platform Migration | Suspension-based production eliminates embryonated egg dependencies and compresses qualification timelines for recombinant vaccines. |
| Temperature-Stable Formulation Development | Ceva's investment in limited cold-chain infrastructure compatibility captures Bangladesh and Indonesian archipelago procurement volumes. |
| Direct Manufacturer-to-Farm Contracting | Zoetis and Boehringer Ingelheim disintermediate Vietnamese distributor networks through embedded technical service teams. |
| DIVA-Compatible Serological Validation | USDA APHIS and OIE alignment on vaccinated-versus-infected animal distinction unlocks export-oriented Brazilian contract grower demand. |
| EU Green Deal Compliance Certification | EMA lifecycle assessment documentation requirements favor suppliers with validated low-emission manufacturing processes in European procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vaccine manufacturing executives, USDA APHIS regulatory affairs specialists, layer cooperative procurement managers, and veterinary biologics distribution channel partners with secondary validation against OIE strain surveillance databases, USDA strain-specific licensing records, EMA batch-release protocols, and national poultry biosecurity directive filings. Bottom-up demand modeling across vaccine type, target species, and administration route segments triangulated with top-down market sizing anchored to stockpile procurement disclosures and commercial contract announcements.
Comparable-period anchoring linked projection assumptions to historical reference windows spanning pre-pandemic baseline, H5N1 clade diversification acceleration, and recombinant platform commercialization phases. Segmentation dimensions modeled encompassed vaccine platform technology, target species production cycle economics, administration route equipment requirements, and end-user procurement scale categories. CAGRs derived from slope-consistency checks against strain emergence frequency, regulatory approval velocity, and cold-chain infrastructure investment trajectories. Industry-specific inputs included hemagglutinin inhibition titer durability data and DIVA serological protocol adoption rates across OIE member states.
Caveats apply where antigenic drift uncertainty outpaces seed strain development cycles or where EMA batch-release testing timeline extensions materially alter working capital requirements for EU market entry. Forecasts reflect assumptions regarding continued USDA APHIS stockpile procurement continuity, OIE trade facilitation standard harmonization velocity, and Southeast Asian layer cooperative consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
North America and Europe Veterinary Telehealth Market
Veterinary
Veterinary Anesthesia Drugs Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Vet Software Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Veterinary Excipients Market
Veterinary
Europe Veterinarians Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Europe Dog Dewormers Market
Veterinary
Global Cattle Vaccines Market
Veterinary
France Veterinary Healthcare Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Animal Microchip Implant Market
Veterinary
Canine Flu Therapeutics Market