
 Veterinary Biomarkers Market | 2026-2036
Veterinary Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Biomarkers Market Intelligence
A shift from single-source antibody suppliers toward multi-source reagent partnerships is hardening across the veterinary biomarkers supply base. Zoetis leverages captive biologics manufacturing to secure assay consistency across companion animal diagnostics. IDEXX Laboratories anchors its competitive position through vertically integrated reference laboratory networks in North America and Europe. Thermo Fisher Scientific extends its presence by supplying mass spectrometry platforms to third-party veterinary test developers.
Veterinary biomarkers are measurable biological indicators—proteins, nucleic acids, or metabolites—extracted from blood, urine, or tissue samples to detect disease states, physiological stress, or drug responses in animals, typically quantified via immunoassay sensitivity thresholds or mass spectrometry resolution parameters. Their primary purpose is to enable objective, early-stage disease identification in livestock and companion animals where clinical symptoms remain latent. Proteomic technology platforms command the deepest margin pools due to antibody development complexity and recurring reagent consumption. Diagnostics applications lead volume adoption as veterinary clinics replace empirical treatment protocols with evidence-based panels. Research applications represent the fastest-growing segment as pharmaceutical sponsors integrate biomarker endpoints into veterinary drug trials.
FDA Center for Veterinary Medicine oversees diagnostic kit approvals and labeling claims, while USDA Animal and Plant Health Inspection Service regulates livestock disease surveillance assays used in interstate commerce. ISO 17025 accreditation requirements for veterinary testing laboratories are expanding from human diagnostics into animal health, raising capital barriers for new entrants. Stakeholders must monitor how evolving regulatory harmonization between FDA and EMA veterinary pathways reshapes product registration strategies and geographic launch sequencing.
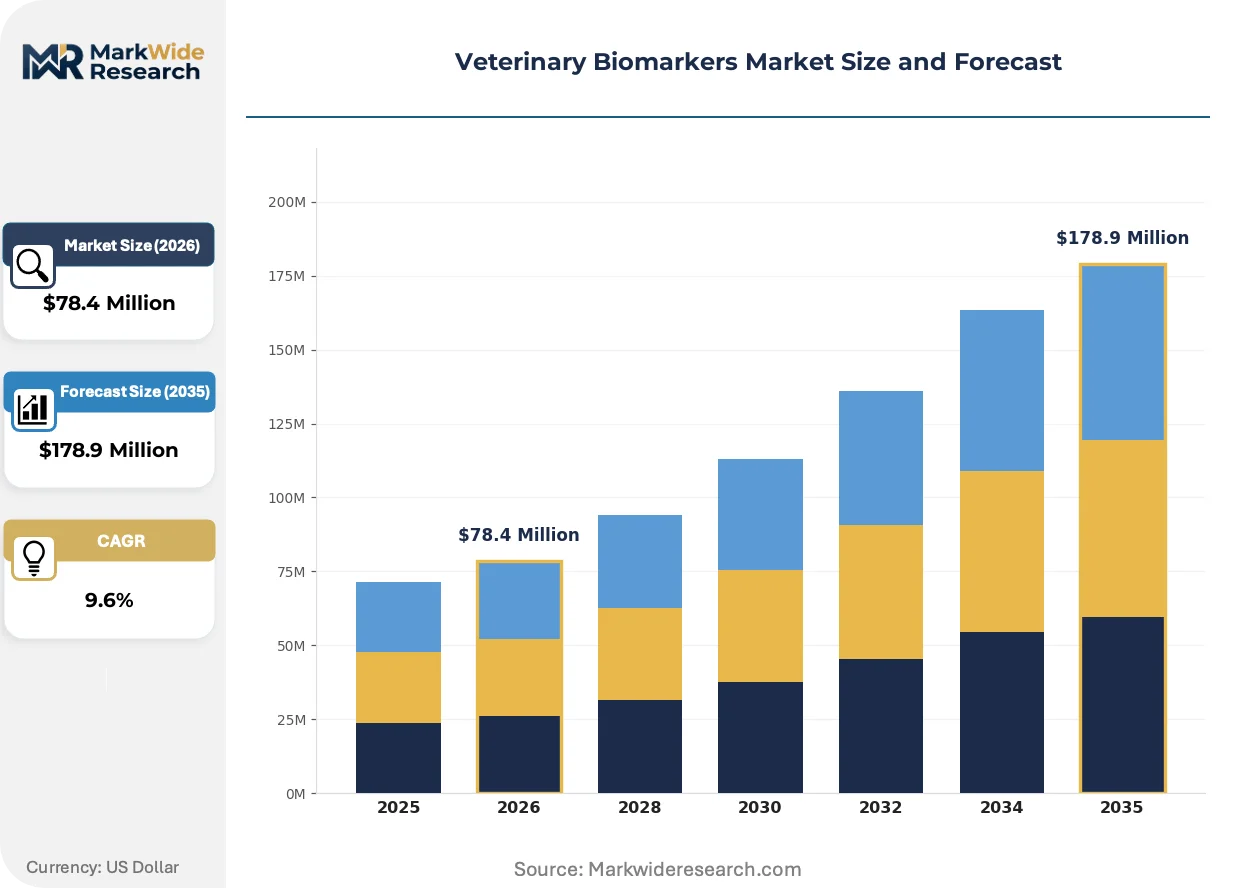
Market Dynamics
Veterinary biomarker development is hardening around ISO 17025 laboratory accreditation requirements, which are compressing assay validation timelines and raising capital barriers for new diagnostic entrants.
Growth Catalysts
- ISO 17025 Accreditation Mandates:Veterinary testing laboratories across the United States, Germany, and Japan face expanding quality management requirements. This standardization is driving consolidation toward certified reference laboratories capable of multi-species panels.
- Companion Animal Insurance Expansion:Pet insurance penetration in the United States and Germany is deepening specialist veterinary care infrastructure. Reimbursement protocols increasingly mandate biomarker-based diagnostics before authorizing therapeutic interventions.
- Mass Spectrometry Platform Integration:Thermo Fisher Scientific's supply partnerships with third-party veterinary developers are accelerating metabolite quantification capabilities. This technology shift is enabling multi-analyte panels that replace single-marker immunoassays.
Market Restraints
- Antibody Development Cost Structure:Proteomic biomarker production requires sustained investment in hybridoma cell lines and recombinant expression systems. Input costs for species-specific antibody generation create margin pressure for assay manufacturers.
- Regulatory Pathway Fragmentation:FDA Center for Veterinary Medicine diagnostic kit approvals operate on timelines distinct from USDA Animal and Plant Health Inspection Service livestock surveillance mandates. This bifurcation forces dual-track validation strategies that extend commercialization cycles.
- Reference Laboratory Concentration:North American and European reference laboratory networks control access to high-throughput validation data. Independent assay developers face dependency relationships with vertically integrated laboratory operators.
Strategic Opportunities
- Livestock Pharmaceutical Integration:Veterinary drug sponsors are embedding biomarker endpoints into efficacy trials for production animal therapeutics. This application segment offers white space for contract research organizations with GLP-compliant bioanalytical capabilities.
- Japan Specialist Clinic Channel:METI-supported regional veterinary medical centers in Japan are expanding diagnostic service menus. Foreign assay developers can access this channel through distribution partnerships with domestic animal health distributors.
- EMA-FDA Harmonization Trajectory:Emerging regulatory alignment between European and American veterinary pathways is reducing duplicate validation requirements. First-mover assay developers can leverage mutual recognition to compress geographic launch sequencing.
Industry Challenges
- Veterinary Bioinformatics Talent Scarcity:Cross-trained professionals capable of integrating mass spectrometry data with species-specific reference ranges remain concentrated in academic veterinary medicine programs. Commercial laboratories compete for this limited talent pool against pharmaceutical sponsors.
- Legacy Immunoassay Infrastructure Lock-in:Companion animal clinics have sunk capital into ELISA-based diagnostic equipment with depreciation cycles extending through 2028. Biomarker platform transitions require concurrent hardware replacement and staff retraining investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Biomarkers Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $178.9 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme-Linked Immunosorbent Assay, PCR, Mass Spectrometry, Liquid Chromatography Application: Diagnostics, Toxicology, Research, Drug Development End User: Veterinary Clinics, Research Laboratories, Pharmaceuticals, Academic Institutions Technology: Genomic, Proteomic, Metabolomic, Bioinformatics |
| Companies Covered | Zoetis, IDEXX Laboratories, Virbac, Merck & Co., Inc., Life Diagnostics, ACUVET BIOTECH, Antech Diagnostics, Thermo Fisher Scientific, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Biomarkers Market Strategic Shifts & Innovations
Digital pathology integration with biomarker quantification is compressing diagnostic turnaround times from days to hours, reshaping how veterinary clinics structure treatment protocols and specialist referrals.
Liquid chromatography-tandem mass spectrometry (LC-MS/MS) is electrifying steroid hormone and therapeutic drug monitoring in companion animal practice. Specialty and emergency veterinary hospitals in the United States are adopting these platforms at accelerating pace, replacing send-out reference laboratory workflows with in-house quantitative capabilities. This displacement is compressing revenue capture for traditional reference laboratory networks while enabling point-of-care therapeutic decision-making.
REACH chemical registration requirements in Europe are tightening specifications for diagnostic reagent manufacturing inputs, particularly affecting antibody conjugation chemistries and stable isotope standards. Manufacturers serving the European Economic Area must now document substance identity and hazard profiles across their supply chains. Veterinary assay developers with European commercialization strategies are responding by qualifying alternative suppliers and reformulating buffer systems to maintain CE marking compliance.
Specialist veterinary hospitals are unbundling diagnostic service contracts from equipment procurement agreements, shifting toward reagent rental models with per-test pricing. This procurement evolution is disrupting traditional capital equipment sales channels in the United States and Germany. Independent veterinary clinic groups in these markets are consolidating purchasing decisions through group procurement organizations, concentrating negotiating leverage with assay platform vendors.
Veterinary Biomarkers Market Segmentation
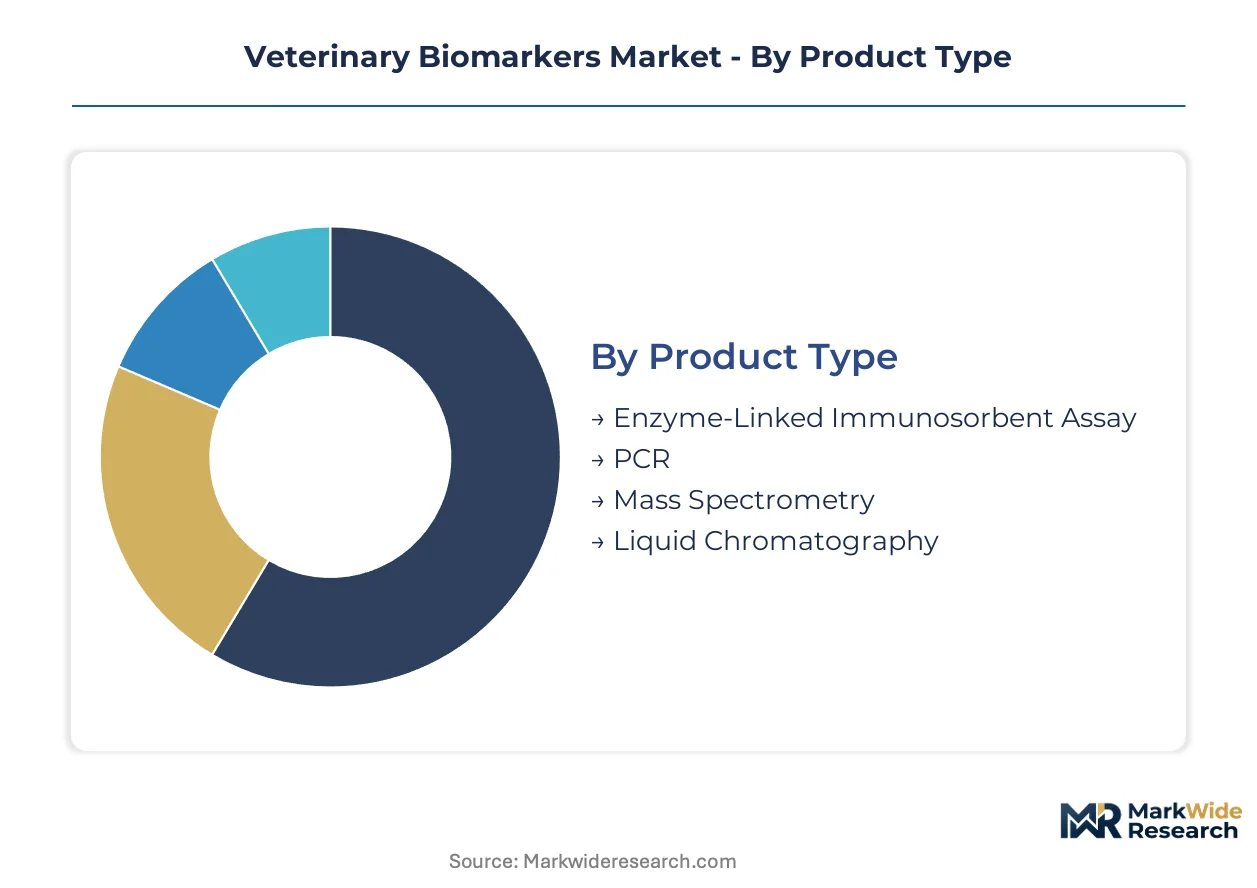
Veterinary biomarker segmentation reveals distinct technology maturity curves and customer capability requirements that shape vendor go-to-market strategies. Product type and technology platform choices determine capital intensity, while application focus dictates regulatory pathway selection and reimbursement eligibility.
Product Type:
Detection chemistry and instrumentation sophistication define performance ceilings and operational economics across veterinary diagnostic workflows.
- Enzyme-Linked Immunosorbent Assay:Antibody-antigen binding reactions quantified via colorimetric or chemiluminescent readouts dominate companion animal screening panels. United States veterinary clinics deploy ELISA platforms for heartworm, Lyme disease, and feline leukemia screening due to established reimbursement codes and minimal technical training requirements.
- Mass Spectrometry:Ionization-based molecular detection enables steroid hormone profiling and therapeutic drug monitoring with picogram sensitivity. Specialty veterinary hospitals in Germany and Japan are displacing reference laboratory send-outs with in-house LC-MS/MS capabilities, compressing diagnostic turnaround from days to hours.
- PCR:Nucleic acid amplification supports pathogen identification and genetic disorder screening in breeding programs. Thermo Fisher Scientific supplies thermal cyclers to third-party veterinary developers expanding infectious disease panels.
- Liquid Chromatography:Separation-based quantification of small molecule metabolites and drug residues serves toxicology screening and residue monitoring in food animal production.
ELISA leads on scale; mass spectrometry leads on momentum.
Application:
Clinical utility and regulatory classification determine pricing power and customer retention patterns across veterinary biomarker deployments.
- Diagnostics:Disease state identification in symptomatic animals drives recurring panel utilization. United States companion animal clinics replace empirical treatment with evidence-based biomarker protocols, deepening per-visit diagnostic revenue capture.
- Research:Biomarker endpoints in veterinary pharmaceutical trials require GLP-compliant bioanalytical validation. Contract research organizations with species-specific reference range databases capture expanding sponsor budgets for production animal therapeutics.
- Toxicology:Poisoning confirmation and environmental contaminant screening serve emergency veterinary hospitals and regulatory surveillance programs. Antibody-based rapid tests address time-critical clinical decisions.
- Drug Development:Pharmacokinetic and pharmacodynamic biomarker integration supports veterinary therapeutic registration packages. FDA Center for Veterinary Medicine mandates biomarker validation for novel drug approvals.
Diagnostics commands volume concentration; research claims the steepest expansion trajectory.
End User:
Capital availability and technical staffing depth segment customer groups by platform complexity and service model preferences.
- Veterinary Clinics:Point-of-care testing demand concentrates in companion animal general practice and emergency settings. United States clinic groups consolidate purchasing through group procurement organizations, shifting toward reagent rental models with per-test pricing.
- Research Laboratories:ISO 17025 accreditation requirements compress assay validation timelines and raise capital barriers. Certified reference laboratories capable of multi-species panels capture consolidation benefits in North America and Europe.
- Pharmaceuticals:Veterinary drug sponsors embed biomarker endpoints into efficacy trials for production animal therapeutics. Zoetis leverages captive biologics manufacturing to secure assay consistency across internal development programs.
- Academic Institutions:Veterinary medicine programs train cross-trained professionals capable of integrating mass spectrometry data with species-specific reference ranges. Commercial laboratories compete against pharmaceutical sponsors for this limited talent pool.
Veterinary clinics anchor volume demand; research laboratories concentrate value capture.
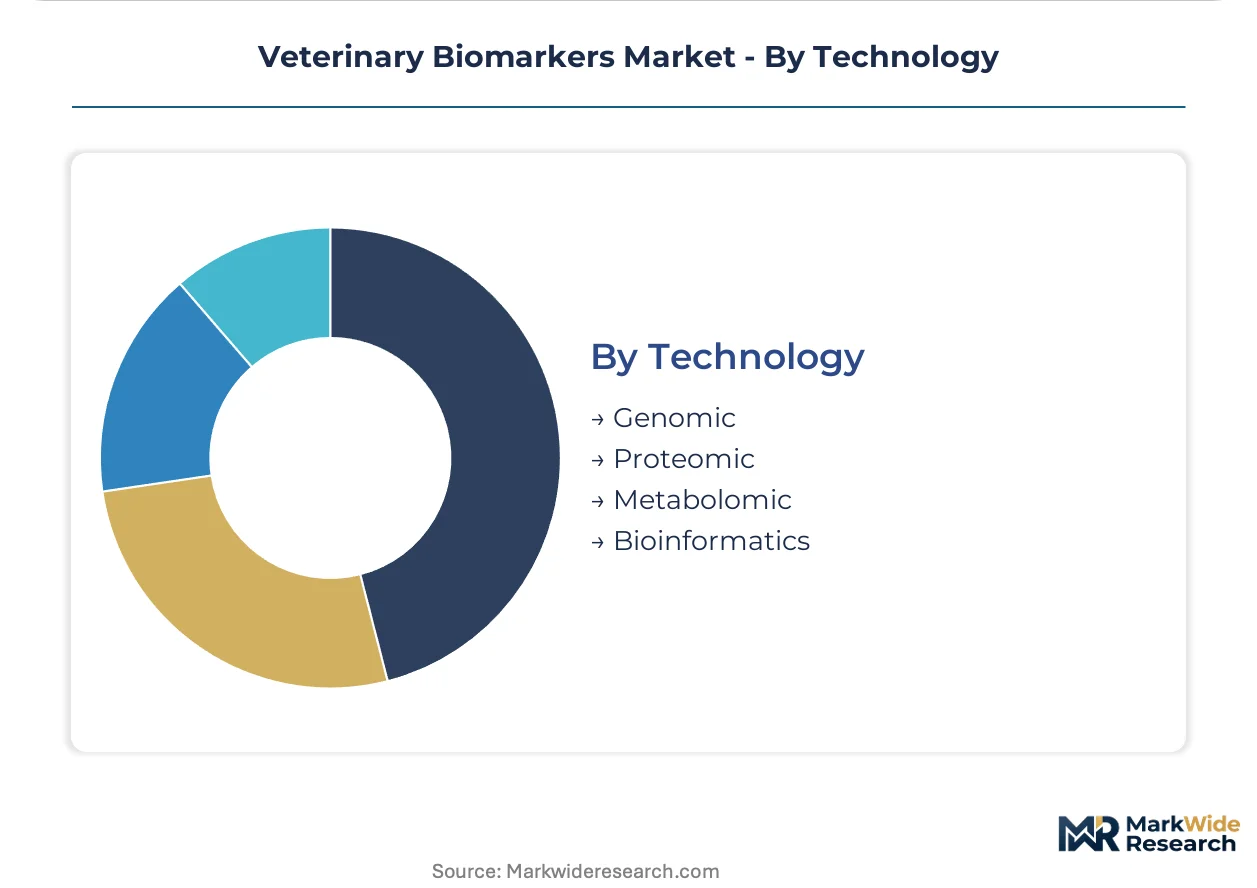
Technology:
Biological information layer and data processing architecture determine competitive differentiation and margin sustainability.
- Proteomic:Protein biomarker quantification via antibody-based assays commands the deepest margin pools due to hybridoma development complexity and recurring reagent consumption. IDEXX Laboratories anchors competitive position through vertically integrated reference laboratory networks.
- Genomic:DNA and RNA analysis supports hereditary disease screening and pathogen genotyping. PCR platform vendors target breeding program customers with high-throughput genetic panel offerings.
- Metabolomic:Small molecule profiling via mass spectrometry enables multi-analyte panels that replace single-marker immunoassays. Thermo Fisher Scientific extends presence by supplying platforms to third-party veterinary test developers.
- Bioinformatics:Computational pipelines for biomarker data interpretation remain concentrated in academic veterinary medicine programs. Commercial deployment requires species-specific algorithm validation absent standardized reference databases.
Proteomic technology leads on revenue concentration; metabolomic approaches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reference laboratory networks concentrate the deepest biomarker validation capabilities and specialist veterinary infrastructure worldwide. Companion animal insurance expansion and ISO 17025 accreditation mandates reshape competitive positioning across national markets.
United States
Pet insurance penetration now exceeds four million covered animals, mandating biomarker diagnostics prior to therapeutic reimbursement. FDA Center for Veterinary Medicine diagnostic kit approvals operate on distinct timelines from USDA livestock surveillance mandates. IDEXX Laboratories anchors vertically integrated reference laboratory networks across North America and Europe.
Germany
Specialist veterinary hospitals in Bavaria and North Rhine-Westphalia displace reference laboratory send-outs with in-house LC-MS/MS platforms. REACH chemical registration requirements tighten specifications for diagnostic reagent manufacturing inputs. The Munich-Stuttgart corridor concentrates metabolite quantification expertise serving central European markets.
Japan
METI-supported regional veterinary medical centers expand diagnostic service menus for companion animal therapeutics. Japan's national pharmaceutical regulator enforces stringent quality management requirements for imported assay platforms. The Kanto region surrounding Tokyo hosts the densest concentration of specialist veterinary clinics adopting biomarker panels.
United Kingdom
Group procurement organizations consolidate independent veterinary clinic purchasing decisions, shifting toward reagent rental models. EMA veterinary pathway alignment with FDA standards reduces duplicate validation requirements for assay developers. The Greater London area concentrates reference laboratory capacity serving domestic and Irish markets.
Canada
Health Canada veterinary drug approval processes integrate biomarker endpoints into efficacy trial mandates for production animal therapeutics. Provincial veterinary medical associations promote ISO 17025 accreditation as a quality differentiator for diagnostic laboratories. The Ontario-Quebec corridor anchors companion animal specialist infrastructure serving urban veterinary markets.
Veterinary Biomarkers Market Key Industry Players
Global majors compete with regional champions across reference laboratory network coverage and assay platform standardization. Market structure tilts toward consolidated reference laboratory operators controlling validation data access and vertically integrated pharmaceutical manufacturers securing captive biologics supply. Three archetypes dominate: vertically integrated pharmaceutical-to-diagnostics conglomerates, independent reference laboratory networks with multi-species panel capabilities, and platform-agnostic instrument suppliers serving third-party assay developers. Competitive moves center on reagent rental model proliferation and multi-source antibody partnerships replacing single-source dependencies.
Within the vertically integrated tier, Zoetis and IDEXX Laboratories occupy positions securing assay consistency across companion animal diagnostics through captive biologics manufacturing and reference laboratory network control. Thermo Fisher Scientific exemplifies the platform-supplier archetype, extending market presence through mass spectrometry instrumentation partnerships with third-party veterinary test developers rather than direct assay commercialization. These three anchors illustrate divergent strategic paths: pharmaceutical-captive integration, laboratory-network dominance, and instrumentation-led ecosystem enablement.
| Leading Market Players |
|---|
| Zoetis |
| IDEXX Laboratories |
| Virbac |
| Merck & Co., Inc. |
| Life Diagnostics |
| ACUVET BIOTECH |
| Antech Diagnostics |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Others |
Cost & Logistics Intelligence
Cross-trained bioinformatics professionals concentrated in academic veterinary medicine programs in the United States and Germany create labor-cost differentials that widen pricing-tier spreads between premium reference laboratory services and economy clinic-based panels.
Pricing Analysis
Input-cost pass-through from species-specific antibody development and hybridoma cell line maintenance drives pricing stratification across assay tiers. Three-tier pricing structure across premium, standard, and economy levels separates GLP-validated research endpoints from clinical screening panels and rapid point-of-care tests. Cost compression in economy immunoassay tiers is intensifying because reference laboratory networks consolidate purchasing leverage through group procurement organizations. Small independent veterinary clinics exhibit highest price sensitivity, while pharmaceutical sponsors demonstrate lowest sensitivity due to regulatory mandate requirements.
Supply Chain Analysis
Domestic-content mandates in Japan's METI-supported veterinary medical centers and REACH chemical registration requirements in Europe are reshaping sourcing strategies for antibody conjugation chemistries and stable isotope standards. Manufacturing concentration rests on the United States, Germany, and China for diagnostic reagent production. Key inputs include recombinant expression systems, monoclonal antibody cell lines, and mass spectrometry consumables. Single-source vulnerability pervades species-specific antibody supply, particularly for exotic and production animal assays. Distribution runs through vertically integrated reference laboratory networks controlling validation data access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through metabolomic platform displacement of legacy immunoassay infrastructure and premium-tier adoption of LC-MS/MS capabilities in specialist hospitals.
For Market Incumbents: Deepen captive biologics manufacturing control over hybridoma cell line supply to secure assay consistency against emerging platform-agnostic instrument suppliers. Expand ISO 17025-accredited reference laboratory capacity in the United States and Germany to capture consolidation benefits from accreditation mandates. Anchor multi-species panel capabilities through backward integration into antibody development rather than outsourcing to single-source suppliers. For New Entrants and Emerging Players: Launch via reagent rental models with per-test pricing to bypass capital equipment procurement barriers facing independent veterinary clinic groups. Target Japan's METI-supported regional veterinary medical centers through distribution partnerships with domestic animal health distributors as the most penetrable geographic entry point. Embed bioinformatics capabilities for species-specific algorithm validation to differentiate from commodity immunoassay providers. For Investors and Strategic Acquirers: Pharmaceutical sponsors are the most active acquirer in this space, seeking GLP-compliant bioanalytical capabilities for veterinary drug trial integration. Over the medium-term horizon, contract research organizations with validated reference range databases represent the highest-viability acquisition archetype. Monitor EMA-FDA regulatory harmonization progress as the critical signal for geographic launch sequencing compression.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Model Proliferation | Shifts veterinary clinic procurement from capital expenditure to operational expenditure, accelerating platform transitions. |
| Multi-Source Antibody Partnerships | Reduces dependency on single hybridoma suppliers, mitigating supply disruption risks for assay manufacturers. |
| LC-MS/MS Platform Integration | Enables in-house metabolite quantification, displacing reference laboratory send-outs in specialty hospitals. |
| EMA-FDA Harmonization Leverage | Compresses duplicate validation requirements, accelerating geographic expansion for first-mover assay developers. |
| Bioinformatics Capability Buildout | Addresses talent scarcity in species-specific algorithm validation, differentiating premium service tiers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with reference laboratory directors, veterinary clinic procurement managers, pharmaceutical regulatory affairs leads, and diagnostic platform engineers with secondary validation against FDA Center for Veterinary Medicine filings, USDA Animal and Plant Health Inspection Service surveillance protocols, ISO 17025 accreditation databases, and EMA veterinary pathway documentation. Bottom-up assay volume estimates and top-down market sizing triangulated to constrain variance bands.
Comparable-period anchoring to historical reference laboratory network expansion and companion animal insurance penetration trends established baseline trajectory assumptions across the projection horizon. Segmentation dimensions modeled include technology platform, application purpose, end-user capital availability, and regional regulatory cluster. CAGRs derived from weighted average of technology adoption curves and reimbursement protocol evolution. Industry-specific forecast inputs incorporated metabolomic platform displacement rates and ISO 17025 accreditation mandate implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory pathway fragmentation scenarios or accelerated EMA-FDA harmonization. Forecasts reflect documented assumptions regarding antibody development cost trajectories and reference laboratory consolidation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Global Veterinary Grooming Aids Market
Veterinary
Veterinary Healthcare Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Veterinary Hospitals Market
Veterinary
Canine Flu Therapeutics Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Isoxazoline Market
Veterinary
Canine Parvovirus Market
Veterinary
Mastitis Market
Veterinary
United Kingdom Veterinary Healthcare Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Global Canine Influenza Vaccine Market