
 Animal Drug Compounding Market | 2026-2036
Animal Drug Compounding Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Drug Compounding Market Intelligence
USP-grade active pharmaceutical ingredient sourcing is rotating toward higher-purity specifications across veterinary compounding. Wedgewood Pharmacy leverages its vertically integrated sourcing network to secure consistent API quality. Triangle Compounding Pharmacy sustains regional dominance through specialized equine formulation capabilities. Akina Animal Health differentiates via technology leadership in flavor-masked oral suspensions for feline patients.
Animal drug compounding involves the tailored preparation of veterinary medications from bulk pharmaceutical ingredients or FDA-approved products to achieve species-specific dosages, alternate delivery routes, or palatability modifications that commercial products cannot address. Formulations typically incorporate active ingredients at concentrations ranging from microgram to milligram scales, with pH stabilization and preservative systems ensuring shelf stability under variable storage conditions. Oral formulations occupy the largest volume share due to their adaptability across canine and feline populations, while transdermal patches represent the fastest-expanding segment as pet owners seek stress-free administration alternatives. Injectable solutions concentrate margin pools in equine and livestock applications where veterinary supervision ensures precise delivery.
FDA guidance on compounding from bulk drug substances, USP chapter standards for veterinary preparation sterility, and state pharmacy board regulations collectively govern market access and product liability exposure. The FDA's draft GFI 256 framework specifically restricts which bulk substances 503A compounders may use, directly constraining formulation menus available to veterinary practitioners. Stakeholders must monitor whether Congress codifies bulk compounding restrictions or preserves current enforcement discretion, as this legislative inflection will determine facility investment requirements and competitive barriers across the supply base.
Market Dynamics
FDA's draft GFI 256 framework is actively constraining which bulk drug substances 503A compounders may source, forcing veterinary pharmacies to restructure supplier relationships and formulation menus while state pharmacy boards tighten sterility enforcement.
Growth Catalysts
- Specialty veterinary practice expansion:Companion animal clinics in the United States are expanding personalized dosing services for chronic conditions, driving volume for customized oral suspensions and transdermal alternatives.
- USP Chapter 797 sterility standards:The updated chapter mandates rigorous environmental monitoring and beyond-use dating protocols, elevating barrier requirements for sterile compounding operations serving equine and exotic species.
- Flavor-masked suspension technology:Palatability engineering for feline patients is decomposing traditional tablet administration, with pet owners prioritizing stress-free dosing experiences that reduce veterinary visit frequency.
Market Restraints
- Bulk API sourcing volatility:USP-grade active pharmaceutical ingredient prices fluctuate with global chemical supply chain disruptions, compressing margin pools for small-batch veterinary formulations.
- FDA enforcement discretion uncertainty:The unresolved legislative status of bulk compounding restrictions creates facility investment paralysis, as compounders delay capital deployment pending Congressional codification.
- Commercial product substitution:FDA-approved veterinary drugs with flexible labeling are capturing cases that previously required compounding, particularly in canine dermatology and endocrinology.
Strategic Opportunities
- Equine sports medicine specialization:Underpenetrated racetrack and performance horse clinics present white space for customized injectable anti-inflammatories with extended stability profiles.
- Telemedicine-tethered compounding:Virtual veterinary consultations are creating direct-to-consumer dispensing channels that bypass traditional clinic inventory constraints.
- State-level pharmacy autonomy:Jurisdictions with permissive bulk substance lists offer regulatory arbitrage for multi-state operators willing to segment production across facility networks.
Industry Challenges
- Sterile compounding technician scarcity:USP 797 certification requirements and aseptic technique proficiency are narrowing the qualified labor pool, extending hiring timelines for expansion projects.
- Cross-state licensing complexity:Practitioners seeking compounded medications across jurisdictional boundaries face fragmented reciprocity agreements that delay treatment initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Drug Compounding Market |
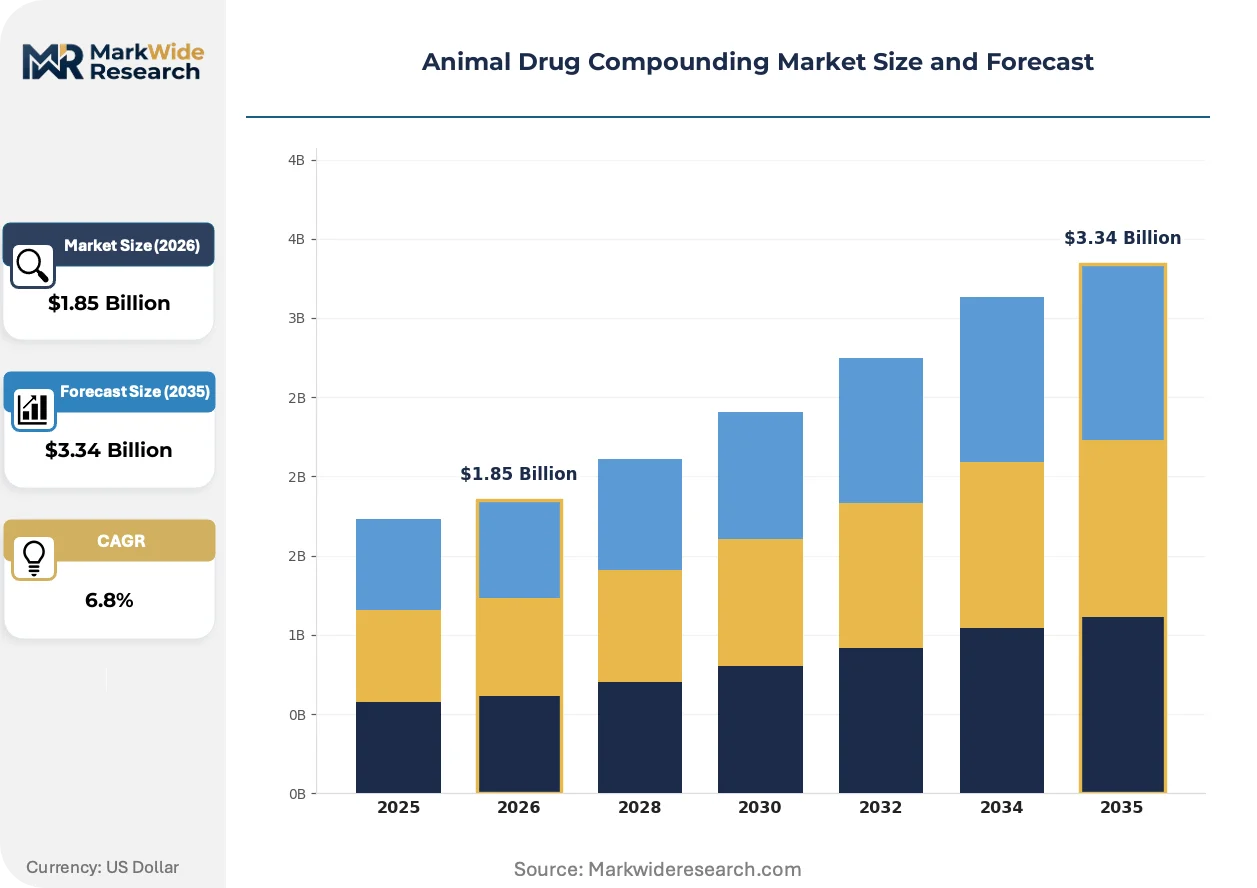
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Solutions, Oral Formulations, Topical Preparations, Transdermal Patches Species Type: Canine, Feline, Equine, Livestock Delivery Mode: IV Administration, Oral Administration, Subcutaneous Delivery, Intranasal Administration End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Pharmacies |
| Companies Covered | Wedgewood Pharmacy, Triangle Compounding Pharmacy, Akina Animal Health, Vimian, Davis Islands Pharmacy, Custom Med Compounding Pharmacy, Diamondback Drugs, Mixlab, Central Compounding Center South, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Drug Compounding Market Strategic Shifts & Innovations
Formulation science and delivery mechanism engineering are converging to address species-specific physiological barriers, with palatability and administration convenience now ranking alongside therapeutic efficacy in veterinary prescribing decisions.
Micro-dose transdermal gel technology is decomposing traditional oral administration paradigms in feline medicine. The technology delivers therapeutic concentrations through pinna absorption, eliminating pilling stress. Specialty cat practices are adopting these formulations for chronic renal and hyperthyroid management, compressing the addressable market for conventional tablets.
EMA's veterinary regulation harmonization initiative is creating cross-border formulation standards for compounded products used in food-producing animals. The framework restricts certain bulk substances in livestock applications to residue-avoidance thresholds. European equine practitioners are responding by segregating compounding operations between companion and production animal lines.
Pet owner purchasing behavior is fragmenting across subscription-based auto-ship platforms and urgent same-day fulfillment channels. Veterinary clinics are losing formulary control as clients price-shop compounded alternatives through third-party pharmacies. This channel disintermediation is most pronounced in urban United States markets with dense specialty practice clusters.
Animal Drug Compounding Market Segmentation
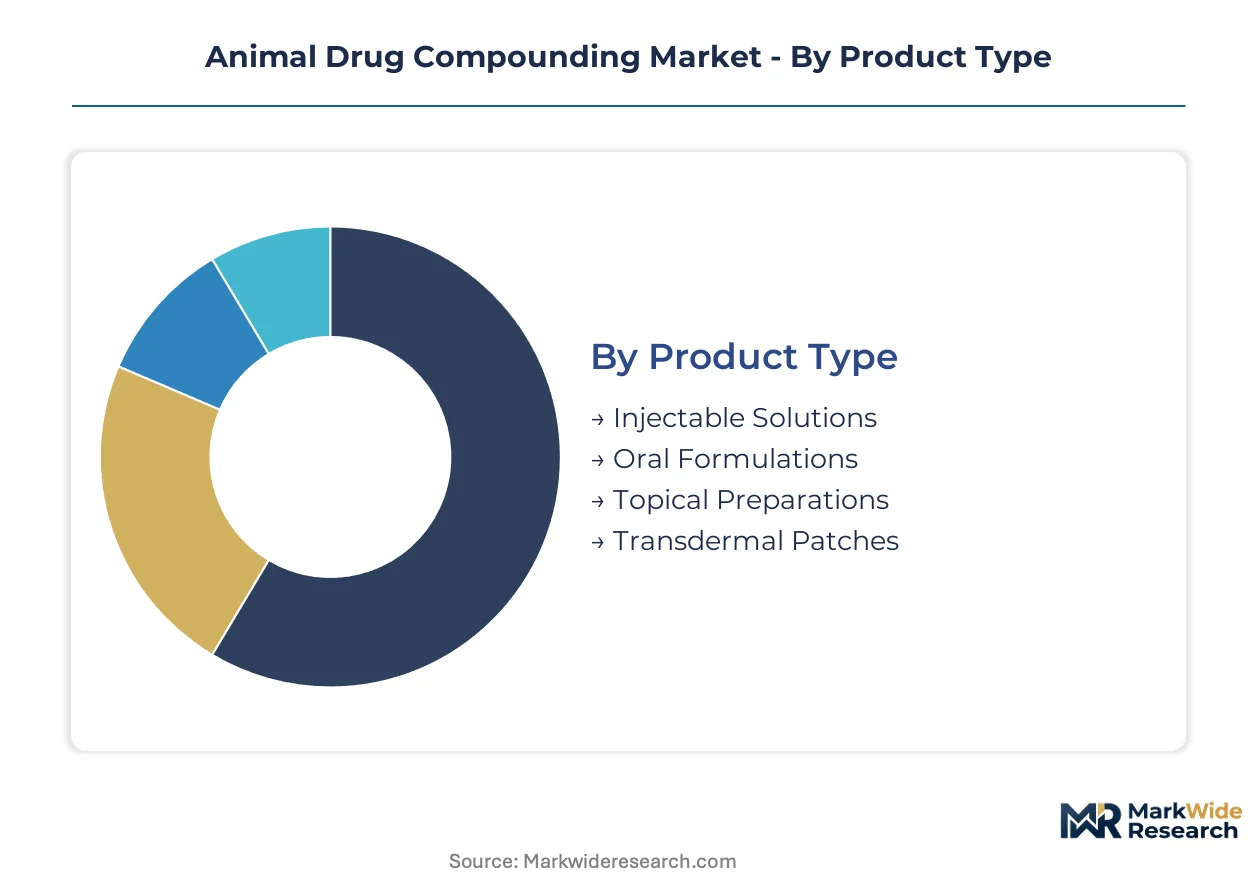
Animal drug compounding segments diverge sharply by administration complexity and regulatory exposure. Channel economics favor formulations that bypass sterile processing requirements while meeting species-specific palatability demands.
Product Type:
Channel mix splits between clinic-dispensed oral preparations and pharmacy-fulfilled sterile injectables, with transdermal alternatives capturing direct-to-consumer growth.
- Injectable Solutions:Sterile formulations requiring USP 797 compliance concentrate margin pools in equine sports medicine and exotic veterinary applications. Demand clusters at specialty practices in Texas and Kentucky where veterinary supervision ensures precise delivery of anti-inflammatory and anesthetic compounds.
- Oral Formulations:Suspensions and flavored tablets dominate canine and feline dispensing volumes through general practice clinics. Palatability engineering with fish-based and poultry-based flavor matrices reduces pet owner administration failure rates.
- Topical Preparations:Dermatological creams and otic solutions serve localized infection management with lower barrier-to-entry compounding requirements.
- Transdermal Patches:Pinna-absorption gels for feline hyperthyroid management bypass pilling stress, expanding through specialty cat practices and subscription pharmacy channels.
Oral formulations dominate installed base. Transdermal patches are where expansion concentrates.
Species Type:
Cost tier stratification separates premium companion animal formulations from volume-driven livestock applications with divergent API sourcing protocols.
- Canine:Chronic condition management drives sustained demand for customized oral suspensions in dermatology and endocrinology, with FDA-approved alternatives capturing share in standardized dosing scenarios.
- Feline:Stress-free administration requirements elevate transdermal and palatable liquid formulations, concentrating volume at feline-exclusive practices in urban United States markets.
- Equine:Performance and racing applications sustain premium pricing for extended-stability injectable anti-inflammatories, with racetrack veterinarians in Florida and California driving formulation customization.
- Livestock:Residue-avoidance constraints under FDA and state agricultural department oversight limit bulk substance menus, channeling volume toward FDA-approved veterinary drugs with production animal labeling.
Canine applications anchor revenue volume. Feline-specific formulations are climbing the fastest.
Delivery Mode:
Application urgency determines whether administration routes require veterinary presence or enable remote patient management.
- IV Administration:Critical care and surgical applications concentrate in emergency and referral hospitals with 24-hour pharmacy capabilities.
- Oral Administration:Chronic disease management and at-home dosing sustain the broadest addressable market across general practice channels.
- Subcutaneous Delivery:Insulin and fluid therapy applications bridge clinic and home administration, requiring patient-specific dosing education.
- Intranasal Administration:Vaccine and sedative delivery for fractious animals occupies niche positioning in shelter and exotic veterinary settings.
Oral administration commands patient volume. Subcutaneous delivery is gaining share fastest through diabetic pet management protocols.
End User:
Customer type segmentation fragments across institutional purchasing authority and formulary control dynamics.
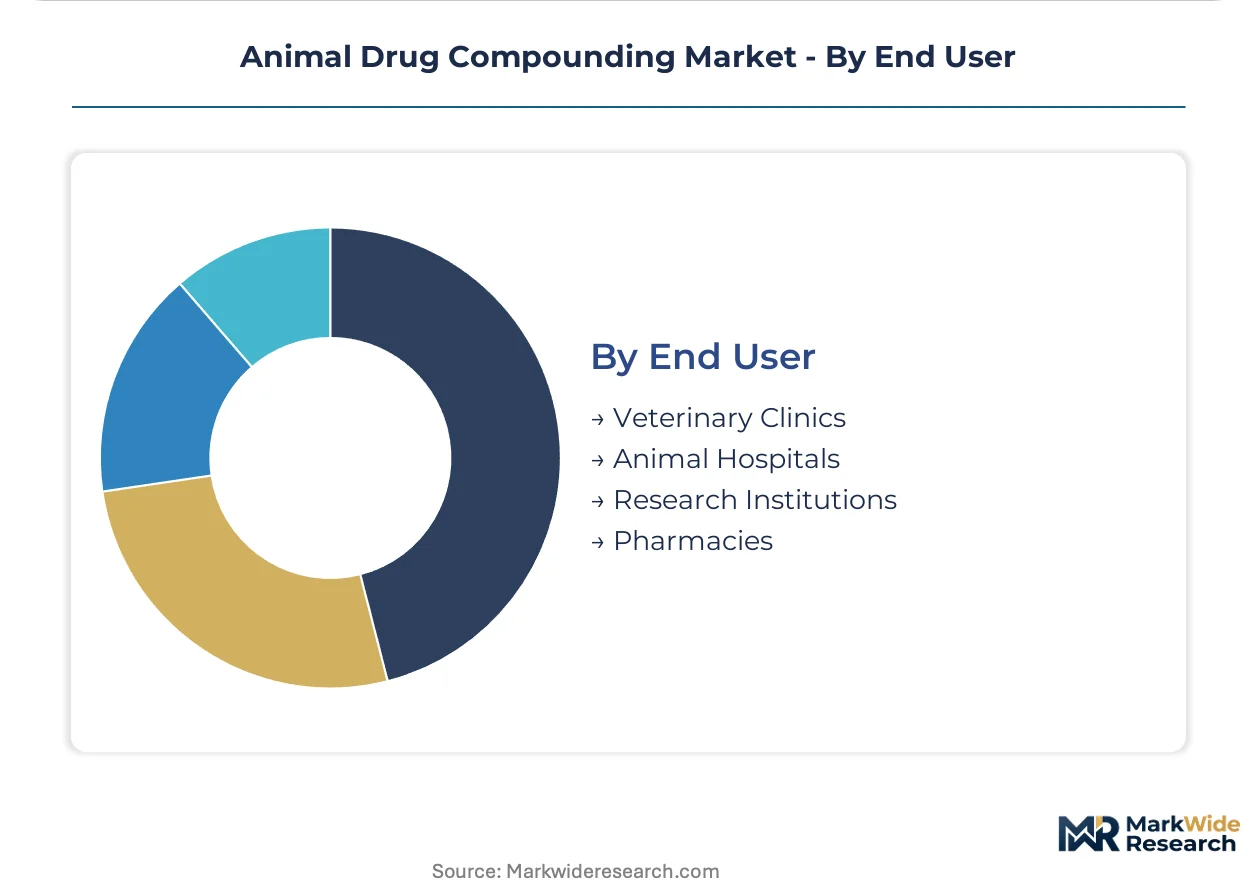
- Veterinary Clinics:General and specialty practices retain formulary influence in suburban and rural markets, though urban clients increasingly price-shop through third-party channels.
- Animal Hospitals:Emergency and referral centers with captive pharmacies capture acute care compounding for critical stabilization and surgical support.
- Research Institutions:Protocol-specific dosing for toxicology and efficacy studies demands documentation rigor exceeding standard veterinary compounding.
- Pharmacies:Wedgewood Pharmacy and regional compounders serve telemedicine-tethered dispensing, disintermediating traditional clinic inventory relationships.
Veterinary clinics retain the deepest installed relationships. Pharmacies are where channel expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary compounding operations concentrate where specialty practice density intersects with permissive regulatory environments. Facility investment clusters around metropolitan veterinary hubs with established sterile processing infrastructure.
United States
Specialty companion animal practices in Florida and California sustain premium demand for customized anti-inflammatories and transdermal formulations. FDA draft GFI 256 constrains bulk substance menus for 503A compounders, forcing supplier restructuring. Racetrack veterinarians in Kentucky and Texas drive equine formulation customization with extended stability requirements.
Germany
Equine sports medicine practitioners in Lower Saxony and Bavaria generate sustained volume for sterile injectable compounds. EMA veterinary regulation harmonization restricts bulk substances in food-producing animals to residue-avoidance thresholds. Compounding pharmacies in Baden-Württemberg segregate operations between companion and production animal lines.
United Kingdom
Feline-exclusive practices in Greater London and Southeast England elevate demand for palatable liquid formulations and pinna-absorption gels. The Veterinary Medicines Directorate maintains strict enforcement of the prescribing cascade for compounded products. Regional compounders in the Midlands serve telemedicine-tethered dispensing channels.
Australia
Exotic veterinary clinics in New South Wales and Victoria require specialized dosing for marsupial and avian species. The Therapeutic Goods Administration coordinates with state pharmacy boards on bulk compounding oversight. Sydney-based compounding facilities capture critical care demand from emergency animal hospitals.
Canada
Equine performance clinics in Ontario and Alberta sustain demand for customized sedative and anti-inflammatory preparations. Health Canada and provincial pharmacy regulators enforce USP-grade API sourcing standards. Vancouver-area compounders serve growing telemedicine dispensing across British Columbia.
Animal Drug Compounding Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the veterinary compounding space. Vertically integrated pharmacy networks secure captive API supply chains while regional specialists maintain formulation expertise in narrow species segments. The competitive structure fragments across three archetypes: national scale operators with multi-state licensing, regional specialists with species-specific capabilities, and technology-enabled direct-to-consumer platforms. Consolidation pressure intensifies through strategic partnerships between compounding pharmacies and telemedicine providers, alongside capacity expansion in sterile processing infrastructure.
Among vertically integrated operators, Wedgewood Pharmacy anchors the national scale tier with multi-state distribution reach. Triangle Compounding Pharmacy exemplifies the regional specialist archetype with concentrated equine formulation capabilities. Akina Animal Health occupies a position within the technology-enabled segment, representing investment in palatability engineering for feline applications.
| Leading Market Players |
|---|
| Wedgewood Pharmacy |
| Triangle Compounding Pharmacy |
| Akina Animal Health |
| Vimian |
| Davis Islands Pharmacy |
| Custom Med Compounding Pharmacy |
| Diamondback Drugs |
| Mixlab |
| Central Compounding Center South |
| Others |
Cost & Logistics Intelligence
Multi-state sterile processing capacity utilization rates above 80% create pricing power concentration among USP 797-certified facilities, compressing margin pools for smaller compounders while elevating price floors for extended-stability injectables in equine and exotic applications. This scale dynamic reinforces supplier consolidation incentives as veterinary pharmacies seek captive API sourcing to defend formulation margins against bulk substance price volatility.
Pricing Analysis
FDA draft GFI 256 dictates the pricing tier structure by constraining eligible bulk substances and elevating compliance costs for 503A compounders. Three-tier pricing structure across premium sterile injectables, standard oral suspensions, and economy topical creams separates facilities by certification grade and sterility assurance level. Pricing pressure stems from commercial veterinary drugs with flexible labeling capturing chronic condition cases previously requiring compounding. General practice clinics exhibit highest price sensitivity due to client retention pressures, while racetrack veterinarians show lowest sensitivity for customized anti-inflammatories with performance-critical stability profiles.
Supply Chain Analysis
Just-in-time API inventory management with 60-90 day procurement cycles exposes compounders to disruption from overseas supplier delays. Active pharmaceutical ingredient sourcing concentrates in India, China, and the United States for USP-grade veterinary inputs. Formulation operations depend on excipient supplies from European chemical manufacturers and preservative systems from North American specialty chemical producers. Single-source vulnerability for certain bulk substances under FDA restricted lists creates supply continuity risk. Distribution runs through veterinary clinic dispensing, pharmacy direct-to-consumer platforms, and telemedicine-tethered fulfillment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal drug compounding sits in early-cycle expansion as feline-specific transdermal formulations displace conventional tablet administration and telemedicine channels unlock direct-to-consumer growth beyond traditional clinic inventory relationships.
For Market Incumbents: Consolidate sterile processing capacity in Florida and California metropolitan hubs to capture specialty practice density, while securing backward integration into USP-grade API sourcing networks to offset bulk substance price volatility from restricted supplier lists. Defend margin pools by investing in USP 797 certification upgrades ahead of state board enforcement tightening. For New Entrants and Emerging Players: USP 797 certification fast-track programs in permissive regulatory jurisdictions offer entry acceleration for sterile compounding operations targeting underserved exotic veterinary segments. White space concentrates in telemedicine-integrated pharmacy platforms serving urban feline-exclusive practices. Go-to-market execution should prioritize subscription-based auto-ship models with flavor-engineered oral suspensions. For Investors and Strategic Acquirers: Regional specialists with concentrated equine formulation capabilities and established racetrack veterinarian relationships represent priority acquisition targets. Long-term viability hinges on regulatory arbitrage durability across multi-state facility networks. Monitor FDA Congressional codification efforts as the inflection signal determining facility investment requirements and competitive barrier height.| Strategic Initiative | Industry Significance |
|---|---|
| USP 797 Certification Investment | Elevates barrier requirements for sterile compounding serving equine and exotic species under state board enforcement. |
| Telemedicine Platform Integration | Creates direct-to-consumer dispensing channels that bypass traditional clinic inventory constraints in urban markets. |
| Flavor-Masked Suspension R&D | Addresses feline patient palatability barriers that decompose traditional tablet administration paradigms. |
| Multi-State Licensing Expansion | Enables regulatory arbitrage across jurisdictions with permissive bulk substance lists for 503A compounders. |
| Captive API Sourcing Network | Secures consistent USP-grade active pharmaceutical ingredient quality against global supply chain disruptions. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across veterinary specialty practices, compounding pharmacy operations, and state pharmacy board regulators. Primary interviews captured prescribing behavior, formulation preferences, and compliance investment patterns from equine sports medicine veterinarians in Kentucky and Texas, feline-exclusive practitioners in Florida and California, and sterile compounding technicians facing certification requirements. Secondary validation drew from FDA guidance documents, USP chapter standards, state pharmacy board regulations, and veterinary medical association proceedings. Bottom-up prescription volume modeling and top-down market sizing triangulated across facility capacity data and API procurement flows.
Across the analysis window, projections integrate species-specific formulation demand, administration route adoption curves, and regulatory enforcement trajectory scenarios. Segmentation dimensions modeled include product type, species application, delivery mode, and end-user channel. CAGRs derive from compound annual growth rate calculations applied to base year market sizing against projected volume and value outputs. Forecast inputs incorporate specialty practice expansion rates, USP 797 adoption timelines, and telemedicine platform penetration curves.
Decision-makers should treat outputs as directional under assumptions of continued FDA enforcement discretion and stable USP-grade API sourcing availability; material deviation through Congressional codification of bulk compounding restrictions or significant supply chain disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
US Surgical Pet Collar Market
Veterinary
Veterinary Thermography Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Global Avian Influenza Vaccines Market
Veterinary
Veterinary Excipients Market
Veterinary
Bovine Mastitis Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
Global Canine Atopic Dermatitis Market
Veterinary
Canine Arthritis Market
Veterinary
North America and Europe Veterinary Telehealth Market
Veterinary
Global Orthopedic Veterinary Implants Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Veterinary Vaccines Market
Veterinary
Otc Pet Medication Market
Veterinary
Veterinary Lasers Market
Veterinary
Veterinary Tables Market