
 Global Equine Supplement Products Market | 2026-2036
Global Equine Supplement Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Equine Supplement Products Market Foresight
A shortage of veterinary nutritionists with equine specialization is unwinding supply chain confidence across formulated product lines. Zoetis Services LLC leverages its pharmaceutical heritage to anchor premium supplement credibility with veterinarians. Boehringer Ingelheim International GmbH sustains broad distribution reach across European equestrian centers. Kentucky Equine Research differentiates through science-backed formulations tied to peer-reviewed studies on thoroughbred performance.
Equine supplement products comprise orally administered nutritional formulations designed to address physiological gaps in horse diets, typically delivered as pellets, powders, or pastes containing defined active ingredient concentrations measured in milligrams per kilogram of body weight. These products serve commercial and competitive stables seeking to optimize performance metrics, recovery intervals, and reproductive outcomes in high-value animals. Joint health formulations occupy the premium margin tier due to chronic demand from aging sport horses and the high cost of active ingredients like glucosamine and chondroitin sulfate. Digestive aids represent the fastest-expanding category as microbiome research reshapes feeding protocols across racing and breeding operations. Online platforms are displacing traditional feed dealers among recreational riders seeking subscription-based convenience.
The FDA Center for Veterinary Medicine oversees ingredient safety claims in the United States, while the EU Feed Additives Regulation mandates pre-market authorization for novel compounds entering European supply chains. Australia's APVMA enforces residue limits that directly shape export-oriented manufacturer formulation choices. Stakeholders must monitor evolving probiotic classification debates across jurisdictions, as regulatory reclassification could force reformulation investments or channel restrictions.
Market Dynamics
Veterinary oversight tightening across major jurisdictions is forcing manufacturers to restructure formulation disclosure protocols and accelerate clinical validation timelines for active ingredient claims.
Growth Catalysts
- EU Feed Additives Regulation:Pre-market authorization requirements for novel compounds are elevating entry barriers that favor established science-backed suppliers with veterinary pharmacy heritage.
- Microbiome research advancement:Peer-reviewed studies on equine gut health are accelerating adoption of digestive aid formulations across racing and breeding operations.
- United States competitive equestrian culture:Professional trainers and racehorse owners in Kentucky and Florida sustain premium purchasing for joint health formulations targeting aging sport horses.
Market Restraints
- Glucosamine and chondroitin sulfate cost volatility:Marine-derived sourcing concentration exposes joint health margins to fishery quota fluctuations and ocean freight rate spikes.
- Veterinary nutritionist shortage:Specialized credential scarcity limits manufacturer capacity to validate complex multi-ingredient formulations for regulatory submission.
- Probiotic regulatory reclassification risk:Jurisdictional debates over live culture classification threaten forced reformulation investments across European supply chains.
Strategic Opportunities
- Subscription-based direct-to-consumer channels:Recreational riders in Australia are bypassing traditional feed dealers for automated replenishment of pelleted digestive supplements.
- Residue-limit harmonization:Australia's APVMA export standards alignment creates formulation templates applicable to multiple Asia-Pacific racing jurisdictions.
- Reproductive outcome optimization:Breeding farms in Germany are expanding demand for trace mineral formulations tied to foal development metrics.
Industry Challenges
- Clinical trial capacity constraints:Limited equine research facilities extend peer-review validation timelines for performance claims on thoroughbred cohorts.
- Cross-jurisdiction label compliance:Divergent FDA Center for Veterinary Medicine and EFSA disclosure requirements force SKU proliferation or lowest-common-denominator formulation dilution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Equine Supplement Products Market |
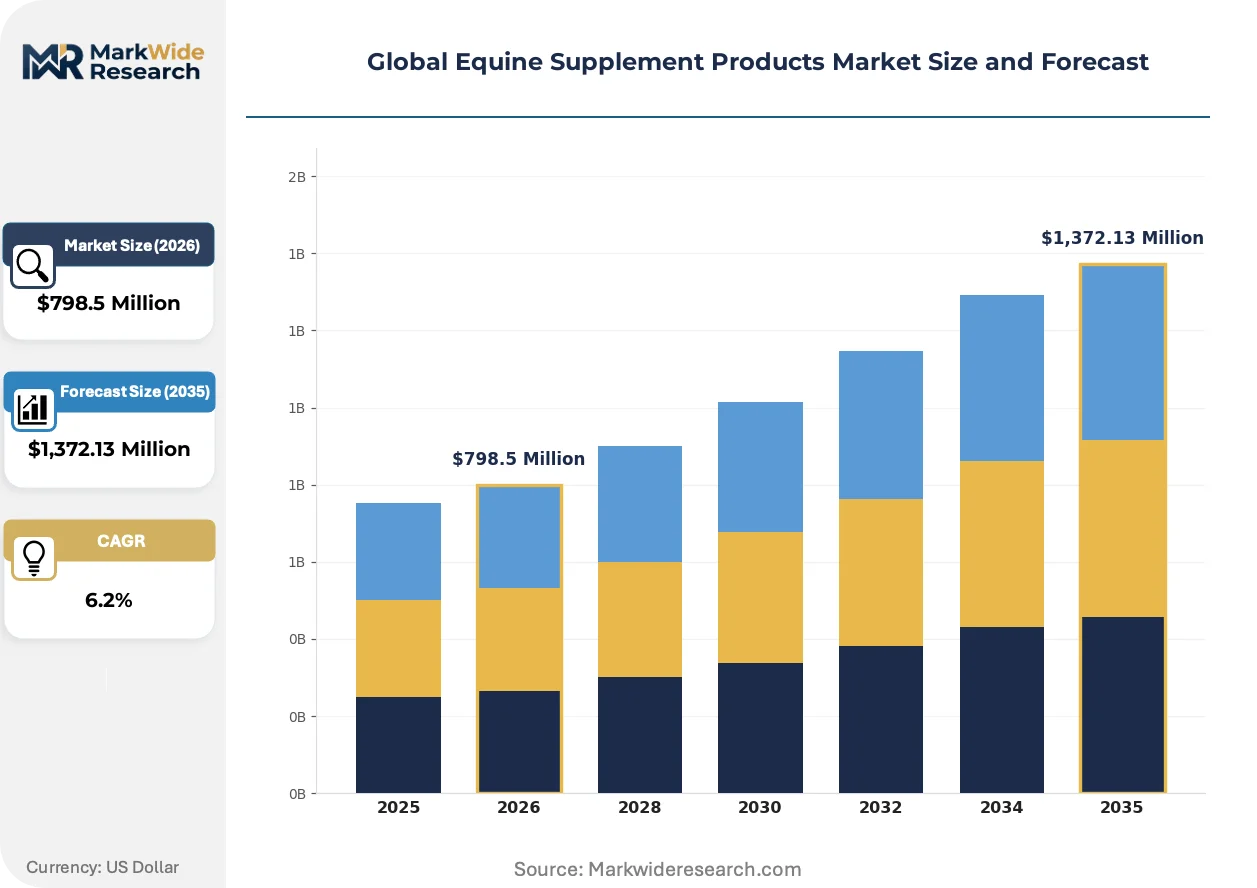
| Market Size in 2026 | $798.5 Million |
| Market Size in 2035 | $1,372.13 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Electrolytes, Joint Health, Digestive Aids, Skin & Coat Enhancers Application: Performance Enhancement, Recovery Support, Growth Promotion, Reproductive Health, Immune Support, Weight Management End User: Breeders, Trainers, Racehorse Owners, Equestrian Centers, Veterinary Clinics, Recreational Riders Distribution Channel: Specialty Stores, Online Platforms, Veterinary Pharmacies, Feed Dealers, Direct Sales, Retail Chains |
| Companies Covered | Zoetis Services LLC, Boehringer Ingelheim International GmbH, Bayer AG, Purina Animal Nutrition LLC, Vetoquinol S.A., Kentucky Equine Research, Farnam Companies Inc., SmartPak Equine LLC, Lallemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Equine Supplement Products Market Shifts & Advancements
Formulation science and distribution architecture are undergoing parallel transformation as microbiome research reshapes product development priorities and digital channels capture recreational buyer segments.
Targeted synbiotic delivery systems combining prebiotic fibers with strain-specific probiotics are displacing generic yeast-based digestive aids in premium racing stables. Kentucky and Dubai-based trainers are adopting these formulations within eighteen-month switching cycles. The technology is displacing commodity digestive products by enabling measurable methane reduction and feed conversion ratio improvements that justify per-dose cost premiums.
REACH-aligned substance authorization pathways in Europe are compressing novel ingredient introduction timelines for non-pharmaceutical actives. Manufacturers must now submit full toxicological dossiers before market entry. Joint health categories containing marine-derived chondroitin face heightened scrutiny, prompting suppliers to accelerate terrestrial fermentation alternatives.
Recreational rider segments are consolidating purchase decisions through vertically integrated equine service platforms that bundle nutrition with farrier and veterinary scheduling. Traditional independent feed dealers in the United States and Australia are losing share to these ecosystems. Subscription retention rates exceed eighty percent where platforms offer personalized dosing algorithms tied to individual horse workload data.
Global Equine Supplement Products Market Segmentation
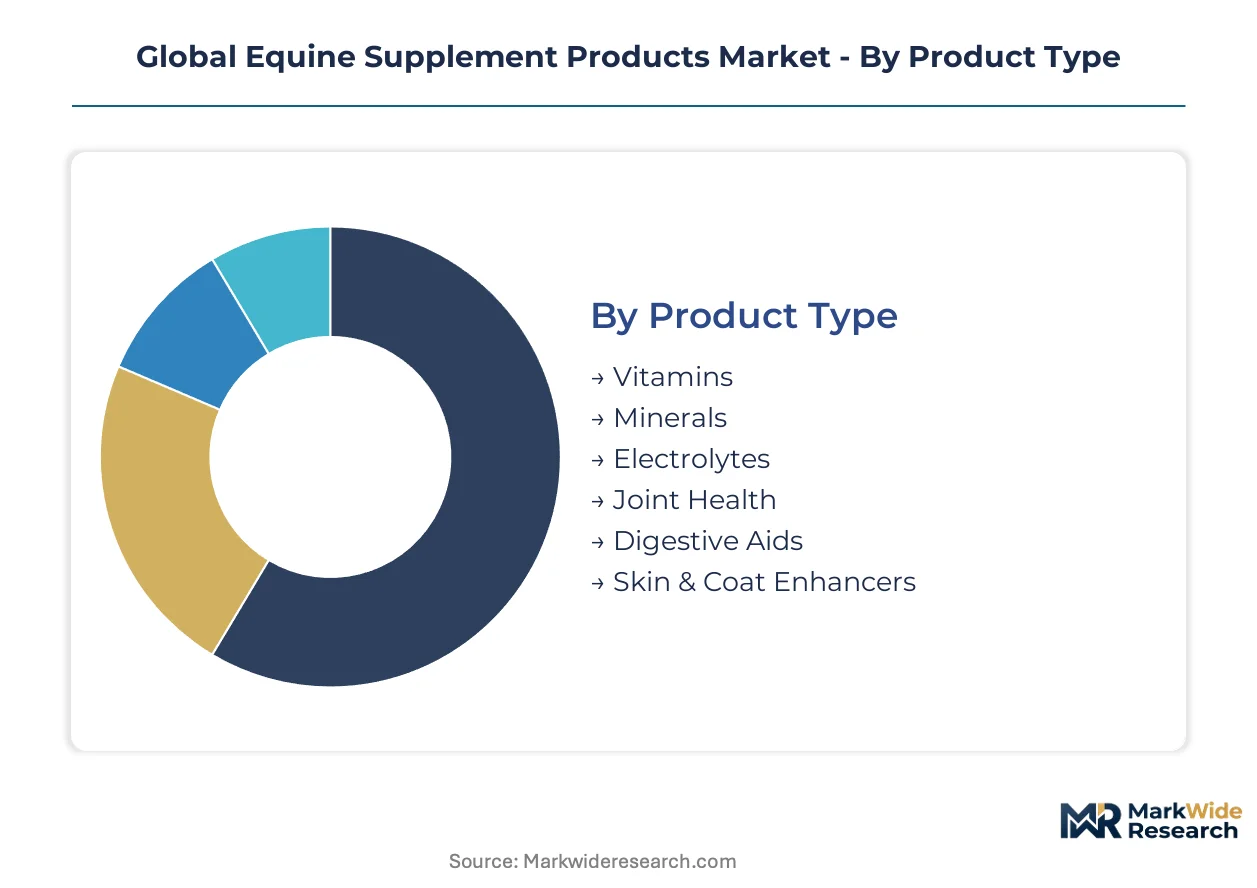
Equine supplement purchasing patterns diverge sharply across product categories and buyer profiles. Trainers in Kentucky and breeders in Germany prioritize clinical validation, while Australian recreational riders favor subscription convenience. These distinctions shape formulation priorities and channel investments across the value chain.
Product Type:
Domestic consumption dominates vitamin and mineral categories, whereas joint health and digestive formulations drive cross-border trade into Asia-Pacific racing jurisdictions.
- Joint Health:Glucosamine and chondroitin sulfate formulations target aging sport horses with chronic mobility degradation. Demand concentrates in the United States and Germany where competitive equestrian cultures sustain premium pricing for marine-derived active ingredients.
- Digestive Aids:Prebiotic-probiotic combinations address microbiome optimization in thoroughbred racing stables. Australian breeding operations and Dubai-based trainers are adopting synbiotic delivery systems within compressed switching cycles.
- Vitamins:Standardized micronutrient blends serve baseline nutritional gaps across commercial stables.
- Minerals:Trace element formulations support reproductive outcomes in German breeding farms.
- Electrolytes:Hydration management products target endurance disciplines in hot-climate racing.
- Skin & Coat Enhancers:Omega fatty acid blends address cosmetic presentation in show circuits.
Joint Health holds the largest share; momentum sits with Digestive Aids.
Application:
Cost tier stratification separates premium performance claims from commodity maintenance categories.
- Performance Enhancement:Targeted formulations optimize oxygen utilization and muscle recovery metrics in racehorses. Kentucky trainers and Florida-based owners sustain premium purchasing for peer-reviewed active ingredients with measurable thoroughbred outcomes.
- Recovery Support:Anti-inflammatory and tissue repair formulations reduce lay-up periods after injury. Veterinary clinics in Germany and Australia prescribe these products as adjuncts to pharmaceutical protocols.
- Growth Promotion:Developmental nutrition targets foal skeletal formation in breeding operations.
- Reproductive Health:Trace mineral and antioxidant blends support mare fertility and stallion viability.
- Immune Support:Seasonal stress management for transport and competition schedules.
- Weight Management:Metabolic conditioning for easy-keeper breeds and post-injury rehabilitation.
Performance Enhancement commands premium margins; Recovery Support is expanding most quickly.
End User:
Customer type determines regulatory exposure and formulation complexity requirements.
- Racehorse Owners:High-value animals justify premium pricing for clinically validated ingredients with residue compliance. Florida and Kentucky owners drive demand for FDA Center for Veterinary Medicine compliant formulations with export-grade documentation.
- Trainers:Daily management decisions prioritize measurable performance metrics and feed conversion efficiency. Dubai and Australian racing stables are consolidating purchases through vertically integrated service platforms.
- Breeders:Long-horizon investments in foal development sustain demand for reproductive and growth formulations.
- Equestrian Centers:Mixed-discipline operations require flexible multi-purpose supplement protocols.
- Veterinary Clinics:Prescription-adjacent products with clinical validation support professional credibility.
- Recreational Riders:Convenience-oriented purchasing through online subscription channels displaces traditional feed dealers.
Racehorse Owners generate the highest revenue per animal; Recreational Riders are gaining share fastest through digital channels.
Distribution Channel:
Supply concentration in specialty retail is fragmenting as digital platforms capture recreational segments.
- Online Platforms:Subscription algorithms personalize dosing based on individual horse workload data. Australian recreational riders and U.S. amateur competitors exceed eighty percent retention where platforms bundle nutrition with farrier and veterinary scheduling.
- Veterinary Pharmacies:Professional credibility anchors premium supplement positioning with clinical validation requirements. German and U.S. veterinarians prescribe these channels for racehorse owners seeking residue-compliant formulations.
- Specialty Stores:Staff expertise supports complex multi-ingredient selection decisions.
- Feed Dealers:Traditional relationships with commercial stables face erosion from digital alternatives.
- Direct Sales:Manufacturer relationships with large breeding operations bypass intermediaries.
- Retail Chains:Mass-market accessibility for basic vitamin and mineral categories.
Veterinary Pharmacies retain the highest margin position; Online Platforms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets: competitive racing cultures in the United States and Germany prioritize clinically validated joint health formulations, while Australian recreational riders favor subscription-based digestive supplement delivery.
United States
Kentucky and Florida racing stables sustain premium purchasing for glucosamine and chondroitin sulfate formulations targeting aging thoroughbreds. The FDA Center for Veterinary Medicine enforces ingredient safety claims that elevate documentation burdens for novel compounds. Ocala's concentrated breeding operations anchor demand for residue-compliant export-grade supplements.
Germany
Bavarian and North Rhine-Westphalian breeding farms drive demand for trace mineral formulations tied to foal development metrics. The EU Feed Additives Regulation mandates pre-market authorization that favors established suppliers with veterinary pharmacy heritage. Warendorf's equestrian centers cluster procurement decisions for performance-oriented product lines.
Australia
New South Wales and Victoria recreational riders are consolidating purchases through vertically integrated digital platforms bundling nutrition with veterinary scheduling. The APVMA enforces residue limits that directly shape export-oriented manufacturer formulation choices. Sydney's suburban stables exceed eighty percent subscription retention where personalized dosing algorithms apply.
United Kingdom
Home counties and Cotswolds competitive yards sustain demand for peer-reviewed joint health products with measurable mobility outcomes. The Veterinary Medicines Directorate coordinates with EFSA disclosure requirements that complicate cross-channel label compliance. Newmarket's racing infrastructure anchors premium supplement procurement for thoroughbred operations.
United Arab Emirates
Dubai-based racing stables adopt synbiotic digestive formulations within compressed eighteen-month switching cycles. The Ministry of Climate Change and Environment oversees feed import standards that align with European regulatory frameworks. Meydan's concentrated high-value horse population justifies per-dose cost premiums for microbiome-optimized products.
Global Equine Supplement Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical heritage suppliers commanding veterinary credibility and science-backed validation capacity. The upper tier leverages regulatory dossier expertise and clinical trial infrastructure to secure pre-market authorizations under tightening EU and FDA frameworks. Mid-tier specialists differentiate through subscription platform integration and regional breeding operation relationships. Competitive moves concentrate on portfolio diversification into synbiotic formulations and geographic expansion through residue-limit harmonization across Asia-Pacific racing jurisdictions.
Within the pharmaceutical-heritage tier, Zoetis Services LLC and Boehringer Ingelheim International GmbH exemplify integrated players leveraging veterinary pharmacy credibility to anchor premium positioning with clinicians. Kentucky Equine Research occupies a specialist position, representing the science-backed formulation archetype tied to peer-reviewed thoroughbred performance studies. These three entities collectively illustrate the competitive spectrum from broad regulatory capacity to narrow research depth.
| Leading Market Players |
|---|
| Zoetis Services LLC |
| Boehringer Ingelheim International GmbH |
| Bayer AG |
| Purina Animal Nutrition LLC |
| Vetoquinol S.A. |
| Kentucky Equine Research |
| Farnam Companies Inc. |
| SmartPak Equine LLC |
| Lallemand Inc. |
| Others |
Supply & Pricing Matrix
Marine-derived chondroitin sulfate extraction capacity in coastal processing facilities anchors both supply concentration and price floors across joint health formulations. Scale economies in glucosamine fermentation tighten margin structures for smaller compounders while elevating entry barriers for novel entrants seeking veterinary pharmacy credibility.
Pricing Analysis
Long-term offtake contracts between thoroughbred breeding operations and established manufacturers dominate premium joint health categories, insulating pricing from spot volatility in marine ingredient markets. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated formulations with export documentation from generic maintenance blends. Cost compression in standard-tier digestive aids intensifies as Australian subscription platforms consolidate purchasing power. Recreational riders exhibit highest price sensitivity, while Kentucky racehorse owners absorb per-dose premiums for residue-compliant products.
Supply Chain Analysis
Strait of Hormuz transit underwrites marine-derived chondroitin supply from Southeast Asian fisheries to European compounding facilities. Active ingredient sourcing draws from China for glucosamine fermentation, Iceland for fishmeal processing, and India for botanical extracts. Single-source vulnerability in marine collagen supply exposes joint health margins to fishery quota restrictions. Distribution runs through veterinary pharmacies for premium clinical formulations, while direct-to-consumer platforms capture recreational segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The equine supplement market exhibits cyclical recovery characteristics tied to thoroughbred breeding cycle reinvestment patterns following economic contraction periods.
For Market Incumbents: Compound veterinary credibility advantages by accelerating peer-reviewed clinical validation for synbiotic formulations before EU Feed Additives Regulation pre-market authorization deadlines. Deepen backward integration into terrestrial chondroitin fermentation to offset marine supply volatility. Channel control through veterinary pharmacy relationships remains the critical defensive lever against platform disintermediation. For New Entrants and Emerging Players: Differentiate on subscription algorithm personalization for Australian recreational riders, where eighty percent retention rates signal white-space viability. Target German trace mineral formulations for breeding farms, a segment with limited science-backed competition. A direct-to-consumer platform bundling nutrition with farrier scheduling offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with validated clinical trial infrastructure and regulatory dossier expertise. Long-term viability over the coming decade hinges on microbiome research translation capabilities. Acquisition targets should demonstrate peer-reviewed publication pipelines and veterinary pharmacy channel penetration. The signal to watch is probiotic reclassification rulings across European jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Peer-reviewed validation anchors premium pricing with Kentucky trainers and German veterinarians. |
| Regulatory Approval Pathway | EU Feed Additives Regulation pre-market authorization elevates barriers favoring established dossier capacity. |
| Backward Integration | In-house fermentation of terrestrial chondroitin alternatives reduces marine supply vulnerability. |
| Platform Integration | Subscription algorithms bundling nutrition with veterinary scheduling capture Australian recreational riders. |
| Geographic Expansion | APVMA residue-limit alignment creates formulation templates for Asia-Pacific racing jurisdictions. |
Research Methodology
A spread of perspectives from equine nutritionists, veterinary clinic procurement managers, racing stable trainers, and feed compounder R&D directors converged on the working assumptions driving this analysis. Primary field engagement combined with secondary validation against FDA Center for Veterinary Medicine filings, EU Feed Additives Regulation authorization databases, Australian APVMA residue limit schedules, and thoroughbred performance research publications. Bottom-up segment sizing and top-down market triangulation cross-checked projections across the analysis window.
Segmentation dimensions modeled include product type, application purpose, end-user archetype, and distribution channel structure. CAGRs derive from trend extrapolation anchored to documented veterinary oversight tightening and microbiome research advancement trajectories. Forecast inputs incorporate breeding cycle reinvestment patterns and regulatory authorization pipeline velocities without specifying temporal endpoints.
The analysis sits within stated boundaries; outcomes outside sustained competitive equestrian culture investment or accelerated probiotic reclassification would require recalibration. Forecasts reflect documented assumptions regarding clinical validation capacity and marine ingredient supply stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Lasers Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market
Veterinary
Veterinary Excipients Market
Veterinary
Veterinary Biomarkers Market
Veterinary
Compression Veterinary Bandages Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Bovine Collagen Market
Veterinary
Veterinary Vaccines Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
Animal Antibiotics Market
Veterinary
Veterinary Clostridium Vaccine Market
Veterinary
Veterinary Home Diagnostics Market