
 Veterinary Faecal Filters Market | 2026-2036
Veterinary Faecal Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Faecal Filters Market Analytics
Companion animal diagnostics is broadening its share of veterinary faecal filter consumption, pulling volume away from production animal applications. IDEXX Laboratories leverages its installed base of in-clinic analysers to secure recurring filter purchases. Thermo Fisher Scientific anchors its position through supply contracts with university veterinary teaching hospitals. Zoetis competes by bundling filters with its broader parasitology diagnostics portfolio.
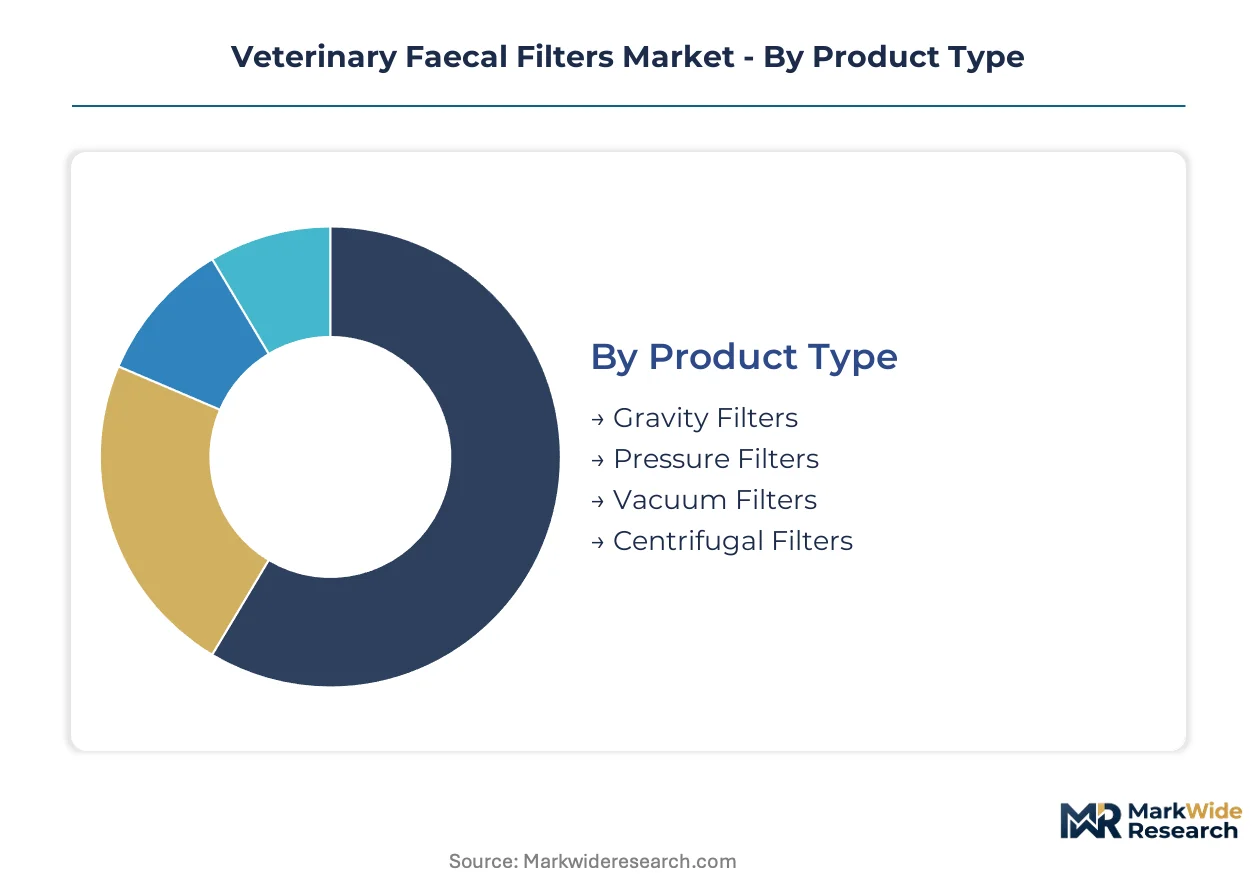
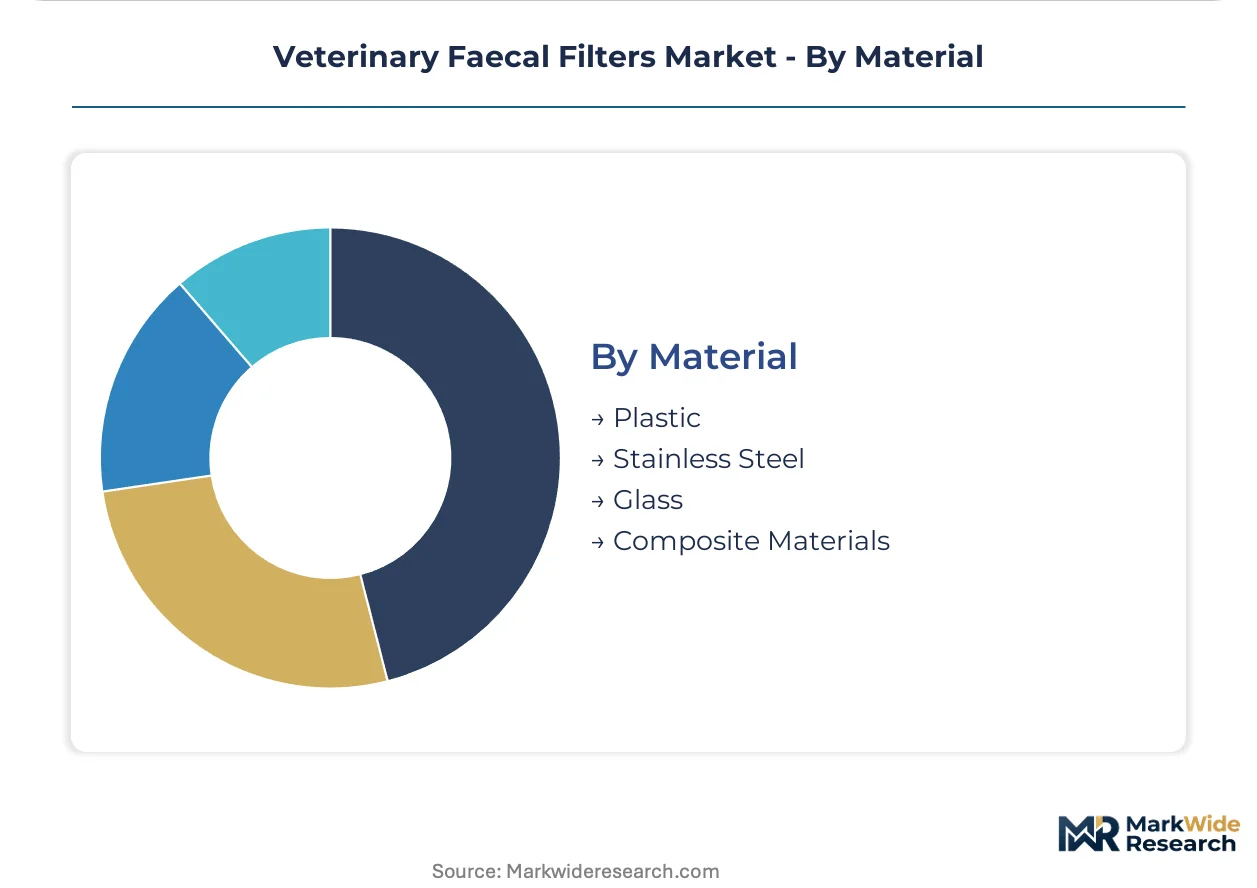
Veterinary faecal filters are porous separation devices, typically constructed from polypropylene or cellulose acetate with pore sizes ranging from 25 to 100 micrometres, designed to concentrate helminth eggs and protozoan oocysts from faecal suspensions for microscopic examination. Gravity filters retain dominant share in routine clinical practice due to their minimal equipment requirements and low per-test cost. Pressure filters are gaining ground in high-throughput diagnostic labs where processing speed directly determines laboratory capacity. Composite materials represent the fastest-growing material segment as manufacturers seek to balance chemical resistance with disposability compliance.
The US FDA's Center for Veterinary Medicine oversees diagnostic device quality standards, while ISO 17025 accreditation requirements shape laboratory procurement specifications for filter consistency and traceability. The EU IVDR extension to veterinary diagnostics is pressuring non-certified suppliers to exit the European market. Stakeholders must monitor regulatory divergence between US and European quality frameworks when configuring product portfolios and manufacturing footprints.
Market Dynamics
Centralized reference laboratory networks in Germany are consolidating procurement specifications, forcing filter manufacturers to standardize pore-size tolerances and batch-traceability protocols across production lines serving veterinary diagnostics.
Growth Catalysts
- EU IVDR Extension:Veterinary diagnostic consumables now face mandatory quality-system audits, accelerating replacement of uncertified suppliers with accredited manufacturers across European diagnostic chains.
- Composite Material Adoption:Polypropylene-cellulose hybrid filters balance chemical resistance against single-use compliance requirements, winning preference from university veterinary teaching hospitals seeking extended reagent compatibility.
- Pressure Filter Migration:High-throughput diagnostic laboratories in Germany are converting from gravity to pressure filtration, compressing processing times and expanding daily test capacity without proportional staffing increases.
Market Restraints
- Petrochemical Input Volatility:Polypropylene resin prices fluctuate with crude oil indices, compressing margin stability for filter manufacturers locked into annual supply contracts with diagnostic laboratory networks.
- Supplier Concentration Risk:Cellulose acetate membrane production concentrates among three European specialty chemical suppliers, creating vulnerability to single-source disruption for manufacturers dependent on certified raw materials.
- Gravity Filter Entrenchment:Small-animal veterinary clinics retain gravity filtration for routine parasitology, limiting addressable market expansion for premium pressure-filter systems despite superior throughput metrics.
Strategic Opportunities
- Point-of-Care Expansion:In-clinic analysers in US companion animal practices create demand for pre-calibrated, single-use filter cassettes that eliminate manual preparation steps for veterinary technicians.
- ISO 17025 Bundling:Accreditation-driven procurement specifications enable filter manufacturers to capture multi-year supply contracts by embedding traceability documentation directly into packaging workflows.
- Telemedicine Integration:Remote veterinary consultation platforms are piloting mail-in faecal sample collection kits, opening direct-to-consumer channels bypassing traditional distributor relationships.
Industry Challenges
- Metrology Skill Scarcity:Pore-size verification using bubble-point testing requires specialized technicians, constraining quality-control throughput at manufacturers scaling production for IVDR compliance deadlines.
- Legacy Equipment Interoperability:Pressure filter adoption stalls where veterinary laboratories operate mixed fleets of analysers requiring proprietary cassette geometries, fragmenting addressable volumes across incompatible formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Faecal Filters Market |
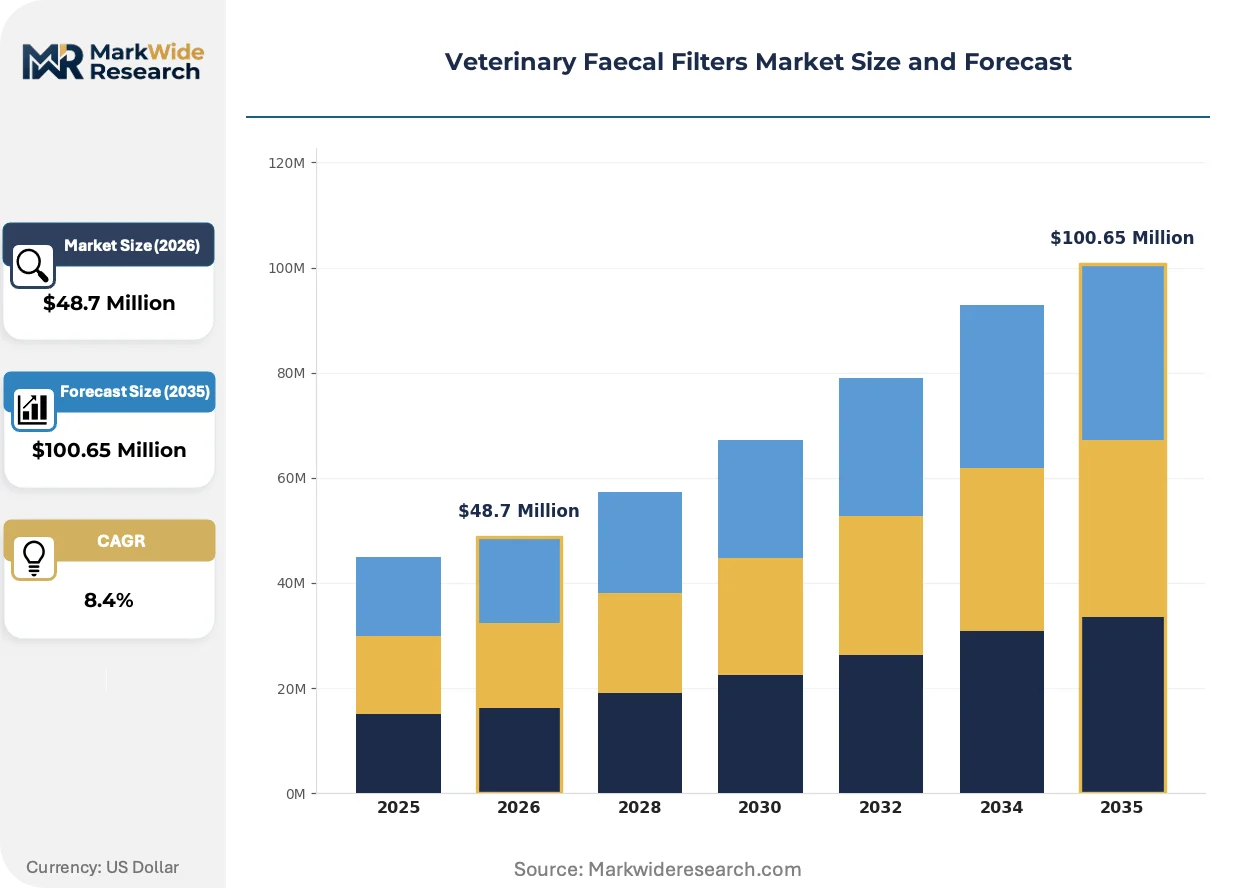
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $100.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity Filters, Pressure Filters, Vacuum Filters, Centrifugal Filters Application: Veterinary Clinics, Animal Hospitals, Research Facilities, Diagnostic Labs End User: Veterinarians, Pet Owners, Research Scientists, Educational Institutions Material: Plastic, Stainless Steel, Glass, Composite Materials |
| Companies Covered | IDEXX Laboratories, Inc., Zoetis Inc., Thermo Fisher Scientific Inc., Woodley Equipment, DiaSys, Jorgensen Laboratories, Kruuse, DeLaval, Lely, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Faecal Filters Market Evolving Landscape
Digital imaging integration and automated parasite detection algorithms are compressing the diagnostic workflow from sample preparation to result reporting, restructuring equipment purchasing criteria across veterinary laboratory tiers.
Automated sedimentation systems are automating the concentration step previously performed manually by veterinary technicians. Reference laboratories in Germany and the Netherlands are deploying these platforms to standardize helminth egg recovery rates across multiple technician shifts. The technology is automating quality-control documentation, reducing the labor burden associated with ISO 17025 audit preparation.
REACH restrictions on phthalate plasticizers are compelling filter manufacturers to reformulate polypropylene masterbatches for European market access. The regulation is forcing migration toward bio-based plasticizers in cellulose acetate composites, extending material validation timelines by six to nine months for suppliers lacking pre-certified alternatives. Veterinary diagnostic OEMs with captive polymer compounding capabilities are absorbing compliance costs internally to protect market position.
Consolidated purchasing by multi-site veterinary groups is compressing supplier negotiation cycles from annual to quarterly intervals. Independent diagnostic laboratories in the US Midwest are responding by forming regional buying cooperatives to match volume discounts previously exclusive to national chains. The shift is most visible among companion animal specialty practices where parasitology screening volumes justify dedicated procurement staff.
Veterinary Faecal Filters Market Segmentation
Veterinary faecal filter procurement patterns diverge sharply across clinical settings, with equipment upgrade cycles and regulatory compliance timelines dictating segment-level demand trajectories. Understanding these fault lines enables manufacturers to align R&D pipelines with replacement waves rather than greenfield installations.
Product Type:
Upgrade cycles vary from immediate consumable replacement to multi-year capital equipment refresh, creating tiered revenue predictability across filtration technologies.
- Gravity Filters:Polypropylene or cellulose acetate devices relying on gravitational sedimentation with pore sizes of 25-100 micrometres. Small-animal veterinary clinics in Germany and the United States retain these for routine parasitology due to minimal capital requirements and technician familiarity, though throughput ceilings constrain expansion.
- Pressure Filters:Pneumatic or hydraulic systems compressing processing times by 60-80% versus gravity methods. High-throughput diagnostic laboratories in the Netherlands and university veterinary hospitals are converting to these systems to expand daily test capacity without proportional staffing increases.
- Vacuum Filters:Negative-pressure systems enabling rapid sample concentration through membrane suction. Research facilities with intermittent high-volume screening needs deploy these for seasonal parasite surveillance studies.
- Centrifugal Filters:Spin-based separation devices integrating directly with automated sedimentation platforms. Reference laboratories piloting these in Germany and Switzerland seek standardized helminth egg recovery rates across technician shifts.
Volume placements concentrate in Gravity Filters; the faster expansion belongs to Pressure Filters.
Application:
Customer procurement sophistication scales with test volume, fragmenting pricing power across facility tiers.
- Veterinary Clinics:Companion animal practices with 3-5 daily parasitology tests favoring pre-calibrated, single-use cassettes. US Midwest independent clinics are forming regional buying cooperatives to match volume discounts previously exclusive to national chains.
- Animal Hospitals:Multi-specialty facilities with dedicated laboratory staff and ISO 17025 accreditation requirements. These sites demand embedded traceability documentation in packaging workflows, enabling multi-year supply contract capture.
- Research Facilities:University and pharmaceutical sites requiring extended reagent compatibility and chemical resistance. REACH restrictions on phthalate plasticizers are compelling reformulation of polypropylene masterbatches for European market access.
- Diagnostic Labs:Centralized reference networks consolidating procurement specifications across multiple sites. German laboratory networks are standardizing pore-size tolerances and batch-traceability protocols, forcing manufacturers to harmonize production lines.
Procurement concentration sits with Diagnostic Labs; the steepest expansion trajectory runs through Veterinary Clinics.
End User:
Technical capability gaps between user categories drive product simplification versus performance specialization.
- Veterinarians:Licensed practitioners requiring minimal preparation steps for in-clinic analysers. IDEXX Laboratories leverages its installed base to secure recurring filter purchases through integrated consumable programs.
- Pet Owners:Direct-to-consumer segment emerging through telemedicine-integrated mail-in sample collection kits. Remote veterinary consultation platforms are piloting these channels, bypassing traditional distributor relationships.
- Research Scientists:Academic and pharmaceutical investigators prioritizing reproducibility and publication-grade documentation. Thermo Fisher Scientific anchors position through supply contracts with university veterinary teaching hospitals.
- Educational Institutions:Veterinary schools training students on standardized protocols. These sites favor composite material filters balancing chemical resistance with disposability compliance for extended teaching laboratory use.
Current volume concentrates with Veterinarians; Research Scientists are gaining share fastest.
Material:
Regulatory compliance timelines and raw material certification requirements are extending validation cycles, advantaging suppliers with captive compounding capabilities.
- Plastic:Polypropylene and cellulose acetate formulations dominating routine clinical practice. Petrochemical input volatility compresses margin stability for manufacturers locked into annual supply contracts with diagnostic laboratory networks.
- Stainless Steel:Reusable frames and housings for pressure filtration systems in high-throughput settings. German reference laboratories specify these for durability under continuous operation.
- Glass:Borosilicate components for specialized microscopy applications requiring optical clarity. Limited to research facilities with dedicated parasitology microscopy suites.
- Composite Materials:Polypropylene-cellulose hybrids and bio-based plasticizer formulations. These represent the fastest-growing material segment as manufacturers balance chemical resistance against single-use compliance requirements under EU IVDR frameworks.
Production volume clusters in Plastic; Composite Materials are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Leibniz Science Campus for Livestock Health in Lower Saxony concentrates veterinary diagnostic R&D, drawing filter manufacturers toward German research clusters. Centralized reference laboratory networks in Germany, the Netherlands, and Switzerland standardize procurement specifications, creating regional demand concentration around ISO 17025-accredited facilities.
Germany
Centralized reference laboratory networks in Bavaria and North Rhine-Westphalia consolidate procurement specifications, forcing manufacturers to harmonize pore-size tolerances across production lines. The EU IVDR extension mandates quality-system audits for veterinary diagnostic consumables, accelerating replacement of uncertified suppliers. The Leibniz Institute for Farm Animal Biology in Dummerstorf anchors parasitology standardization efforts, piloting automated sedimentation platforms for helminth egg recovery.
United States
Companion animal specialty practices in the Midwest and Southeast drive demand for pre-calibrated, single-use filter cassettes compatible with in-clinic analysers. The FDA Center for Veterinary Medicine oversees diagnostic device quality standards, shaping laboratory procurement specifications for filter consistency. Regional buying cooperatives among independent clinics in Ohio and Illinois match volume discounts previously exclusive to national veterinary chains.
Netherlands
High-throughput diagnostic laboratories in Utrecht and Rotterdam convert from gravity to pressure filtration, compressing processing times to expand daily test capacity. The Dutch Food and Consumer Product Safety Authority enforces traceability requirements for veterinary diagnostic consumables under EU harmonized standards. Wageningen University & Research coordinates European parasitology proficiency testing, influencing filter specification adoption across Benelux laboratory networks.
Switzerland
University veterinary teaching hospitals in Zurich and Bern prioritize composite material filters balancing chemical resistance with single-use compliance. Swissmedic maintains stringent quality requirements for imported diagnostic consumables, extending validation timelines for non-EU suppliers. The Institute of Parasitology at the University of Zurich publishes reference methodologies that shape filter procurement specifications across Alpine veterinary networks.
United Kingdom
Animal hospitals in London and the Southeast demand embedded traceability documentation for ISO 17025 accreditation compliance. The Veterinary Medicines Directorate aligns post-Brexit regulatory frameworks with EU IVDR standards, preserving market access for certified suppliers. The Royal Veterinary College in Hertfordshire trains technicians on standardized parasitology protocols, reinforcing demand for consistent filter performance specifications.
Veterinary Faecal Filters Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with diagnostic OEMs capturing recurring consumable revenue while independent suppliers serve price-sensitive research accounts. The market structure concentrates around three tiers: integrated veterinary diagnostic platforms, specialty consumable manufacturers, and regional distribution intermediaries. Strategic archetypes include captive consumable bundlers, ISO-certified specialty suppliers, and research-focused niche providers. Competitive moves center on backward integration into polymer compounding and multi-year supply contract capture through accreditation bundling.
Among US-based diagnostic platforms, IDEXX Laboratories and Zoetis occupy positions as integrated consumable bundlers leveraging installed bases of in-clinic analysers. Thermo Fisher Scientific exemplifies the research-focused archetype through supply relationships with university veterinary teaching hospitals. These three companies represent distinct competitive vectors: recurring revenue lock-in through equipment integration, parasitology portfolio breadth, and academic research channel anchoring respectively.
| Leading Market Players |
|---|
| IDEXX Laboratories, Inc. |
| Zoetis Inc. |
| Thermo Fisher Scientific Inc. |
| Woodley Equipment |
| DiaSys |
| Jorgensen Laboratories |
| Kruuse |
| DeLaval |
| Lely |
| Others |
Value Network & Pricing Analysis
Metrology technician scarcity in Bavaria and North Rhine-Westphalia widens spreads between premium-certified and economy-grade filter tiers, as bubble-point testing expertise commands wage premiums that manufacturers pass through to ISO 17025-accredited buyers.
Pricing Analysis
Short lead-time premiums command pricing power over spot inventory discounts in European procurement cycles. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and batch-traceability depth. Price differentiation hinges on IVDR compliance documentation and pore-size tolerance guarantees. Pricing pressure stems from petrochemical input volatility compressing margins on polypropylene formulations. Small-animal veterinary clinics in the US Midwest exhibit highest price sensitivity through cooperative buying structures, while German reference laboratories accept premiums for harmonized specifications.
Supply Chain Analysis
Reverse logistics for stainless steel pressure-filter housings enables refurbishment cycles that extend asset life in German university hospitals. Raw material supply concentrates in Germany, the Netherlands, and Belgium for cellulose acetate membrane production. Filter manufacturing draws from polypropylene resin feedstocks and specialty cellulose pulp inputs. Single-source vulnerability sits with three European specialty chemical suppliers certified for IVDR-compliant membrane production. Distribution runs through regional veterinary distributors and direct contracts with centralized laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellulose acetate membrane production capacity constraints prop pricing premiums for IVDR-certified filters, creating supply-constrained market dynamics through the projection horizon.
For Market Incumbents: Deploy backward integration into polymer compounding to absorb REACH compliance costs internally. Capture multi-year supply contracts by embedding ISO 17025 traceability documentation directly into packaging workflows. Counter pressure-filter margin erosion by standardizing cassette geometries across mixed analyser fleets in European reference laboratories. For New Entrants and Emerging Players: Automated sedimentation platform compatibility offers entry into German and Dutch high-throughput diagnostic laboratories converting from gravity filtration. Target point-of-care pre-calibrated cassettes for US companion animal practices seeking technician workflow simplification. Pursue telemedicine-integrated mail-in kit channels bypassing traditional distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with captive consumable bundlers given recurring revenue lock-in through in-clinic analyser installed bases. Five-to-ten year viability favors manufacturers with captive polymer compounding capabilities navigating extended EU IVDR validation timelines. Monitor German reference laboratory network consolidation as early signal for procurement specification harmonization waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of REACH-compliant masterbatches protects margin position against cellulose acetate supplier concentration. |
| ISO 17025 Documentation Bundling | Embedded traceability workflows capture multi-year contracts with German animal hospitals facing accreditation audits. |
| Pressure Filter Cassette Standardization | Unified geometries reduce fragmentation across mixed analyser fleets in Dutch high-throughput laboratories. |
| Telemedicine Kit Channel Development | Direct-to-consumer mail-in collection bypasses distributor markups in US companion animal segment expansion. |
| Automated Sedimentation Platform Partnership | Integration with German reference laboratory pilot programs secures volume placement ahead of workflow conversion waves. |
Research Methodology
Document review covered EU IVDR implementation guidance, FDA Center for Veterinary Medicine quality standards, and ISO 17025 accreditation protocols, complemented by interviews with diagnostic laboratory procurement managers, veterinary clinic practice owners, polymer compounding technical directors, and regulatory affairs specialists at filter manufacturers. Secondary sources included customs trade data for polypropylene and cellulose acetate imports, SEC filings from listed veterinary diagnostic platforms, and German federal procurement registry records. Bottom-up test volume estimates from veterinary clinic density data were triangulated against top-down filter consumption projections from centralized laboratory network capacity.
Segment-level outputs across product type, application, end user, and material categories were generated through the projection horizon. Modeled dimensions included filtration technology upgrade cycles, regulatory compliance tier migration patterns, and regional laboratory network consolidation trajectories. CAGRs were derived from replacement rate assumptions tied to equipment depreciation schedules and consumable attach rates. Industry-specific inputs incorporated EU IVDR audit timeline probabilities and REACH bio-based plasticizer substitution curves.
Several conditions sit outside the modeled scope, including abrupt petrochemical price shocks, single-source cellulose acetate supplier disruptions, and accelerated gravity-to-pressure filter conversion rates beyond historical equipment replacement patterns. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and laboratory accreditation maintenance rates. Practitioners should monitor German reference network procurement specification releases and FDA guidance document revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Pet Cremation Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Global Animal Intestinal Health Market
Veterinary
Veterinary Wound Sprays Market
Veterinary
Isoxazoline Market
Veterinary
North America and Europe Veterinary Telehealth Market
Veterinary
Animal Drug Compounding Market
Veterinary
Companion Animal Drugs Market
Veterinary
Veterinary Disinfectants Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Bovine Mastitis Market
Veterinary
Japan Veterinary Healthcare Market