
 Vet Software Market | 2026-2036
Vet Software Market Size, Share, and Industry Trends Forecast 2026-2036
Vet Software Market Insights
Buyer concentration among veterinary service providers is pivoting as corporate ownership groups absorb independent practices, creating procurement power that favors integrated software suites over point solutions. IDEXX Laboratories, Inc. leverages its diagnostic hardware footprint to bundle practice management subscriptions, while Covetrus anchors distribution through its pharmaceutical supply chain relationships. Nordhealth competes on cloud-native architecture designed for multi-clinic operators, and Cencora Inc. extends its wholesale infrastructure into software-enabled inventory management for veterinary customers.
Veterinary software encompasses digital platforms that manage clinical workflows, patient records, billing, and scheduling across animal health service providers, typically integrating with laboratory information systems and diagnostic imaging equipment through HL7 or proprietary APIs. Cloud-based deployment now dominates new implementations, displacing on-premise servers that burden smaller clinics with IT maintenance overhead. Practice Management systems capture the largest revenue share by automating appointment scheduling, inventory tracking, and client communications across high-volume operations. Electronic Health Records represent the fastest-growing product category as regulators mandate interoperable patient data exchange between primary care veterinarians and specialty referral hospitals.
The FDA Center for Veterinary Medicine governs software used in diagnostic device interfaces, while the USDA Animal and Plant Health Inspection Service sets traceability standards affecting herd health management platforms. State veterinary medical boards increasingly require audit trails in electronic prescribing modules, pushing vendors toward compliant architecture by design. Stakeholders must monitor how corporate practice consolidation reshapes vendor selection criteria, as centralized procurement teams prioritize API extensibility and cross-platform data portability over legacy brand loyalty.
Market Dynamics
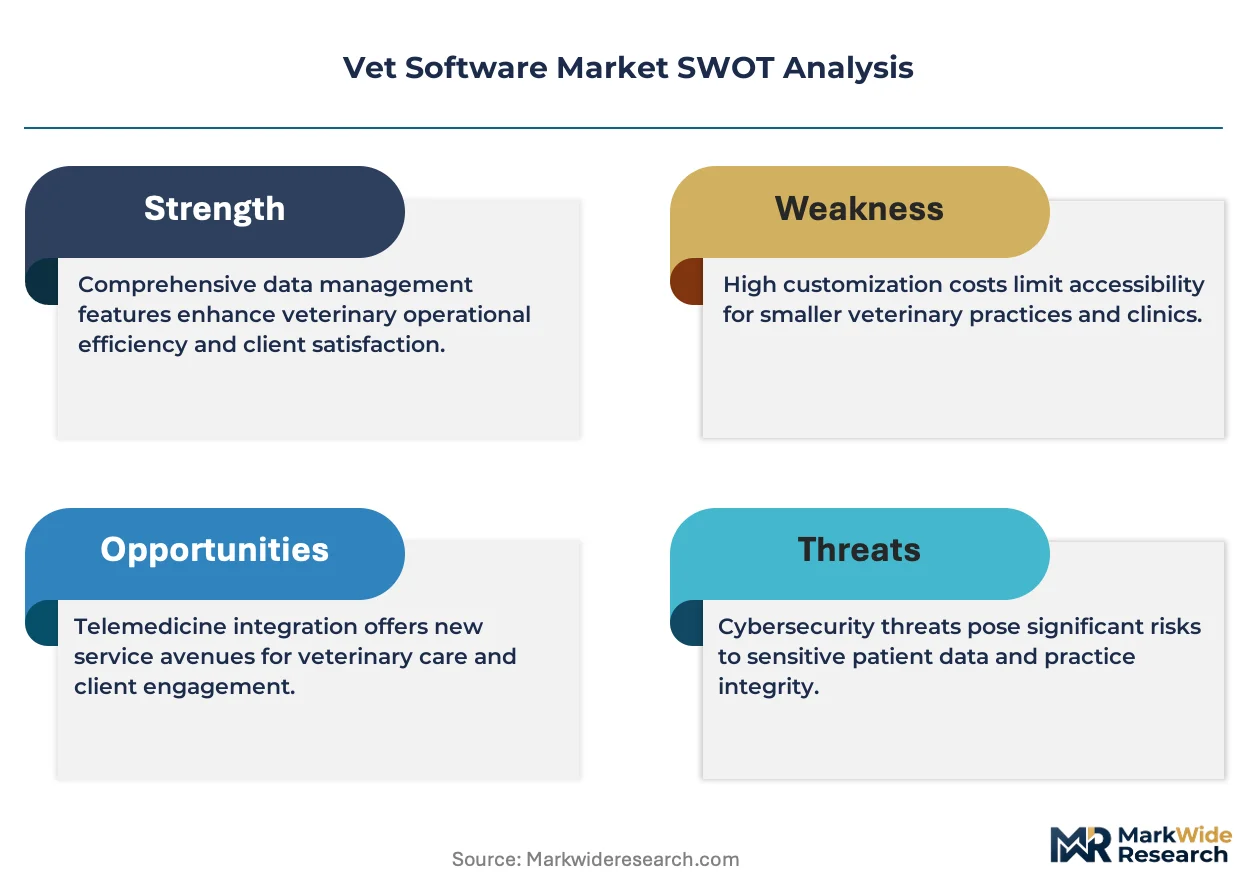
Corporate veterinary group consolidation is compressing vendor selection cycles and favoring cloud-native platforms with open APIs over legacy on-premise systems that isolate patient data across locations.
Growth Catalysts
- HL7 FHIR Interoperability Mandates:The FDA Center for Veterinary Medicine is tightening oversight of diagnostic device interfaces, compelling software vendors to build standardized data exchange protocols that accelerate referral hospital coordination.
- Multi-Site Practice Management:Corporate ownership groups operating hundreds of locations require centralized inventory visibility and unified client communication platforms that single-clinic solutions cannot deliver.
- Cloud Migration:Veterinary clinics are abandoning server maintenance burdens for subscription-based deployment models that reduce IT overhead and enable remote access to patient records.
Market Restraints
- Input Cost Volatility:Cybersecurity infrastructure investments for HIPAA-compliant cloud hosting have risen sharply, squeezing margins for mid-tier software vendors competing against well-capitalized diagnostic equipment bundlers.
- Supply Concentration Risk:Diagnostic imaging and laboratory information system APIs are dominated by a narrow set of hardware manufacturers, creating integration dependencies that limit software vendor flexibility.
- Regulatory Friction:State veterinary medical boards impose inconsistent electronic prescribing audit trail requirements, forcing vendors to maintain jurisdiction-specific compliance modules that fragment development resources.
Strategic Opportunities
- Telemedicine Expansion:The USDA Animal and Plant Health Inspection Service is clarifying telehealth prescribing rules for food animal veterinarians, opening remote consultation platforms for large-animal practices previously excluded from digital workflows.
- AI Diagnostics Convergence:Machine learning algorithms trained on radiographic image databases are integrating with practice management systems to automate preliminary case screening and prioritize urgent referrals.
- Specialty Hospital Networks:Emergency and referral centers in the United States are consolidating into regional networks that demand cross-platform patient record portability, creating procurement openings for interoperability-focused vendors.
Industry Challenges
- Veterinary Informatics Talent Gap:Software vendors struggle to hire professionals who bridge clinical workflow knowledge with cloud architecture expertise, slowing product development cycles.
- Legacy System Integration Complexity:Independent practices migrating from decades-old on-premise servers face data migration risks and staff retraining costs that delay cloud adoption decisions.
- State-by-State Licensure Tracking:Telemedicine platforms must maintain real-time verification of veterinarian credentials across multiple jurisdictions, adding operational overhead to multi-state deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vet Software Market |
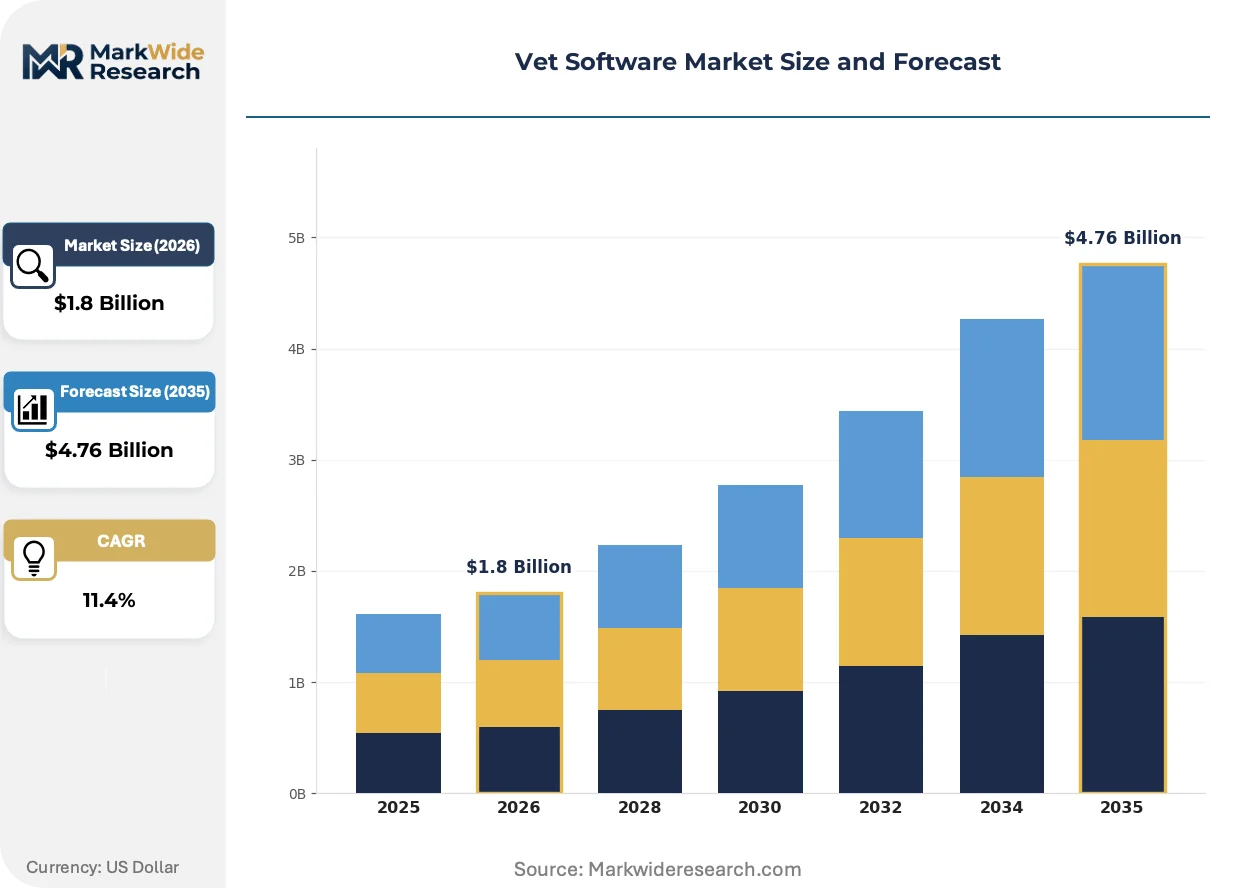
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Practice Management, Electronic Health Records, Billing Solutions, Appointment Scheduling End User: Veterinary Clinics, Animal Hospitals, Mobile Vet Services, Research Laboratories Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Service Type: Technical Support, Training Services, Software Maintenance, Consulting |
| Companies Covered | IDEXX Laboratories, Inc., Covetrus, Nordhealth, Cencora Inc., Carestream Health, DaySmart Software, Animal Intelligence Software, Antech Diagnostics, Inc., Patterson Companies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vet Software Market Trends and Innovations
Artificial intelligence and machine learning capabilities are embedding into diagnostic workflows, while regulatory pressure on data interoperability accelerates platform consolidation among vendors serving corporate practice groups.
Embedded AI radiology tools are integrating with cloud-based practice management systems to flag abnormal imaging findings before specialist review. Emergency veterinary hospitals are deploying these capabilities to triage critical cases during overnight shifts. This technology is integrating diagnostic hardware, software platforms, and clinical decision support into unified workflows that compress time-to-treatment metrics.
The FDA Center for Veterinary Medicine is expanding oversight of software-as-a-medical-device classifications for diagnostic algorithms. Vendors must now submit premarket notifications for AI tools that interpret laboratory results or imaging studies. Specialty referral hospitals in the United States are responding by demanding vendor documentation of regulatory clearance status before procurement.
Subscription-based pricing models are displacing perpetual license structures as corporate procurement teams prioritize operational expenditure predictability. Centralized IT departments at multi-site veterinary groups are negotiating enterprise agreements that bundle practice management, telemedicine, and client communication tools. This transition is most visible among corporate groups operating across the United States, where standardized technology stacks reduce training costs during clinic acquisitions.
Vet Software Market Segmentation
Veterinary software procurement patterns diverge sharply across buyer types and deployment preferences, with corporate consolidation favoring integrated suites while independent practices prioritize modular point solutions. Understanding these fault lines reveals where vendor R&D resources generate disproportionate returns.
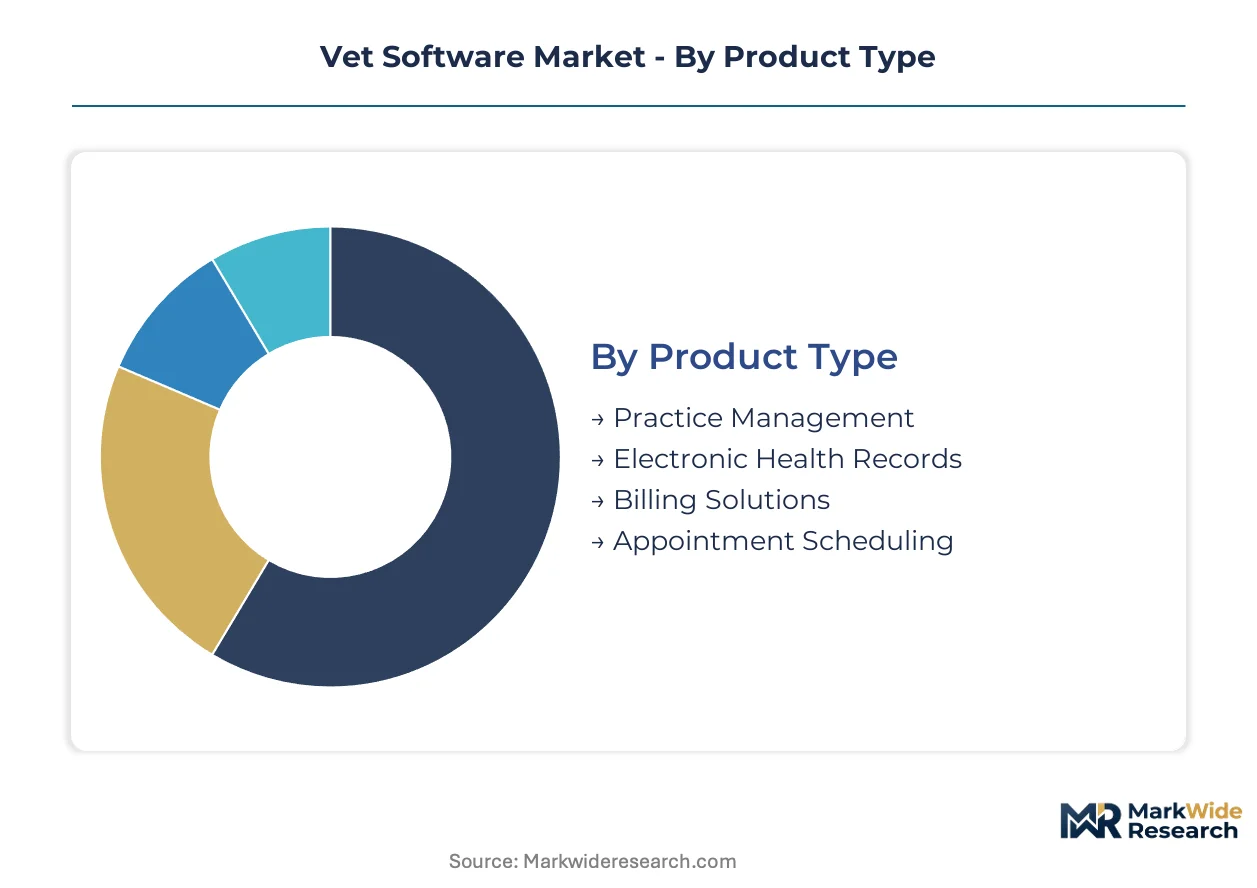
Product Type:
Buyer sophistication separates those seeking workflow automation from those demanding clinical intelligence layers.
- Practice Management:Comprehensive platforms orchestrate appointment scheduling, inventory tracking, billing cycles, and client communications through unified dashboards. Corporate veterinary groups operating across the United States deploy these systems to standardize operations during clinic acquisitions, compressing onboarding timelines for newly absorbed locations.
- Electronic Health Records:Digital patient charting systems capture diagnostic histories, treatment protocols, and prescription records with structured data fields enabling cross-platform exchange. Specialty referral hospitals in the United States mandate these capabilities to satisfy FDA Center for Veterinary Medicine interoperability requirements for diagnostic device interfaces.
- Billing Solutions:Revenue cycle modules automate insurance claim submission, payment processing, and accounts receivable tracking for high-volume practices.
- Appointment Scheduling:Client-facing booking engines integrate with reminder systems and telemedicine portals to reduce no-show rates.
Volume sits with Practice Management; growth tilts toward Electronic Health Records.
End User:
Operational scale determines whether buyers prioritize standardization or customization flexibility.
- Veterinary Clinics:Primary care facilities serving companion animals require streamlined workflows for routine wellness visits, vaccine administration, and minor procedures. Multi-site corporate operators in the United States favor cloud-native platforms that centralize inventory visibility across dozens of locations.
- Animal Hospitals:Emergency and specialty centers demand intensive care unit monitoring integration, advanced imaging archival, and referral coordination tools. These facilities in the United States are consolidating into regional networks that require cross-platform patient record portability.
- Mobile Vet Services:Field-based practitioners need offline-capable applications with GPS routing and portable diagnostic device synchronization.
- Research Laboratories:Academic and pharmaceutical facilities require audit trails, protocol management, and regulatory submission support.
Procurement concentrates with Animal Hospitals; expansion tilts toward Mobile Vet Services.
Deployment:
IT infrastructure maturity and capital constraints shape architecture decisions across buyer tiers.
- Cloud-Based:Browser-accessible platforms eliminate server maintenance burdens while enabling remote record access from any location. Corporate veterinary groups in the United States are abandoning on-premise installations to reduce IT overhead during rapid expansion.
- SaaS:Subscription pricing models convert capital expenditure to predictable operational outlays favored by private equity-backed practice consolidators. These arrangements bundle automatic updates and security patching that independent clinics struggle to maintain independently.
- On-Premise:Local server installations persist among rural practices with unreliable internet connectivity or stringent data sovereignty requirements.
- Hybrid:Mixed architectures retain sensitive records locally while pushing client communications and scheduling to cloud tiers.
Adoption clusters in Cloud-Based; momentum builds fastest in SaaS.
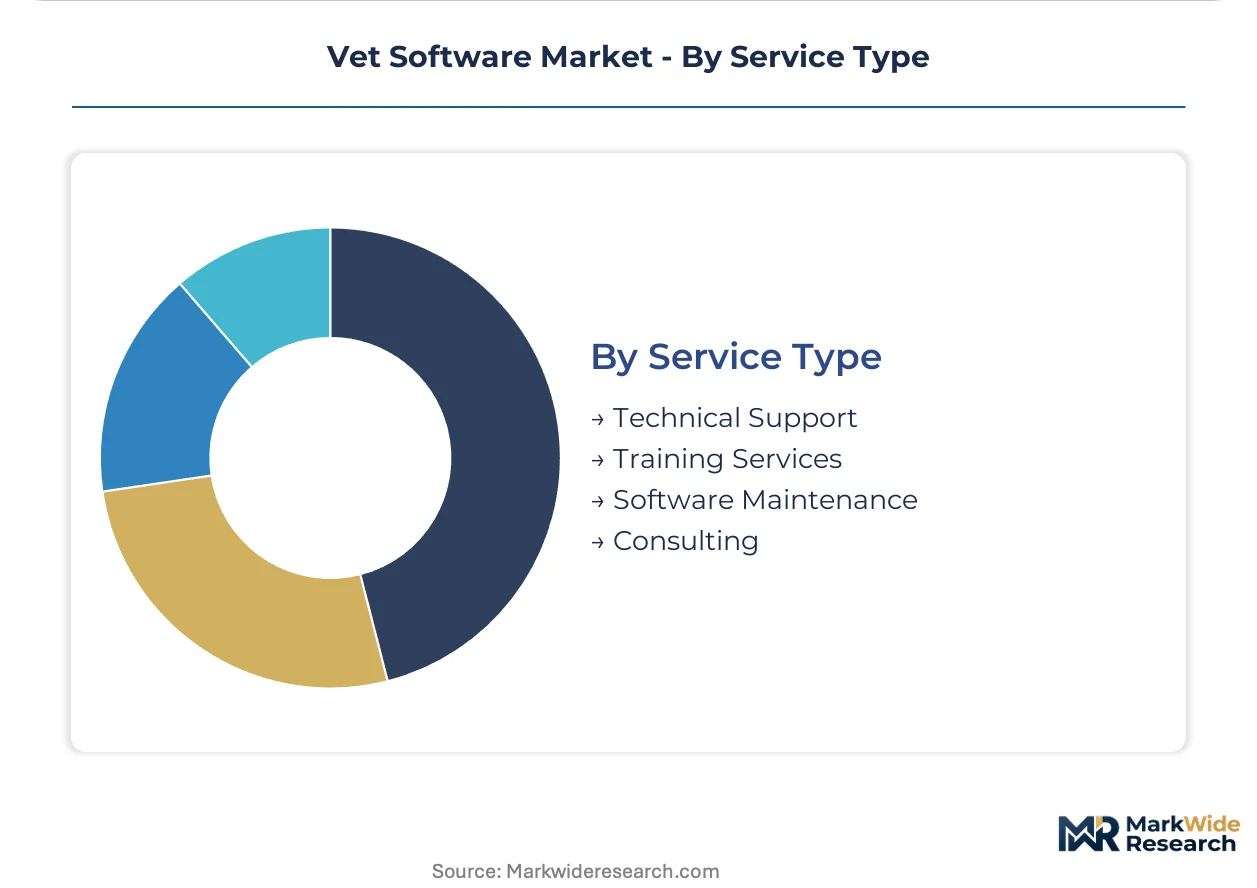
Service Type:
Internal technical capabilities determine whether buyers self-manage or outsource ongoing platform support.
- Technical Support:Help desk services resolve integration failures, data corruption incidents, and user access issues through phone, chat, and remote diagnostic tools. Corporate IT departments in the United States negotiate enterprise service level agreements guaranteeing response times during critical system outages.
- Training Services:Onboarding programs cover workflow configuration, staff certification, and change management during platform transitions. These services prove essential for independent practices migrating from decades-old legacy systems with entrenched user habits.
- Software Maintenance:Update subscriptions deliver security patches, regulatory compliance modules, and feature enhancements.
- Consulting:Professional services optimize workflow design, data migration strategies, and third-party integration architecture.
Revenue concentrates in Technical Support; expansion accelerates in Training Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate veterinary groups in the United States absorb independent practices at accelerating pace, concentrating procurement power among multi-site operators that demand cloud-native platforms. This demand-side shift ripples through developed veterinary markets, reshaping vendor selection criteria toward interoperability and centralized data management.
United States
Mars Veterinary Health and Vetcor operate hundreds of locations requiring unified practice management systems. The FDA Center for Veterinary Medicine enforces diagnostic device interface standards that software vendors must satisfy. Corporate headquarters in Portland and Boston coordinate technology standardization across acquired clinic networks.
Germany
Specialty referral hospitals in Munich and Berlin drive demand for cross-platform patient record exchange. The EMA veterinary medicines framework influences software compliance requirements for pharmaceutical inventory tracking. Baden-Württemberg hosts dense clusters of precision livestock farming operations adopting herd health management platforms.
United Kingdom
Independent practice consolidation accelerates through private equity-backed groups seeking operational standardization. The UK Veterinary Medicines Directorate mandates audit trail capabilities for electronic prescribing modules. London and Southeast England concentrate corporate veterinary operators digitizing multi-site workflows.
Australia
Rural mixed-animal practices adopt mobile-enabled platforms for field-based large animal services. The TGA regulates veterinary software interfaces with diagnostic devices under medical device classification rules. Queensland and New South Wales host expanding corporate groups acquiring regional clinic networks.
Canada
Provincial veterinary medical boards impose varying electronic record standards that complicate multi-jurisdictional deployments. Health Canada oversight of veterinary diagnostic devices affects software integration requirements. Ontario and British Columbia concentrate telemedicine platform adoption for remote agricultural veterinary services.
Vet Software Market Competitive Landscape
United States vendors anchor the diagnostic-integrated tier; European cloud-native specialists hold the multi-site practice management segment. Market structure tilts toward consolidation as corporate procurement teams favor bundled suites over point solutions. Three archetypes dominate: diagnostic equipment bundlers leveraging hardware footprints, pharmaceutical distributors extending into software-enabled inventory, and cloud-native architects purpose-built for scale. Competitive dynamics center on M&A absorption of regional software vendors and API partnership networks with imaging hardware manufacturers.
Within the diagnostic-integrated tier, IDEXX Laboratories, Inc. and Covetrus exemplify hardware-centric bundling strategies that capture procurement decisions at corporate veterinary groups. Nordhealth occupies a position representing cloud-native architecture designed for multi-clinic operators, while Cencora Inc. anchors the pharmaceutical distribution extension archetype. These three patterns illustrate how vendor origin—diagnostic hardware, pure software, or supply chain infrastructure—shapes competitive positioning as buyer concentration accelerates.
| Leading Market Players |
|---|
| IDEXX Laboratories, Inc. |
| Covetrus |
| Nordhealth |
| Cencora Inc. |
| Carestream Health |
| DaySmart Software |
| Animal Intelligence Software |
| Antech Diagnostics, Inc. |
| Patterson Companies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Multi-site corporate veterinary groups operating across the United States negotiate enterprise SaaS contracts that compress pricing power for mid-tier software vendors competing against diagnostic equipment bundlers. Subscription-based deployment models dominate procurement decisions as centralized IT departments prioritize operational expenditure predictability over perpetual license structures.
Pricing Analysis
Volume concentrates in standardized SaaS tiers while margins accrue to vendors bundling diagnostic hardware with practice management subscriptions. Pricing stratifies across enterprise, professional, and entry-level tiers differentiated by API extensibility and multi-location support depth. Cost compression in the mid-market intensifies as IDEXX Laboratories and Covetrus leverage diagnostic footprints to subsidize software pricing. Independent single-clinic practitioners exhibit highest price sensitivity, whereas corporate procurement teams prioritize interoperability over per-seat cost.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscale data center operators in the United States, Ireland, and Singapore with localized hosting for data sovereignty compliance. Software development draws from specialized veterinary informatics talent pools concentrated in North American and Western European technology hubs. Single-source vulnerability emerges from diagnostic imaging API dependencies controlled by narrow hardware manufacturer oligopolies. Distribution runs through direct enterprise sales teams for corporate accounts and value-added resellers serving independent practice segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary software market consolidation accelerates as FDA interoperability mandates and corporate procurement centralization force point-solution vendors toward acquisition or exit. Margin pressure from diagnostic equipment bundlers compresses viable standalone positioning.
For Market Incumbents: Anticipate regulatory complexity expansion by pre-building jurisdiction-specific compliance modules for state veterinary medical board audit trail requirements. Deepen API partnership networks with imaging hardware manufacturers to reduce single-source vulnerability. Prioritize certification investment for FDA Center for Veterinary Medicine software-as-a-medical-device classifications ahead of AI diagnostic tool proliferation.
For New Entrants and Emerging Players: Mobile veterinary services represent the most penetrable buyer archetype, with field-based practitioners underserved by legacy on-premise systems lacking offline capability and GPS routing integration. Target rural mixed-animal practices in Australia and Canada with purpose-built platforms synchronizing portable diagnostic devices. Pursue telemedicine-enabled go-to-market positioning aligned with USDA Animal and Plant Health Inspection Service telehealth prescribing rule clarifications.
For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native architecture specialists with proven multi-clinic deployment track records in the United States. Long-term viability centers on vendors demonstrating API extensibility and cross-platform data portability as corporate procurement criteria harden. Watch FDA premarket notification submission volumes for AI diagnostic algorithms as inflection indicator for regulatory clearance moat value.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies practice management, telemedicine, and client communication tools for Mars Veterinary Health-scale operators. |
| Acquisition of Specialist Firm | Absorbs regional software vendors with established state veterinary medical board compliance modules. |
| Strategic Partnership | Secures diagnostic imaging API access from hardware manufacturers to reduce integration dependency. |
| Product Launch | Introduces FDA-compliant AI radiology tools with premarket notification clearance for emergency hospital triage. |
| Geographic Expansion | Establishes localized cloud hosting in Germany and Australia for data sovereignty compliance. |
Research Methodology
Multi-period observation of corporate veterinary group acquisition velocity, FDA premarket notification submissions, and cloud deployment migration rates anchored the trend analysis, supplemented by interviews with practice management software executives, veterinary clinic IT directors, diagnostic equipment integration specialists, and pharmaceutical distribution technology leads. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, USDA Animal and Plant Health Inspection Service rulemakings, SEC filings of publicly traded veterinary service consolidators, and state veterinary medical board regulatory updates. Bottom-up clinic-level deployment estimates triangulated against top-down vendor revenue segmentation.
Segment-weighting across deployment models, practice scale tiers, and regional regulatory clusters shaped the analytical framework across the analysis window. CAGRs derived from clinician headcount expansion, corporate acquisition pipelines, and cloud infrastructure capacity additions in veterinary-specific hosting environments. Veterinary informatics talent availability and HL7 FHIR implementation timelines served as industry-specific forecast sensitivity inputs.
Revisions become necessary when FDA software-as-a-medical-device classification scope expands materially, corporate veterinary group consolidation pauses, or diagnostic hardware API access terms shift toward exclusivity. Forecasts reflect assumptions about regulatory enforcement consistency and cloud migration completion rates. A small set of named triggers—FDA premarket notification backlogs, state board audit trail mandate divergence, and hyperscaler veterinary data center capacity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Faecal Filters Market
Veterinary
Bovine Mastitis Market
Veterinary
Isoxazoline Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Canine Arthritis Market
Veterinary
Global Animal Vaccine Market
Veterinary
Companion Animal Vaccines Market
Veterinary
Global Pet Obesity Management Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Veterinary Healthcare Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Veterinary Scales Market
Veterinary
Pet Hypothyroidism Therapy Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
Otc Pet Medication Market