
 Bovine Mastitis Treatment System Market | 2026-2036
Bovine Mastitis Treatment System Market Size, Share, and Industry Trends Forecast 2026-2036
Bovine Mastitis Treatment System Market Insights
EU MDR veterinary extensions is broadening compliance obligations for intramammary device manufacturers entering European markets. Zoetis leverages its diagnostic-treatment integration to sustain premium positioning across dairy farm channels. Boehringer Ingelheim Animal Health anchors its portfolio in vaccine-based prevention, competing directly with antibiotic-dependent rivals. Elanco Animal Health differentiates through molecular diagnostic partnerships that reduce treatment cycles.
Bovine mastitis treatment systems encompass pharmaceutical formulations, delivery devices, and diagnostic platforms designed to detect, manage, and resolve intramammary infections in dairy cattle, typically involving intramammary infusions with specific particle size distributions and pH-balanced formulations to preserve milk quality. These systems serve the primary commercial purpose of minimizing somatic cell count elevations and preventing subclinical infection progression that degrades bulk tank milk premiums. Antibiotics retain the largest revenue share within product type segments, though non-antibiotic solutions and herbal treatments are gaining fastest as residue-conscious processors tighten procurement specifications. Intramammary delivery dominates mode share due to direct udder tissue targeting, while optical sensors within technology segments command expanding R&D allocation for real-time infection detection.
FDA veterinary feed directive protocols restrict prophylactic antibiotic use, forcing reformulation toward recovery agents and immunological techniques. EMA and EFSA residue monitoring frameworks shape European product registration timelines and maximum residue limit compliance costs. Stakeholders must monitor regulatory divergence between jurisdictions while building antimicrobial stewardship credentials that secure long-term dairy processor contracts.
Market Dynamics
Antibiotic stewardship mandates are compressing treatment windows and forcing pharmaceutical repositioning toward non-antibiotic alternatives across dairy supply chains. The FDA veterinary feed directive and EMA residue frameworks now determine product viability before clinical efficacy enters the conversation.
Growth Catalysts
- EMA residue monitoring frameworks:European bulk milk processors now require sub-100,000 somatic cell counts, accelerating adoption of optical sensor diagnostics that catch infections before antibiotic intervention becomes necessary.
- Large-scale commercial dairy farms:Automated parlor systems in the United States and New Zealand integrate mastitis detection with milking robotics, creating bundled procurement demand for diagnostic-treatment platforms.
- Precision livestock farming investments:Real-time udder health monitoring via machine vision is overtaking manual California Mastitis Test protocols, particularly in German cooperative dairies with 500+ head operations.
Market Restraints
- Antibiotic withdrawal period costs:Milk discard requirements during and post-treatment compress margins for smallholder operations with limited tank capacity, particularly in seasonal grazing systems.
- Intramammary device supply concentration:Polymer formulation expertise clusters among three European specialty manufacturers, creating single-source vulnerability for pH-balanced infusion delivery systems.
- Diagnostic platform technical limitations:Optical sensors struggle with teat-end debris interference, generating false-positive rates that erode farmer trust and delay treatment decisions.
Strategic Opportunities
- Underpenetrated Indian dairy cooperatives:The National Dairy Development Board's artificial insemination networks offer established distribution infrastructure for mastitis prevention vaccines reaching 2.5 million village-level producers.
- EU Green Deal veterinary pharmaceutical incentives:Biodegradable intramammary delivery tubes qualify for accelerated regulatory review and procurement preference in Dutch and Danish supermarket supply contracts.
- Telemedicine-veterinary convergence:Remote udder health consultation platforms enable diagnostic-treatment bundling without on-farm veterinarian presence, reducing labor costs for isolated Australian pastoral operations.
Industry Challenges
- Veterinary pharmaceutical formulation talent scarcity:Intramammary suspension stability expertise concentrates among aging specialists, constraining R&D pipeline velocity for next-generation non-antibiotic candidates.
- ISO 22000 dairy processor certification timelines:Mastitis treatment residue documentation requirements extend supplier onboarding to 18-24 months, freezing out innovative entrants lacking established quality management systems.
- Legacy herd management software integration friction:New diagnostic platforms require API development for compatibility with decades-old farm data systems, delaying technology adoption and fragmenting health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bovine Mastitis Treatment System Market |
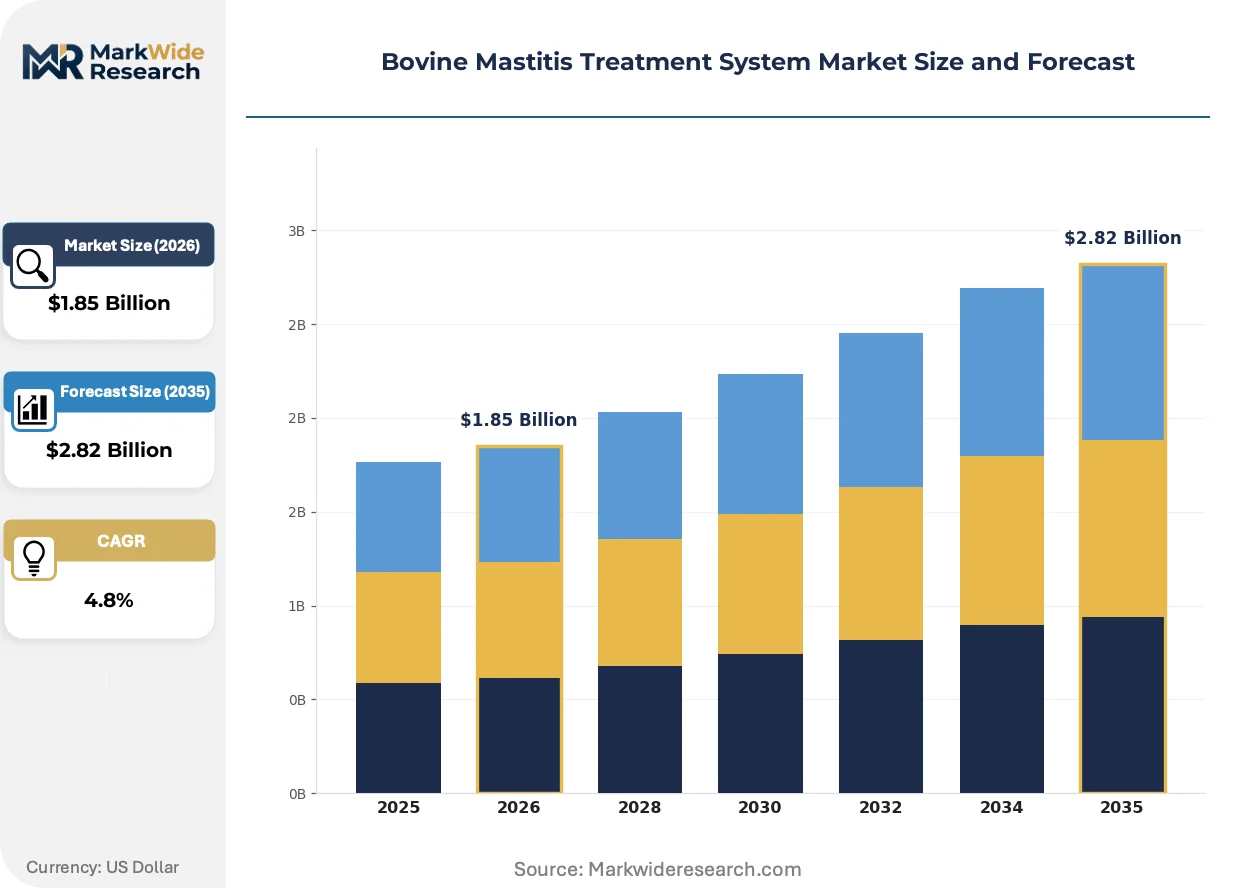
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Recovery Agents, Non-Antibiotic Solutions, Herbal Treatments Delivery Mode: Intradermal, Intramammary, Oral, Topical End User: Dairy Farms, Veterinary Clinics, Animal Hospitals, Research Institutions Technology: Culture Methods, Immunological Techniques, Molecular Diagnostics, Optical Sensors |
| Companies Covered | Elanco Animal Health, HIPRA, Zoetis, Forte Healthcare Ltd., Ecolab Inc., Boehringer Ingelheim Animal Health, Ceva Santé Animale, Neogen Corporation, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bovine Mastitis Treatment System Market Trends and Innovations
Machine vision and molecular diagnostics are compressing the detection-to-treatment interval from days to hours, while regulatory residue thresholds harden faster than formulation science can adapt. These forces are restructuring competitive advantage around data integration rather than compound chemistry alone.
Optical sensor arrays embedded in milking parlor liners are overtaking manual strip-cup inspection as the frontline detection method. Large commercial dairies in Wisconsin and Canterbury now deploy real-time somatic cell count estimation with 94% accuracy against laboratory standards. This compression of diagnostic latency is enabling selective dry cow therapy protocols that reduce blanket antibiotic use by 60% in participating herds.
EU MDR veterinary device extensions now classify intramammary infusion cannulas as Class IIa medical devices, imposing clinical evidence requirements previously reserved for human pharmaceuticals. German and Dutch manufacturers face 18-month registration delays while assembling biocompatibility dossiers. Smaller entrants without existing quality management infrastructure are exiting European markets, concentrating supply among established device specialists with ISO 13485 certification.
Certification-driven procurement now dominates dairy processor supply contracts, with somatic cell count premiums replacing commodity milk pricing in cooperative negotiations. Fonterra's guaranteed payment scheme in New Zealand and Arla's climate and nature program in Denmark explicitly reward mastitis incidence below 15 cases per 100 cows annually. Farmers in these systems now prioritize prevention platforms over reactive treatment, reshaping vendor sales cycles toward annual subscription models for diagnostic monitoring.
Bovine Mastitis Treatment System Market Segmentation
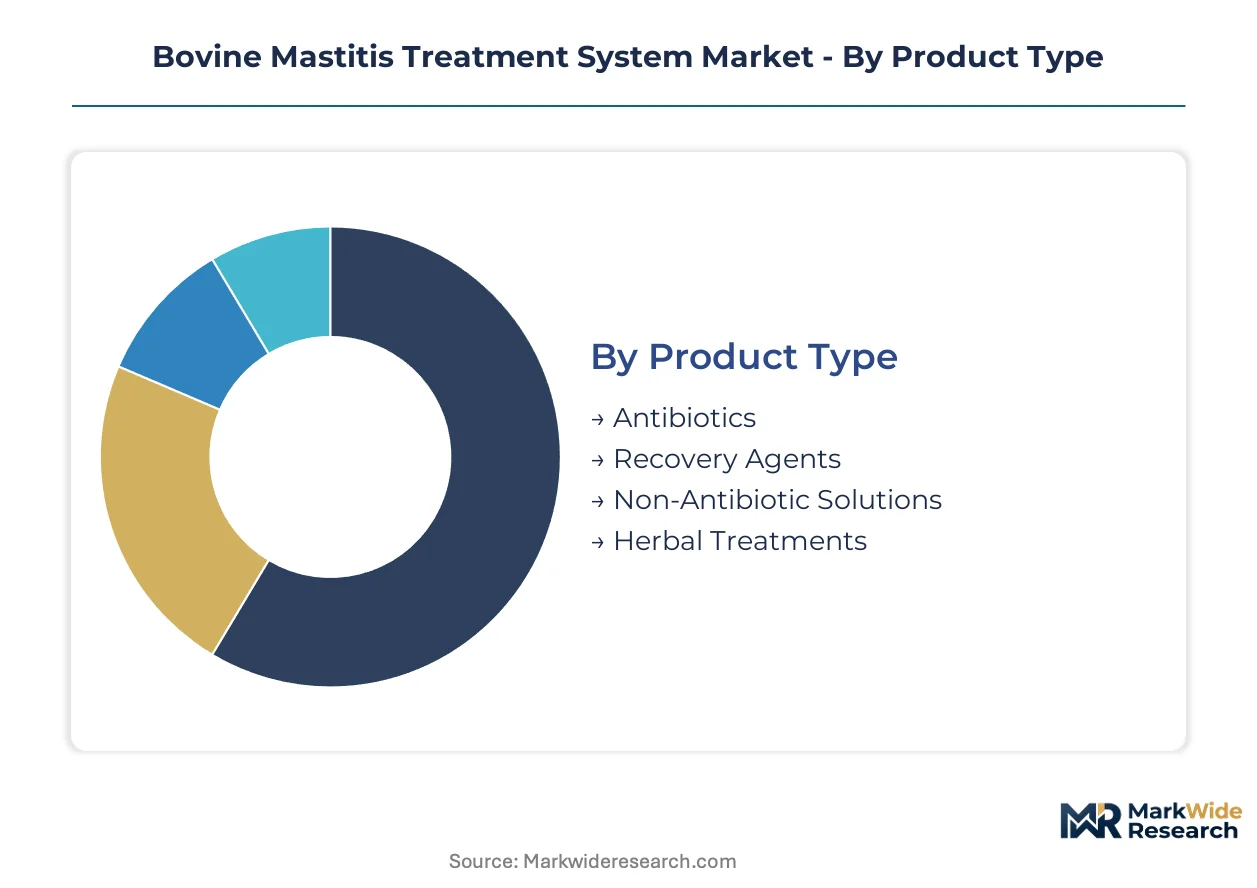
Product architecture in bovine mastitis treatment systems separates volume-driven commodity formulations from premium diagnostic-integrated platforms. Procurement patterns diverge sharply between cost-sensitive cooperative dairies and technology-forward commercial operations seeking residue-free certification. Vendor positioning requires matching segment-specific compliance burdens with formulation capabilities.
Product Type:
Antibiotics command volume share while non-antibiotic alternatives capture margin expansion from processor residue protocols.
- Antibiotics:Intramammary beta-lactam and cephalosporin formulations remain the clinical default for acute gram-positive infections. Demand concentrates in United States large-scale operations where FDA veterinary feed directive compliance costs favor established veterinary prescription channels over preventive alternatives.
- Non-Antibiotic Solutions:Bacteriocins, antimicrobial peptides, and phage therapies target processors with zero-tolerance residue specifications. German and Dutch supermarket supply contracts now mandate these alternatives for premium milk tier qualification, accelerating reformulation investments.
- Recovery Agents:NSAID and corticosteroid combinations reduce inflammation without antimicrobial action. New Zealand pastoral systems favor these for seasonal drying-off protocols.
- Herbal Treatments:Plant-derived formulations with documented udder tissue compatibility serve organic certification pathways. Indian dairy cooperatives trial neem and turmeric extracts through National Dairy Development Board extension networks.
Today's leader: Antibiotics. Tomorrow's challenger: Non-Antibiotic Solutions.
Delivery Mode:
Route selection determines tissue penetration depth, withdrawal period duration, and labor automation compatibility.
- Intramammary:Direct udder infusion via polymer cannulas achieves therapeutic concentrations in milk cistern tissue. Wisconsin and Canterbury robotic milking systems integrate automated infusion ports, bundling delivery hardware with diagnostic platforms.
- Topical:Teat dip and spray formulations dominate prevention protocols. German cooperative dairies with 500+ head operations specify iodine-alternatives for automated post-milking application.
- Oral:Systemic absorption routes serve concurrent systemic infections. Seasonal grazing systems in New Zealand favor oral NSAIDs for labor efficiency.
- Intradermal:Vaccine and immunomodulator administration targets lymphoid tissue. Research institutions in the United States pilot intradermal DNA vaccines for Staphylococcus aureus resistance.
Intramammary delivery anchors current procurement. Topical applications gain fastest from automation integration.
End User:
Customer type dictates regulatory exposure, purchasing consolidation, and technology adoption velocity.
- Dairy Farms:Herd-scale operations from 50 to 5,000 head drive volume demand. United States commercial dairies with automated parlor systems bundle diagnostic-treatment procurement through cooperative buying groups.
- Veterinary Clinics:Mixed-animal practices in rural United States and Germany retain prescription authority for antibiotic distribution. FDA and EMA residue documentation requirements extend their compliance burden.
- Animal Hospitals:University-affiliated facilities handle refractory cases and resistance profiling. Molecular diagnostic partnerships concentrate here before field deployment.
- Research Institutions:Public and private research bodies validate novel formulations. Dutch and Danish veterinary universities lead non-antibiotic efficacy trials under EU Green Deal incentives.
Dairy Farms dominate transaction volume. Veterinary Clinics control antibiotic access gates.
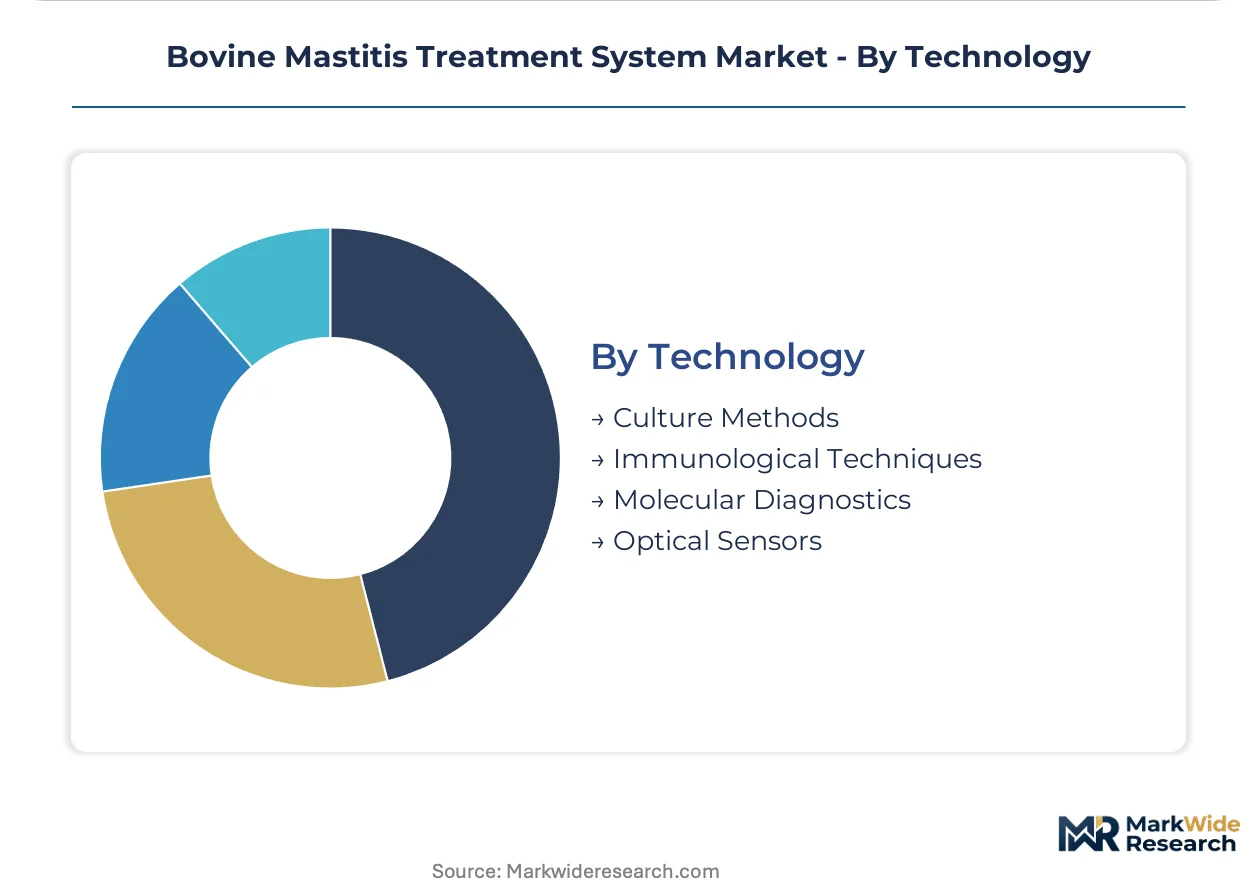
Technology:
Detection modality determines treatment timing precision and antibiotic stewardship compliance.
- Optical Sensors:Machine vision and spectroscopic arrays embedded in milking parlor liners estimate somatic cell count in real time. Large Wisconsin dairies achieve 94% accuracy against laboratory standards, enabling selective dry cow therapy that reduces blanket antibiotic use.
- Molecular Diagnostics:PCR and LAMP platforms identify pathogen species within hours versus days for culture. Elanco Animal Health partnerships target this segment to compress treatment cycles.
- Culture Methods:Traditional bacterial plating remains the regulatory gold standard for residue investigation. EMA and FDA reference laboratories maintain this capability.
- Immunological Techniques:Antibody-based assays detect infection biomarkers. German manufacturers integrate these into handheld devices for field veterinarians.
Optical Sensors lead R&D allocation. Molecular Diagnostics climb fastest on pathogen specificity demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary pharmaceutical formulation expertise concentrates in Germany, the United States, and the Netherlands, with diagnostic platform engineering gravitating toward Wisconsin and Canterbury. These talent clusters anchor regional production of intramammary devices and optical sensor arrays. Dairy processor procurement specifications now determine geographic market access more than manufacturing cost.
United States
Wisconsin's automated parlor systems integrate mastitis detection with milking robotics, creating bundled demand for diagnostic-treatment platforms. FDA veterinary feed directive protocols restrict prophylactic antibiotic use, forcing reformulation toward recovery agents. Large commercial dairies in California deploy machine vision somatic cell count estimation with 94% laboratory accuracy.
Germany
Baden-Württemberg and Lower Saxony host polymer formulation specialists supplying pH-balanced infusion delivery systems. EMA residue monitoring frameworks shape product registration timelines and maximum residue limit compliance costs. Cooperative dairies with 500+ head operations in Bavaria specify iodine-alternative teat dips for automated post-milking application.
New Zealand
Canterbury's pastoral systems favor oral NSAIDs for labor efficiency in seasonal grazing operations. Fonterra's guaranteed payment scheme explicitly rewards mastitis incidence below 15 cases per 100 cows annually. Dairy farmers in Waikato prioritize prevention platforms over reactive treatment, reshaping vendor sales cycles toward subscription diagnostic monitoring.
Netherlands
Dutch supermarket supply contracts mandate non-antibiotic alternatives for premium milk tier qualification, accelerating reformulation investments. EU Green Deal veterinary pharmaceutical incentives qualify biodegradable intramammary delivery tubes for accelerated regulatory review. Wageningen University leads non-antibiotic efficacy trials under public research programs.
India
The National Dairy Development Board's artificial insemination networks offer established distribution infrastructure for mastitis prevention vaccines. Indian dairy cooperatives trial neem and turmeric extracts through village-level extension networks reaching 2.5 million producers. Maharashtra and Gujarat concentrate commercial dairy processing capacity with tightening bulk milk quality standards.
Bovine Mastitis Treatment System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across pharmaceutical, diagnostic, and device segments. The vendor base stratifies into three tiers: multinational animal health conglomerates with integrated diagnostic-treatment portfolios, regional pharmaceutical specialists with intramammary formulation expertise, and emerging technology vendors with sensor-based detection platforms. Dominant competitive moves include diagnostic-treatment bundling through strategic partnerships and backward integration into polymer cannula manufacturing to secure supply.
Within the multinational conglomerate tier, Zoetis, Boehringer Ingelheim Animal Health, and Elanco Animal Health occupy positions defined by portfolio breadth and regulatory infrastructure scale. Zoetis exemplifies the diagnostic-treatment integration archetype, while Boehringer Ingelheim Animal Health represents vaccine-based prevention positioning against antibiotic-dependent rivals. Elanco Animal Health sits within the molecular diagnostic partnership segment, compressing treatment cycles through pathogen specificity. These three entities anchor competitive dynamics through their respective quality management certifications and established dairy processor relationships.
| Leading Market Players |
|---|
| Elanco Animal Health |
| HIPRA |
| Zoetis |
| Forte Healthcare Ltd. |
| Ecolab Inc. |
| Boehringer Ingelheim Animal Health |
| Ceva Santé Animale |
| Neogen Corporation |
| Merck & Co., Inc. |
| Others |
Pricing and Supply Chain Analysis
Polymer formulation costs for pH-balanced intramammary cannulas flow from three European specialty manufacturers through tiered pricing structures that separate automated diagnostic-treatment bundles from commodity antibiotic infusions. Dairy processor somatic cell count premiums now determine which tier a farm supplier can access, with certification documentation extending onboarding timelines and compressing margins for entrants lacking established quality systems.
Pricing Analysis
Bundled diagnostic-treatment platforms command premium positioning against unbundled antibiotic formulations across procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates optical sensor-integrated systems from conventional intramammary infusions and generic teat dips. Price differentiation stems from ISO 13485 certification status and after-sales diagnostic monitoring subscription depth. Pricing pressure stems from EMA residue documentation requirements extending supplier qualification costs. Smallholder cooperatives exhibit highest price sensitivity, while automated parlor operators in Wisconsin and Canterbury prioritize performance specifications over unit cost.
Supply Chain Analysis
Polymer formulation expertise for pH-balanced infusion devices rests on specialty manufacturers concentrated in Germany, the Netherlands, and Switzerland. Raw material dependencies include medical-grade silicone elastomers, antimicrobial polymer additives, and optical sensor semiconductor components. Single-source vulnerability concentrates in European cannula production, with limited qualified alternatives for biocompatibility-certified delivery systems. Distribution runs through veterinary pharmaceutical wholesalers and dairy cooperative buying groups, with direct procurement from large-scale commercial operations gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where residue-free certification specifications from Fonterra and Arla are displacing commodity procurement across premium milk tiers.
For Market Incumbents: Anchor diagnostic-treatment integration through backward integration into polymer cannula manufacturing, securing supply against single-source concentration risks in European specialty formulation. Invest in ISO 13485 certification infrastructure to compress EMA registration timelines that currently freeze out competitors. Defend against molecular diagnostic entrants by deepening machine vision algorithm training datasets across diverse herd conditions. For New Entrants and Emerging Players: Dairy cooperative extension networks in India offer established distribution infrastructure for mastitis prevention vaccines reaching village-level producers. Target underpenetrated pastoral systems in New Zealand with oral NSAID formulations optimized for seasonal labor efficiency. Pursue telemedicine-veterinary convergence platforms to enable remote diagnostic-treatment bundling without on-farm veterinarian presence. For Investors and Strategic Acquirers: Roll-up economics work for regional intramammary device specialists because EMA MDR veterinary extensions are forcing smaller entrants without quality management infrastructure to exit European markets. Long-term viability centers on data integration capabilities rather than compound chemistry alone. Watch for optical sensor false-positive rate improvements as the inflection signal determining farmer trust and platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Cannula Manufacturing | Secures supply chain resilience against three-manufacturer concentration in European specialty formulation. |
| Optical Sensor Platform Integration | Enables real-time somatic cell count estimation that reduces blanket antibiotic use in Wisconsin robotic parlors. |
| EU MDR Veterinary Device Certification | Qualifies intramammary infusion cannulas for accelerated Dutch and Danish supermarket supply contract procurement. |
| Telemedicine-Veterinary Partnership Development | Reduces labor costs for isolated Australian pastoral operations through remote udder health consultation platforms. |
| Non-Antibiotic Formulation Pipeline Expansion | Addresses Fonterra and Arla residue specifications that now mandate alternatives for premium milk tier qualification. |
Research Methodology
Direct dialogue with veterinary pharmaceutical formulation specialists, dairy cooperative procurement managers, intramammary device engineers, and precision livestock farming technology directors grounded qualitative findings in operational realities. Secondary validation drew from FDA veterinary feed directive filings, EMA residue monitoring framework updates, Fonterra guaranteed payment scheme documentation, and ISO 13485 certification registry data. Bottom-up farm-level demand modeling and top-down dairy processor procurement specification analysis were triangulated against trade flow data from German and Dutch veterinary pharmaceutical customs records.
Bottom-up volume modeling tracked intramammary device unit shipments, antibiotic formulation tonnage, and optical sensor installation rates across automated parlor systems. Top-down value analysis calibrated against dairy processor premium payment scheme disclosures and cooperative buying group procurement volumes. Segmentation dimensions included product type, delivery mode, end-user scale tier, and technology detection modality across the projection horizon. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory inflection points including FDA veterinary feed directive implementation and EU MDR veterinary extension timelines.
Revisions become necessary when EMA residue threshold adjustments, optical sensor accuracy breakthroughs, or Indian dairy cooperative infrastructure expansions materialize differently than modeled assumptions anticipate. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption elasticity. A small set of named triggers—FDA antibiotic stewardship rulemaking, EU Green Deal incentive program renewal, and machine vision algorithm validation studies—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Canine Arthritis Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Veterinary Parasiticides Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Veterinary Immunodiagnostics Market
Veterinary
Veterinary Anesthesia Drugs Market
Veterinary
United Kingdom Veterinary Healthcare Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
North America and Europe Veterinary Telehealth Market
Veterinary
Veterinary Equipment and Supplies Market