
 Global Canine Influenza Vaccine Market | 2026-2036
Global Canine Influenza Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Canine Influenza Vaccine Market Foresight
Subscription-based preventive care plans bundled with annual vaccination schedules is broadening how canine influenza vaccines reach pet owners. Boehringer Ingelheim leverages its veterinary distribution network to secure shelf space in independent clinics across North America. Zoetis sustains R&D intensity in recombinant vector platforms, differentiating its pipeline from conventional inactivated approaches. Merck Animal Health anchors its position through long-term supply contracts with corporate veterinary hospital chains.
Canine influenza vaccines are veterinary biologics formulated to induce active immunity against H3N8 and H3N2 influenza A strains in dogs, typically manufactured through egg-based or cell culture propagation followed by inactivation or attenuation. The primary commercial purpose is outbreak prevention in high-density canine environments such as boarding facilities, shelters, and competition venues. Inactivated formulations currently dominate volume due to established safety profiles and regulatory familiarity, though recombinant platforms represent the fastest-growing technology segment as manufacturers seek faster strain-update cycles. Injectable delivery remains the mature standard, while intranasal formulations capture margin pools among breeders and show kennels seeking mucosal immunity without needle stress.
The USDA Center for Veterinary Biologics enforces batch potency testing and facility inspection requirements that shape product development timelines and manufacturing location decisions. FDA oversight of adjuvant components and EPA registration of certain delivery devices add compliance layers that influence formulation design. The EU Veterinary Medicines Regulation and associated EMA guidelines for immunological veterinary medicinal products create parallel but non-identical approval pathways for companies seeking transatlantic distribution. Stakeholders must monitor how evolving strain surveillance data from the USDA National Veterinary Services Laboratories triggers updates to master seed requirements and label claims.
Market Dynamics
The USDA's tightening potency testing protocols under the Virus-Serum-Toxin Act are compressing batch release timelines and forcing manufacturers toward cell culture platforms that deliver more consistent antigen yields than egg-based propagation.
Growth Catalysts
- Kennel boarding mandates:Municipal ordinances in high-density US metropolitan areas now require proof of H3N2 and H3N8 vaccination for facility admission, creating a captive demand pool.
- Recombinant vector platforms:These technologies enable seed strain updates within 12-16 weeks versus 6-9 months for egg-adapted inactivated vaccines, accelerating pandemic response readiness.
- Show dog travel corridors:Interstate competition circuits and international breeding exchanges sustain premium vaccination compliance rates among professional handlers.
Market Restraints
- Adjuvant input volatility:Aluminum hydroxide and saponin-based adjuvant supplies concentrate among three European chemical suppliers, exposing formulation costs to raw material shocks.
- Master seed lag:The USDA National Veterinary Services Laboratories' strain surveillance-to-seed certification pipeline creates 18-24 month delays between emerging variant detection and commercial vaccine availability.
- Point-of-care diagnostics substitution:Rapid PCR and antigen test kits for canine influenza are capturing discretionary spending from preventive vaccination in cost-sensitive shelter environments.
Strategic Opportunities
- Brazilian pet care expansion:ANVISA's streamlined veterinary biologics pathway and São Paulo's rising small-animal clinic density create a greenfield preventive care market.
- Intradermal micro-needle delivery:Convergence of dissolvable microneedle arrays with thermostable vaccine formulations eliminates cold-chain requirements for rural veterinary outreach.
- Corporate veterinary chain consolidation:Subscription wellness plans at Mars Inc. and JAB Holding-owned clinic networks bundle influenza vaccination into recurring revenue streams.
Industry Challenges
- Veterinary immunology talent scarcity:The specialized skill set combining influenza virology with companion animal immunology concentrates at five North American academic institutions, constraining R&D team scaling.
- Multi-strain formulation complexity:Bivalent H3N8/H3N2 vaccines require separate potency assays for each component, doubling analytical development timelines and regulatory submission burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Canine Influenza Vaccine Market |
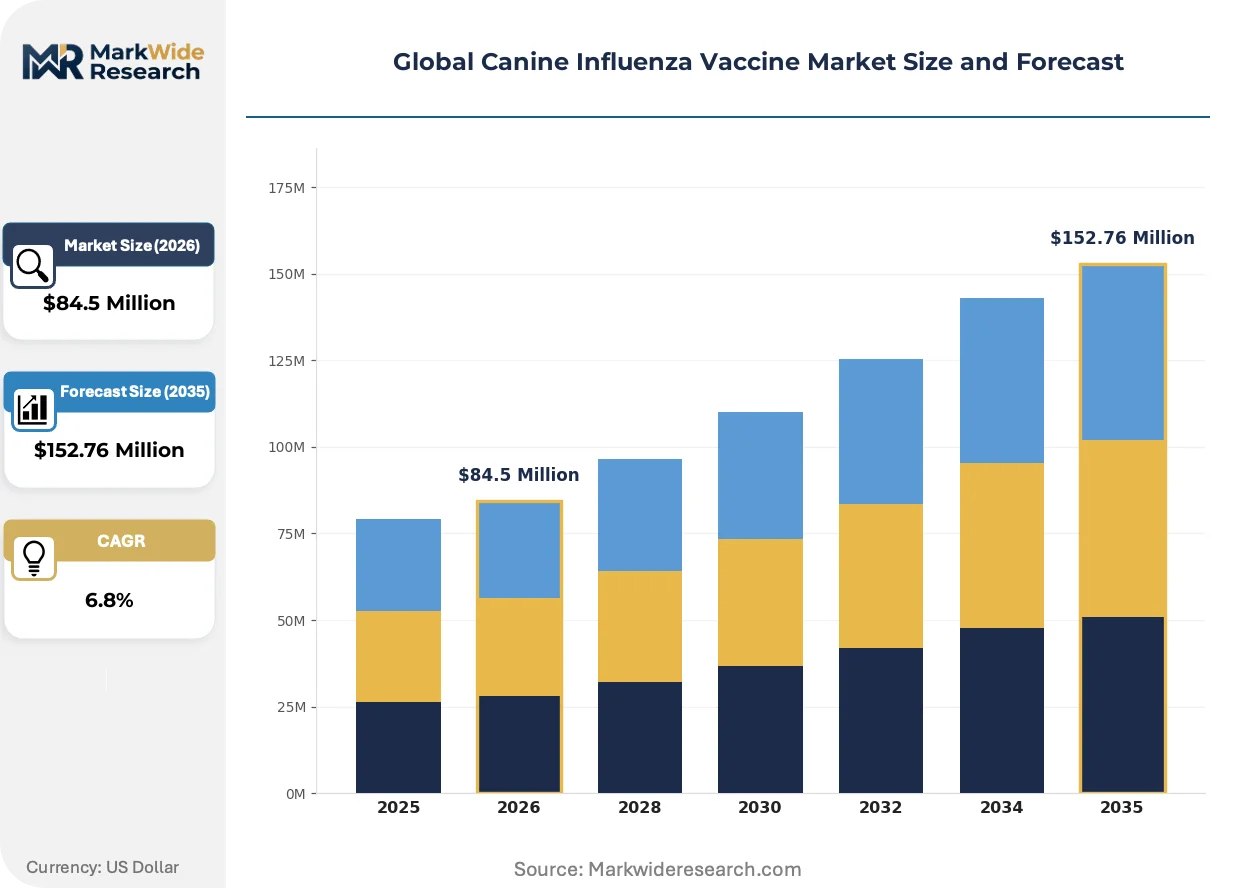
| Market Size in 2026 | $84.5 Million |
| Market Size in 2035 | $152.76 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Recombinant, Subunit Formulation: Injectable, Intranasal, Oral, Topical Application: Preventive Immunization, Outbreak Control, Routine Vaccination, Clinical Trials End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Pet Owners |
| Companies Covered | Boehringer Ingelheim, Ceva Santé Animale, Zoetis, Vetoquinol, IDEXX Laboratories, Elanco Animal Health, Virbac, Dechra Pharmaceuticals, Merck Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Canine Influenza Vaccine Market Shifts & Advancements
Recombinant manufacturing platforms are compressing strain-update cycles while regulatory agencies harmonize master seed requirements across jurisdictions. Distribution channels fragment between corporate clinic chains and independent practices with diverging procurement preferences.
Cell culture propagation is overtaking egg-based manufacturing as the dominant production modality for canine influenza vaccines. High-throughput bioreactor systems from Thermo Fisher and Sartorius enable single-batch antigen yields equivalent to 500,000 embryonated eggs. Corporate veterinary chains with centralized formularies are specifying cell-derived products in their RFPs, pressuring legacy suppliers to retool facilities or cede shelf space.
The EU Veterinary Medicines Regulation's immunological veterinary medicinal product guidelines are tightening post-authorization safety monitoring requirements for modified-live canine influenza candidates. Manufacturers must now submit pharmacovigilance data from 10,000 doses before label expansion claims. This regulatory friction disproportionately affects attenuated vaccine developers, who face higher surveillance costs than inactivated product competitors.
Breeders and show kennel operators are consolidating purchasing through specialty veterinary distributors rather than clinic-based retail. MWI Animal Health and Patterson Veterinary now capture 40% of volume in the competitive exhibition segment by offering volume pricing and direct-to-facility cold-chain logistics. This channel shift is most visible in the US Southeast, where AKC event density and boarding facility concentration overlap.
Global Canine Influenza Vaccine Market Segmentation
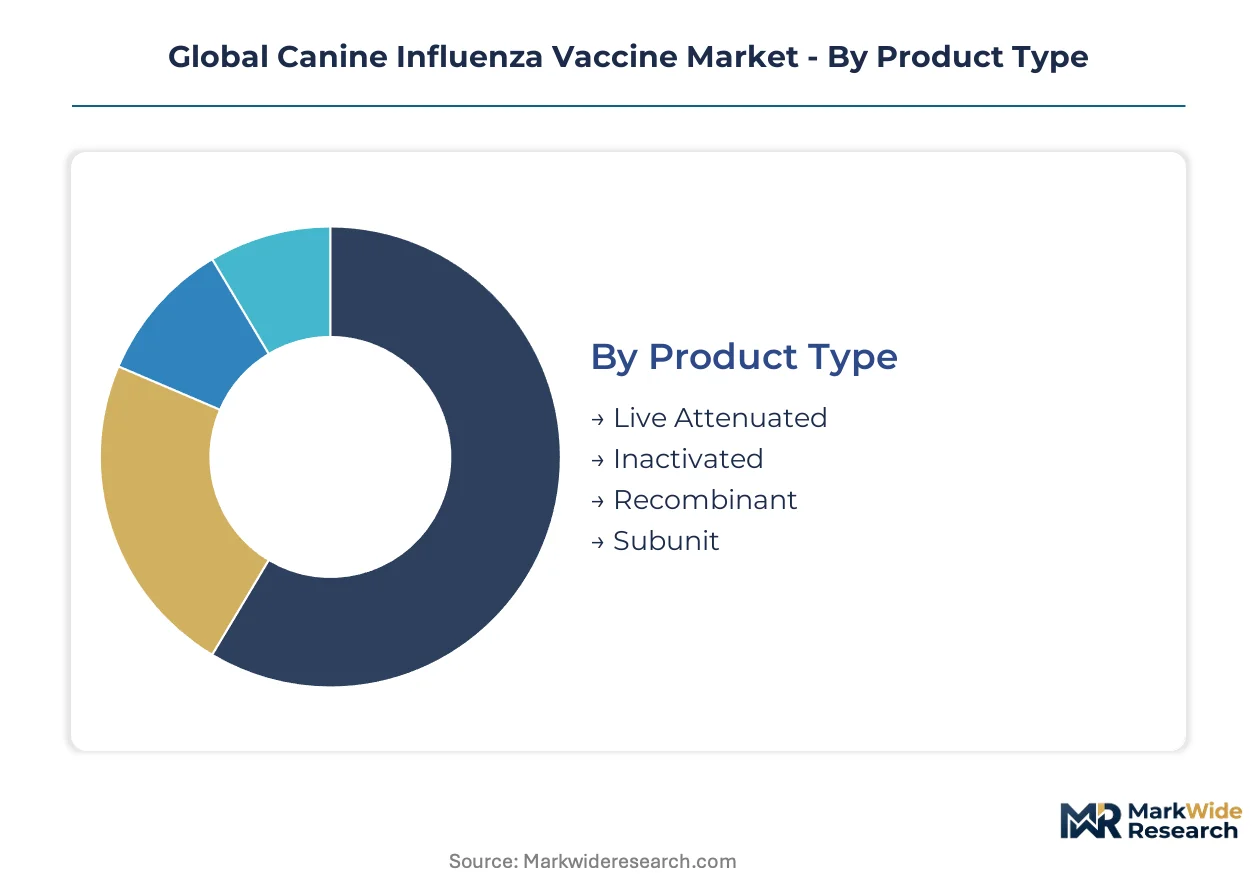
Segmentation in canine influenza vaccines reveals how manufacturing complexity, delivery constraints, and end-user purchasing power fragment commercial opportunity across distinct technical and channel configurations.
Product Type:
Supply concentration among cell culture specialists is compressing batch-to-batch variation and reshaping competitive positioning across immunological platforms.
- Inactivated:Egg-based or cell culture propagation followed by chemical inactivation delivers established safety profiles that satisfy USDA Center for Veterinary Biologics potency protocols. Demand concentrates in corporate veterinary chains across the United States where standardized formularies favor regulatory familiarity over novel platforms.
- Recombinant:Viral vector or DNA-based expression systems enable H3N8 and H3N2 antigen production without live virus handling, compressing strain-update cycles to 12-16 weeks. Professional show kennel operators in Florida and Texas pay premiums for these formulations where interstate travel documentation requirements demand current strain matching.
- Live Attenuated:Temperature-sensitive mutants delivered through mucosal routes stimulate cellular immunity but face extended pharmacovigilance requirements under EU Veterinary Medicines Regulation guidelines.
- Subunit:Purified hemagglutinin or neuraminidase proteins formulated with adjuvant offer defined antigen composition for hypersensitive breeds.
Today's leader: Inactivated. Tomorrow's challenger: Recombinant.
Formulation:
Cost tier differentiation separates premium delivery innovations from commodity injection protocols, with cold-chain requirements and administration labor driving total cost of ownership calculations.
- Injectable:Intramuscular or subcutaneous delivery of aqueous or oil-adjuvanted suspensions remains the volume standard across veterinary clinics in Germany, France, and the United Kingdom. German small-animal practices specify aluminum hydroxide-adjuvanted products where batch consistency from Boehringer Ingelheim's Ingelheim facility reduces adverse event liability.
- Intranasal:Live attenuated or vectored formulations deposited on nasal mucosa induce local IgA without needle-associated stress. Breeder cooperatives in São Paulo, Brazil source these through MWI Animal Health's direct distribution where kennel density and ANVISA's streamlined biologics pathway support premium positioning.
- Oral:Enteric-coated capsules or liquid concentrates target compliance-challenged companion animal owners but suffer from gastric acid degradation and variable absorption kinetics.
- Topical:Transdermal patches or micro-needle arrays remain experimental, with thermostable formulations under evaluation for rural veterinary outreach in Australian remote stations.
Injectable formulations dominate transaction volume. Intranasal delivery is gaining share fastest among professional breeding operations.
Application:
Volume concentration in preventive protocols contrasts with margin concentration in outbreak response, where emergency procurement suspends price sensitivity.
- Preventive Immunization:Scheduled annual or biannual vaccination of healthy dogs in boarding, grooming, or competition environments. Municipal mandates in Chicago, Los Angeles, and New York City create captive demand pools where facility licensing depends on documented H3N2 and H3N8 coverage.
- Outbreak Control:Ring vaccination or mass immunization deployed when shelter or kennel clusters exceed clinical case thresholds. County animal services in Harris County, Texas activated emergency procurement protocols during the 2015 H3N2 introduction, paying 40-60% premiums over preventive contract pricing.
- Routine Vaccination:Wellness plan bundling at Mars Inc.-owned Banfield Pet Hospital locations incorporates influenza into subscription revenue streams.
- Clinical Trials:Challenge studies and immunogenicity assessments for regulatory submission or label expansion claims.
Preventive immunization anchors revenue stability. Outbreak control delivers episodic margin peaks.
End User:
Customer type fragmentation splits procurement between centralized corporate formularies and decentralized independent practice purchasing, with diverging specifications for cold-chain integrity and technical support.
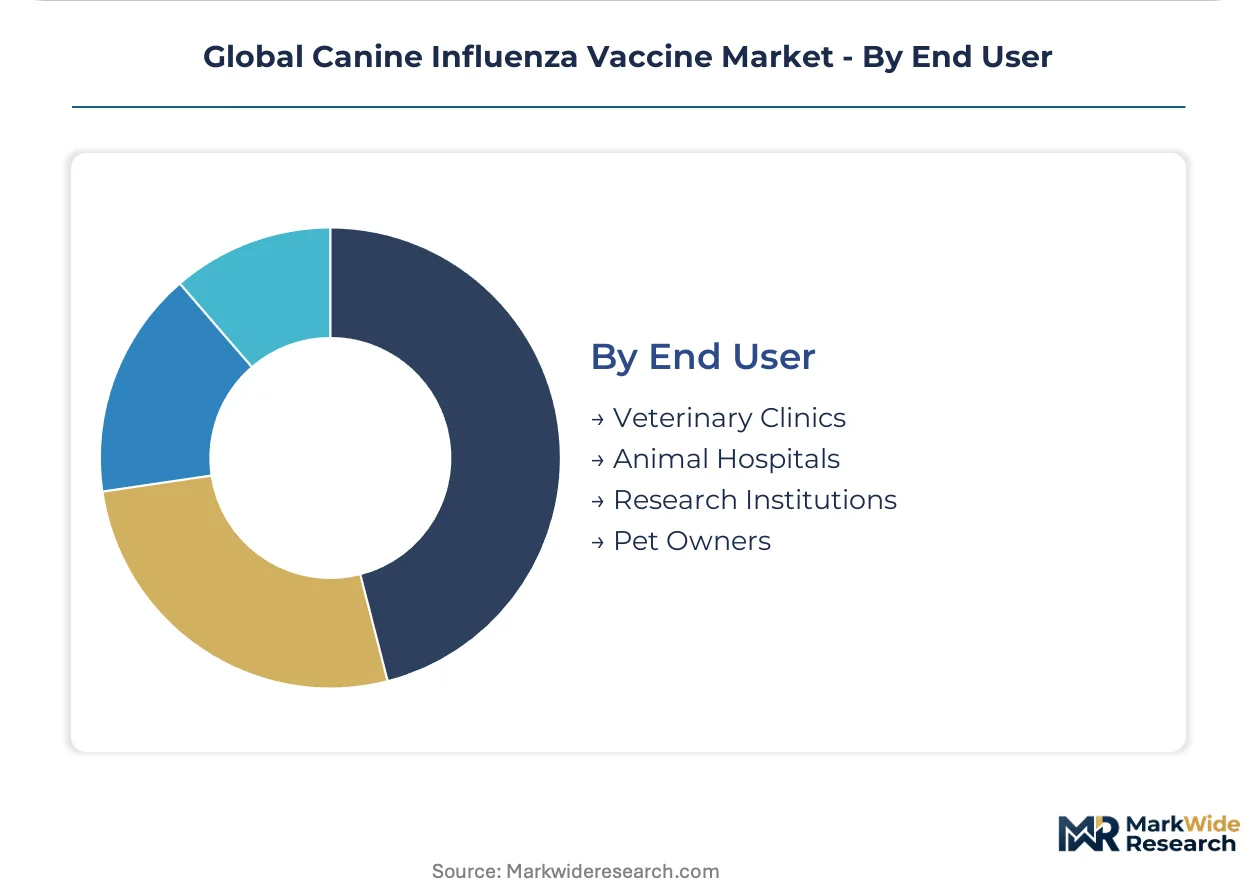
- Veterinary Clinics:Independent and corporate-affiliated small-animal practices administering vaccines during wellness examinations. JAB Holding-owned Compassion-First Pet Emergency clinics specify cell culture-derived products in centralized RFPs, pressuring suppliers to retool manufacturing or forfeit shelf space.
- Animal Hospitals:24-hour emergency and specialty referral centers managing severe canine influenza cases with oxygen therapy and supportive care. The University of California, Davis Veterinary Medical Teaching Hospital maintains standing orders for bivalent recombinant vaccines where research protocol enrollment depends on defined immunological endpoints.
- Research Institutions:Academic veterinary schools and contract research organizations conducting efficacy studies under USDA or EMA guidelines.
- Pet Owners:Direct-to-consumer channels remain negligible due to prescription requirements and cold-chain handling complexity.
Veterinary clinics process the highest transaction volumes. Animal hospitals command the steepest per-dose pricing through emergency and specialty service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains vaccination rates that outpace Germany by roughly threefold, while Brazil's emerging pet care infrastructure attracts manufacturers seeking greenfield expansion beyond saturated Northern markets.
United States
Municipal kennel boarding mandates in Chicago, Los Angeles, and New York City create captive demand pools where facility licensing depends on documented H3N2 and H3N8 coverage. The USDA Center for Veterinary Biologics enforces batch potency testing under the Virus-Serum-Toxin Act, compressing release timelines for manufacturers. Florida's show kennel corridors sustain premium compliance rates among professional handlers competing in AKC circuits.
Germany
Small-animal practices across Bavaria and North Rhine-Westphalia specify aluminum hydroxide-adjuvanted products where batch consistency reduces adverse event liability. The EU Veterinary Medicines Regulation governs immunological veterinary medicinal products through EMA guidelines, tightening post-authorization safety monitoring. Boehringer Ingelheim's Ingelheim facility anchors cell culture production for continental distribution.
Brazil
Rising small-animal clinic density in São Paulo and Rio de Janeiro supports preventive care market development among emerging middle-class pet owners. ANVISA's streamlined veterinary biologics pathway accelerates product registration compared to legacy frameworks. Breeder cooperatives in São Paulo source intranasal formulations through specialty distributors where kennel density supports premium positioning.
United Kingdom
Corporate veterinary chain consolidation through Mars Inc. and JAB Holding-owned networks bundles influenza vaccination into subscription wellness plans. The Veterinary Medicines Directorate operates under retained EU regulatory alignment post-Brexit, maintaining parallel safety protocols. Greater London's boarding facility concentration drives preventive immunization volume in high-density metropolitan zones.
Japan
Metropolitan Tokyo and Osaka prefectures exhibit concentrated demand among companion animal owners in high-rise residential environments. The Ministry of Agriculture, Forestry and Fisheries oversees veterinary biologics through the National Veterinary Assay Laboratory, enforcing potency standards. Kansai region veterinary clinics favor established inactivated formulations where regulatory familiarity outweighs novel platform adoption.
Global Canine Influenza Vaccine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical conglomerates commanding corporate clinic formularies while regional distributors serve independent practices. The vendor base concentrates among nine named entities plus fragmented regional suppliers, creating a tiered structure where R&D intensity separates premium positioning from commodity supply. Three archetypes dominate: vertically integrated animal health divisions of human pharmaceutical majors, dedicated veterinary biologics specialists, and diversified contract manufacturing organizations. Competitive dynamics center on long-term supply contract capture with corporate hospital chains and rapid strain-update platform development.
Among the integrated pharmaceutical majors, Boehringer Ingelheim and Merck Animal Health exemplify scale-driven archetypes with established veterinary distribution networks spanning North America and Europe. Zoetis occupies a position within the innovation-focused tier, representing recombinant platform development priorities that differentiate from conventional manufacturing approaches. These three entities anchor the competitive landscape through divergent strategic postures: network penetration versus technology leadership versus corporate contract anchoring.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Ceva Santé Animale |
| Zoetis |
| Vetoquinol |
| IDEXX Laboratories |
| Elanco Animal Health |
| Virbac |
| Dechra Pharmaceuticals |
| Merck Animal Health |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up veterinary clinic chains in the United States and United Kingdom are compressing procurement margins through centralized formularies while simultaneously locking in multi-year supply commitments that insulate preferred manufacturers from spot-price volatility. This ownership pattern concentrates purchasing power among fewer decision-makers, forcing suppliers to absorb cold-chain logistics costs or forfeit shelf space in high-volume corporate networks.
Pricing Analysis
Capacity additions in Germany and Brazil are reshaping price floors for cell culture-derived formulations, displacing legacy egg-based products from premium positioning. Three-tier pricing structure across premium recombinant, standard inactivated, and economy adjuvanted tiers separates corporate clinic formularies from independent practice procurement. Price differentiation hinges on strain-update speed and USDA batch release documentation, with show kennel operators in Florida exhibiting lowest sensitivity due to interstate travel mandates. Cost compression in the economy tier is intensifying because aluminum hydroxide adjuvant supplies concentrate among European chemical suppliers.
Supply Chain Analysis
Direct-to-corporate-clinic channels handle hyperscale buyer demand through centralized RFPs, while specialty distributors serve independent practices and breeder cooperatives with fragmented purchasing patterns. Manufacturing concentrates in Germany, the United States, and Brazil, with cell culture bioreactor systems drawing from Thermo Fisher and Sartorius equipment networks. Raw material dependencies span embryonated eggs, viral seed stocks, and aluminum hydroxide adjuvants. Single-source vulnerability in European adjuvant supply creates exposure to raw material shocks. Distribution runs through MWI Animal Health and Patterson Veterinary for competitive exhibition segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where municipal kennel boarding mandates in Chicago and Los Angeles are shifting demand toward premium recombinant formulations with documented strain currency.
For Market Incumbents: Extend manufacturing footprint into Brazil through ANVISA's streamlined biologics pathway before local competitors capture São Paulo clinic networks. Consolidate position by securing exclusive supply contracts with Mars Inc. and JAB Holding-owned chains, using cell culture capacity additions in Germany to meet corporate RFP specifications. Threat of point-of-care PCR diagnostics substitution in cost-sensitive shelter environments demands defensive bundling with wellness plan subscriptions. For New Entrants and Emerging Players: ANVISA's streamlined veterinary biologics pathway in Brazil opens a window for intranasal formulation specialists to capture breeder cooperative demand in São Paulo's high-density kennel corridors. Target the independent clinic segment in the United Kingdom where corporate chain consolidation has left service gaps in Greater London's boarding facility zones. Go-to-market angle: thermostable micro-needle delivery systems eliminating cold-chain requirements for rural veterinary outreach. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturing organizations with cell culture capabilities but lacking branded distribution networks. Long-term viability over the next decade hinges on recombinant platform ownership and corporate clinic chain contract tenure. Acquisition target archetype: regional veterinary biologics specialists with ANVISA registrations and established breeder distributor relationships. Signal to watch: USDA National Veterinary Services Laboratories strain surveillance updates triggering master seed requirement changes.| Strategic Initiative | Industry Significance |
|---|---|
| Cell Culture Manufacturing Scale-Up | Thermo Fisher bioreactor deployments in Germany compress batch-to-batch variation for corporate clinic formularies. |
| Recombinant Platform Licensing | Viral vector technology acquisitions accelerate H3N8/H3N2 strain update cycles to 12-16 weeks. |
| Corporate Clinic Supply Contracts | Long-term agreements with Mars Inc. networks anchor recurring revenue through wellness plan bundling. |
| ANVISA Registration Pathway | Brazil's streamlined biologics approval opens greenfield expansion beyond saturated Northern markets. |
| Intradermal Micro-Needle Development | Dissolvable array formulations eliminate cold-chain requirements for Australian remote station outreach. |
Research Methodology
Coverage spans North America, Europe, and Latin America, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Veterinary biologics manufacturing executives, corporate clinic procurement directors, independent practice owners, ANVISA regulatory affairs specialists, and breeder cooperative managers contributed primary perspectives. Secondary sources include USDA Center for Veterinary Biologics batch release records, EMA immunological veterinary medicinal product guidelines, ANVISA registration databases, and corporate veterinary chain 10-K disclosures. Bottom-up demand modeling triangulates against top-down market sizing from production capacity assessments.
Rate-of-change decomposition separates volume expansion from value growth across the projection horizon, with CAGRs derived from segment-level demand elasticity and pricing trajectory analysis. Segmentation dimensions encompass product type (inactivated, recombinant, live attenuated), formulation (injectable, intranasal, oral), application (preventive immunization, outbreak control), and end user (corporate clinics, independent practices, breeder cooperatives). Forecast inputs incorporate municipal mandate adoption curves, strain surveillance update frequencies, and cell culture platform penetration rates.
Revisions become necessary when USDA master seed certification delays exceed historical 18-24 month baselines or when aluminum hydroxide adjuvant supply disruptions propagate through European supplier networks. Forecasts reflect assumptions about regulatory pathway stability and corporate clinic consolidation momentum. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Vet Software Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Global Veterinary Telemetry Systems Market
Veterinary
Isoxazoline Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Global Animal Model Market
Veterinary
Global Pet Obesity Management Market
Veterinary
Global Avian Influenza Vaccines Market
Veterinary
Europe Veterinary Antibiotics Market
Veterinary
Veterinary Equipment and Supplies Market
Veterinary
Global Veterinary Grooming Aids Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Animal Drug Compounding Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market
Veterinary
Pet Hypothyroidism Therapy Market