
 Veterinary Antibiotics Market | 2026-2036
Veterinary Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Antibiotics Market Outlook
The EU Green Deal's farm-to-fork antibiotic reduction targets is realigning procurement criteria across European livestock cooperatives. Zoetis Inc. leverages its integrated diagnostics-to-therapeutics platform to sustain contract loyalty with large-scale poultry integrators. Merck & Co., Inc. anchors its position through captive vaccine-antibiotic combination portfolios. Boehringer Ingelheim differentiates via species-specific formulation R&D intensity.
Veterinary antibiotics comprise antimicrobial compounds administered to food-producing and companion animals for therapeutic, metaphylactic, and growth-promotion purposes, formulated to achieve tissue-specific pharmacokinetic profiles with defined withdrawal intervals. Tetracyclines retain the largest installed base due to broad-spectrum efficacy and cost-optimized manufacturing routes. Oral liquids capture disproportionate growth momentum in aquaculture application segments where medicated feed delivery proves logistically constrained. Injectable formulations concentrate margin pools in cattle markets requiring extended-duration plasma concentration maintenance.
The FDA's Veterinary Feed Directive and EMA's CVMP antimicrobial guidelines jointly constrain over-the-counter distribution pathways while elevating veterinary prescription requirements. China's MEE dual carbon goals intersect with agricultural antibiotic discharge standards, reshaping manufacturing environmental compliance burdens. Stakeholders must monitor evolving residue tolerance harmonization between Codex Alimentarius and national food safety regulators to anticipate export market access shifts.
Market Dynamics
Antimicrobial stewardship mandates from the EU Green Deal and China's MEE dual carbon goals are compressing legacy prescription volumes while redirecting R&D investment toward species-specific formulation platforms and residue-monitoring diagnostics.
Growth Catalysts
- Intensive livestock consolidation:Large-scale poultry integrators in Brazil and pork producers across Sichuan province are expanding veterinary prescription protocols under national agricultural ministry guidelines.
- EMA CVMP antimicrobial guidelines:Elevated prescription requirements are creating captive demand for integrated diagnostics-to-therapeutics service bundles among European livestock cooperatives.
- Aquaculture expansion:Oral liquid formulations are capturing disproportionate momentum in medicated feed delivery where logistics constrain traditional feed-based administration.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for tetracycline-class products clusters in specific coastal Chinese industrial zones, exposing procurement to environmental compliance disruption.
- Withdrawal interval complexity:Extended plasma concentration maintenance requirements in cattle markets necessitate costly pharmacokinetic profiling that smaller feedlot operators cannot absorb.
- Residue tolerance fragmentation:Divergent Codex Alimentarius harmonization timelines against national food safety regulators create export market access uncertainty for cross-border protein shipments.
Strategic Opportunities
- Vaccine-antibiotic combination portfolios:Captive integration of prophylactic and therapeutic modalities offers contract loyalty mechanisms for large-scale cattle operations seeking simplified procurement.
- Companion animal pivot:Metaphylactic application segments in small-animal veterinary clinics remain underpenetrated relative to food-producing animal saturation.
- Environmental discharge standards:China's MEE dual carbon goals are reshaping manufacturing compliance burdens, creating first-mover advantage for facilities with closed-loop waste treatment infrastructure.
Industry Challenges
- Veterinary pharmacology specialization:Tissue-specific pharmacokinetic expertise scarcity constrains formulation development timelines for species-specific platforms.
- Legacy system integration:Diagnostic-to-therapeutic data platforms require reconfiguration of existing herd management software architectures across distributed feedlot networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Antibiotics Market |
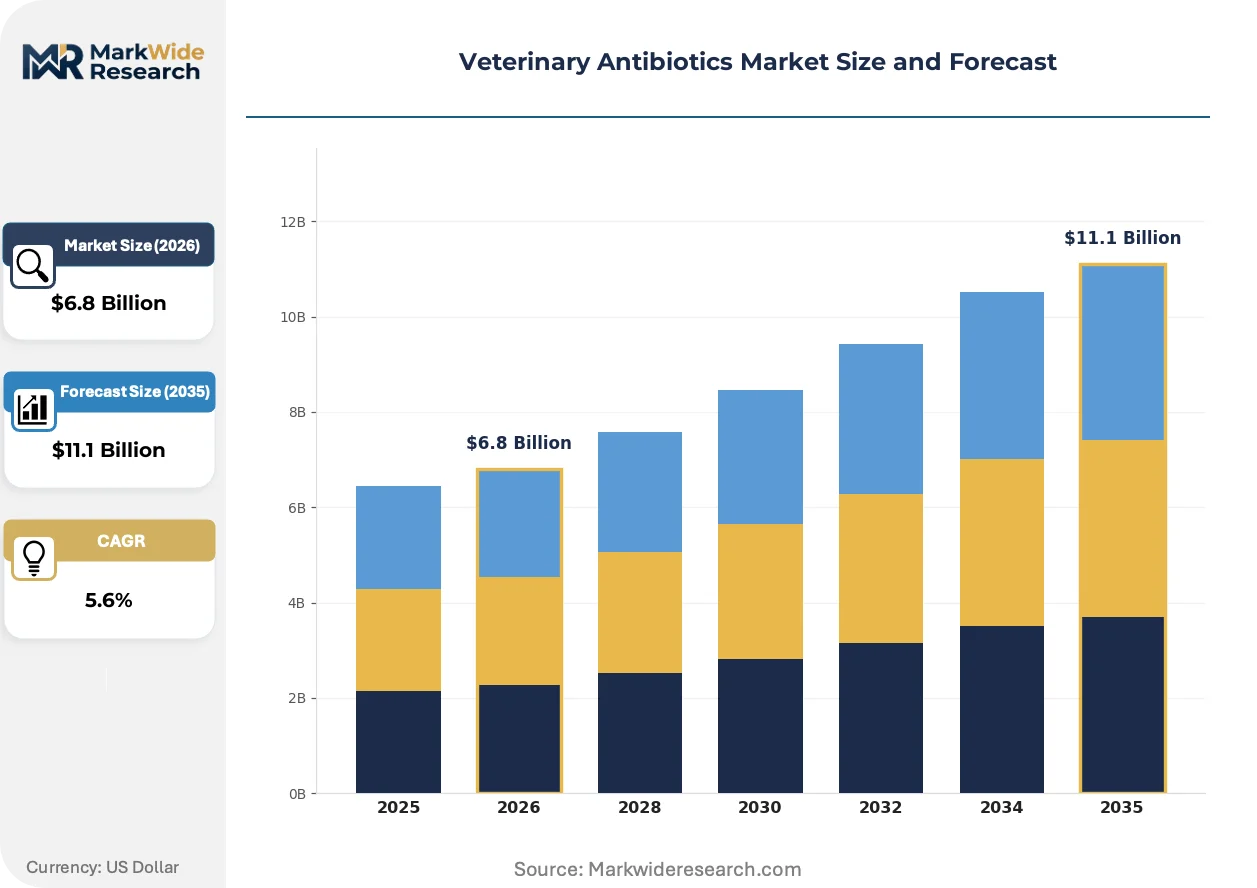
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Penicillins, Tetracyclines, Macrolides, Sulfonamides Application: Poultry, Swine, Cattle, Aquaculture Formulation: Injectables, Oral Solids, Oral Liquids, Topicals Distribution Channel: Retail Pharmacies, Veterinary Clinics, Online Stores, Direct Sales |
| Companies Covered | Zoetis Inc., Merck & Co., Inc., Boehringer Ingelheim, Elanco Animal Health, Ceva Santé Animale, Vetoquinol, Virbac, Dechra Pharmaceuticals, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Antibiotics Market Strategic Shifts
Formulation science is fragmenting toward precision-delivery mechanisms while regulatory architectures harden against prophylactic use, forcing competitive differentiation through diagnostic integration rather than volume scale.
Microencapsulation technologies for rumen-protected delivery are modularizing oral antibiotic bioavailability across ruminant species. Beef cattle feedlots in the North American plains are adopting these platforms to bypass gastric degradation and extend therapeutic windows. The technology is modularizing what were previously injectable-only margin pools into oral administration categories with lower labor costs.
EU Green Deal farm-to-fork antibiotic reduction targets are compressing metaphylactic prescription ceilings across European livestock cooperatives. Procurement criteria now prioritize residue-monitoring diagnostics bundled with therapeutic contracts. Poultry integrators in France and Germany are responding by consolidating supplier relationships around integrated service platforms rather than commodity antibiotic purchasing.
Direct-to-producer digital channels are disintermediating traditional veterinary distributor networks for routine prescription refills. Large-scale pork operations in Henan province are piloting tele-veterinary platforms that connect on-farm staff with remote prescription authorization. This behavioral shift concentrates most visibly in China's intensive production belt where labor mobility constraints limit on-site veterinary presence.
Veterinary Antibiotics Market Segmentation
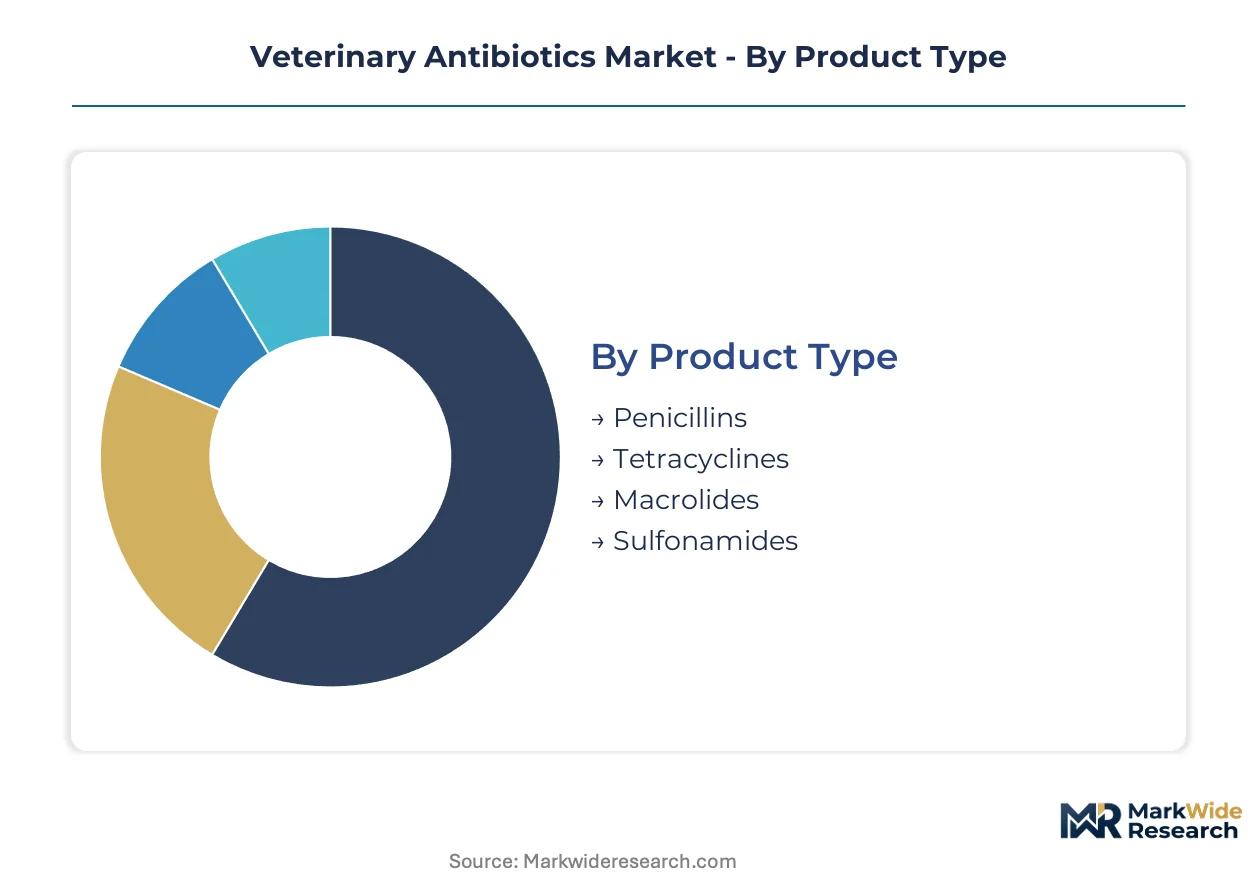
Veterinary antibiotics segment along pharmacological, species, and delivery dimensions that dictate regulatory pathways, manufacturing scale, and margin architecture. Procurement patterns diverge sharply between consolidated livestock integrators and fragmented smallholder operations across each axis.
Product Type:
Cost sensitivity and spectrum breadth differentiate buyer procurement behavior across antimicrobial classes.
- Tetracyclines:Broad-spectrum bacteriostatic agents with established resistance profiles and cost-optimized fermentation manufacturing routes. Feedlot operations in Brazil's Mato Grosso region and Sichuan province pork producers concentrate procurement here under national agricultural ministry stewardship guidelines.
- Penicillins:Beta-lactam compounds with narrow-spectrum efficacy against Gram-positive pathogens. Dairy cattle operations in Germany's Lower Saxony cluster prioritize these for mastitis protocols under EMA CVMP prescription elevation mandates.
- Macrolides:Protein synthesis inhibitors with tissue-penetrating pharmacokinetics suited to respiratory indications. Poultry integrators in France's Brittany region specify these for mycoplasma control within integrated diagnostics-to-therapeutics contracts.
- Sulfonamides:Folate pathway antagonists frequently compounded with potentiator agents. Aquaculture operations in Vietnam's Mekong Delta apply these for systemic bacterial infections where water-borne delivery demands solubility optimization.
Tetracyclines lead volumes today; macrolides are gaining share fastest.
Application:
Species-specific pharmacokinetics and withdrawal interval economics drive formulation investment priorities.
- Cattle:Large-molecule therapeutics requiring extended plasma concentration maintenance through depot formulations. North American plains feedlots absorb premium pricing for long-acting injectables that minimize labor costs across dispersed operations.
- Swine:High-density confinement systems with metaphylactic mass medication protocols. China's Henan province operations pilot tele-veterinary prescription platforms to satisfy MEE environmental discharge compliance.
- Poultry:Rapid turnover cycles compress therapeutic windows and elevate residue risk sensitivity. Brazilian integrators expanding antimicrobial stewardship programs under ANVISA-aligned ministry protocols.
- Aquaculture:Water-borne delivery constraints favor oral liquid absorption over medicated feed logistics. Vietnam and Indonesia shrimp producers drive disproportionate growth momentum in this channel.
Swine applications dominate prescription volumes; aquaculture is climbing the fastest.
Formulation:
Delivery mechanism determines bioavailability engineering requirements and administration labor economics.
- Injectables:Parenteral delivery achieving precise dosing with defined withdrawal intervals. Cattle markets capture premium margin pools through extended-duration plasma maintenance technologies.
- Oral Liquids:Aqueous suspensions enabling flexible dose titration across variable body weights. Aquaculture segments absorb disproportionate growth where feed-based administration proves logistically constrained.
- Oral Solids:Compressed tablets and bolus formulations for individual animal therapy. Companion animal clinics in urban Japan favor these for precision metaphylaxis.
- Topicals:Dermal and ophthalmic preparations for localized infection control. Dairy mastitis tubes and wound treatments concentrate in European livestock cooperative procurement.
Injectables command the largest revenue share; oral liquids show the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects operation scale, prescription complexity, and regulatory authorization requirements.
- Veterinary Clinics:Prescription gatekeepers under FDA Veterinary Feed Directive and EMA CVMP elevation mandates. European livestock cooperatives consolidate procurement through integrated service platforms bundling diagnostics.
- Direct Sales:Manufacturer-to-producer relationships for large-scale integrators. Brazil's poultry giants and China's pork operations negotiate captive contracts bypassing distributor markups.
- Retail Pharmacies:Over-the-counter access points for legacy markets transitioning to prescription requirements. Smaller feedlot operators in regions with phased regulatory implementation rely here.
- Online Stores:Digital channels disintermediating traditional networks for routine refill authorization. Henan province tele-veterinary pilots exemplify this behavioral shift.
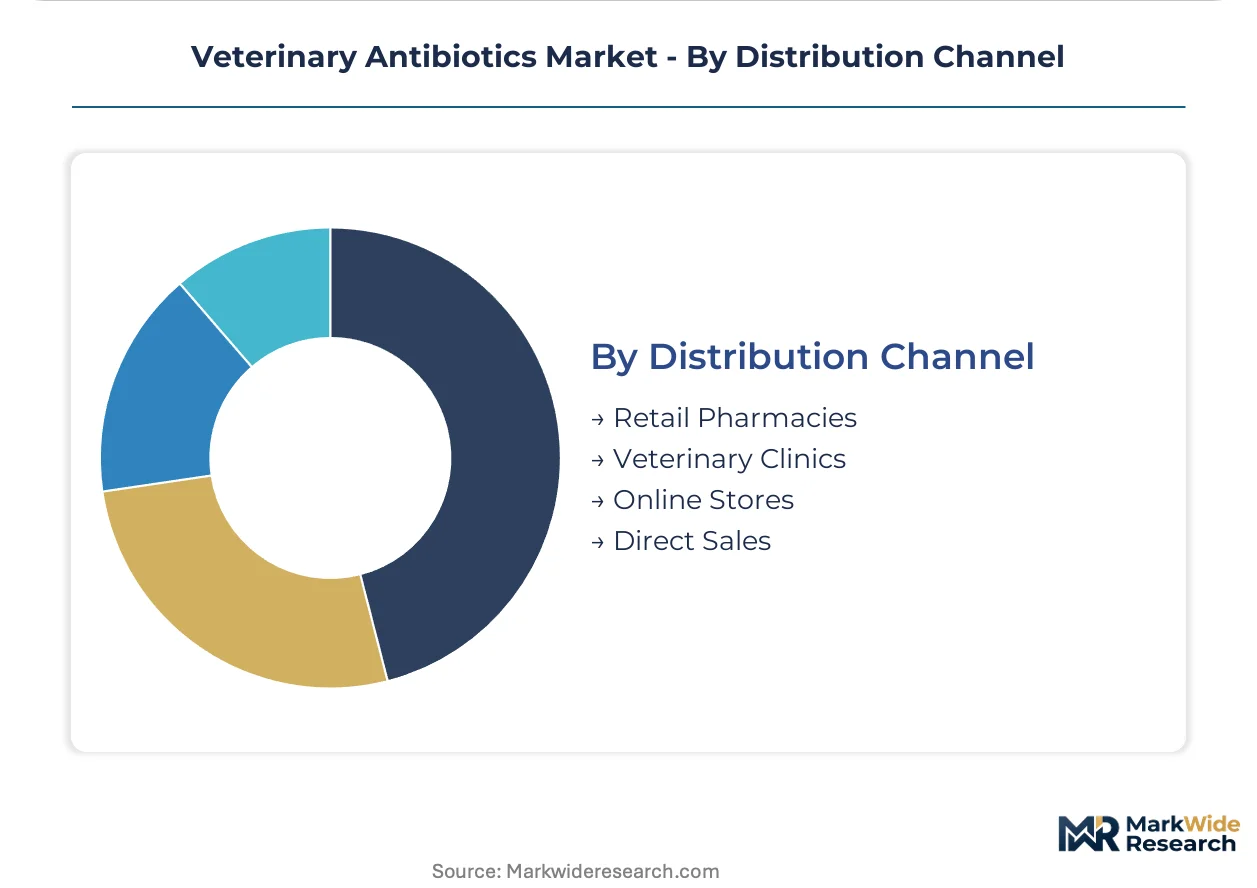
Veterinary clinics anchor channel volumes; direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary pharmacology expertise clusters in agricultural heartlands where livestock density intersects with regulatory enforcement capacity. This concentration pattern shapes where formulation R&D and stewardship programs actually deploy.
China
Pork production intensity in Henan and Sichuan provinces drives prescription volume concentration. MEE dual carbon goals are tightening antibiotic discharge standards at manufacturing facilities. Tele-veterinary platforms in Henan pilot remote prescription authorization for large-scale operations facing veterinary labor shortages.
United States
Beef cattle feedlots across the North American plains absorb premium injectable formulations for extended-duration therapy. FDA Veterinary Feed Directive mandates elevate prescription requirements for medicated feed distribution. Kansas and Texas feedlot clusters are adopting microencapsulation technologies to convert injectable margin pools into oral administration categories.
Brazil
Poultry integrators in São Paulo and Paraná states are expanding antimicrobial stewardship programs under ANVISA-aligned agricultural ministry protocols. Large-scale operators negotiate direct manufacturer contracts bypassing traditional distributor networks. Mato Grosso feedlot operations concentrate tetracycline procurement under national stewardship guidelines.
Germany
Dairy cattle operations in Lower Saxony prioritize penicillin-class products for mastitis protocols under EMA CVMP prescription elevation mandates. Livestock cooperatives are consolidating procurement around integrated diagnostics-to-therapeutics service bundles. Bavaria-based research clusters are advancing species-specific formulation platforms for residue-monitoring compliance.
France
Poultry integrators in Brittany specify macrolide formulations for mycoplasma control within bundled veterinary service contracts. EU Green Deal farm-to-fork targets are compressing metaphylactic prescription ceilings across livestock cooperatives. Île-de-France diagnostic firms are integrating therapeutic contracts with residue-monitoring platforms to sustain supplier loyalty.
Veterinary Antibiotics Market Competitive Environment
Capital-heavy producers with integrated manufacturing footprints compete with asset-light specialists licensing formulation technologies from third-party development houses. Market structure tilts toward consolidation at the top tier, with four to six players capturing disproportionate contract value from large-scale livestock integrators. Three strategic archetypes dominate: diversified human-animal health conglomerates, pure-play veterinary specialists, and regional formulation houses serving price-sensitive procurement. Competitive moves center on captive vaccine-antibiotic combination portfolios and geographic expansion through distributor acquisition in emerging livestock markets.
Within the diversified health conglomerate tier, Zoetis Inc. and Merck & Co., Inc. exemplify integrated diagnostics-to-therapeutics platform strategies. Boehringer Ingelheim occupies a position emphasizing species-specific R&D intensity among European-headquartered players. These three anchors represent contrasting approaches to sustaining contract loyalty with large-scale poultry and cattle integrators.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck & Co., Inc. |
| Boehringer Ingelheim |
| Elanco Animal Health |
| Ceva Santé Animale |
| Vetoquinol |
| Virbac |
| Dechra Pharmaceuticals |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap formulation houses in India's Gujarat and Maharashtra clusters anchor supply-side discipline through generational manufacturing relationships that resist price volatility. Their captive fermentation infrastructure for tetracycline-class APIs sustains contract stability for Brazilian feedlot operators while limiting margin erosion from Chinese environmental compliance costs.
Pricing Analysis
Bundled diagnostics-to-therapeutics service contracts command premium positioning against unbundled commodity antibiotic procurement. Pricing stratifies across integrated platform tiers, standalone formulation tiers, and generic API tiers based on residue-monitoring certification levels and veterinary prescription authorization depth. Cost compression in generic tetracycline segments intensifies as Henan province pork producers consolidate procurement volumes. Smallholder aquaculture operators in Vietnam exhibit highest price sensitivity; large-scale poultry integrators in São Paulo state absorb premium pricing for captive service bundles.
Supply Chain Analysis
Freight cost differentials between coastal Chinese API zones and inland formulation facilities reshape regional procurement patterns for European livestock cooperatives. Active pharmaceutical ingredient manufacturing concentrates in China's Zhejiang and Jiangsu provinces, India's Hyderabad-Visakhapatnam corridor, and Italy's Lombardy cluster. Finished formulation production draws from fermentation-derived tetracyclines, synthetic penicillin intermediates, and macrolide starter cultures. Single-source vulnerability runs through Zhejiang environmental discharge permit renewals under MEE dual carbon enforcement. Distribution runs through veterinary clinic networks under FDA and EMA prescription elevation mandates, direct manufacturer contracts with Brazilian and Chinese integrators, and emerging tele-veterinary platforms in Henan province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary antibiotics market compounds steadily as livestock protein demand intensifies across emerging economies and regulatory stewardship mandates elevate veterinary service bundling. This structural demand driver sustains pricing power for integrated platform providers despite generic commoditization pressures.
For Market Incumbents: Deploy diagnostic integration capabilities to capture EMA CVMP-mandated prescription elevation revenue streams. Incumbent veterinary pharmaceutical conglomerates should consolidate captive vaccine-antibiotic combination portfolios to defend against emerging biosimilar entrants in European livestock cooperatives. Backward integration into closed-loop waste treatment infrastructure secures first-mover positioning under China's tightening MEE discharge standards.
For New Entrants and Emerging Players: FDA Veterinary Feed Directive implementation in US cattle markets opens a window for tele-veterinary platform specialists targeting dispersed feedlot operations across Kansas and Texas. Aquaculture oral liquid formulations in Vietnam and Indonesia represent the most penetrable white-space segment given medicated feed logistics constraints. A direct-to-producer digital channel strategy bypasses entrenched veterinary distributor networks for routine prescription refill authorization.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulation houses with captive API sourcing and species-specific R&D pipelines. The five-to-ten-year viability window favors acquisition targets with integrated residue-monitoring diagnostic capabilities aligned to EU Green Deal farm-to-fork compliance timelines. The signal to watch is tele-veterinary prescription authorization adoption rates across China's intensive pork production belt.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Platform Integration | Bundled EMA CVMP-compliant service contracts capture prescription elevation revenue from European livestock cooperatives. |
| Species-Specific Formulation R&D Investment | Targeted pharmacokinetic profiling for cattle depot formulations sustains margin pools in North American feedlot markets. |
| Closed-Loop Manufacturing Infrastructure | MEE-aligned environmental compliance secures operational continuity for API facilities in China's coastal industrial zones. |
| Tele-Veterinary Channel Development | Remote prescription authorization platforms address veterinary labor shortages in Henan province pork operations. |
| Vaccine-Antibiotic Combination Portfolio Expansion | Captive prophylactic-therapeutic integration strengthens contract loyalty with Brazilian poultry integrators under ANVISA protocols. |
Study Parameters
Bottom-up livestock end-use modeling reconciled against top-down API manufacturing capacity tracking forms the analytical core of this study. Primary interviews with veterinary pharmaceutical executives, livestock cooperative procurement directors, regulatory affairs specialists at national agricultural ministries, and feedlot operations managers combined with secondary validation from FDA Veterinary Feed Directive filings, EMA CVMP guideline publications, China's MEE discharge standard records, and ANVISA regulatory submissions. Cross-referencing prescription volume data from national veterinary drug monitoring systems against manufacturing output statistics from customs and trade databases enabled bottom-up and top-down triangulation.
Historical antibiotic prescription trendlines across cattle, swine, poultry, and aquaculture segments established baseline growth patterns extrapolated across the projection horizon. Segmentation modeling incorporated pharmacological class, species application, formulation type, and distribution channel dimensions alongside regulatory framework clustering by geography. CAGRs derived from fitted trend analysis adjusted for antimicrobial stewardship policy implementation intensity. Forecast inputs included livestock herd consolidation rates, tele-veterinary platform penetration curves, and environmental compliance cost pass-through coefficients.
Revisions become necessary when MEE enforcement intensity exceeds modeled scenarios or Codex Alimentarius residue tolerance harmonization accelerates against national food safety regulator timelines. Forecasts reflect documented assumptions regarding prescription authorization pathway evolution and generic API supply concentration stability. A model refresh is warranted upon material change in EU Green Deal farm-to-fork antibiotic reduction target enforcement or China's dual carbon goal implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Animal Vaccine Market
Veterinary
Global Canine Atopic Dermatitis Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Pet Cremation Market
Veterinary
Wearable Sensors for Animal Health Management Market
Veterinary
Pet DNA Testing Market
Veterinary
Veterinary Thermography Market
Veterinary
Global Animal Model Market
Veterinary
Veterinary and Animal Healthcare Logistics Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Global Dog Vaccines Market
Veterinary
Global Swine Vaccines Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Veterinary Ophthalmic Equipment Market
Veterinary
Vet Software Market