
 Pet Cancer Therapeutics Market | 2026-2036
Pet Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Cancer Therapeutics Market Analysis
Consolidation among multi-site veterinary hospital groups is realigning procurement patterns for oncology therapeutics. Zoetis leverages its integrated diagnostics-to-treatment platform to secure long-term supply agreements with these expanding networks. Boehringer Ingelheim anchors its position through deep R&D investment in biologic modalities for companion animals. ELIAS Animal Health specializes in autologous cancer vaccines, differentiating its portfolio from mass-manufactured small-molecule alternatives.
Pet cancer therapeutics comprise pharmaceutical agents and biologic interventions designed to inhibit neoplastic cell proliferation, including alkylating agents, monoclonal antibodies, and checkpoint inhibitors formulated for canine and feline metabolism. These products undergo species-specific pharmacokinetic validation before commercial distribution to ensure therapeutic efficacy and minimize adverse events. Immunotherapy commands expanding development pipelines as checkpoint inhibitors demonstrate durable responses in lymphoma indications. Chemotherapy retains volume leadership through established protocols for osteosarcoma and mast cell tumors, though margin pools increasingly shift toward targeted therapy segments with higher pricing power and patent protection.
The FDA Center for Veterinary Medicine and the EMA Committee for Medicinal Products for Veterinary Use govern approval standards for novel oncology agents, extending development timelines but elevating clinical evidence requirements that favor well-capitalized developers. State veterinary practice acts and DEA controlled-substance scheduling further constrain distribution channels, privileging established manufacturers with compliant logistics infrastructure. Stakeholders must monitor evolving companion animal insurance reimbursement policies and their influence on physician prescribing behavior for premium-priced biologics.
Market Dynamics
Companion animal oncology is pivoting toward biologic modalities as checkpoint inhibitors demonstrate durable remission rates in lymphoma and melanoma indications, compressing development timelines for traditional chemotherapeutic protocols.
Growth Catalysts
- Immunotherapy platform maturation:Canine lymphoma patients receiving anti-PD-1 antibodies show response rates exceeding carboplatin protocols, accelerating veterinary oncologist training investments across United States referral networks.
- Pet insurance reimbursement expansion:United States and United Kingdom carriers now cover biologic cancer treatments, reducing out-of-pocket cost barriers for mast cell tumor interventions.
- EMA Committee for Medicinal Products for Veterinary Use streamlined pathways:Conditional marketing authorizations for novel biologics compress European commercialization timelines by twelve to eighteen months versus full approval routes.
Market Restraints
- Cold chain logistics concentration:Autologous vaccine production requires temperature-controlled distribution networks concentrated in Germany and Netherlands, creating single-point vulnerability for European supply security.
- Active pharmaceutical ingredient sourcing:Vincristine and doxorubicin precursors depend on Chinese and Indian bulk chemical manufacturers, exposing formulation costs to raw material volatility.
- FDA species-specific pharmacokinetic requirements:Beagle and feline metabolism studies add eighteen to twenty-four months to IND-to-approval timelines, elevating capital requirements for novel molecular entities.
Strategic Opportunities
- Japan veterinary oncology underpenetration:Pet insurance penetration lags United States benchmarks by forty percentage points, creating whitespace for biologic introduction as METI promotes companion animal welfare legislation.
- Telemedicine-integrated treatment monitoring:Remote chemotherapy supervision platforms enable community veterinary practices to retain oncology cases previously referred to urban academic centers.
- ISO 17025 laboratory accreditation convergence:Diagnostic laboratories achieving veterinary pathology certification unlock preferred supplier status with multi-site hospital procurement committees.
Industry Challenges
- Veterinary oncology specialist scarcity:American College of Veterinary Internal Medicine diplomate production averages sixty candidates annually, constraining service capacity expansion at specialty referral hospitals.
- Biologic manufacturing facility qualification:Cell culture suite validation and GMP compliance for autologous vaccines demand capital commitments exceeding fifteen million dollars per production site.
- Multi-jurisdictional patent harmonization:Companion animal therapeutic claims face divergent examination standards between USPTO and EPO, complicating freedom-to-operate assessments for monoclonal antibody platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Cancer Therapeutics Market |
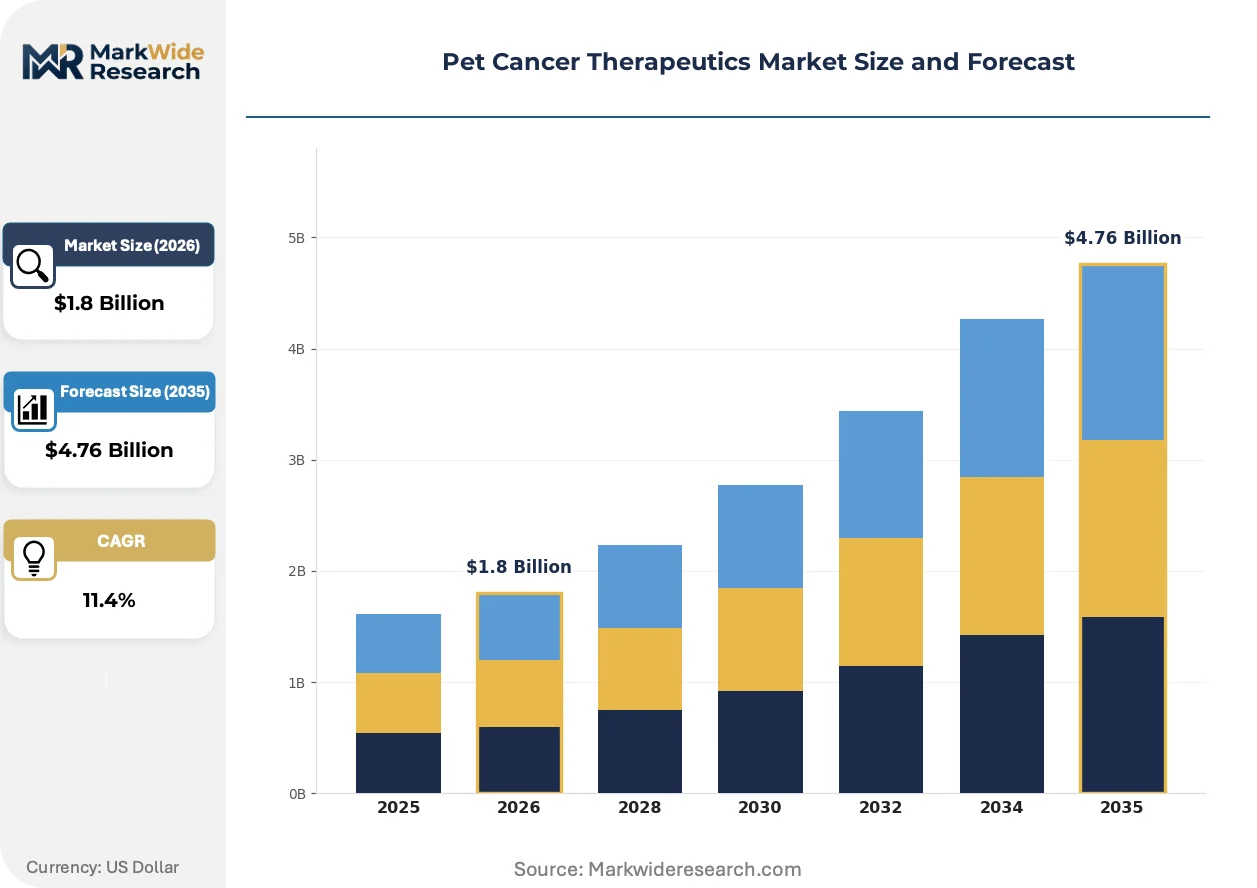
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Supportive Care End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Home Care Therapy Area: Lymphoma, Osteosarcoma, Hemangiosarcoma, Mast Cell Tumors Administration Route: Intravenous, Oral, Subcutaneous, Topical |
| Companies Covered | Zoetis, Elanco Animal Health, Boehringer Ingelheim, Virbac, AB Science, ELIAS Animal Health, Qbiotics, VetDC, Karyopharm Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Cancer Therapeutics Market Emerging Trajectories
Checkpoint inhibitor development pipelines are compressing the dominance of cytotoxic chemotherapy in first-line protocols, while diagnostic liquid biopsy platforms enable earlier therapeutic intervention windows.
Canine osteosarcoma vaccines utilizing autologous tumor lysate are converging with adoptive cell transfer protocols, enabling personalized neoantigen targeting. United States academic veterinary centers are adopting these platforms at accelerating pace, with three reference laboratories now offering commercial manufacturing services. This convergence is compressing the addressable market for standard-of-care amputation-plus-chemotherapy protocols.
EMA's 2023 revised guideline on quality, safety, and efficacy of immunological veterinary medicinal products elevates clinical evidence requirements for biologic oncology agents. Manufacturers must now demonstrate progression-free survival endpoints rather than objective response rates alone. Small-cap developers without Phase II infrastructure are exiting European filing strategies, consolidating opportunity among established biologics specialists.
Specialty veterinary hospital groups are unbundling chemotherapy administration from diagnostic interpretation, enabling community practitioners to retain revenue from supportive care while outsourcing protocol design. This channel fragmentation is most visible in United States metropolitan markets where corporate practice consolidation exceeds sixty percent penetration. Independent oncology specialists are responding with outcome-based care bundles that capture lifetime patient value.
Pet Cancer Therapeutics Market Segmentation
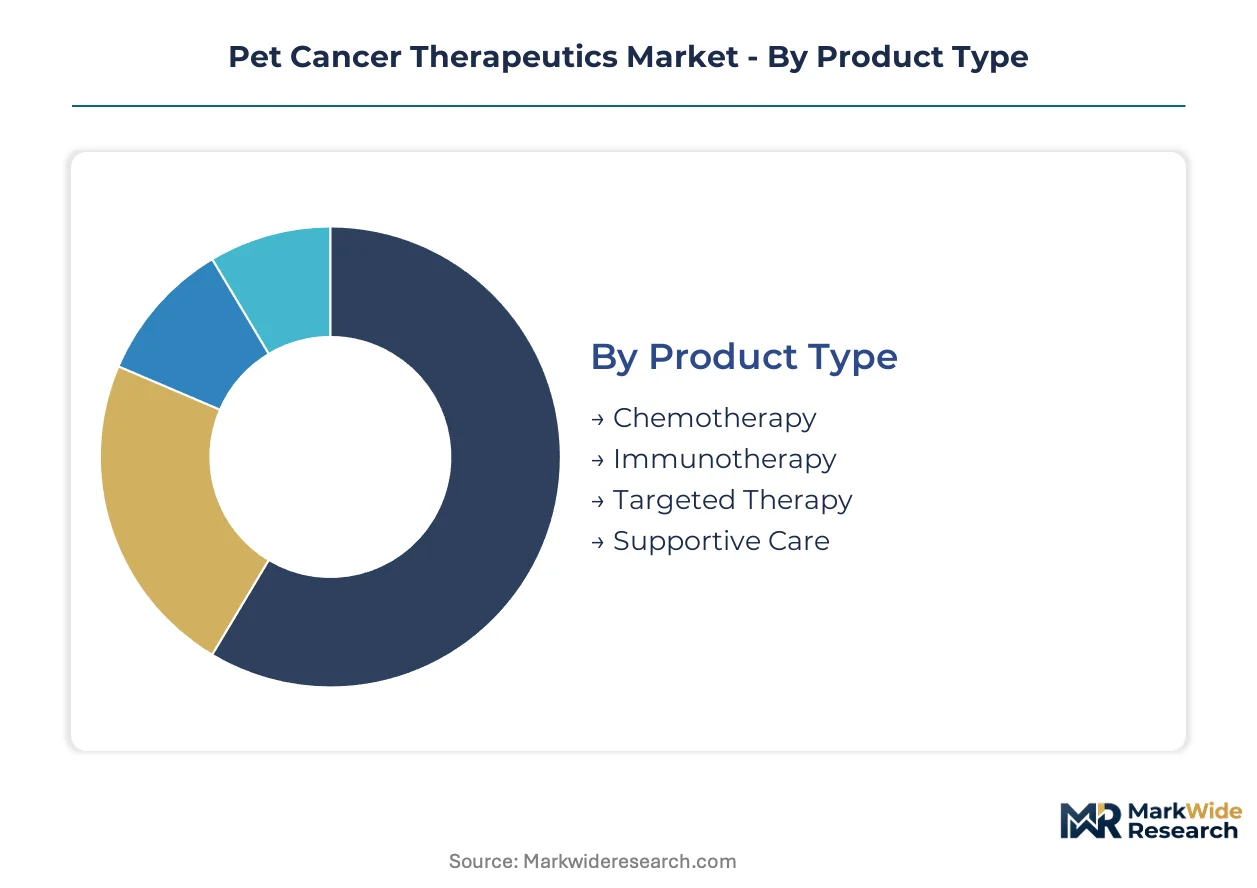
Pet cancer therapeutics segmentation reveals divergent margin profiles across standardized small-molecule chemotherapy and bespoke biologic manufacturing. Procurement committees at consolidated veterinary hospital groups weight formulary decisions differently across these divides, reshaping supplier competitive dynamics.
Product Type:
Standardized alkylating agents and antimetabolites occupy the chemotherapy tier, while autologous vaccines and monoclonal antibodies demand patient-specific production protocols.
- Chemotherapy:Established protocols for osteosarcoma and lymphoma rely on vincristine, doxorubicin, and carboplatin formulations with validated canine pharmacokinetic profiles. Demand concentrates in United States referral hospitals where pet insurance reimbursement supports multi-cycle administration regimens.
- Immunotherapy:Checkpoint inhibitors and autologous cancer vaccines trigger durable remissions in lymphoma indications through PD-1 and CTLA-4 pathway modulation. Manufacturing requires cell culture suites and GMP compliance that elevates production costs above small-molecule alternatives.
- Targeted Therapy:Tyrosine kinase inhibitors for mast cell tumors deliver precision intervention with reduced systemic toxicity versus cytotoxic protocols.
- Supportive Care:Anti-emetics, appetite stimulants, and pain management agents enable protocol completion rates in community veterinary settings.
Most installed capacity flows through chemotherapy. Expansion is steepest in immunotherapy.
End User:
Channel structure fragments across high-acuity tertiary centers and volume-driven primary care access points with divergent capital equipment requirements.
- Veterinary Clinics:Community practices administer oral chemotherapy and supportive care while referring complex cases to specialty networks. Revenue retention pressures are driving telemedicine-integrated monitoring investments that reduce referral leakage.
- Animal Hospitals:Multi-site corporate groups command procurement leverage through centralized formularies and long-term supply agreements with integrated diagnostics-to-treatment platforms.
- Research Institutions:Academic veterinary centers conduct Phase II trials for novel biologics and manufacture autologous vaccines under investigational protocols.
- Home Care:Oral targeted therapy administration shifts treatment delivery away from clinical settings, reducing cold chain logistics burdens for pet owners.
Volume concentrates in animal hospitals. Margin expansion is most rapid in home care.
Therapy Area:
Oncology service line planning prioritizes incidence prevalence and protocol standardization potential across tumor histologies.
- Lymphoma:B-cell and T-cell variants in canines respond to CHOP protocols and emerging anti-PD-1 antibodies with documented progression-free survival endpoints. United States academic centers are training diplomates in immunotherapy administration to meet referral demand.
- Osteosarcoma:Appendicular skeletal malignancies in large-breed dogs require amputation-plus-chemotherapy standards that autologous vaccines are beginning to displace.
- Hemangiosarcoma:Splenic and cardiac presentations carry poor prognosis with limited durable response to available therapeutics.
- Mast Cell Tumors:Cutaneous and visceral forms drive tyrosine kinase inhibitor prescribing in both specialty and community settings.
Treatment density peaks in lymphoma. Novel protocol adoption is advancing fastest in osteosarcoma.
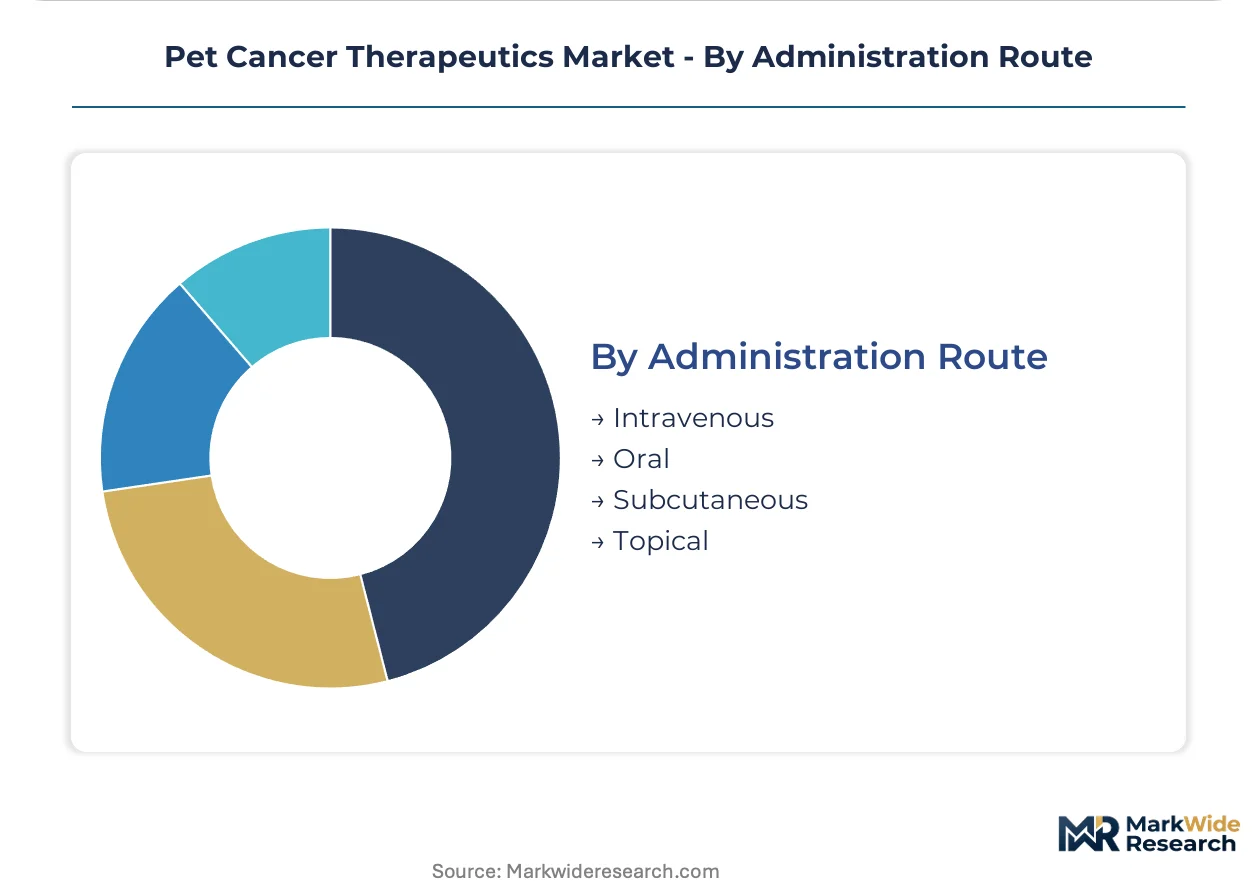
Administration Route:
Delivery modality selection determines site-of-care requirements and cold chain infrastructure investment intensity.
- Intravenous:Cytotoxic agents and monoclonal antibodies require infusion suite staffing and chemotherapy safety protocols that limit administration to specialty hospitals.
- Oral:Targeted small molecules and palliative agents enable home administration with compliance monitoring through telemedicine platforms.
- Subcutaneous:Autologous vaccines and certain biologics permit administration in community settings with reduced handling complexity versus intravenous protocols.
- Topical:Cutaneous mast cell tumor presentations utilize localized delivery for superficial lesions with minimal systemic exposure.
Procedure volume runs through intravenous. Patient convenience is driving share gains in oral.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands higher pet insurance penetration than the United Kingdom, yet both markets demonstrate accelerating biologic cancer treatment adoption. Germany anchors European autologous vaccine production capacity. Japan lags in insurance coverage but shows regulatory momentum. Australia concentrates specialist referral networks. Canada mirrors United States protocol standards with reduced biologic access.
United States
Referral hospital networks in metropolitan corridors drive demand for checkpoint inhibitors and autologous vaccines. The FDA Center for Veterinary Medicine maintains stringent pharmacokinetic validation requirements for novel biologics. Academic veterinary centers in California, Colorado, and North Carolina manufacture patient-specific vaccines under commercial contracts.
Germany
Specialty oncology practices in Munich and Berlin expand immunotherapy service portfolios as companion animal spending rises. The EMA Committee for Medicinal Products for Veterinary Use offers conditional marketing authorizations that compress European commercialization timelines. Cell culture facilities in Baden-Württemberg and Bavaria concentrate autologous vaccine production capacity for Western European distribution.
United Kingdom
Pet insurance carriers now reimburse biologic cancer treatments, reducing out-of-pocket barriers for lymphoma interventions. The Veterinary Medicines Directorate aligns with EMA standards while maintaining national pharmacovigilance protocols. London and Southeast England referral hospitals train diplomates in anti-PD-1 antibody administration to meet rising case volumes.
Japan
Companion animal welfare legislation promoted by METI creates whitespace for biologic introduction despite lagging insurance penetration. The PMDA applies species-specific safety requirements that extend development timelines for novel molecular entities. Tokyo and Osaka academic centers pilot immunotherapy protocols through investigator-initiated trials.
Australia
Specialist referral networks concentrate in Sydney and Melbourne with limited biologic manufacturing infrastructure. The TGA governs veterinary medicine approvals with reference to APVMA guidelines for novel oncology agents. Queensland and Victoria universities conduct Phase II trials for osteosarcoma vaccines through commercial research partnerships.
Pet Cancer Therapeutics Market Vendor Landscape
United States producers anchor one tier; European specialists hold manufacturing advantages in autologous platforms. Market structure fragments across integrated pharmaceutical conglomerates, dedicated animal health divisions, and emerging biologic specialists. Three archetypes dominate: diagnostics-to-treatment platform integrators, biologic modality developers, and autologous vaccine manufacturers. Consolidation among multi-site veterinary hospital groups drives long-term supply agreement competition, while cold chain logistics partnerships secure distribution exclusivity.
Within the integrated platform tier, Zoetis and Elanco Animal Health exemplify scale-driven market presence. Boehringer Ingelheim anchors the biologic modality developer archetype through deep R&D positioning. ELIAS Animal Health occupies a distinct position among autologous vaccine specialists, differentiating from mass-manufactured alternatives. These three entities represent the competitive spectrum from conglomerate integration to bespoke manufacturing specialization.
| Leading Market Players |
|---|
| Zoetis |
| Elanco Animal Health |
| Boehringer Ingelheim |
| Virbac |
| AB Science |
| ELIAS Animal Health |
| Qbiotics |
| VetDC |
| Karyopharm Therapeutics |
| Others |
Supply Flow & Price Mechanics
Captive cell culture manufacturing in Germany and the Netherlands anchors both supply security and pricing power for autologous cancer vaccines, while outsourced small-molecule production in India and China constrains margin expansion for generic chemotherapy agents. This bifurcation concentrates premium pricing with integrated biologic manufacturers and compresses returns for commoditized alkylating agents.
Pricing Analysis
Capacity additions in Baden-Württemberg and Bavaria are reshaping price floors for patient-specific immunotherapies as GMP-compliant suite expansion outpaces referral hospital procurement growth. Pricing stratifies across premium autologous vaccines, standard monoclonal antibodies, and economy-tier generic chemotherapy with vincristine and doxorubicin facing the steepest compression. Cost pressure in the chemotherapy tier intensifies because Chinese API feedstock volatility transmits directly to formulation costs. Community veterinary clinics exhibit highest price sensitivity for supportive care agents, while academic referral centers absorb premium biologic pricing through insurance reimbursement channels.
Supply Chain Analysis
Dual-sourcing qualification requirements from consolidated veterinary hospital groups mandate redundant supplier relationships for checkpoint inhibitors and cold-chain biologics. Manufacturing concentration centers on Germany, the United States, and the Netherlands for cell culture-derived products, while active pharmaceutical ingredient production draws from India and China for cytotoxic agents. Single-source vulnerability runs through temperature-controlled distribution networks for autologous vaccines, where qualified logistics partners in the Netherlands handle Western European fulfillment. Distribution runs through specialty veterinary distributors with GMP warehouse certification, though direct-to-hospital agreements are gaining share among multi-site corporate groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where companion animal owners shift spending toward progression-free survival endpoints and away from palliative cytotoxic protocols. Premium biologic specifications now command formulary preference at consolidated referral networks.
For Market Incumbents: Acquire cell culture manufacturing assets in Germany or the Netherlands to secure captive supply of autologous vaccine capacity. Consolidate backward integration into canine pharmacokinetic testing facilities to compress IND-to-approval timelines against FDA species-specific requirements. Defensive positioning requires pre-emptive long-term supply agreements with expanding multi-site hospital groups before competitor biologics gain formulary entry.
For New Entrants and Emerging Players: Launch via telemedicine-integrated monitoring platforms that enable community practices to retain oncology revenue previously leaked to academic referral centers. Target Japan's whitespace where METI welfare legislation precedes insurance penetration expansion. White-space concentration sits with oral targeted therapy formulations for mast cell tumors that shift site-of-care toward home administration and reduce cold chain infrastructure barriers.
For Investors and Strategic Acquirers: Roll-up economics work for autologous vaccine specialists because manufacturing facility qualification costs exceed fifteen million dollars per site and constrain small-cap developer entry. The five-to-ten year viability window favors platforms with demonstrated progression-free survival endpoints under EMA revised guidelines. Watch FDA conditional approval pathways for canine lymphoma indications as the inflection signal for immunotherapy platform valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | GMP cell culture suite expansion in Germany secures Western European autologous vaccine supply security. |
| Regulatory Approval Pathway | FDA Center for Veterinary Medicine species-specific pharmacokinetic validation elevates clinical evidence requirements for novel biologics. |
| Long-term Supply Agreement | Multi-year contracts with consolidated veterinary hospital groups lock in formulary preference for checkpoint inhibitors. |
| Pipeline Diversification | Expansion from lymphoma into osteosarcoma indications captures share from amputation-plus-chemotherapy standards. |
| Strategic Partnership | Telemedicine platform alliances enable community practices to retain cases with remote chemotherapy supervision. |
Methodological Framework
Multiple input streams — regulatory filing databases, veterinary hospital procurement records, and companion animal insurance claims data — were reconciled through bottom-up and top-down triangulation. Primary interviews engaged veterinary oncologists, animal health procurement directors, biologic manufacturing executives, and pet insurance reimbursement specialists. Secondary validation drew from FDA Center for Veterinary Medicine submissions, EMA Committee for Medicinal Products for Veterinary Use filings, and multi-site veterinary hospital group financial disclosures.
Data-stream reconciliation across the projection horizon applied treatment-line segmentation by therapy area, administration route clustering by site-of-care requirements, and regional regulatory framework differentiation. CAGRs were derived from installed base growth rates, protocol adoption curves, and pricing trajectory modeling. Forecast inputs incorporated pet insurance penetration benchmarks, veterinary oncology specialist production rates, and conditional marketing authorization timelines.
Several conditions sit outside the modeled scope, including investigator-initiated trial outcomes, raw material tariff regime shifts, and pandemic-related veterinary service disruptions. Deviation in FDA species-specific pharmacokinetic study requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
OTC Cat Medicines Market
Veterinary
Veterinary Healthcare Market
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Veterinary Ophthalmic Equipment Market
Veterinary
CBD Pet Market
Veterinary
Global Livestock Vaccines Market
Veterinary
Veterinary Thermography Market
Veterinary
Global Animal Vaccine Market
Veterinary
Global Animal Sedative Market
Veterinary
Europe Veterinary Healthcare Market
Veterinary
Veterinary in Vitro Fertilization Market
Veterinary
Mastitis Market
Veterinary
Veterinary Clostridium Vaccine Market
Veterinary
Canine Flu Therapeutics Market
Veterinary
Global Animal Intestinal Health Market
Veterinary
Veterinary Vaccine Adjuvants Market