
 Attenuated Vaccines Market | 2026-2036
Attenuated Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Attenuated Vaccines Market Outlook
Public procurement channels is tilting toward tiered supplier qualification systems that favor manufacturers with WHO prequalification status. GlaxoSmithKline plc leverages its established prequalification portfolio to sustain large-volume tenders across multiple geographies. Serum Institute of India Pvt. Ltd. anchors supply security for Gavi-eligible markets through in-house bulk antigen production. Merck & Co. differentiates by controlling specialized cold-chain distribution networks for thermolabile live-virus formulations.
Attenuated vaccines contain live pathogens weakened through serial passage in cell culture or embryonated eggs, reducing virulence while preserving immunogenicity; formulations typically require sustained cold-chain storage between two and eight degrees Celsius to maintain titer potency. The product-type dimension centers on measles-mumps-rubella combination vaccines as the mature revenue base, while yellow fever supply tightens amid production bottlenecks at a limited number of seed-virus facilities. Subcutaneous administration dominates pediatric delivery, though intranasal platforms attract R&D allocation for needle-free compliance gains in school-based programs.
FDA lot-release protocols and WHO prequalification standards jointly determine market access timelines for new attenuated vaccine submissions, with EMA batch-testing reciprocity reducing redundant certification burdens for European supply. India's CDSCO aligns domestic licensing with WHO technical standards, enabling parallel registration for export-oriented manufacturers such as Bharat Biotech. Stakeholders must monitor how evolving stability-data requirements for alternative temperature profiles reshape formulation investment priorities without assuming legacy cold-chain dependencies will persist unchanged.
Market Dynamics
Cold-chain infrastructure gaps in tropical climates are forcing manufacturers toward thermostable formulation investments that reduce distribution dependency on sustained refrigeration between two and eight degrees Celsius.
Growth Catalysts
- WHO Prequalification Pathways:India's CDSCO alignment with WHO technical standards accelerates parallel licensing for export-oriented manufacturers targeting Gavi-eligible procurement channels.
- Pediatric Program Expansion:National immunization schedules in Indonesia, Nigeria, and Bangladesh incorporate measles-mumps-rubella combination doses into routine childhood delivery.
- mRNA Platform Spillover:Lipid nanoparticle stabilization techniques developed for COVID-19 vaccines transfer to live-virus envelope preservation, extending shelf-life at elevated temperatures.
Market Restraints
- Embryonated Egg Supply Concentration:Yellow fever seed-virus production bottlenecks at limited WHO-approved facilities create single-source vulnerability for outbreak response stockpiles.
- Cold-Chain Capex Burden:Solar-powered refrigeration deployment in rural sub-Saharan Africa requires donor co-financing that delays program scale-up timelines.
- Regulatory Divergence:FDA lot-release protocols and EMA batch-testing reciprocity gaps force redundant stability studies for multi-jurisdictional submissions.
Strategic Opportunities
- Intranasal Delivery Platforms:Needle-free administration formats attract R&D allocation for school-based immunization compliance gains in densely populated South Asian urban corridors.
- Thermostable Formulation White Space:Lyophilization advances and excipient engineering enable ambient-temperature distribution models that bypass legacy refrigeration infrastructure.
- PLI Scheme Incentives:India's production-linked incentive framework subsidizes bulk antigen manufacturing capacity expansion for export market capture.
Industry Challenges
- Seed-Virus Facility Certification Timelines:WHO prequalification audits for new manufacturing sites extend 18-24 months, constraining surge capacity during outbreak emergencies.
- Specialized Cold-Chain Talent Scarcity:Qualified personnel for temperature-controlled logistics and vaccine vial monitor interpretation remain underrepresented in frontier market distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Attenuated Vaccines Market |
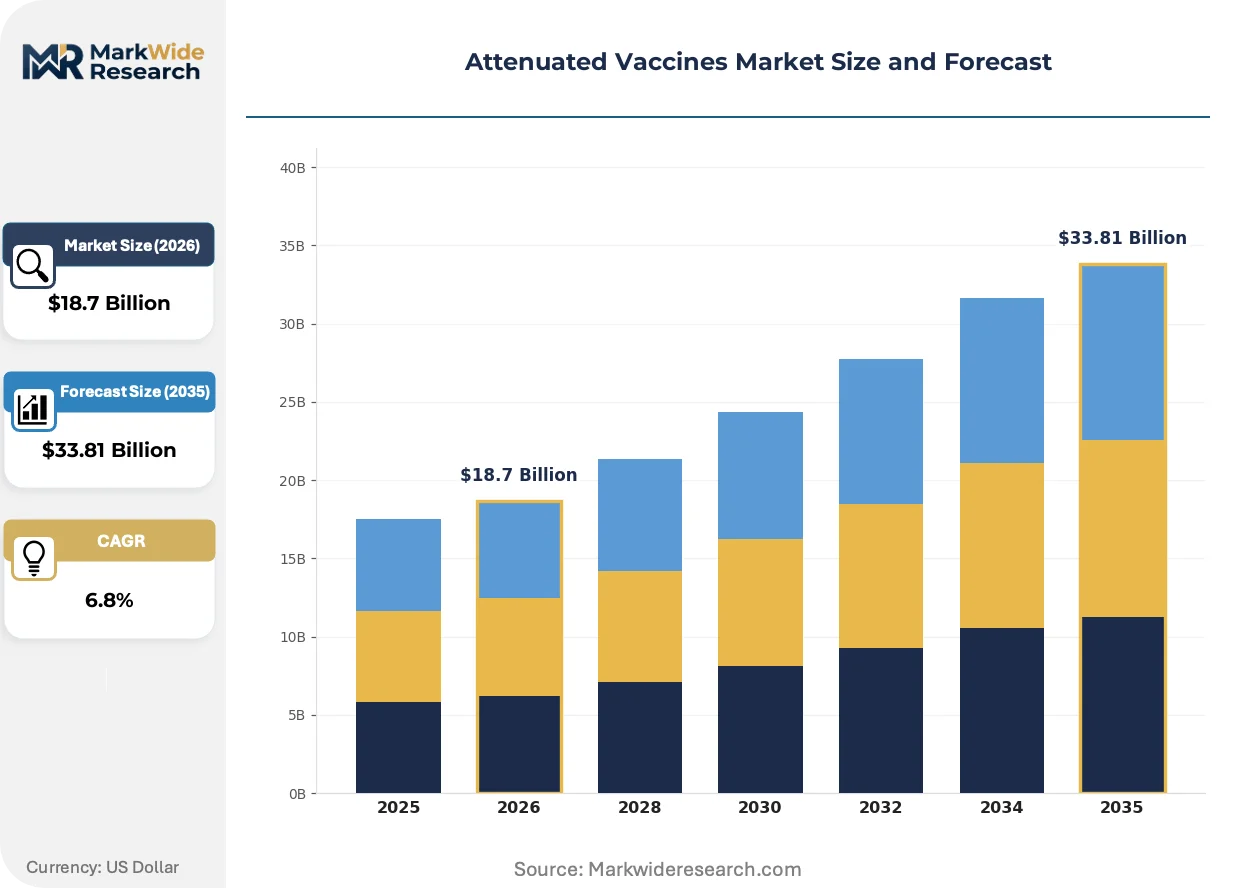
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Measles, Mumps, Rubella, Yellow Fever End User: Hospitals, Clinics, Research Institutions, Pharmacies Administration Route: Intramuscular, Subcutaneous, Oral, Intranasal Distribution Channel: Direct, Wholesale, Online, Retail |
| Companies Covered | GlaxoSmithKline plc, Merck & Co., Pfizer Inc., Sanofi, Serum Institute of India Pvt. Ltd., Johnson & Johnson, AstraZeneca, Bharat Biotech, CSL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Attenuated Vaccines Market Strategic Shifts
Formulation science and delivery modality convergence are compressing traditional cold-chain dependencies while regulatory harmonization efforts reshape manufacturing investment priorities across prequalification-dependent markets.
Lyophilization technology is migrating from niche outbreak-stockpile applications toward routine pediatric combination vaccines, with Serum Institute of India and Bharat Biotech deploying spray-dried live-virus matrices for measles-rubella presentations. African national immunization programs pilot ambient-stable formats in last-mile distribution trials. This migration from frozen-liquid dependency toward dry-powder stability is enabling direct-to-clinic delivery models that bypass regional cold-store infrastructure.
EMA batch-testing reciprocity agreements with WHO prequalification standards are reducing redundant certification burdens for European supply, though FDA lot-release protocols maintain independent potency verification requirements that fragment regulatory timelines. Indian manufacturers leverage CDSCO-WHO alignment to compress parallel registration cycles. Pediatric combination vaccines face the steepest compliance complexity given multi-antigen stability data requirements across divergent jurisdiction protocols.
Public procurement consolidation through Gavi and UNICEF Supply Division is compressing supplier qualification windows toward tiered prequalification status as a binary eligibility filter. Manufacturers without WHO-approved facilities face exclusion from multi-year tender awards regardless of price competitiveness. This buyer-concentration dynamic concentrates contract awards among established prequalification holders in India and selected European facilities, with Southeast Asian national programs adopting similar tiered supplier frameworks for domestic procurement.
Attenuated Vaccines Market Segmentation
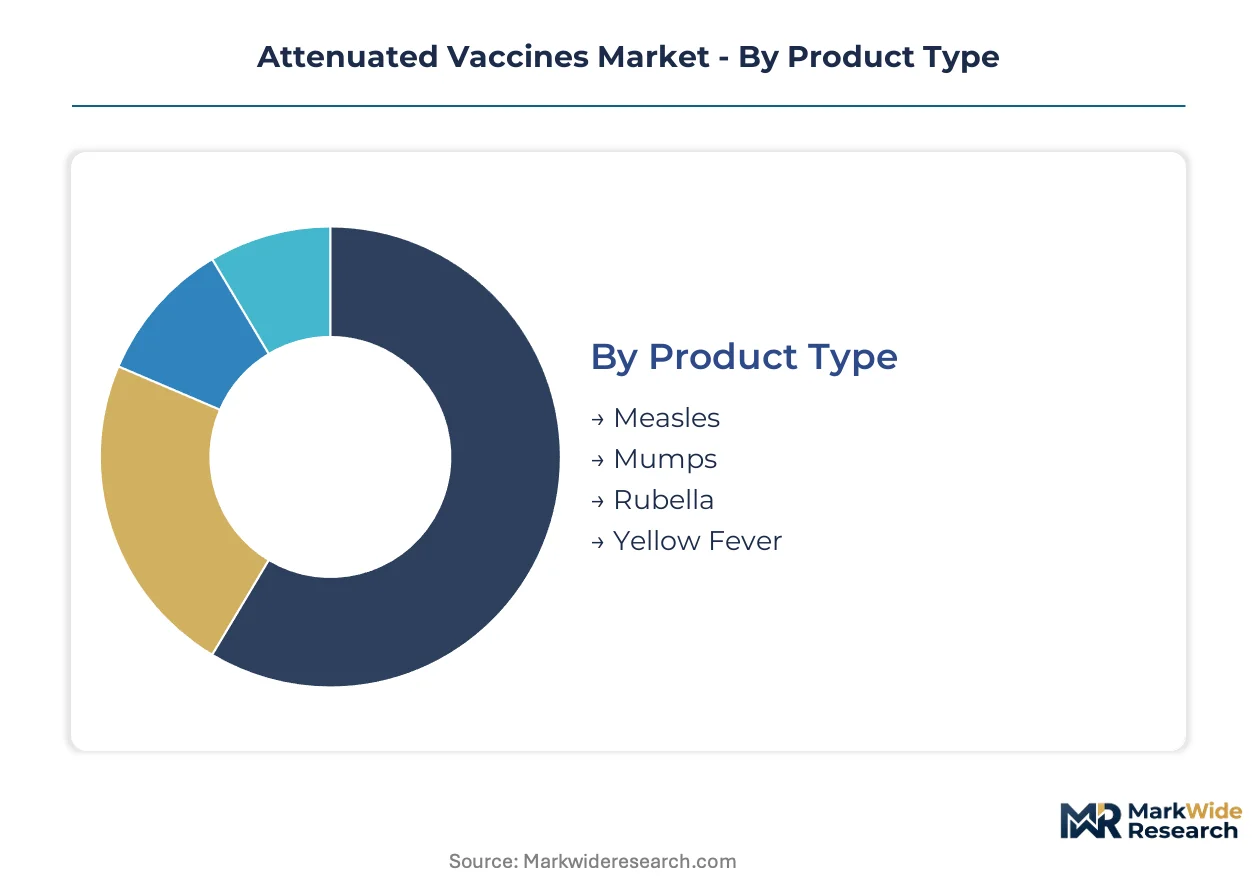
Segmentation in attenuated vaccines reveals how formulation requirements, delivery constraints, and procurement channel structures fragment commercial opportunity across distinct operational models. Understanding these divides helps manufacturers align R&D investment with the infrastructure realities of target markets.
Product Type:
After-sales service intensity varies sharply across product types, with combination vaccines demanding technical support for cold-chain troubleshooting while single-antigen formats require less post-delivery intervention.
- Measles:Live-attenuated Edmonston-Zagreb or Schwarz strain formulations require sustained two-to-eight-degree Celsius storage throughout distribution. Demand concentrates in Gavi-eligible African markets where national immunization programs prioritize first-dose coverage campaigns.
- Mumps:Jeryl Lynn-derived attenuated strains demonstrate superior thermal stability compared to Urabe AM9 alternatives, influencing procurement decisions in tropical climates with intermittent refrigeration. Nigerian and Indonesian public health programs favor this strain profile for routine pediatric schedules.
- Rubella:RA 27/3 strain vaccines serve congenital rubella syndrome elimination initiatives across Southeast Asian urban corridors.
- Yellow Fever:17D-204 substrain production faces seed-virus bottlenecks at WHO-approved facilities, constraining outbreak response stockpiles.
Measles holds the largest share; momentum sits with MMR combination formats.
End User:
Cost tier stratification separates institutional purchasers with cold-chain infrastructure from retail channels serving individual travelers.
- Hospitals:Tertiary facilities with on-site pharmacy-grade refrigeration manage bulk inventory for inpatient pediatric wards and pre-travel consultation clinics. Indian government hospitals anchor public procurement volume through centralized state-level tendering.
- Clinics:Primary health centers in Bangladesh and Nigeria rely on passive cooling devices and vaccine vial monitors for last-mile delivery. These facilities generate recurring demand for single-dose presentations that minimize wastage from multi-dose vial policy constraints.
- Research Institutions:Academic medical centers and WHO collaborating centers conduct phase III field trials for thermostable formulation candidates.
- Pharmacies:Retail channels in urban India and Brazil serve private-pay travelers requiring yellow fever certification for international entry requirements.
Hospitals command the greatest procurement volume; clinics show the steepest expansion trajectory as national programs push toward universal coverage.
Administration Route:
Application context determines route selection, with mass campaigns favoring rapid-deployment methods while routine immunization accepts slower techniques.
- Intramuscular:Deltoid injection of inactivated vaccines occasionally substitutes for attenuated alternatives in specific contraindication scenarios. This route sees limited use in attenuated vaccine portfolios due to inferior immunogenicity for live-virus formulations.
- Subcutaneous:Standard delivery for measles-containing vaccines and yellow fever products, leveraging adipose tissue drainage to lymph nodes. Indonesian school-based immunization programs deploy this route for grade-level MMR catch-up campaigns.
- Oral:Sabin poliovirus vaccine represents the dominant oral attenuated format, though polio eradication transition has shifted procurement toward inactivated alternatives. Rotavirus oral vaccines share distribution infrastructure with this modality.
- Intranasal:Needle-free delivery attracts R&D allocation for influenza live-attenuated intranasal platforms, with spillover potential for measles aerosol formulations under WHO investigation.
Subcutaneous administration dominates current volume; intranasal platforms are gaining share fastest through needle-free compliance advantages.
Distribution Channel:
Supply concentration shapes channel viability, with manufacturer scale determining whether direct engagement or intermediary networks prove economical.
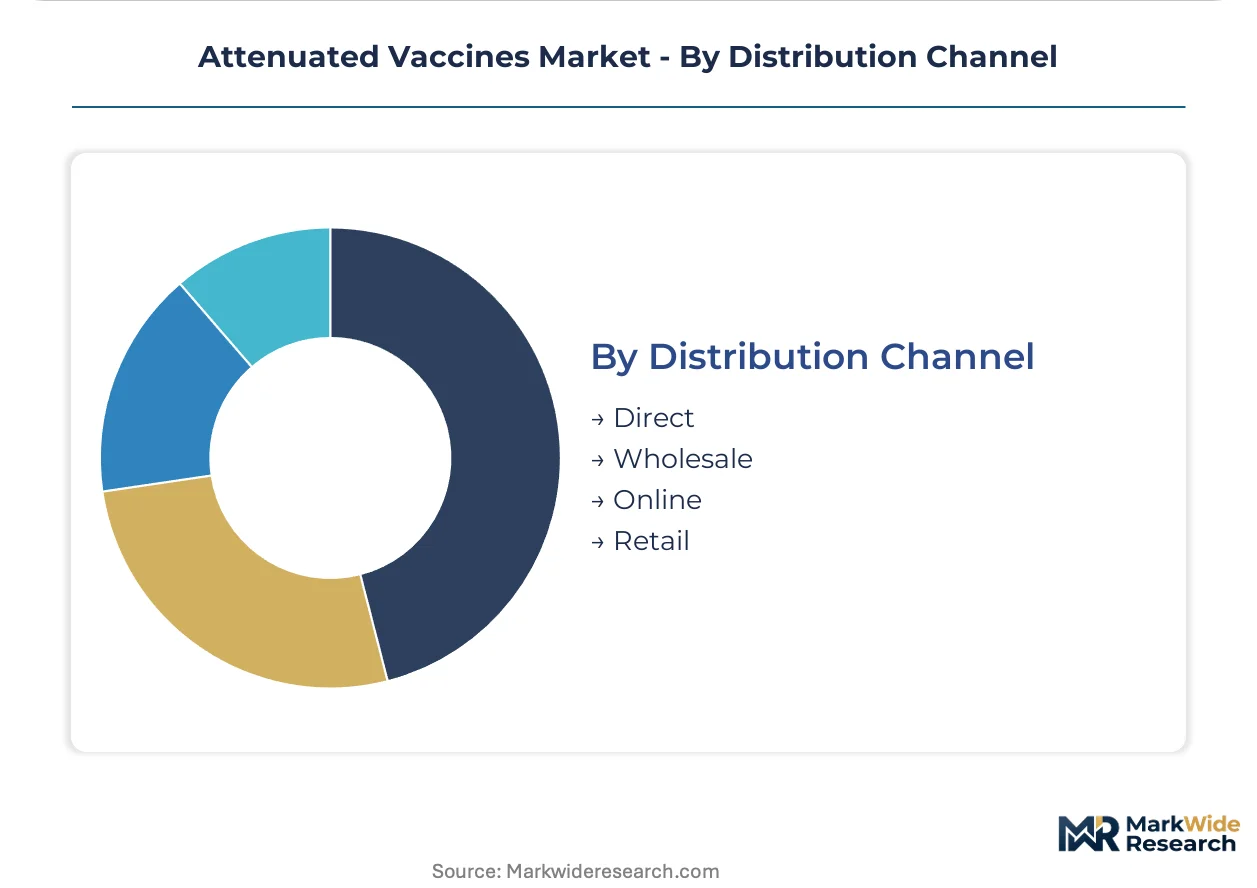
- Direct:Serum Institute of India and Bharat Biotech maintain direct supply relationships with UNICEF Supply Division and national governments for Gavi-eligible procurement. This channel eliminates margin stacking but requires dedicated tender response capabilities and WHO prequalification maintenance.
- Wholesale:Regional vaccine distributors in sub-Saharan Africa aggregate demand across multiple national programs, offering consolidated cold-chain logistics that smaller manufacturers cannot replicate independently.
- Online:Digital procurement platforms serve private-sector travel medicine clinics in Brazil and India with scheduled delivery and temperature-logging documentation.
- Retail:Pharmacy chains in urban Southeast Asian markets stock travel vaccines for immediate dispensing to outbound tourists.
Direct channels capture the prequalified institutional segment; wholesale networks are expanding most quickly as African immunization programs consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold-chain logistics networks and WHO prequalification manufacturing hubs define geographic opportunity distribution. National immunization program scale and regulatory alignment determine procurement access tiers across key production and consumption centers.
India
Serum Institute of India and Bharat Biotech anchor bulk antigen production for Gavi-eligible markets. CDSCO alignment with WHO technical standards compresses parallel licensing cycles for export-oriented manufacturers. The Pune-Hyderabad vaccine corridor concentrates lyophilization capacity and thermostable formulation R&D.
United States
FDA lot-release protocols maintain independent potency verification requirements that fragment multi-jurisdictional submission timelines. Federal procurement through CDC stockpile programs sustains demand for yellow fever and MMR combination doses. Maryland and Massachusetts biotech clusters host specialized seed-virus facilities and cold-chain distribution infrastructure.
Indonesia
National immunization schedules incorporate measles-mumps-rubella combination doses into routine childhood delivery across 17,000 islands. The Ministry of Health's cold-chain expansion program deploys solar-powered refrigeration in Eastern provinces. Java-based distribution hubs manage last-mile logistics for subcutaneous vaccine delivery in school-based campaigns.
Germany
EMA batch-testing reciprocity with WHO prequalification standards reduces redundant certification burdens for European supply. Bavarian and Hesse manufacturing zones concentrate fill-finish capacity for thermolabile live-virus formulations. Frankfurt and Munich airports anchor specialized pharmaceutical cargo corridors for temperature-controlled exports.
Brazil
ANVISA licensing frameworks govern domestic attenuated vaccine registration while retail pharmacy channels serve private-pay travelers requiring yellow fever certification. The São Paulo-Rio de Janeiro corridor concentrates hospital procurement volume through state-level centralized tendering. Butantan Institute maintains public-sector manufacturing capacity for outbreak response stockpiles.
Attenuated Vaccines Market Competitive Environment
On the supply side, the industry is consolidating around WHO prequalification status as a binary eligibility filter for institutional procurement. Established bulk antigen producers with in-house seed-virus facilities occupy tier-one positions, while regional fill-finish specialists serve domestic markets. Two archetypes dominate: vertically integrated manufacturers controlling upstream antigen production, and distribution-focused entities leveraging specialized cold-chain networks. Competitive moves center on thermostable formulation licensing and prequalification audit acceleration.
Within the vertically integrated tier, GlaxoSmithKline plc and Serum Institute of India Pvt. Ltd. exemplify contrasting scale models. Merck & Co. occupies a position defined by cold-chain distribution specialization for thermolabile formats. These three anchors illustrate how geographic regulatory alignment and infrastructure control separate procurement-access tiers in Gavi-eligible markets.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Merck & Co. |
| Pfizer Inc. |
| Sanofi |
| Serum Institute of India Pvt. Ltd. |
| Johnson & Johnson |
| AstraZeneca |
| Bharat Biotech |
| CSL Limited |
| Others |
Value Chain & Pricing Dynamics
Seed-virus facility concentration in India and selected European sites anchors margin capture at the bulk antigen tier, while downstream fill-finish operations compete on cost efficiency. WHO prequalification status functions as a pricing gatekeeper that separates prequalified institutional suppliers from price-competitive but excluded regional manufacturers.
Pricing Analysis
Volume-discount tiering structures dominate Gavi and UNICEF procurement channels, with multi-year tenders rewarding manufacturers achieving ten-million-dose annual commitments. Price differentiation rests on WHO prequalification status and thermostable formulation certification, with ambient-stable presentations commanding modest premiums over frozen-liquid alternatives. Pricing pressure stems from donor budget consolidation and expanded supplier lists in Indian manufacturing. Public procurement officers at national immunization programs exhibit highest price sensitivity; private travel medicine clinics show lowest sensitivity due to patient out-of-pocket payment structures.
Supply Chain Analysis
Upstream embryonated egg and seed-virus feedstock draws from India, Germany, and the United States, with limited WHO-approved facilities creating single-source dependencies for yellow fever production. Critical inputs span specific-pathogen-free eggs, live-virus master seeds, and specialized excipients for lyophilization stability. Supply chain risk centers on regulatory audit backlogs that extend facility certification timelines. Distribution runs through UNICEF Supply Division and national government tenders for institutional volume, with regional wholesalers managing fragmented private-sector channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified personnel for temperature-controlled logistics and vaccine vial monitor interpretation remain acutely scarce across frontier market distribution networks, constraining last-mile delivery scale-up regardless of manufacturing capacity expansion.
For Market Incumbents: Pre-empt thermostable formulation licensing from regional challengers by accelerating lyophilization R&D partnerships with Indian CDSCO-aligned facilities. Prioritize backward integration into seed-virus master seed banks to reduce dependency on limited WHO-approved external suppliers. Secure multi-year Gavi tender extensions before ambient-stable alternatives from Bharat Biotech and Serum Institute of India reach full commercial scale. For New Entrants and Emerging Players: Establish a beachhead in intranasal delivery platform development for school-based measles immunization programs in Indonesian and Bangladeshi urban corridors. Target thermostable formulation white space where legacy cold-chain infrastructure gaps persist in sub-Saharan African national programs. Deploy licensing partnerships with established WHO prequalified manufacturers rather than pursuing independent facility certification. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated bulk antigen producers with captive seed-virus facilities and existing WHO prequalification portfolios. Long-term viability favors manufacturers controlling both upstream antigen production and specialized cold-chain distribution networks for thermolabile formats. Monitor CDSCO audit acceleration timelines and Gavi supplier list expansion decisions as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Thermostable Formulation Development | Lyophilization advances enable ambient-temperature distribution bypassing legacy refrigeration infrastructure in tropical climates. |
| WHO Prequalification Acceleration | CDSCO-aligned audit pathways compress parallel licensing cycles for Indian manufacturers targeting Gavi-eligible procurement. |
| Intranasal Platform R&D | Needle-free delivery formats address compliance gaps in densely populated South Asian school-based immunization programs. |
| Seed-Virus Facility Certification | WHO-approved master seed banks reduce single-source vulnerability for yellow fever outbreak response stockpiles. |
| Cold-Chain Distribution Specialization | Solar-powered refrigeration deployment and vaccine vial monitor training expand last-mile reach in rural sub-Saharan Africa. |
Study Parameters
Initial hypotheses were tested against primary input from regulatory affairs directors at attenuated vaccine manufacturers, national immunization program managers in Gavi-eligible countries, cold-chain logistics specialists, and WHO prequalification auditors, then refined through secondary validation. Primary interviews combined with FDA lot-release documentation, CDSCO licensing records, Gavi tender award databases, and UNICEF Supply Division procurement reports. Bottom-up demand modeling across pediatric program expansion timelines triangulated with top-down manufacturing capacity assessments.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, end user, administration route, and distribution channel. CAGRs were derived from installed base expansion rates and dose-volume projections by national immunization schedule. Forecast inputs incorporated cold-chain infrastructure investment trajectories and regulatory harmonization progress between FDA, EMA, and WHO standards.
Stress conditions across seed-virus facility certification delays, donor budget volatility, and thermostable formulation adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory alignment timelines and procurement consolidation patterns. Cross-checking against WHO prequalification pipeline data and Gavi supplier diversification announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Sarcoidosis Drugs Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Europe Contraceptives Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Middle East and Africa Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Ciclopirox Olamine Market