
 Veterinary Biologics Market | 2026-2036
Veterinary Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Biologics Market Outlook
Market Context with Strategic Players
Companion animal clinics is expanding their share of veterinary biologics procurement as pet owners prioritize preventive care over reactive treatment. Zoetis Inc. leverages its vertical integration across vaccine manufacturing to sustain pricing power in the canine and feline segments. Merck Animal Health anchors its position through R&D intensity in cattle respiratory vaccines, while Boehringer Ingelheim Animal Health differentiates via geographic dominance in European livestock markets.
Technical Definition and Structural Segments
Veterinary biologics comprise immunologically active products derived from living organisms, including attenuated or inactivated viral vaccines with specified titers, polyclonal antisera, and recombinant immunoglobulins manufactured through cell culture or embryonated egg propagation, designed to induce active or passive immunity in animals. Vaccines occupy the largest value pool within product type segmentation due to recurring revaccination schedules, while diagnostic kits represent the fastest-expanding category as point-of-care testing displaces centralized laboratory workflows. Cattle and poultry dominate animal type demand by volume, though margin pools concentrate in canine and feline biologics where pricing power reflects pet owner willingness to pay.
Regulatory Framework and Forward Outlook
USDA Center for Veterinary Biologics governs licensure and batch release for animal vaccines in the United States, while EMA and national competent authorities enforce the EU Veterinary Medicines Regulation for immunological veterinary medicinal products across Europe. These frameworks shape demand by mandating efficacy demonstration against specified challenge strains and post-authorization pharmacovigilance reporting, which elevates barriers for new entrants and rewards incumbents with established regulatory infrastructure. Stakeholders must monitor convergence between USDA-CVB and EMA standards on recombinant product classification, as harmonization would reshape market access economics for multinational portfolios.
Market Dynamics
The veterinary biologics sector is experiencing a fundamental demand recalibration as specialty veterinary hospital chains consolidate procurement power and compress supplier negotiation cycles. This buyer concentration is forcing manufacturers to restructure their commercial operations around direct-account management rather than traditional distributor-led models.
Growth Catalysts
- USDA-CVB pathway acceleration:The Center for Veterinary Biologics has streamlined novel vaccine licensure timelines, reducing batch-release bottlenecks for recombinant products and incentivizing R&D investment in platform technologies.
- Companion animal preventive care protocols:Pet owner expenditure on scheduled immunization programs is displacing reactive treatment spending, creating recurring revenue streams for canine and feline vaccine portfolios.
- Point-of-care diagnostic adoption:Veterinary clinics are integrating rapid serology and PCR testing into appointment workflows, expanding the addressable market for companion animal diagnostic kits beyond centralized laboratories.
Market Restraints
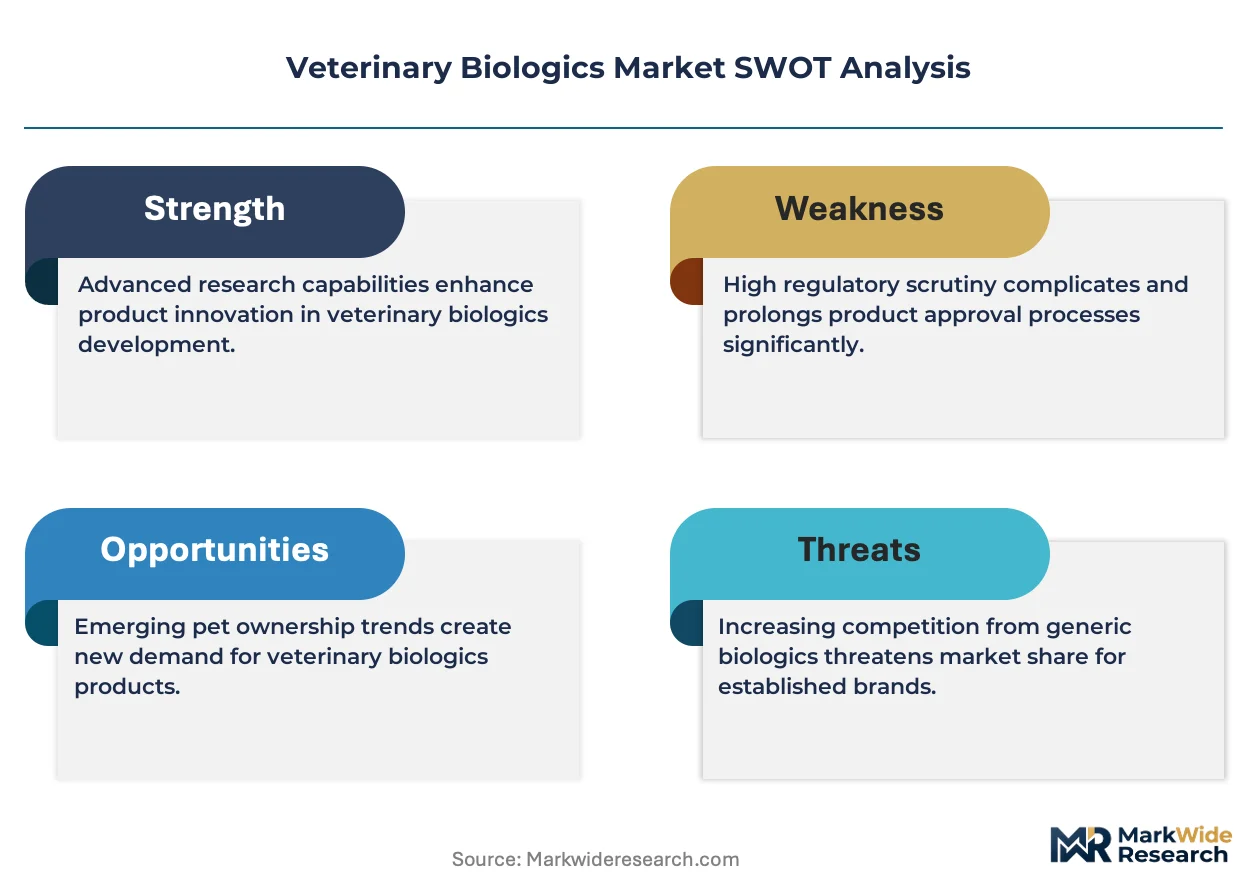
- Egg-based production dependency:Viral vaccine manufacturing remains tethered to embryonated chicken egg supply chains, exposing titers to avian influenza disruptions and input cost volatility.
- EMA batch-release complexity:The EU Veterinary Medicines Regulation imposes divergent stability-testing requirements versus USDA-CVB standards, fragmenting regulatory economics for multinational portfolios.
- Livestock vaccine margin compression:Cattle and poultry biologics face pricing pressure from generic inactivated vaccines, limiting reinvestment capacity for novel antigen development.
Strategic Opportunities
- Cell-culture platform migration:Suspension-based bioreactor production is absorbing investment from egg-dependent systems, enabling faster scale-up for pandemic response and reducing allergen contamination risks.
- US specialty hospital direct contracting:Consolidated veterinary chains in Texas, California, and Florida are negotiating exclusive supply agreements, bypassing traditional wholesale distribution.
- Digital health integration:Vaccine reminder systems and telemedicine platforms are creating stickier patient relationships, embedding biologics purchasing into subscription-based preventive care packages.
Industry Challenges
- Regulatory affairs talent scarcity:The convergence of USDA-CVB and EMA standards on recombinant classification is outpacing the supply of dual-qualified submission specialists.
- Cold chain integrity at last mile:Rural veterinary clinics lack validated storage infrastructure for temperature-sensitive live attenuated vaccines, risking potency degradation and efficacy failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Biologics Market |
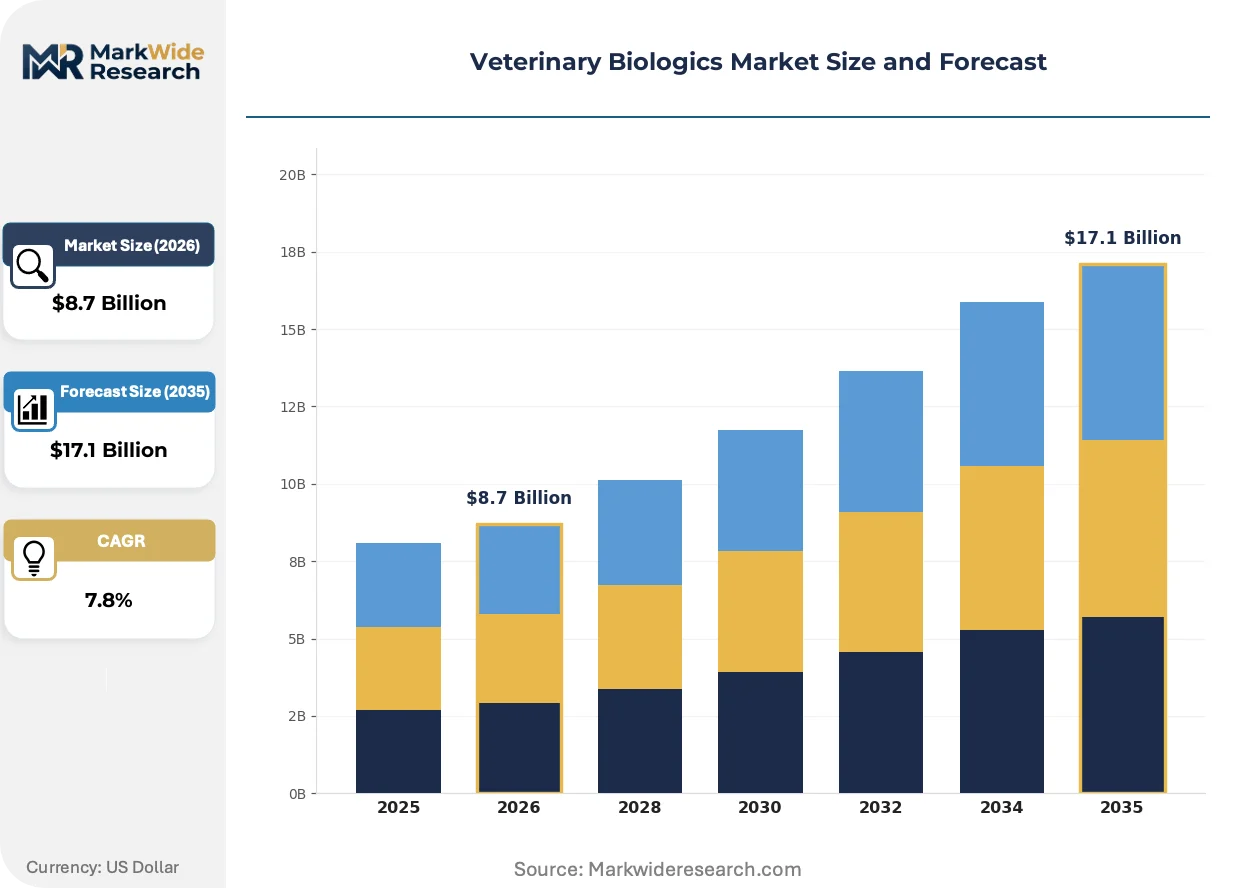
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antisera, Immunoglobulins, Diagnostic Kits Animal Type: Dogs, Cats, Cattle, Poultry Application: Preventive Care, Treatment, Diagnosis, Research Distribution Channel: Veterinary Clinics, Hospitals, Pharmacies, E-commerce |
| Companies Covered | Elanco Animal Health, Virbac SA, Zoetis Inc., Phibro Animal Health Corporation, IDEXX Laboratories Inc., Merck Animal Health, Ceva Sante Animale, Hester Biosciences Limited, Boehringer Ingelheim Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Biologics Market Strategic Shifts
mRNA platform technology is penetrating veterinary vaccine development, transferring manufacturing expertise from human pharmaceutical applications into animal health. This convergence is compressing development timelines and enabling rapid response to emerging pathogen variants.
DNA-launched viral vector vaccines are absorbing development resources previously allocated to conventional inactivated platforms. Large livestock operations in the US Midwest are piloting these products for bovine respiratory disease, attracted by reduced handling stress and single-dose efficacy profiles. The technology is absorbing regulatory attention as USDA-CVB establishes novel efficacy endpoints for gene-based immunization.
The EU Veterinary Medicines Regulation is mandating environmental risk assessments for all new immunological products, extending registration timelines for aquatic and wildlife vaccines. Manufacturers targeting European livestock markets are restructuring dossiers to include ecotoxicology data, while companion animal biologics face lighter scrutiny under the same framework. This divergence is fragmenting portfolio prioritization decisions for multinational suppliers.
Subscription-based preventive care bundles are displacing transaction-based vaccine purchasing in companion animal practice. Veterinary clinic chains in metropolitan US markets are unbundling core immunizations from wellness exams, creating transparent pricing that shifts consumer selection toward perceived value rather than brand loyalty. This behavioral shift is most visible in coastal states where pet insurance penetration exceeds national baselines.
Veterinary Biologics Market Segmentation
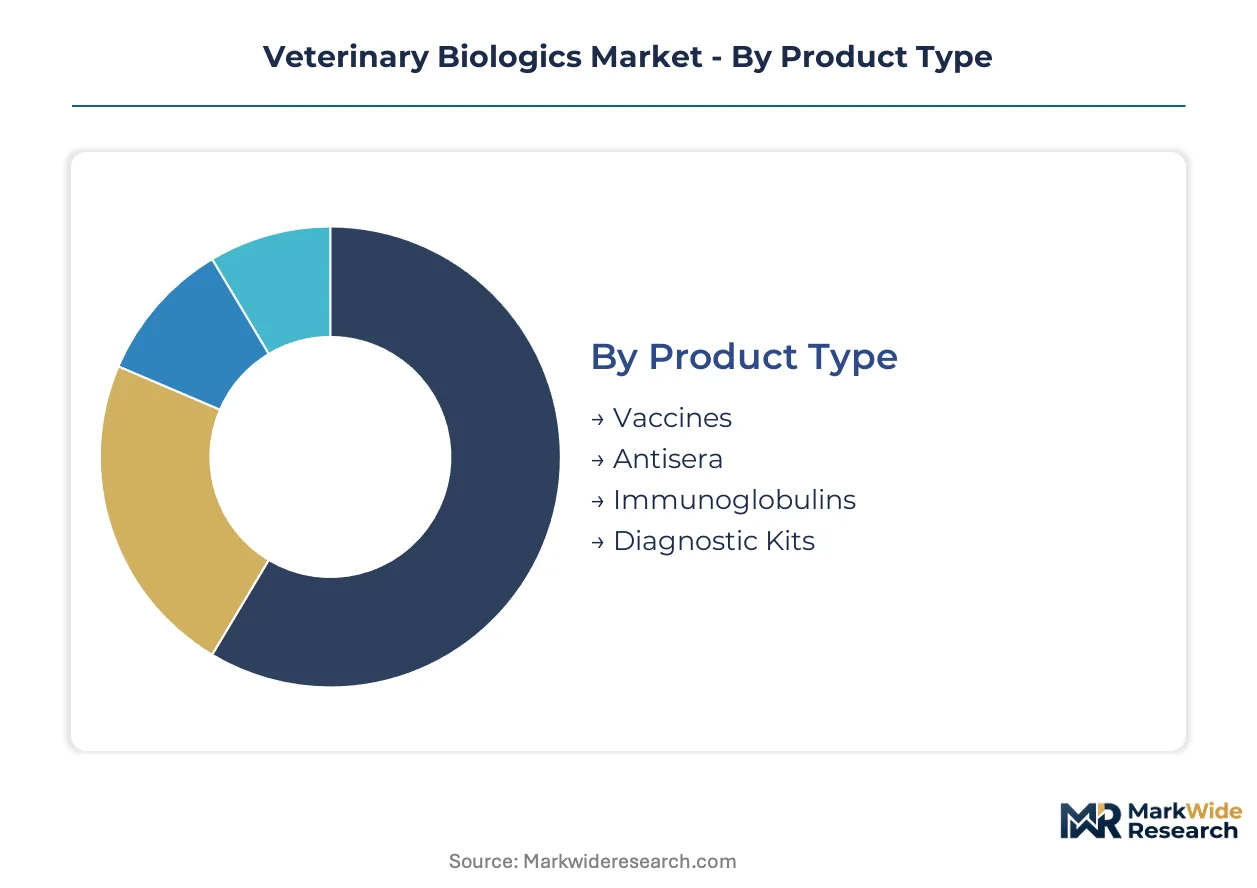
Segmentation in veterinary biologics reveals divergent margin structures and regulatory intensities across product categories. Manufacturers calibrate R&D portfolios and commercial deployment based on animal type economics and channel access constraints.
Product Type:
Upgrade cycles in this category are compressing as platform technologies displace legacy manufacturing methods and recombinant products accelerate replacement of egg-derived stocks.
- Vaccines:Attenuated and inactivated viral formulations with specified titers dominate procurement volumes through recurring revaccination schedules. Demand concentrates in United States specialty hospital chains where consolidated purchasing power is restructuring supplier negotiations around direct-account terms.
- Diagnostic Kits:Rapid serology and PCR testing platforms enable point-of-care workflows displacing centralized laboratory processing. Expansion concentrates in metropolitan United States markets where pet insurance penetration drives transparent pricing for preventive care bundles.
- Antisera:Polyclonal antibody preparations derived from hyperimmunized animals provide passive immunity in acute toxin exposures.
- Immunoglobulins:Recombinant and plasma-derived immunoglobulin products manufactured through cell culture propagation address immunodeficiency conditions.
Volume placements concentrate in Vaccines; the faster expansion belongs to Diagnostic Kits.
Animal Type:
Cost tier differentiation separates commodity livestock biologics from premium companion animal products where pricing power reflects owner willingness to pay.
- Cattle:Respiratory and clostridial vaccines for feedlot and dairy operations constitute the largest volume segment by animal headcount. Demand flows through veterinary distributors serving the US Midwest where large integrated operations negotiate volume-based procurement contracts.
- Dogs:Core immunization protocols against distemper, parvovirus, and rabies generate recurring revenue streams in companion animal practice. Concentration is visible in California and Texas specialty clinic chains unbundling vaccines from wellness examinations.
- Cats:Feline viral rhinotracheitis and calicivirus vaccines follow similar scheduling patterns with lower per-dose pricing than canine equivalents.
- Poultry:Hatchery-administered Marek's disease and Newcastle disease vaccines face intense margin pressure from generic inactivated alternatives.
Cattle absorbs the highest absolute volumes; Dogs captures the steepest margin expansion trajectory.
Application:
Application patterns track the shift from reactive treatment toward scheduled preventive protocols in developed veterinary markets.
- Preventive Care:Scheduled immunization programs and wellness screening protocols create recurring patient touchpoints. United States coastal states with elevated pet insurance penetration are embedding biologics into subscription-based care packages.
- Diagnosis:Serological surveillance and pathogen detection support treatment decisions and epidemiological monitoring. Point-of-care adoption is displacing reference laboratory workflows in Florida metropolitan clinic networks.
- Treatment:Therapeutic antisera and immunoglobulin administration addresses established disease conditions with episodic purchasing patterns.
- Research:Custom biologics production for academic and pharmaceutical studies operates on contract manufacturing terms with specialized regulatory handling.
Preventive Care commands the dominant share; Diagnosis is climbing the fastest.
Distribution Channel:
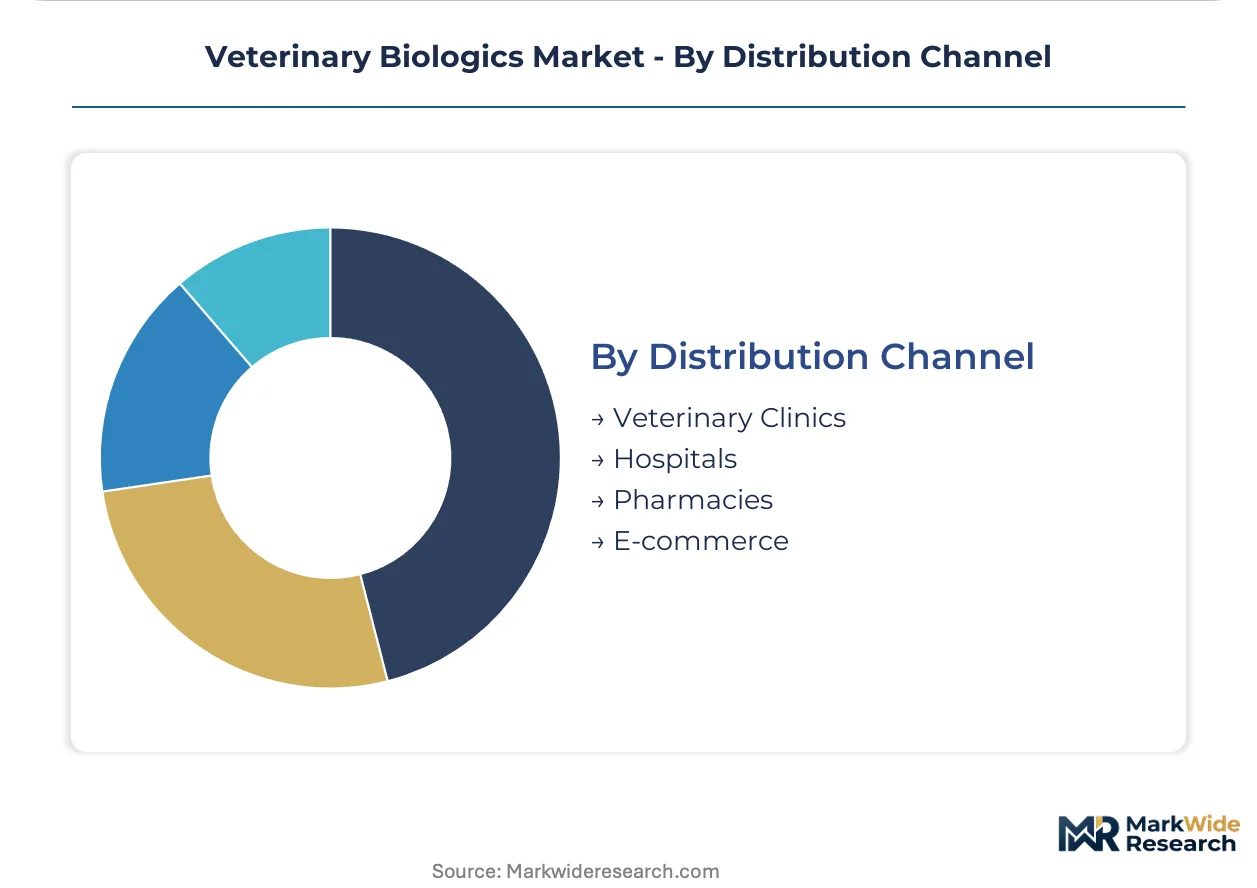
Channel configuration reflects consolidation pressure as buyer concentration forces restructuring of traditional wholesale relationships.
- Veterinary Clinics:Primary care and specialty practices represent the dominant dispensing point for companion animal biologics. Texas and California clinic chains are negotiating exclusive supply agreements bypassing traditional distribution.
- Hospitals:Emergency and referral centers handle complex cases requiring immediate biologics access with premium pricing tolerance.
- Pharmacies:Human pharmacy chains with veterinary divisions are capturing prescription diet and biologic adjacencies in suburban markets.
- E-commerce:Direct-to-consumer platforms face USDA-CVB and state veterinary practice act restrictions on prescription biologics sales.
Veterinary Clinics retain the volume concentration; E-commerce faces regulatory headwinds limiting expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in developed pharmaceutical clusters while consumption patterns diverge between livestock-dominant and companion animal-heavy markets. The United States absorbs the largest absolute value, though production gravity pulls toward European biologics hubs and emerging Asian vaccine centers.
United States
Specialty veterinary hospital chains in Texas and California are consolidating procurement power through direct-account negotiations with manufacturers. USDA-CVB pathway acceleration for novel recombinant vaccines compresses development timelines versus European counterparts. The Research Triangle Park in North Carolina anchors cell-culture platform R&D investment from major animal health manufacturers.
Germany
Livestock vaccine demand from intensive dairy and pork operations in Lower Saxony and Bavaria sustains volume throughput for inactivated viral formulations. EMA batch-release requirements under EU Veterinary Medicines Regulation impose divergent stability-testing standards versus USDA-CVB, fragmenting regulatory economics. The Rhine-Main cluster around Frankfurt houses centralized distribution infrastructure serving Central European veterinary markets.
China
Poultry vaccine consumption dominates absolute volumes as industrial-scale layer and broiler operations expand in Shandong and Guangdong provinces. NMPA oversight of veterinary immunological products mandates local clinical trials for imported biologics, extending market access timelines. The Yangtze River Delta biopharma corridor is absorbing investment in cell-culture manufacturing capacity to reduce egg-based production dependency.
Brazil
Cattle respiratory vaccine demand from feedlot operations in Mato Grosso and São Paulo states generates recurring procurement cycles for clostridial and viral formulations. ANVISA regulatory harmonization with USDA-CVB standards remains incomplete, creating dual dossier requirements for multinational portfolios. The São Paulo metropolitan cluster concentrates veterinary distributor networks serving South American export markets.
India
Foot-and-mouth disease control programs drive public-sector vaccine procurement from dairy cooperatives in Gujarat and Maharashtra. CDSCO regulation of veterinary biologics operates alongside state-level livestock department tendering, fragmenting commercial access channels. The Hyderabad-Visakhapatnam pharmaceutical corridor is emerging as a contract manufacturing hub for recombinant animal vaccines targeting export markets.
Veterinary Biologics Market Competitive Environment
Top-tier vendors anchor consolidated vaccine and diagnostic portfolios, while mid-scale specialists occupy niche antisera and regional livestock segments. The competitive structure reflects heavy R&D intensity in recombinant platform technologies alongside persistent price competition in generic inactivated vaccines. Three archetypes dominate: vertically integrated pharmaceutical conglomerates with human-animal health synergies; pure-play animal health companies with geographic specialization; and emerging market manufacturers competing on cost-position in bulk livestock biologics. Capacity expansion in cell-culture platforms and strategic partnerships for mRNA technology licensing represent the dominant competitive moves reshaping positioning.
Among the integrated pharmaceutical conglomerates, Zoetis Inc. and Merck Animal Health occupy positions exemplifying the human-animal health synergy archetype, leveraging regulatory infrastructure and manufacturing scale across species boundaries. Boehringer Ingelheim Animal Health represents the geographic specialization vector with established European livestock market presence. These three entities anchor the premium-tier competitive set, though their specific strategic postures vary by regional market access and platform technology deployment.
| Leading Market Players |
|---|
| Elanco Animal Health |
| Virbac SA |
| Zoetis Inc. |
| Phibro Animal Health Corporation |
| IDEXX Laboratories Inc. |
| Merck Animal Health |
| Ceva Sante Animale |
| Hester Biosciences Limited |
| Boehringer Ingelheim Animal Health |
| Others |
Value Chain & Pricing Dynamics
Specialty veterinary hospital chain consolidation in Texas and California is forcing manufacturers toward direct-account contracting, compressing distributor margins and restructuring how suppliers recover logistics costs through tiered service offerings.
Pricing Analysis
Short lead-time premiums for temperature-sensitive live attenuated vaccines command pricing separation from standard inventory cycles, with emergency replenishment for rural clinics attracting markups over scheduled distributor deliveries. Three-tier pricing structure across premium, standard, and economy levels reflects cold-chain validation depth, USDA-CVB batch-release priority, and volume commitment scale. Cost compression in generic inactivated livestock vaccines is intensifying because Brazilian and Indian manufacturers are flooding export markets with undifferentiated clostridial formulations. Cattle and poultry operations demonstrate highest price sensitivity, while companion animal specialty hospitals absorb premium positioning for recombinant platforms.
Supply Chain Analysis
Workforce availability constraints in North Carolina's Research Triangle Park and Germany's Rhine-Main biopharma corridor are elevating labor costs for cell-culture platform specialists against egg-based production regions. Manufacturing gravity centers on United States, Germany, and China, with embryonated chicken egg supply chains drawing from Midwest poultry operations and Shandong province layer farms. Single-source vulnerability pervades SPF egg supply for viral seed stock propagation, with avian influenza outbreaks capable of halting titer production across multiple vaccine lines simultaneously. Distribution runs through veterinary distributor networks serving integrated livestock operations, with direct contracting displacing wholesale relationships in consolidated metropolitan clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary biologics is consolidating around platform technology ownership, with regulatory infrastructure investments and cell-culture manufacturing scale forcing sub-scale egg-dependent manufacturers toward exit or acquisition.
For Market Incumbents: Anchor market position through captive supply of cell-culture manufacturing capacity in North Carolina and Rhine-Main clusters, insulating against avian influenza disruptions that threaten egg-based competitors. Deepen backward integration into diagnostic kit production, capturing subscription-based preventive care bundles that embed biologics purchasing into recurring revenue streams and raise switching costs for consolidated clinic chains. For New Entrants and Emerging Players: Capture white-space opportunity in point-of-care diagnostic kits for metropolitan United States markets where pet insurance penetration enables transparent pricing acceptance. Target Brazil and India livestock vaccine tenders with cost-optimized recombinant platforms, bypassing entrenched European and North American incumbents in price-sensitive generic segments through local manufacturing partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with cell-culture platform specialists given USDA-CVB pathway acceleration for recombinant products and EMA environmental risk assessment divergence that fragments regulatory economics. Long-term viability over the next decade favors manufacturers with dual-qualified submission capabilities spanning USDA-CVB and EMA standards. Monitor convergence signals on recombinant classification harmonization as inflection indicator for multinational portfolio value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Culture Platform Migration | Suspension bioreactor investment reduces avian influenza exposure and accelerates pandemic response scale-up. |
| Direct Hospital Contracting | Exclusive supply agreements with Texas and California specialty chains bypass distributor margin extraction. |
| mRNA Technology Licensing | Human pharmaceutical manufacturing expertise transfer compresses veterinary vaccine development timelines. |
| Diagnostic Kit Integration | Point-of-care PCR and serology platforms displace centralized laboratory workflows in metropolitan clinics. |
| Dual Regulatory Qualification | USDA-CVB and EMA submission capability captures harmonization benefits and fragments competitor access. |
Study Parameters
USDA-CVB licensure databases, EMA veterinary product registers, and SEC 10-K filings from publicly traded animal health manufacturers formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with regulatory affairs directors at major biologics manufacturers, procurement managers at consolidated veterinary hospital chains, and distribution channel heads supplemented secondary validation. Bottom-up and top-down triangulation cross-checked manufacturer-reported segment revenues against distributor shipment data and clinic-level purchasing patterns.
Bottom-up modeling aggregated individual product-line projections across vaccines, diagnostic kits, antisera, and immunoglobulins, while top-down analysis calibrated aggregate market expansion against macroeconomic indicators and livestock population trends. Segmentation dimensions spanned product type, animal species, application purpose, and distribution channel structure. CAGRs were derived from regression analysis of historical volume trends and forward elasticity assumptions regarding preventive care adoption and platform technology substitution rates. Forecast inputs incorporated USDA-CVB pathway timeline compression and EMA environmental risk assessment implementation effects.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to avian influenza disruption frequency, regulatory harmonization progress between USDA-CVB and EMA standards, and specialty veterinary chain consolidation pace. Forecasts reflect assumptions regarding cell-culture platform cost parity achievement and companion animal insurance penetration trajectories. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Veterinary Wellness Market
Veterinary Medicine
Over-The-Counter (OTC) Veterinary Drugs Market
Veterinary Medicine
US Veterinarians Market
Veterinary Medicine
Global Newcastle Disease Vaccine Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
Veterinary Anesthesia Machines Market
Veterinary Medicine
United States Veterinary Healthcare Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Veterinary Palliative Care Management Market
Veterinary Medicine
Global Veterinary Eye Care Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Middle East Veterinary Vaccines Market
Veterinary Medicine
Veterinary Skin Care Products Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
South Africa Veterinary Medicine Market