
 Oral Vaccines Market | 2026-2036
Oral Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Vaccines Market Outlook
WHO prequalification standards for thermostable oral vaccines is shifting procurement criteria toward formulations that withstand ambient temperature distribution. Sanofi leverages its established rotavirus oral vaccine infrastructure to sustain manufacturing scale across tropical markets. GSK anchors European regulatory credibility through EMA-aligned development pathways for enteric-coated oral formulations. Serum Institute of India dominates high-volume supply contracts for national immunization programs in South Asia and Africa.
Oral vaccines are biologically active immunological preparations administered through the gastrointestinal tract, typically formulated as enteric-coated tablets, buffered liquids, or lyophilized granules designed to withstand gastric acid degradation and release antigen in the small intestine to induce mucosal IgA and systemic IgG responses. Their primary purpose is to elicit protective immunity without needle-based administration, eliminating sharps waste and enabling mass vaccination in resource-limited settings. Live attenuated products occupy the largest revenue pool due to established rotavirus and polio franchises, while subunit formats represent the fastest-expanding category as recombinant cholera and norovirus candidates advance through Phase III. Delivery mode segmentation shows oral liquids retaining dominance in pediatric campaigns, though tablet formulations are gaining traction in adult travel vaccination where patient compliance and shelf stability command premium positioning.
FDA's Vaccines and Related Biological Products Advisory Committee shapes U.S. approval standards for oral immunogenicity endpoints, while India's CDSCO and Central Drugs Laboratory at Kasauli enforce batch-release protocols for oral polio and rotavirus supplies distributed through the Universal Immunization Programme. WHO prequalification functions as the gatekeeper for GAVI-eligible procurement, effectively determining which oral vaccine manufacturers access pooled demand from low-income countries. Stakeholders must monitor how evolving mucosal immunity correlates of protection redefine regulatory acceptance criteria for novel oral candidates against enteric pathogens.
Market Dynamics
WHO prequalification protocols for thermostable formulations are redirecting R&D investment away from cold-chain-dependent platforms, compressing development timelines for ambient-stable oral vaccines while elevating manufacturing barriers for legacy suppliers.
Growth Catalysts
- Pediatric immunization expansion:National pulse polio campaigns in India and expanding universal immunization coverage across South Asia are generating procurement volumes that justify dedicated oral vaccine production lines.
- EMA-aligned development pathways:European regulatory credibility for enteric-coated oral formulations accelerates cross-recognition agreements, reducing duplicate clinical trial requirements for multinational sponsors.
- Mucosal IgA response targeting:Recombinant subunit platforms against cholera and norovirus are advancing through Phase III, opening therapeutic categories previously dominated by injectable formats.
Market Restraints
- Lyophilization capacity concentration:Contract manufacturing for thermostable granule formats clusters among a limited supplier base in Western Europe, creating single-source vulnerability for tropical-market distribution.
- Gastric acid degradation barriers:Enteric-coating technology requires specialized polymer inputs with volatile pricing, compressing margin structures for buffered liquid alternatives.
- CDSCO batch-release friction:India's Central Drugs Laboratory at Kasauli enforces extended testing protocols for oral polio and rotavirus supplies, elongating time-to-market for new entrants.
Strategic Opportunities
- Adult travel vaccination tablets:Patient compliance and shelf stability requirements in European and North American markets command premium positioning for solid-dose formats against typhoid and cholera.
- GAVI-eligible procurement pools:WHO prequalification functions as the gatekeeper for pooled demand from low-income countries, creating volume guarantees for qualified suppliers.
- Lyophilized granule distribution innovation:Ambient-temperature-stable formats enable direct-to-community health worker channels, bypassing clinic-based cold-chain infrastructure in rural Africa.
Industry Challenges
- Mucosal immunity correlates of protection:Evolving scientific consensus on IgA threshold standards creates regulatory uncertainty for novel candidates against enteric pathogens, complicating endpoint design.
- Formulation scientist scarcity:Specialized expertise in enteric-coating polymer selection and gastric transit modeling concentrates within a limited talent pool, inflating compensation costs for development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Vaccines Market |
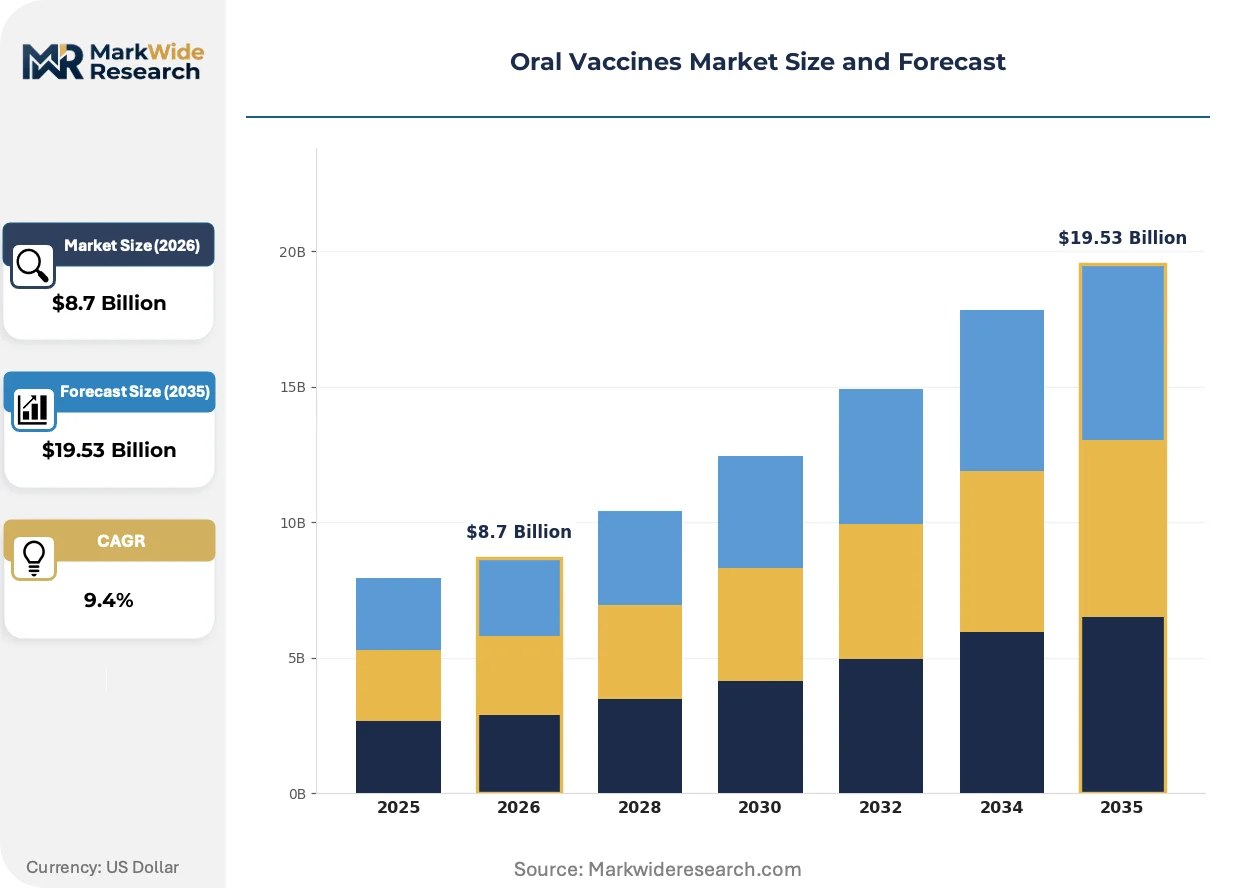
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, DNA, Subunit Delivery Mode: Oral Tablets, Oral Liquids, Granules, Powders End User: Children, Adults, Elderly, Immunocompromised Application: Travel Vaccination, Routine Immunization, Outbreak Management, Animal Health |
| Companies Covered | Sanofi, GSK, Takeda Pharmaceuticals, Merck, Serum Institute of India, Soligenix, Oravax Medical, Prokarium Ltd, Liquidia Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Vaccines Market Strategic Shifts
Bioprocess engineering advances are compressing the cost curve for recombinant subunit production, while regulatory science around mucosal immunity endpoints is rewriting approval standards for novel oral candidates.
Plant-based expression systems for recombinant cholera antigens are electrifying upstream manufacturing economics. Vaccine developers in India and Brazil are adopting Nicotiana benthamiana platforms at pilot scale, reducing capital intensity for antigen production. This technology is electrifying competitive positioning for emerging market suppliers previously excluded from subunit vaccine value chains.
REACH regulation amendments on pharmaceutical polymer classifications are tightening supply chain documentation for enteric-coating excipients. European formulators must now submit extended safety dossiers for methacrylate-based coatings, adding 12-18 months to qualification timelines. Oral tablet developers targeting EMA approval are responding by accelerating validation of alternative cellulose-based coating systems.
Demand from national immunization programs is consolidating procurement around long-term supply agreements with performance-linked pricing. UNICEF and GAVI are displacing spot-market purchasing for oral rotavirus and polio vaccines, favoring manufacturers with demonstrated thermostability data. This pattern is most visible in India's Universal Immunization Programme, where five-year framework contracts now cover over 80 percent of oral vaccine volumes.
Oral Vaccines Market Segmentation
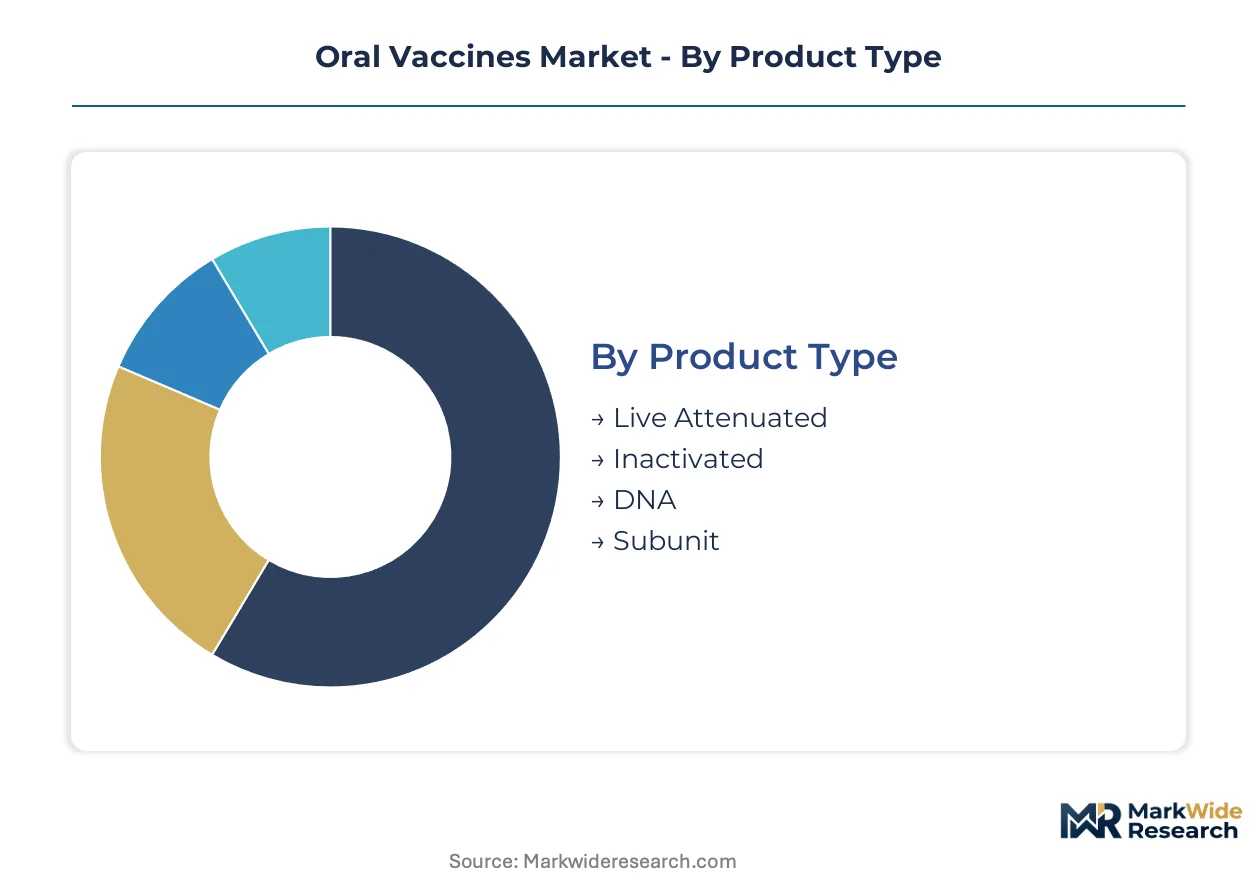
Oral vaccine segmentation reveals how formulation choices determine distribution reach and patient access. Product architecture, delivery format, target population, and clinical use case each create distinct procurement channels and manufacturing requirements.
Product Type:
Standalone live attenuated platforms operate independently of adjuvant systems, while DNA and subunit formats embed into recombinant expression infrastructure.
- Live Attenuated:These formulations contain weakened pathogenic organisms that replicate transiently in the gut mucosa to stimulate robust cellular and humoral immunity. Demand concentrates in India's Universal Immunization Programme, where rotavirus and oral polio campaigns require billions of doses annually with established cold-chain tolerance.
- Subunit:Purified antigen preparations eliminate replication risk and enable precise immune targeting against specific epitopes. Recombinant cholera and norovirus candidates advancing through Phase III trials are redirecting R&D investment toward ambient-stable formulations that bypass lyophilization bottlenecks.
- Inactivated:Heat-killed whole-cell preparations offer safety profiles suitable for immunocompromised populations where live vaccines pose contraindications.
- DNA:Plasmid-based platforms encoding pathogen antigens enable rapid pandemic response through sequence adaptation rather than strain cultivation.
Live attenuated products lead volumes today; subunit formats are gaining share fastest.
Delivery Mode:
Cost tiering separates premium solid-dose formats from economy liquid presentations, with granule systems occupying a mid-tier position on stability-per-dollar metrics.
- Oral Liquids:Buffered suspensions of live attenuated viruses dominate pediatric mass vaccination campaigns due to ease of administration by minimally trained health workers. National pulse polio programs in India and Nigeria specify liquid presentations for door-to-door delivery, though gastric acid degradation limits shelf life without cold-chain maintenance.
- Oral Tablets:Enteric-coated solid doses withstand ambient temperature distribution and enable self-administration by adult travelers. European and North American markets command premium positioning for typhoid and cholera tablets where patient compliance and pharmacy shelf stability justify higher procurement costs.
- Granules:Lyophilized multiparticulate formats dissolve in water for flexible dosing across age groups.
- Powders:Sachet-based presentations reduce shipping weight for remote distribution but require reconstitution at point of use.
Oral liquids lead volumes today; tablets are gaining share fastest.
End User:
Application context distinguishes routine programmatic delivery from discretionary adult purchase, with immunocompromised populations requiring specialized safety profiles.
- Children:Pediatric immunization programs generate the largest procurement volumes through government tenders linked to GAVI eligibility and WHO prequalification. India's expanding universal immunization coverage and birth cohort scale create concentrated demand for rotavirus and polio oral formulations.
- Adults:Travel vaccination markets in Europe and North America favor tablet formats for typhoid and cholera protection, with procurement occurring through private pharmacies and occupational health services rather than national programs.
- Elderly:Aging immune systems require higher antigen doses or adjuvanted formulations to achieve protective titers.
- Immunocompromised:Inactivated or subunit platforms eliminate replication risk in HIV-positive and transplant recipient populations.
Children lead volumes today; adults are gaining share fastest.
Application:
Customer type segmentation separates institutional programmatic purchasing from individual discretionary acquisition, with outbreak response creating surge demand patterns distinct from steady-state immunization.
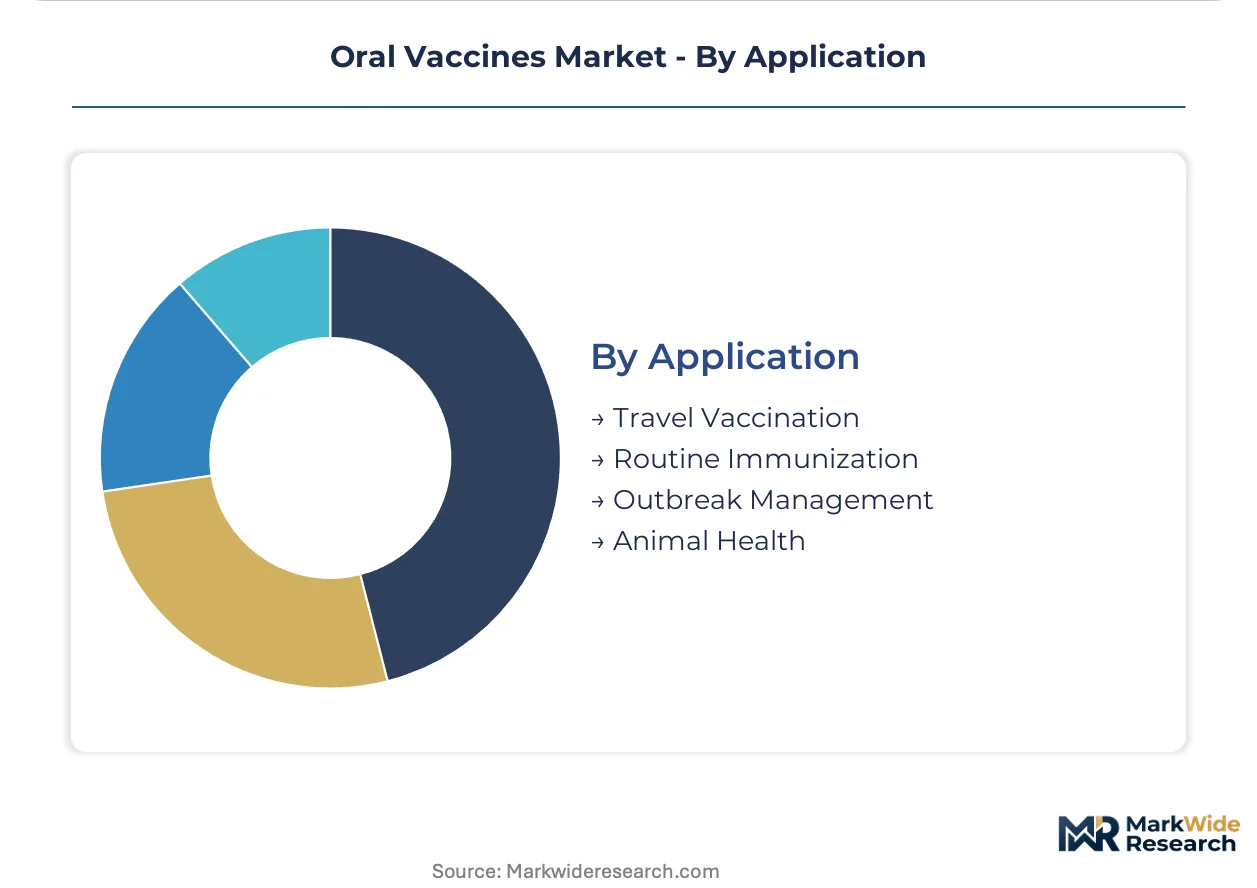
- Routine Immunization:Scheduled pediatric dosing through national programs establishes predictable demand curves and multi-year supply agreements. UNICEF and GAVI procurement pools favor manufacturers with demonstrated thermostability data and WHO prequalification status.
- Travel Vaccination:Pre-departure prophylaxis for tourists, business travelers, and military personnel commands premium pricing in European and North American markets. Patient compliance requirements favor tablet stability over liquid cold-chain dependence.
- Outbreak Management:Emergency cholera and typhoid response creates surge procurement through WHO stockpiles and bilateral government agreements.
- Animal Health:Veterinary oral vaccines for livestock enteric pathogens operate through separate regulatory pathways and distribution channels.
Routine immunization leads volumes today; travel vaccination is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oral vaccine development traces its commercial lineage to mid-20th century polio eradication campaigns that established mass-distribution infrastructure in tropical climates. Manufacturing scale subsequently concentrated in jurisdictions with demonstrated cold-chain-to-ambient formulation capabilities.
United States
FDA's Vaccines and Related Biological Products Advisory Committee sets immunogenicity endpoint standards that shape global clinical trial design. The agency's emphasis on mucosal IgA correlates of protection influences regulatory acceptance criteria for novel enteric-coated candidates. Research clusters in Massachusetts and Maryland anchor bioprocess engineering advances for recombinant subunit platforms.
India
CDSCO and the Central Drugs Laboratory at Kasauli enforce batch-release protocols for oral polio and rotavirus supplies distributed through the Universal Immunization Programme. National pulse polio campaigns generate procurement volumes exceeding billions of doses annually. Manufacturing concentrates in Pune and Hyderabad, where Serum Institute of India operates dedicated production lines for GAVI-eligible supply contracts.
United Kingdom
EMA-aligned development pathways for enteric-coated oral formulations accelerate cross-recognition agreements across European markets. MHRA post-Brexit regulatory autonomy maintains convergence with EMA standards while preserving distinct national authorization procedures. London-based vaccine developers leverage proximity to European clinical trial networks for Phase III mucosal immunity studies.
Brazil
ANVISA oversees registration of thermostable oral vaccines for national immunization program inclusion. The country's universal health system creates predictable demand curves for rotavirus and cholera oral formulations. Research initiatives in São Paulo and Rio de Janeiro pilot Nicotiana benthamiana expression systems for recombinant antigen production at reduced capital intensity.
Switzerland
Swissmedic maintains stringent stability documentation requirements for oral vaccine shelf-life claims, particularly for travel vaccination tablets distributed through European pharmacy channels. Basel and Geneva host formulation science expertise in enteric-coating polymer selection and gastric transit modeling. Swiss manufacturers supply specialized excipients to global tablet developers targeting ambient-temperature distribution.
Oral Vaccines Market Competitive Environment
Premium-margin players sit above commodity-margin players across thermostability certification tiers, with WHO prequalification status functioning as the primary sorting mechanism. The vendor base stratifies between established live-attenuated franchise holders and emerging recombinant subunit specialists. Three archetypes dominate: multinational pharmaceutical conglomerates with rotavirus infrastructure, emerging market scale manufacturers serving national immunization programs, and platform-technology developers advancing novel delivery formats. Competitive moves center on thermostability data generation for prequalification submission and long-term supply agreement negotiation with UNICEF procurement pools.
Among multinational developers, Sanofi and GSK occupy positions as archetypal established franchise holders with demonstrated tropical-market distribution capabilities. Serum Institute of India represents the emerging market scale manufacturer archetype, anchoring high-volume supply relationships with South Asian and African national programs. These three entities exemplify how regulatory credibility and manufacturing scale combine to secure multi-year framework contracts covering the majority of oral vaccine procurement volumes.
| Leading Market Players |
|---|
| Sanofi |
| GSK |
| Takeda Pharmaceuticals |
| Merck |
| Serum Institute of India |
| Soligenix |
| Oravax Medical |
| Prokarium Ltd |
| Liquidia Technologies |
| Others |
Value Chain & Pricing Dynamics
Lyophilization technology transitions from cold-chain-dependent platforms to ambient-stable formulations simultaneously compress manufacturing cost curves and concentrate production capabilities among WHO-prequalified suppliers in India and Western Europe. This dual effect reshapes procurement economics for national immunization programs while elevating barriers for legacy manufacturers lacking thermostability certification.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates WHO-prequalified thermostable tablets for European travel markets from liquid presentations for Indian pediatric campaigns and unqualified economy alternatives. Price differentiation rests on certification grade and volume scale, with EMA-aligned developers commanding premiums against CDSCO-registered suppliers. Cost compression in liquid formats intensifies as Serum Institute of India scales dedicated production lines for GAVI-eligible procurement. Government tenders for routine immunization exhibit highest price sensitivity; private pharmacy channels for adult travel vaccination demonstrate lowest.
Supply Chain Analysis
WHO prequalification status functions as the dominant supply gate, filtering access to UNICEF procurement pools and GAVI volume guarantees. Manufacturing concentrates in India, Switzerland, and the United Kingdom, with Pune and Hyderabad anchoring live-attenuated production and Basel supplying specialized enteric-coating excipients. Raw material dependencies center on methacrylate and cellulose-based polymers for tablet coatings, plus attenuated viral strains from designated seed banks. Single-source vulnerability characterizes lyophilization capacity for thermostable granules. Distribution runs through direct-to-government channels for programmatic delivery and pharmacy networks for private travel markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through successive regulatory milestones, with WHO thermostability prequalification functioning as the primary demand amplifier for GAVI-eligible procurement pools.
For Market Incumbents: Extend thermostability data packages toward ambient-stable tablet formats, capturing premium positioning in European travel markets while defending rotavirus liquid franchises against recombinant subunit challengers. Deepen backward integration into enteric-coating polymer supply through Swiss excipient partnerships, insulating margin structures from REACH regulation volatility. Prioritize long-term framework contract renewal with India's Universal Immunization Programme ahead of subunit platform maturation. For New Entrants and Emerging Players: Capture white-space in adult travel vaccination tablets for typhoid and cholera, where patient compliance requirements and pharmacy shelf stability command pricing premiums unavailable in pediatric liquid markets. Target Brazilian and Southeast Asian manufacturing partnerships to bypass Western European lyophilization bottlenecks. Pursue plant-based expression systems for recombinant antigen production as the primary go-to-market angle, reducing capital intensity against incumbent bioreactor infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among emerging market scale manufacturers with CDSCO registration but pending WHO prequalification, offering asymmetric upside upon thermostability certification completion. Five-to-ten year viability favors suppliers with demonstrated tropical-market distribution and GAVI contract history over platform-technology developers lacking manufacturing scale. Watch mucosal IgA correlate-of-protection standardization as the signal to monitor for regulatory acceptance inflection.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Submission | Thermostability data packages unlock UNICEF procurement pools and GAVI volume guarantees. |
| EMA-Aligned Development Pathway | Cross-recognition agreements reduce duplicate clinical trials for European market entry. |
| Lyophilization Capacity Expansion | Ambient-stable granule production bypasses cold-chain infrastructure limitations in rural Africa. |
| Plant-Based Expression System Adoption | Nicotiana benthamiana platforms reduce upstream capital intensity for recombinant subunit manufacturing. |
| Long-Term Supply Agreement Negotiation | Five-year framework contracts with India's Universal Immunization Programme secure predictable demand curves. |
Study Parameters
Multiple input streams — regulatory filing analysis, manufacturing facility assessments, and procurement database tracking — were reconciled through structured interviews with vaccine development executives, regulatory affairs leads at CDSCO and EMA, UNICEF procurement officers, and hospital pharmacy directors. Secondary validation drew from WHO prequalification listings, ClinicalTrials.gov Phase III trial records, EMA scientific advice documents, and GAVI supply agreement disclosures. Bottom-up demand modeling across patient populations and administration routes was cross-checked against top-down market sizing from manufacturer capacity declarations.
Historical volume trajectories from national immunization program procurement were cross-referenced against expert panel assessments of pipeline progression timelines. Segmentation modeling spanned product type, delivery mode, end user, and application across the analysis window, with regional regulatory clusters treated as distinct demand environments. CAGRs were derived from curve-fitting approaches calibrated to policy-driven procurement acceleration in India and thermostability-driven format substitution in European travel markets. Forecast inputs incorporated CDSCO batch-release protocol durations and REACH polymer reclassification qualification timelines.
Regulatory timeline delays, thermostability data generation failures, and GAVI funding allocation shifts are the dominant revision risks to modeled outcomes. Deviation in WHO prequalification queue processing speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Australia Pharmaceuticals Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Peptic Ulcer Drugs Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Global Lifestyle Drugs Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Global Combination Vaccine Market