
 Europe Veterinary Antibiotics Market | 2026-2036
Europe Veterinary Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Veterinary Antibiotics Market Intelligence
European pharmaceutical manufacturing is pivoting toward consolidated antibiotic production hubs in Germany and France to secure API supply chains for veterinary formulations. Zoetis leverages its vertically integrated European manufacturing network to sustain consistent supply of penicillin-based therapies across livestock-dense regions. Boehringer Ingelheim GmbH anchors its competitive position through specialized R&D facilities focused on macrolide derivatives for cattle respiratory diseases. Virbac competes aggressively in Mediterranean markets with targeted oral formulations for small ruminants.
Europe veterinary antibiotics comprise chemotherapeutic agents administered to food-producing and companion animals for bacterial infection treatment, disease prevention, and growth promotion cessation compliance, with active pharmaceutical ingredients typically synthesized through fermentation-based or semi-synthetic processes meeting EMA purity specifications. Tetracyclines retain dominant volume share in livestock applications where broad-spectrum coverage against respiratory and enteric pathogens remains clinically essential. Injectable delivery modes command premium positioning in emergency veterinary interventions and large-animal hospital settings across Northern Europe. Companion animal segments demonstrate fastest structural expansion as pet insurance penetration and specialist clinic density accelerate in France, the UK, and Scandinavia.
EMA's veterinary medicine regulation framework, coupled with EU Green Deal antimicrobial resistance reduction targets and national farm antibiotic stewardship mandates, progressively restricts prophylactic usage while elevating prescription documentation requirements. REACH compliance and F-Gas Regulation downstream effects additionally constrain solvent selection and manufacturing emissions for API producers operating within EU member states. Stakeholders must monitor evolving MDR spillover into veterinary device-drug combinations and prepare for anticipated conditional reimbursement shifts in livestock insurance schemes tied to antimicrobial usage benchmarking.
Market Dynamics
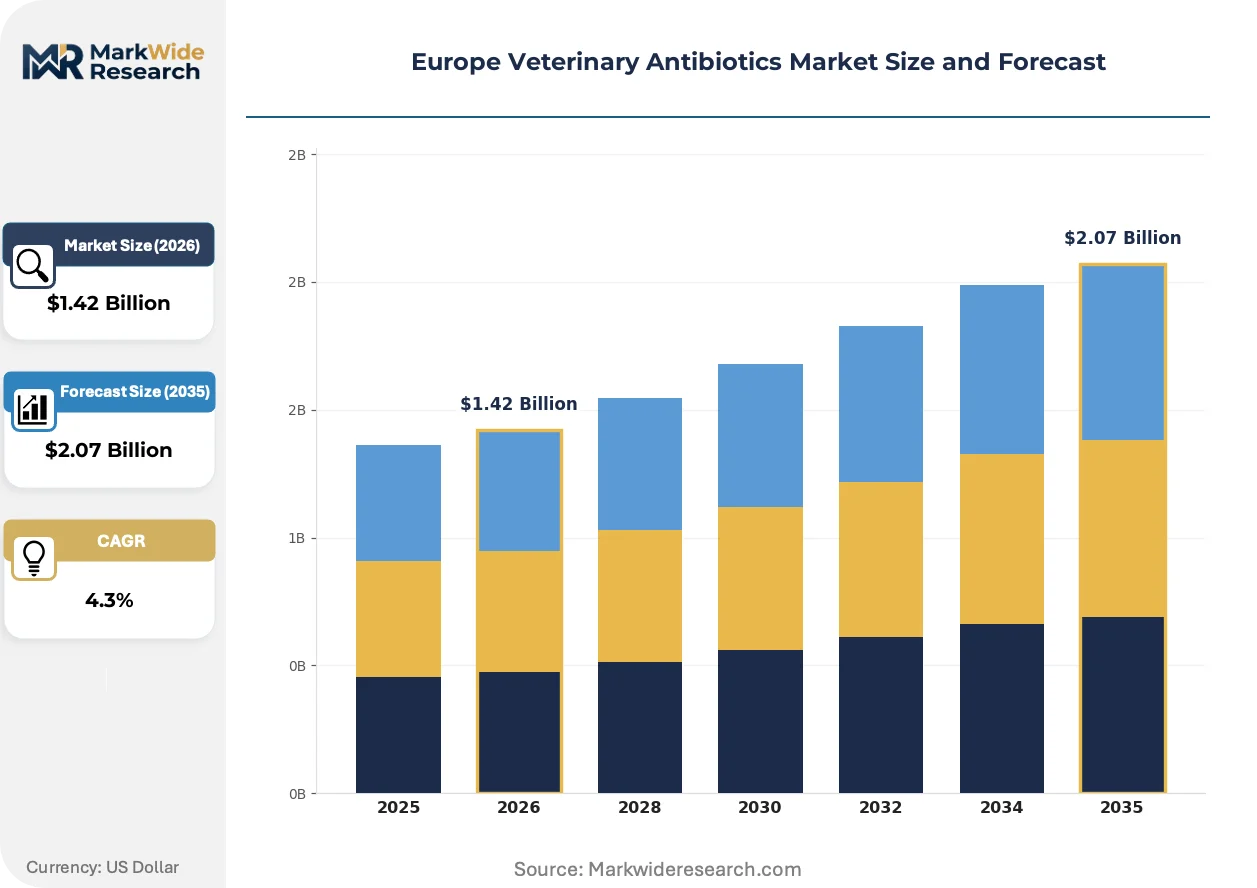
EMA's veterinary medicine regulation framework is compressing prophylactic antibiotic usage across European livestock operations while elevating prescription documentation requirements. This regulatory pressure is reshaping procurement patterns and forcing manufacturers toward narrower-spectrum therapeutic development.
Growth Catalysts
- EU Green Deal antimicrobial targets:National farm stewardship mandates in Germany and France are accelerating demand for diagnostic-guided therapy selection and herd health compliance services.
- Companion animal clinic expansion:Pet insurance penetration in Scandinavia and the UK is driving specialist veterinary visits and premium narrow-spectrum prescriptions.
- Fermentation-based API manufacturing:Consolidated production hubs in Germany and France are securing domestic supply chains for tetracycline and penicillin active ingredients.
Market Restraints
- REACH compliance costs:Solvent selection constraints and manufacturing emissions limits are elevating production costs for API producers operating within EU member states.
- API supply concentration:Dependence on consolidated fermentation facilities in Germany and France creates vulnerability to single-site production disruptions.
- Diagnostic infrastructure gaps:Limited on-farm rapid pathogen identification in Southern European livestock operations delays targeted therapy adoption.
Strategic Opportunities
- Portuguese and Greek livestock sectors:Underpenetrated antimicrobial stewardship programs in these Mediterranean markets offer first-mover positioning for compliance service providers.
- Oral formulation innovation:Palatability-optimized delivery systems for small ruminants address unmet needs in Spanish and Italian hillside farming operations.
- MDR spillover preparation:Anticipated conditional reimbursement shifts in livestock insurance schemes tied to antimicrobial usage benchmarking will reward early data infrastructure investment.
Industry Challenges
- Veterinary pharmacovigilance expertise:Shortages of qualified professionals capable of managing EMA adverse event reporting and periodic safety update documentation are extending compliance timelines.
- Device-drug combination integration:Complexity of aligning veterinary antibiotic formulations with emerging diagnostic hardware platforms is delaying integrated product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Veterinary Antibiotics Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.07 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Penicillins, Tetracyclines, Macrolides, Sulfonamides Delivery Mode: Injectable, Oral, Topical, Implants End User: Farmers, Veterinary Clinics, Research Institutions, Animal Hospitals Animal Type: Livestock, Companion Animals, Aquaculture, Equine |
| Companies Covered | Zoetis, Boehringer Ingelheim GmbH, Merck & Co., Inc., Elanco, Ceva, Vetoquinol S.A., Virbac, Calier, Bimeda, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Veterinary Antibiotics Market Strategic Shifts & Innovations
European veterinary antibiotic markets are experiencing active transformation across manufacturing technology, regulatory compliance architecture, and distribution channel structure. These shifts are compressing legacy business models while opening differentiated positioning pathways.
Long-acting injectable formulations are overtaking conventional oral administration in Northern European cattle operations. These depot-release systems reduce handling frequency and improve compliance with restricted-use protocols. Dairy cooperatives in the Netherlands and Denmark are adopting them rapidly, compressing demand for daily-dose oral products.
REACH and F-Gas Regulation downstream effects are constraining solvent selection and manufacturing emissions for API producers. Fermentation facilities must retrofit purification processes or relocate outside EU jurisdiction. German and French manufacturing hubs are absorbing these capital requirements to maintain EMA purity certification access.
Specialist clinic procurement consolidation is reshaping distribution economics in France and the UK. Large veterinary group practices are centralizing antibiotic purchasing through dedicated procurement functions, displacing traditional wholesaler relationships. This concentration is most visible in companion animal segments where insurance-backed payment flows enable volume commitment structures.
Europe Veterinary Antibiotics Market Segmentation
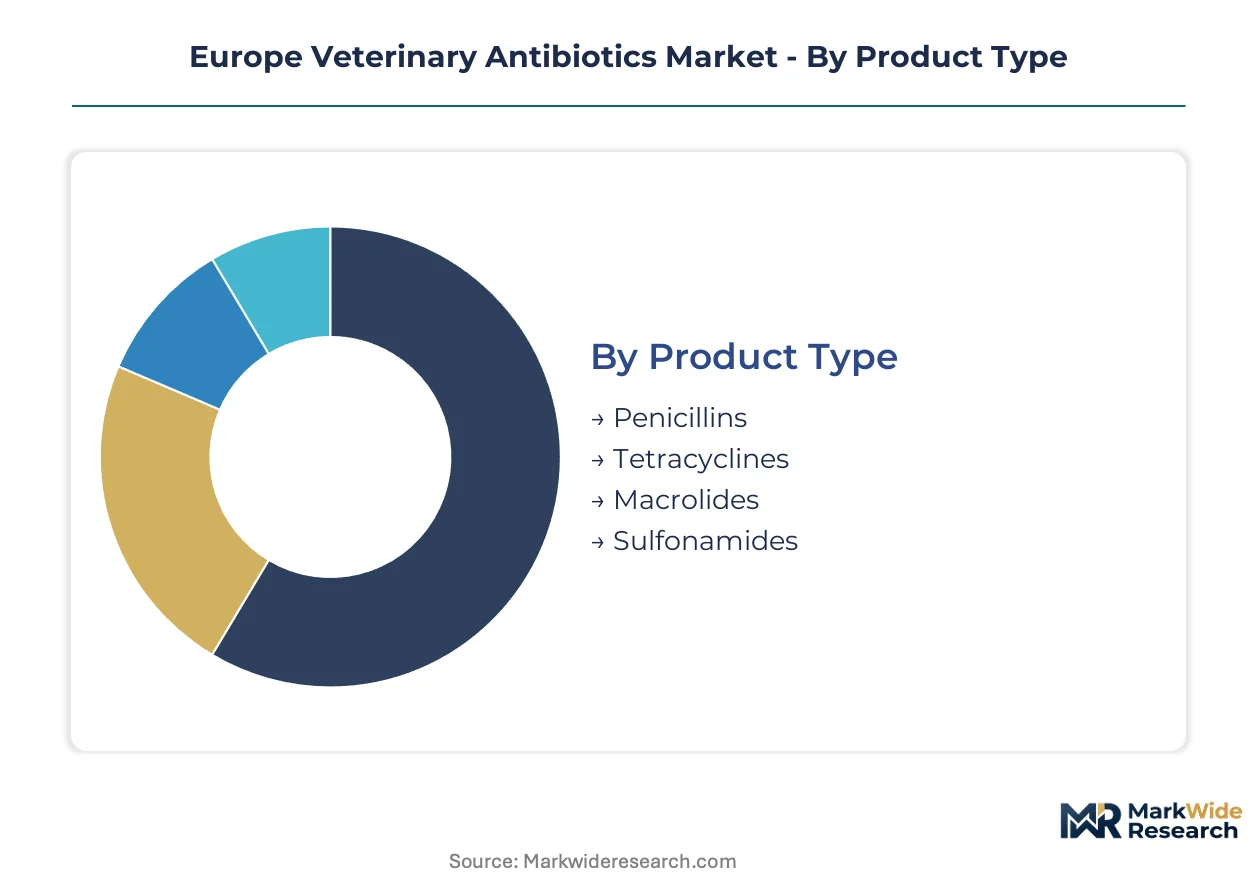
Antibiotic procurement patterns across Europe diverge sharply by therapeutic class, delivery format, and animal category, with EMA stewardship mandates forcing targeted portfolio rebalancing. Manufacturers must align formulation development with species-specific regulatory pathways and end-user compliance capabilities.
Product Type:
Upgrade cycles for antibiotic portfolios accelerate as livestock producers replace broad-spectrum legacy products with EMA-compliant narrow-spectrum alternatives.
- Tetracyclines:Fermentation-derived broad-spectrum agents retain foundational status in cattle respiratory and enteric protocols across Germany and France. Dairy cooperatives in the Netherlands specify chlortetracycline premixes for metaphylaxis programs under veterinary prescription mandates.
- Penicillins:Beta-lactam derivatives dominate companion animal clinics in Spain and Italy where narrow-spectrum gram-positive coverage aligns with diagnostic-guided therapy adoption. Injectable procaine penicillin formulations command premium positioning in equine hospital settings.
- Macrolides:Semi-synthetic derivatives target Mycoplasma bovis and Pasteurella multocida in intensive beef operations.
- Sulfonamides:Potentiated combinations persist in small ruminant applications where cost sensitivity constrains therapeutic selection.
Volume placements concentrate in Tetracyclines; the faster expansion belongs to Penicillins.
Delivery Mode:
Cost tier differentiation separates emergency intervention formats from maintenance protocols, with handling labor economics driving format selection.
- Injectable:Long-acting depot formulations reduce cattle handling frequency in Danish and Dutch dairy systems. These products carry 40-60% price premiums over oral equivalents but lower total labor costs and improve compliance documentation.
- Oral:Water-soluble powders and medicated premixes dominate pig and poultry operations in Poland and Romania where automated delivery systems enable mass medication protocols. Palatability-optimized pastes address small ruminant compliance challenges in Mediterranean hillside farming.
- Topical:Ophthalmic and dermatological preparations serve companion animal dermatology clinics in France and the UK.
- Implants:Subcutaneous slow-release devices target feedlot cattle in Irish and Spanish beef finishing operations.
Procurement volumes favor Oral formats; Injectable modes are gaining share fastest in Northern European cattle sectors.
End User:
Customer type determines prescription authority, documentation requirements, and reimbursement pathways across national veterinary frameworks.
- Veterinary Clinics:Companion animal specialists in Scandinavia and the UK drive narrow-spectrum penicillin demand through insurance-backed diagnostic workflows. These practices centralize antibiotic purchasing through group procurement functions, displacing traditional distribution relationships.
- Farmers:Livestock producers in Germany and France operate under mandatory veterinary prescription requirements with antimicrobial usage benchmarking. On-farm stock-keeping is restricted to emergency supplies with full treatment documentation.
- Animal Hospitals:University-affiliated referral centers in Belgium and the Netherlands manage complex multidrug-resistant infections requiring culture-guided therapy selection.
- Research Institutions:Veterinary schools and pharmaceutical research facilities in Italy and Spain conduct pharmacokinetic studies for novel formulation development.
Transaction volumes cluster with Farmers; Veterinary Clinics are expanding most quickly on a value-per-prescription basis.
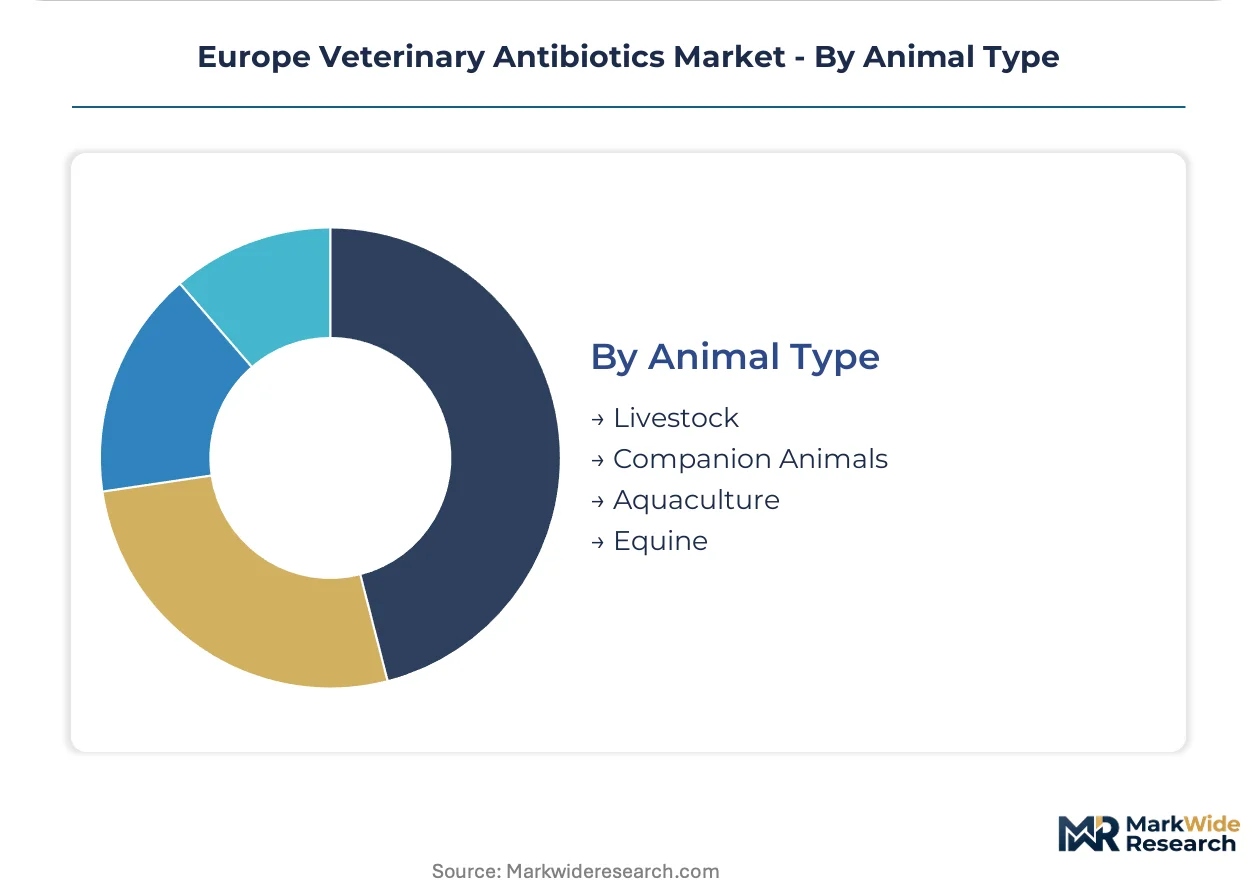
Animal Type:
Species-specific regulatory calendars and production economics create divergent growth trajectories across therapeutic applications.
- Livestock:Cattle, swine, and poultry operations in Germany, France, and the Netherlands absorb the majority of tetracycline and macrolide volumes. EMA's phased reduction targets for prophylactic usage are compressing growth promotion applications while elevating therapeutic treatment documentation.
- Companion Animals:Dogs and cats in French, UK, and Scandinavian households generate premium narrow-spectrum demand through specialist clinic networks. Pet insurance penetration above 40% in Sweden and Norway enables diagnostic-guided prescribing without cost-driven therapeutic compromise.
- Equine:Racing and sport horse populations in Ireland, the UK, and Germany require respiratory and limb infection protocols with strict withdrawal period management.
- Aquaculture:Salmon and trout farms in Norway and Scotland operate under residue monitoring programs with limited antibiotic authorization.
Livestock maintains volume dominance; Companion Animals show the steepest expansion trajectory on value metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-based API production concentrates in Germany's Rhineland and France's Alsace corridor, anchoring supply security for veterinary formulations across the continent.
Germany
Livestock cooperatives in Lower Saxony and Bavaria drive tetracycline demand through herd health compliance programs. EMA's veterinary medicine regulation mandates prescription documentation for all metaphylaxis applications. The Baden-Württemberg manufacturing cluster hosts fermentation facilities producing penicillin and macrolide active ingredients under REACH emissions constraints.
France
Companion animal clinics in Paris and Lyon generate premium narrow-spectrum penicillin prescriptions through insurance-backed diagnostic workflows. EU Green Deal antimicrobial targets compress prophylactic usage in dairy operations across Brittany and Normandy. The Grand Est region anchors semi-synthetic macrolide production for cattle respiratory therapies.
Netherlands
Dairy cooperatives in Friesland and Gelderland adopt long-acting injectable formulations to reduce handling frequency and improve compliance documentation. National farm antibiotic stewardship mandates benchmark antimicrobial usage against EU reduction targets. The Utrecht veterinary research corridor advances pharmacokinetic studies for novel depot-release systems.
Spain
Hillside farming operations in Castile-La Mancha and Andalusia require palatability-optimized oral formulations for small ruminant compliance. EMA guidelines elevate prescription authority requirements for livestock producers across Extremadura. The Barcelona pharmaceutical corridor distributes narrow-spectrum therapies to Mediterranean companion animal markets.
United Kingdom
Specialist veterinary group practices in London and Southeast England centralize antibiotic procurement through dedicated purchasing functions. Pet insurance penetration above 35% enables diagnostic-guided prescribing without cost-driven therapeutic compromise. The Cambridge-Norwich corridor hosts R&D facilities focused on culture-guided therapy selection for multidrug-resistant infections.
Europe Veterinary Antibiotics Market Key Industry Players
Global majors compete with regional champions across formulation development and distribution reach. Market structure consolidates around vertically integrated pharmaceutical conglomerates with captive API supply, while mid-tier specialists occupy niche species segments. Three archetypes dominate: fermentation-integrated conglomerates, companion animal-focused specialists, and generic oral formulation suppliers. Capacity expansion in German and French manufacturing hubs and strategic partnerships with diagnostic platform developers represent the primary competitive vectors.
Among US-based pharmaceutical conglomerates, Zoetis and Elanco occupy positions exemplifying vertical integration from active ingredient production through veterinary clinic distribution. Boehringer Ingelheim GmbH anchors the German manufacturing archetype with Rhineland-based fermentation capacity serving livestock-dense Northern European markets. Virbac represents the Mediterranean-focused specialist model, with formulation development targeting small ruminant and companion animal applications across Spain and Italy.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim GmbH |
| Merck & Co., Inc. |
| Elanco |
| Ceva |
| Vetoquinol S.A. |
| Virbac |
| Calier |
| Bimeda, Inc. |
| Others |
Cost & Logistics Intelligence
Dutch dairy cooperatives and French companion animal clinic networks concentrate procurement volumes, anchoring a contract-based pricing structure where long-term offtake agreements with German and French API manufacturers secure supply stability against spot-market volatility. This buyer-side consolidation elevates negotiating leverage for volume-tiered discounts while compressing margins for generic oral formulation suppliers serving fragmented Southern European livestock operations.
Pricing Analysis
Service-bundling separates prescription documentation support and diagnostic-guided therapy consulting from base product pricing, with EMA compliance advisory now unbundled as a premium add-on. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—REACH-compliant German-manufactured APIs command tier-one positioning, while Eastern European-sourced alternatives occupy economy tiers. Pricing pressure stems from REACH solvent substitution costs elevating production economics, with Polish and Romanian pig farmers exhibiting highest price sensitivity due to automated mass-medication scale requirements.
Supply Chain Analysis
Workforce-availability constraints in Germany's Rhineland and France's Alsace corridor fermentation facilities are elevating automation capital requirements for API purification processes. Active pharmaceutical ingredient production concentrates in Germany, France, and India, with European hubs drawing from Chinese and Indian raw fermentation feedstock sources. Single-source vulnerability pervades tetracycline precursor supply, where regulatory restriction on F-gas solvents has compressed domestic purification capacity. Distribution runs through specialized veterinary pharmaceutical wholesalers in Northern Europe and direct clinic group procurement functions in France and the UK.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European veterinary antibiotics markets are consolidating around backward integration races, with fermentation capacity ownership and captive API supply emerging as the decisive competitive moat against regulatory compliance cost escalation.
For Market Incumbents: Cement dominance by acquiring Portuguese and Greek distribution networks ahead of antimicrobial stewardship program mandates, while expanding Baden-Württemberg fermentation capacity to absorb REACH-driven competitor exit. Threat of generic oral formulation commoditization from Eastern European suppliers demands accelerated narrow-spectrum R&D investment in macrolide derivatives. For New Entrants and Emerging Players: The premium-economy price-point gap in companion animal narrow-spectrum penicillins offers white-space entry through palatability-optimized oral pastes targeting Spanish hillside farming and Italian small ruminant operations. Underpenetrated diagnostic infrastructure in Southern European livestock sectors enables veterinary clinic partnership models bundling rapid pathogen identification with targeted therapy protocols. For Investors and Strategic Acquirers: The window for entry favors mid-tier fermentation-integrated specialists with EMA certification infrastructure already deployed. Long-term viability hinges on conditional livestock insurance reimbursement shifts rewarding antimicrobial usage benchmarking data infrastructure. Watch for MDR spillover into veterinary device-drug combination regulatory complexity as inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive API supply secures margin protection against REACH solvent cost escalation in German manufacturing hubs. |
| EMA Compliance Service Bundling | Prescription documentation advisory creates differentiated positioning against generic competitors in Dutch dairy procurement. |
| Diagnostic Platform Partnership | Culture-guided therapy integration addresses multidrug-resistant infection complexity in Belgian university referral centers. |
| Palatability-Optimized Formulation Development | Small ruminant oral paste innovation penetrates underserved Mediterranean hillside farming segments in Castile-La Mancha. |
| Group Procurement Function Penetration | Direct contracting with UK specialist clinic networks displaces traditional wholesaler relationships in insurance-backed companion animal segments. |
Research Approach
Multi-period observation of antimicrobial usage benchmarking trends and EMA regulatory filing patterns anchored the trend analysis, supplemented by interviews with veterinary pharmaceutical manufacturing executives, regulatory affairs specialists, livestock cooperative procurement managers, and companion animal clinic group purchasing directors. Secondary validation drew from EMA veterinary medicine submissions, EU Green Deal implementation progress reports, national farm stewardship mandate documentation, and REACH compliance disclosure filings. Bottom-up volume modeling across therapeutic class, delivery mode, and animal category segments was triangulated against top-down API production capacity assessments from German and French fermentation facility records.
Segment-weighting approaches applied differential growth assumptions across livestock and companion animal end-use categories, with therapeutic class splits calibrated to veterinary prescription audit data from France, Germany, and the UK. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory phase-in schedules and EU antimicrobial reduction target compliance curves. Formulation development pipeline tracking and diagnostic infrastructure deployment rates in Southern European markets provided industry-specific forecast inputs throughout the projection horizon.
Inputs from EMA adverse event reporting databases and national veterinary prescription registries were available through the study window; gaps in on-farm rapid diagnostic adoption rates in Portuguese and Greek livestock operations introduce uncertainty bands around Southern European therapy selection modeling. Forecasts incorporate assumptions regarding conditional insurance reimbursement policy evolution and MDR regulatory spillover timing. Material deviation in EU Green Deal enforcement stringency or REACH solvent substitution cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Pet DNA Testing Market
Veterinary
Otc Pet Medication Market
Veterinary
Mastitis Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Veterinary Vaccines Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Veterinary Tables Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Veterinary Thermography Market
Veterinary
Pet Cremation Market
Veterinary
Animal Microchip Implant Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market