
 Otc Pet Medication Market | 2026-2036
Otc Pet Medication Market Size, Share, and Industry Trends Forecast 2026-2036
Otc Pet Medication Market Analytics
FDA's evolving OTC monograph framework for animal drugs is decoupling product registration timelines from traditional new animal drug application pathways, lowering cost-of-entry for established manufacturers. Zoetis leverages its vertically integrated manufacturing footprint to sustain shelf-stable formulation advantages across mass retail channels. Boehringer Ingelheim anchors its competitive position through prescription-to-OTC switch capabilities in the antiparasitic category. PetIQ competes aggressively on price-point accessibility through its owned-and-operated veterinary clinics and retail partnerships.
Over-the-counter pet medication encompasses non-prescription pharmaceutical and nutritional formulations administered by pet owners without veterinary supervision, typically containing active ingredients such as fipronil, pyrantel pamoate, or glucosamine hydrochloride at concentrations below prescription thresholds, manufactured through standard tableting, liquid fill, or topical solution processes. These products serve primary commercial purposes in parasite prevention, symptomatic pain management, and dietary supplementation for companion animals. Antiparasitic formulations occupy the largest margin pool given their recurring purchase cycles and seasonal demand spikes, while chewable tablet formulations lead volume due to palatability engineering and dosing convenience. Pain relief applications represent the fastest-growing structural segment as aging pet demographics drive joint care purchasing among dog owners.
USDA's Animal and Plant Health Inspection Service coordinates with FDA's Center for Veterinary Medicine to establish residue tolerance thresholds and manufacturing facility standards that shape product liability exposure and interstate commerce eligibility. The EPA additionally regulates topical antiparasitics under FIFRA, creating dual-agency compliance requirements that filter out undercapitalized entrants. Stakeholders must monitor pending legislative proposals around veterinary telehealth prescribing authority, as relaxed remote diagnosis rules could either expand OTC adjacencies or conversely reclassify certain SKUs back to prescription status.
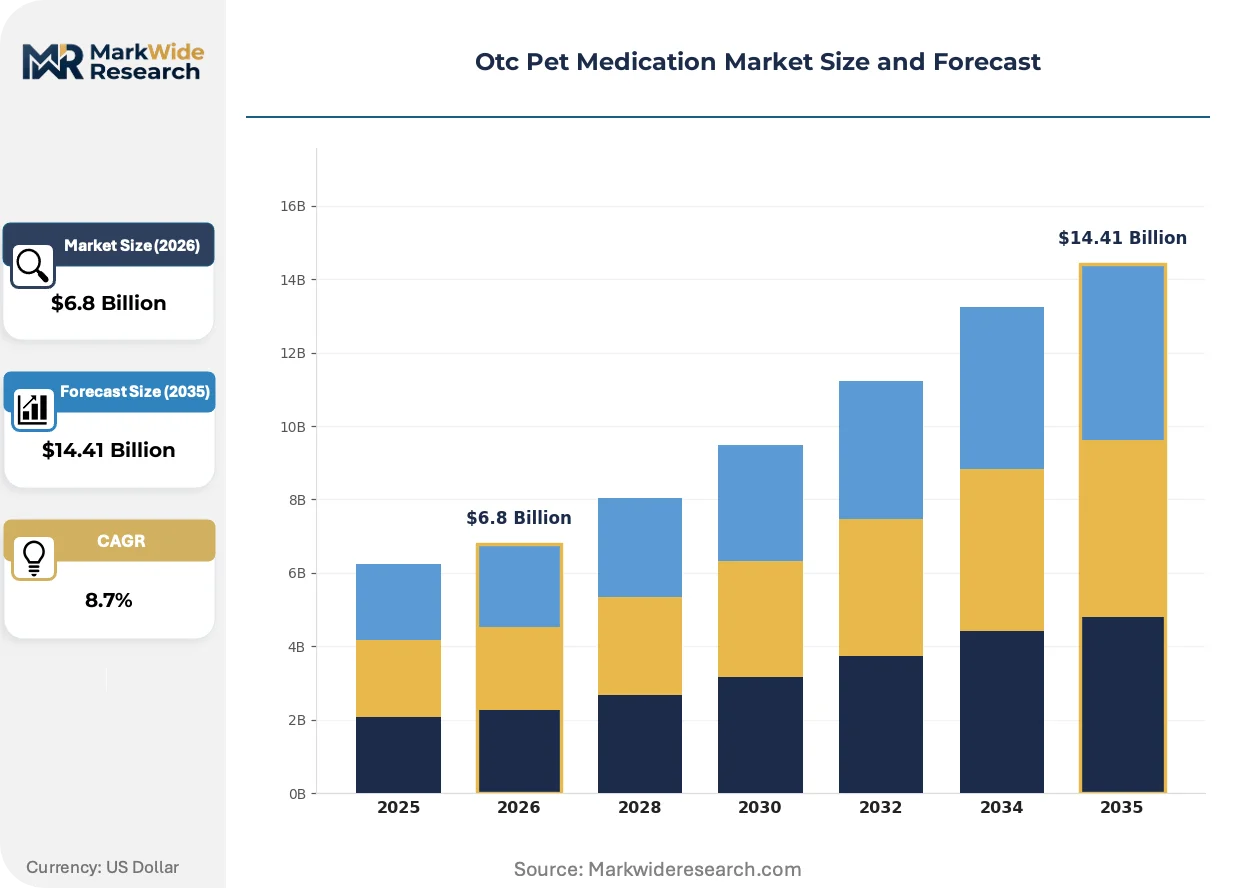
Market Dynamics
The FDA's evolving OTC monograph framework for animal drugs is decoupling product registration from traditional new animal drug application pathways, compressing time-to-market for established manufacturers while raising compliance barriers for undercapitalized entrants.
Growth Catalysts
- Suburban household expansion:Self-administration trends accelerate as pet owners in suburban ZIP codes seek convenience-driven parasite prevention without veterinary visits.
- FDA OTC monograph evolution:Streamlined classification pathways reduce regulatory friction for antiparasitic and joint care formulations.
- Aging pet demographics:Extended lifespans among companion animals expand recurring demand for chronic pain management and dietary supplementation products.
Market Restraints
- Dual-agency compliance burden:EPA FIFRA jurisdiction over topical antiparasitics creates parallel registration requirements with FDA Center for Veterinary Medicine, doubling filing costs.
- Active ingredient concentration ceilings:Prescription thresholds for fipronil and pyrantel pamoate limit efficacy differentiation in OTC parasite control.
- Seasonal demand volatility:Tick and flea seasonality concentrates revenue in Q2-Q3, straining working capital for mass retail channel partners.
Strategic Opportunities
- Veterinary telehealth adjacencies:Relaxed remote diagnosis rules in select states could expand OTC product bundling with digital consultation platforms.
- Chewable palatability engineering:Convergence of pharmaceutical tableting and pet food flavor masking technologies enables premium positioning for compliance-challenged owners.
- Direct-to-consumer pharmacy platforms:Subscription-based auto-ship models bypass traditional veterinary clinic gatekeepers in the United States.
Industry Challenges
- Formulation stability expertise:Shelf-stable topical solutions require specialized excipient chemistry talent scarce outside legacy animal health manufacturers.
- Residue testing protocols:USDA-APHIS tolerance verification creates bottlenecks for new entrants lacking established manufacturing facility standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Otc Pet Medication Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiparasitic, Pain Relief, Vitamins, Antihistamines End User: Pet Owners, Veterinary Clinics, Animal Shelters, Pet Supply Stores Application: Flea Control, Allergy Treatment, Joint Care, Nutritional Support Formulation: Chewable Tablets, Liquid Solutions, Topical Treatments, Powders |
| Companies Covered | Zoetis, Merck Animal Health, Boehringer Ingelheim, Elanco Animal Health, Ceva Sante Animale, Dechra, Virbac, Bayer AG, PetIQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Otc Pet Medication Market Evolving Landscape
Formulation science and regulatory pathway innovation are compressing development cycles while reshaping how pet owners access non-prescription animal health products.
Palatability engineering is integrating pharmaceutical-grade active ingredients with flavor masking systems derived from human food science. Suburban dog owners with aging pets adopt these chewable formats at accelerating rates. This convergence is integrating chronic medication administration into daily feeding routines, reducing abandonment rates for joint care regimens.
EPA's evolving FIFRA registration requirements for topical antiparasitics are tightening environmental fate data submissions. Manufacturers must now demonstrate aquatic toxicity profiles for wash-off scenarios. Small-format topical solutions face the steepest compliance cost escalation, favoring scaled producers with dedicated ecotoxicology capabilities.
Subscription-based replenishment is displacing episodic retail purchasing for recurring parasite prevention. Millennial pet owners in metropolitan United States markets favor auto-ship platforms that synchronize delivery with seasonal risk windows. This behavioral shift concentrates buyer relationships with integrated pharmacy-veterinary clinic networks rather than mass merchandisers.
Otc Pet Medication Market Segmentation
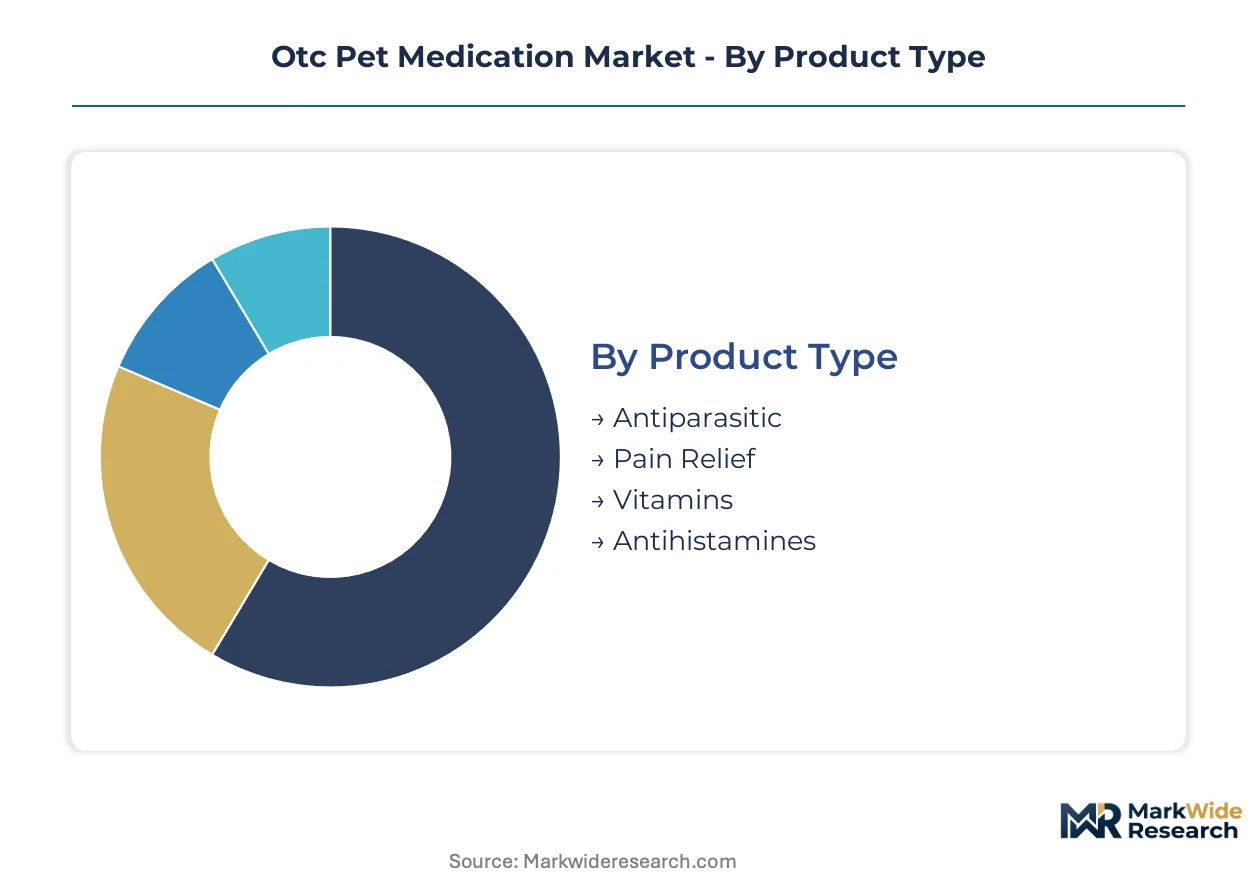
Segmentation in the OTC pet medication market reflects divergent purchasing behaviors across buyer sophistication levels, formulation preferences, and care contexts. Understanding these divisions enables manufacturers to align product development with specific compliance challenges and channel economics.
Product Type:
Margin profiles and purchase frequency separate therapeutic categories in this market.
- Antiparasitic:Formulations containing fipronil, permethrin, or pyriproxyfen target ectoparasite prevention through topical spot-on or collar delivery systems. Recurring seasonal purchase cycles in suburban United States households generate predictable revenue streams, though EPA FIFRA registration requirements concentrate production among scaled manufacturers with dedicated ecotoxicology capabilities.
- Pain Relief:NSAID and nutraceutical combinations address osteoarthritis and post-surgical discomfort in aging companion animals. Demand concentrates among dog owners in metropolitan United States markets where extended pet lifespans drive chronic regimen adherence, with chewable palatability engineering reducing abandonment rates.
- Vitamins:Dietary supplementation addresses nutritional gaps in homemade or specialized diets.
- Antihistamines:Diphenhydramine and chlorpheniramine formulations manage allergic dermatitis and environmental sensitivities.
Volume sits with Antiparasitic; growth tilts toward Pain Relief.
End User:
Channel control and veterinary relationship intensity define purchasing authority across buyer types.
- Pet Owners:Direct consumers in suburban ZIP codes self-administer parasite prevention and chronic pain management without clinical supervision. FDA OTC monograph eligibility enables pharmacy chain and direct-to-consumer platform access, with subscription auto-ship models displacing episodic retail purchasing among millennial demographics.
- Veterinary Clinics:Clinical gatekeepers dispense OTC-adjacent products through in-house retail or affiliated pharmacy networks. United States-based integrated chains leverage prescription-to-OTC switch capabilities to capture margin on antiparasitic refills.
- Animal Shelters:High-volume institutional buyers prioritize cost efficiency in population-scale parasite control.
- Pet Supply Stores:Mass retail channels depend on seasonal merchandising and promotional calendar alignment.
Revenue concentrates with Pet Owners; clinic channel expansion offers the steepest trajectory.
Application:
Clinical indication severity and regimen duration shape product positioning requirements.
- Flea Control:Seasonal prophylaxis dominates household expenditure on companion animal health. Tick and flea seasonality in temperate United States climates concentrates revenue in Q2-Q3, straining working capital for mass retail partners while sustaining subscription platform retention.
- Joint Care:Chronic osteoarthritis management requires sustained glucosamine and chondroitin administration. Aging pet demographics in United States suburban markets drive recurring demand, with palatability-engineered chewables integrating into daily feeding routines.
- Allergy Treatment:Environmental and food sensitivity management addresses episodic symptomatic relief.
- Nutritional Support:Supplemental feeding addresses life-stage and condition-specific dietary requirements.
Transaction frequency peaks with Flea Control; lifetime value accumulates in Joint Care.
Formulation:
Administration compliance and manufacturing complexity create tiered competitive barriers.
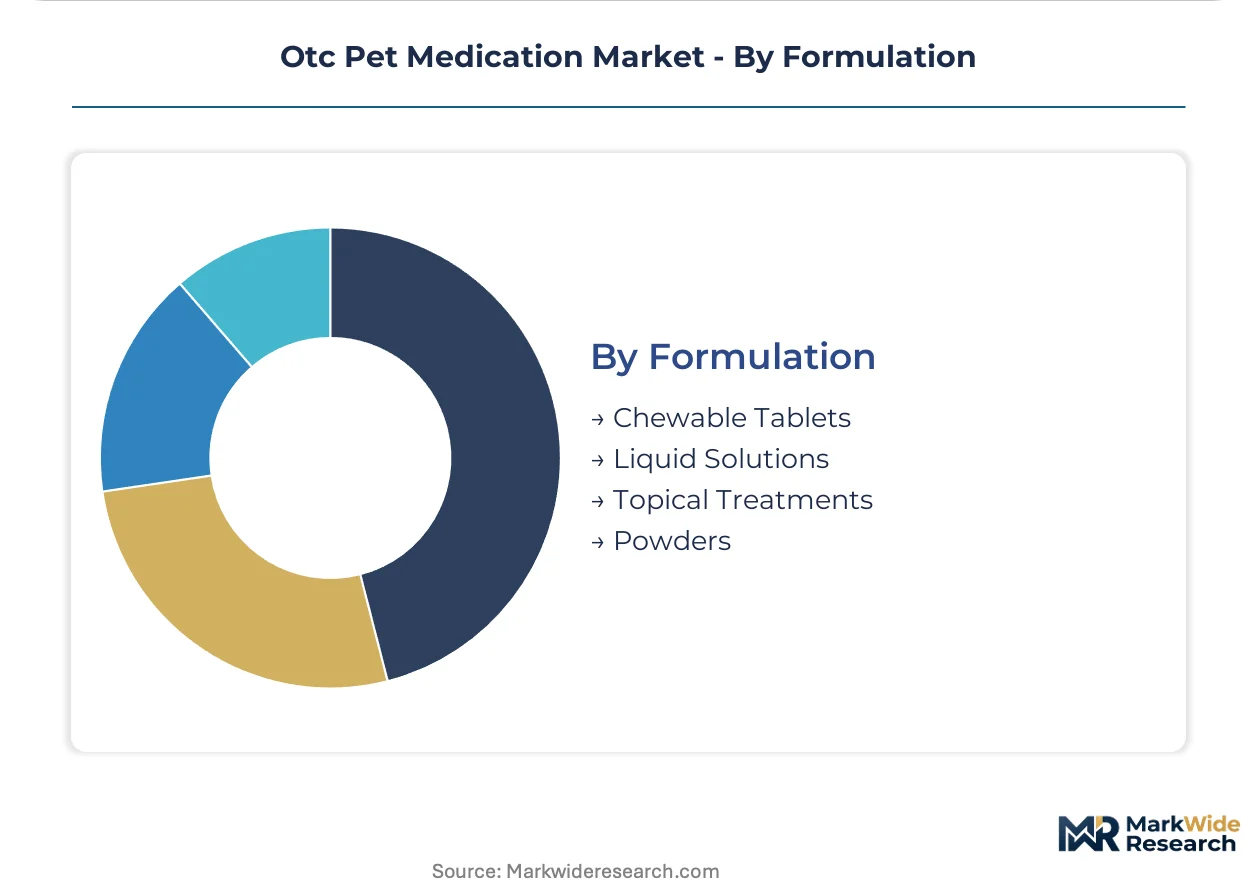
- Chewable Tablets:Pharmaceutical tableting converges with pet food flavor masking to embed active ingredients in palatable matrices. Suburban dog owners with compliance-challenged pets adopt these formats at accelerating rates, reducing regimen abandonment.
- Topical Treatments:Spot-on solutions and sprays require specialized excipient chemistry for shelf stability and transdermal absorption. EPA aquatic toxicity data requirements favor scaled producers with environmental fate testing infrastructure.
- Liquid Solutions:Oral suspensions and additives enable precise dosing flexibility for multi-pet households.
- Powders:Meal-topper formats address palatability variation through dispersion in wet food.
Manufacturing scale concentrates in Topical Treatments; chewable innovation commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United States and pharmaceutical manufacturing clusters in Germany concentrate production capacity for OTC pet medication. These zones offer accelerated FDA and EMA registration pathways for animal health products. Suburban pet ownership density drives demand concentration in specific metropolitan corridors.
United States
Suburban ZIP codes in Texas and Florida generate concentrated demand for self-administered parasite prevention. FDA's Center for Veterinary Medicine coordinates with EPA FIFRA for dual-agency topical antiparasitic approvals. Kansas City's animal health corridor hosts formulation facilities serving mass retail pharmacy chains.
Germany
Extended pet lifespans in Bavaria and North Rhine-Westphalia expand chronic joint care purchasing. EMA's veterinary product committee maintains harmonized OTC classification standards across EU member states. Leipzig's pharmaceutical manufacturing cluster produces shelf-stable chewable formulations for export markets.
United Kingdom
Metropolitan London households favor subscription-based auto-ship platforms for recurring antiparasitic replenishment. The Veterinary Medicines Directorate regulates OTC switches from prescription status for specific active ingredients. Manchester's logistics infrastructure supports direct-to-consumer pharmacy distribution networks.
Japan
Aging companion animal demographics in Tokyo and Osaka drive nutraceutical demand for osteoarthritis management. PMDA's streamlined review pathways for animal health products reduce time-to-market for OTC formulations. Kansai region pharmaceutical manufacturers specialize in palatability-engineered tablet production.
Australia
Tick-borne disease prevalence in Queensland and New South Wales sustains seasonal antiparasitic purchasing cycles. TGA's agricultural and veterinary chemicals unit coordinates with state-level registration requirements. Sydney's veterinary services cluster integrates telehealth platforms with OTC product dispensing.
Otc Pet Medication Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation categories. Market structure tilts toward consolidation among scaled manufacturers with dedicated ecotoxicology and palatability engineering capabilities. Three archetypes dominate: vertically integrated pharmaceutical conglomerates, veterinary service-integrated retailers, and contract manufacturing specialists. Capacity expansion in shelf-stable topical solutions and strategic partnerships for subscription platform access represent the primary competitive moves.
Among pharmaceutical conglomerates with animal health divisions, Zoetis, Boehringer Ingelheim, and Merck Animal Health occupy positions anchored by manufacturing scale and regulatory expertise. These entities exemplify the integrated archetype through captive supply chains and established relationships with mass retail channels. PetIQ represents the veterinary service-integrated model, operating owned-and-operated clinics alongside retail partnerships to capture margin on product dispensing.
| Leading Market Players |
|---|
| Zoetis |
| Merck Animal Health |
| Boehringer Ingelheim |
| Elanco Animal Health |
| Ceva Sante Animale |
| Dechra |
| Virbac |
| Bayer AG |
| PetIQ |
| Others |
Value Network & Pricing Analysis
Subscription auto-ship adoption among millennial pet owners in metropolitan United States markets is compressing spot inventory premiums and forcing manufacturers toward contract-based volume commitments with direct-to-consumer pharmacy platforms.
Pricing Analysis
Short lead-time premiums for seasonal antiparasitic replenishment command 15-25% markups over subscription-contracted volumes in Q2-Q3 demand windows. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, with palatability-engineered chewables and EPA-registered topicals occupying premium tiers. Cost compression in economy-grade generics is intensifying because of Indian and Chinese API oversupply. Animal shelters and institutional buyers exhibit highest price sensitivity; veterinary-integrated clinic networks demonstrate lowest sensitivity due to margin capture on dispensing services.
Supply Chain Analysis
Direct-to-consumer pharmacy platforms and mass retail chains handle fragmented household demand, while veterinary-integrated networks manage higher-margin clinic-adjacent dispensing. Active pharmaceutical ingredient production concentrates in India and China, with finished formulation capacity clustering in the United States and Germany. Supply chains draw from fipronil, pyrantel pamoate, and glucosamine hydrochloride feedstocks. Single-source vulnerability in EPA-registered topical excipients creates bottleneck risk for scaled antiparasitic production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EPA FIFRA and FDA Center for Veterinary Medicine dual-registration requirements erect capital barriers that protect scaled incumbents from undercapitalized challengers.
For Market Incumbents: Anticipate telehealth prescribing rule relaxation by deepening backward integration into palatability-engineering capabilities and securing captive supply of shelf-stable topical excipients. Veterinary telehealth platforms represent the primary substitution threat to clinic-dispensed OTC adjacencies. Manufacturing capacity addition in Kansas City's animal health corridor offers geographic leverage over mass retail pharmacy chains. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for challenger brands seeking to bypass veterinary clinic gatekeepers. White-space targets include palatability-engineered joint care chewables for aging dog demographics and private-label antiparasitic formulations for mass merchandisers. A digital-native, auto-ship-first go-to-market angle aligns with millennial purchasing behavior in suburban United States ZIP codes. For Investors and Strategic Acquirers: The window for entry favors contract manufacturing specialists with EPA ecotoxicology capabilities and palatability formulation expertise. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. The signal to watch is FDA OTC monograph expansion for additional active ingredients, which would trigger consolidation among scaled manufacturers capable of rapid pathway navigation.| Strategic Initiative | Industry Significance |
|---|---|
| Palatability Engineering Investment | Convergence with pet food flavor science reduces regimen abandonment in chronic joint care applications. |
| EPA Ecotoxicology Capability Buildout | Aquatic toxicity data requirements for topical antiparasitics filter out undercapitalized competitors. |
| Direct-to-Consumer Platform Partnership | Subscription auto-ship models bypass veterinary clinic gatekeepers in United States metropolitan markets. |
| Prescription-to-OTC Switch Pipeline | Regulatory pathway expertise unlocks margin expansion in antiparasitic category transitions. |
| Manufacturing Footprint Regionalization | Kansas City and Leipzig clusters offer proximity to FDA and EMA registration pathways respectively. |
Research Methodology
Independent corroboration across regulatory affairs directors at animal health manufacturers, procurement leads at veterinary clinic networks, and pharmacy buyers at mass retail chains underwrites the qualitative findings. Primary interviews with formulation scientists, EPA compliance officers, and direct-to-consumer platform operators combined with secondary validation from FDA OTC monograph filings, EPA FIFRA registration databases, and USDA-APHIS facility inspection records. Bottom-up volume triangulation against top-down regulatory pathway analysis anchored market sizing.
Historical reference periods spanning pre-pandemic baseline through recent telehealth adoption inflection provided forecast anchoring. The analytical framework segmented by product type, end user, application, and formulation complexity across the projection horizon. CAGRs derived from regression against pet ownership demographics, regulatory filing velocity, and channel shift indicators. Modeled inputs included suburban household formation rates and FDA monograph expansion probability.
The model holds under stable dual-agency regulatory enforcement; deviation in EPA aquatic toxicity data requirements or veterinary telehealth prescribing authority would shift manufacturer compliance cost structures. Forecasts reflect base-case assumptions regarding seasonal demand patterns and subscription platform penetration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Veterinary Lasers Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Global Veterinary Grooming Aids Market
Veterinary
Veterinary Supplements Market
Veterinary
Animal Microchip Implant Market
Veterinary
Global Animal Model Market
Veterinary
Foot and Mouth Disease (FMD) Vaccine Market
Veterinary
Vet Software Market
Veterinary
Pet Cremation Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Milking Salve Market
Veterinary
Bovine Mastitis Market
Veterinary
Global Veterinary Drugs Market
Veterinary
CBD Pet Market