
 Veterinary Consumables Market | 2026-2036
Veterinary Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Consumables Market Analysis
Aftermarket service revenue attached to consumable replenishment cycles is rewriting profitability models across veterinary supply chains. Covetrus leverages its distribution network to bundle disposables with inventory management software for multi-site clinic operators. B. Braun SE anchors European production of sterilized procedure kits through captive manufacturing in Germany and Malaysia. Neogen Corporation specializes in diagnostic consumables that tie recurring test volumes to equipment placements in food-animal veterinary settings.
Veterinary consumables encompass single-use and limited-use products employed in animal diagnosis, treatment, and surgery, including syringes, sutures, drapes, culture media, and nutritional formulations manufactured to ISO 10993 biocompatibility and USP Class VI standards. Their primary purpose is to prevent cross-contamination between patients while enabling standardized, repeatable clinical workflows. Injection supplies and surgical instruments command the largest revenue pools due to per-procedure replenishment requirements, though diagnostic tools represent the fastest-expanding category as point-of-care testing migrates from reference laboratories into clinic settings. Nutritional supplements occupy a mature, brand-driven segment where margin accrues to formulation exclusivity rather than manufacturing scale.
FDA enforces Quality System Regulation 21 CFR Part 820 for device-grade consumables, while ISO 13485 certification governs suppliers serving EU markets under MDR requirements; the USDA's Center for Veterinary Biologics additionally regulates diagnostic kit components used in livestock disease programs. These frameworks elevate compliance costs for new entrants but protect incumbent positions for manufacturers with validated sterilization and traceability systems. Stakeholders must monitor evolving MDR technical documentation requirements and FDA digital health guidance as connected diagnostic consumables enter commercial distribution.
Market Dynamics
Stricter FDA sterility guidelines and ISO 13485 certification mandates are forcing veterinary clinics to upgrade from reusable to single-use surgical consumables, compressing replenishment cycles and rewriting distributor profitability models.
Growth Catalysts
- Regulatory stringency:FDA Quality System Regulation 21 CFR Part 820 mandates device-grade sterility documentation, compelling companion animal clinics to standardize on pre-validated surgical drapes and syringes.
- Point-of-care migration:Diagnostic consumables are displacing laboratory-based testing workflows as veterinary practices install in-house analyzers requiring recurring reagent purchases.
- Food-animal disease surveillance:USDA Center for Veterinary Biologics protocols drive recurring diagnostic kit volumes in livestock operations across the United States.
Market Restraints
- Ethylene oxide sterilization constraints:EPA emissions restrictions on EtO gas limit contract sterilizer capacity, creating bottlenecks for suture and drape manufacturers.
- Polymer feedstock volatility:Polypropylene and medical-grade PVC price swings compress margins for injection-molded consumable producers.
- European supply concentration:Germany and Malaysia host disproportionate sterilized kit production, exposing buyers to single-source geographic risk.
Strategic Opportunities
- Connected diagnostics convergence:RFID-enabled consumables paired with cloud inventory platforms are digitizing replenishment forecasting for multi-site clinic operators.
- Biologics packaging specialization:Temperature-stable vial and syringe formats for refrigerated veterinary vaccines represent underdeveloped white space.
- EU MDR technical documentation:Early compliance with expanded traceability requirements positions suppliers for premium tiering under CE-marking rules.
Industry Challenges
- Sterilization validation timelines:ISO 11135 ethylene oxide validation cycles extend 12-18 months, delaying new product commercialization.
- ISO 13485 auditor scarcity:Limited notified body capacity stretches certification lead times for mid-tier manufacturers seeking EU market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Consumables Market |
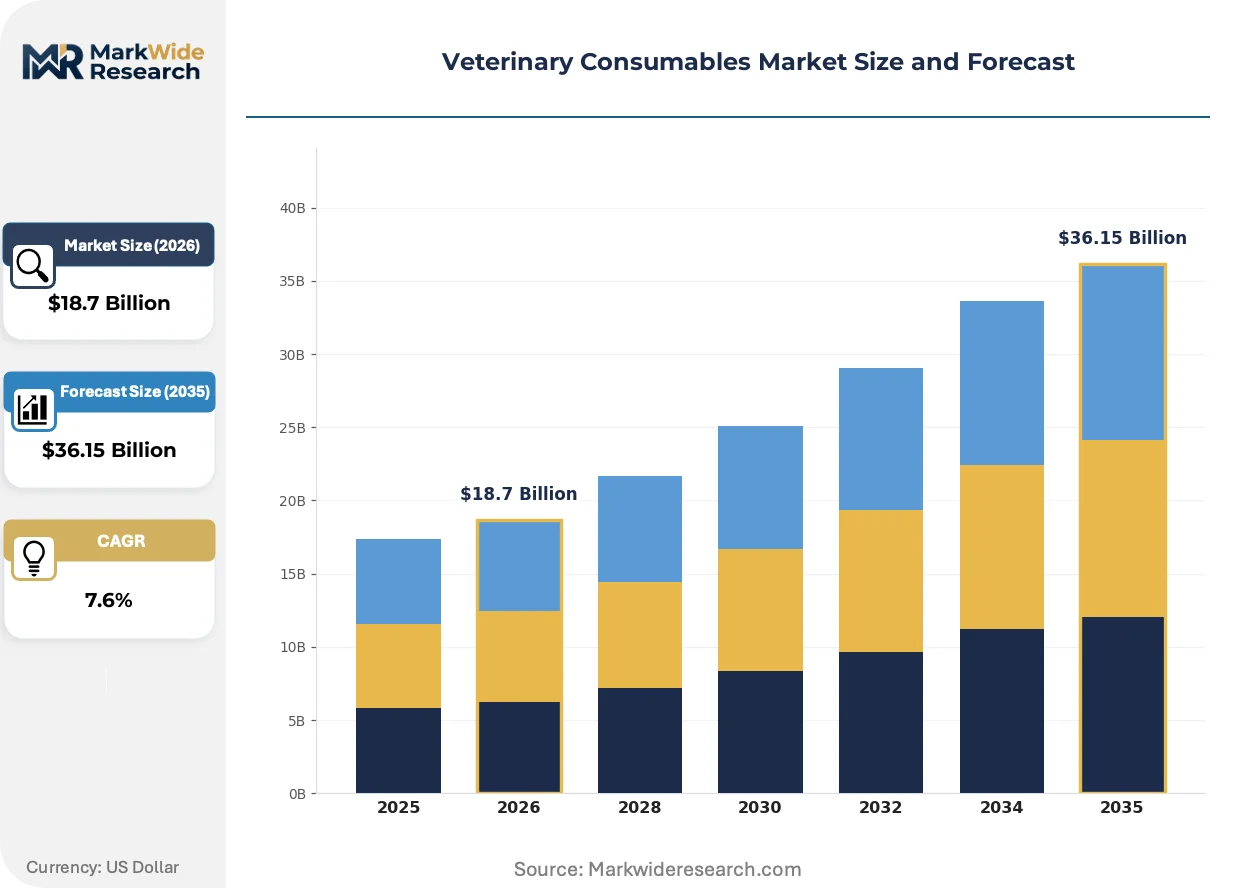
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Supplies, Surgical Instruments, Diagnostic Tools, Nutritional Supplements End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Pharmacies Distribution Channel: Online Stores, Direct Sales, Distributors, Retail Outlets Application: Routine Check-ups, Emergency Treatments, Surgical Procedures, Preventive Care |
| Companies Covered | Shenzhen Mindray Bio-Medical Electronics, Midmark Corporation, Smiths Medical, Covetrus, B. Braun SE, BD, Cardinal Health, ICU Medical, Neogen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Consumables Market Emerging Trajectories
Digital integration of consumable inventory with practice management software is compressing procurement cycles and enabling predictive replenishment models across veterinary supply chains.
Radio-frequency identification tags embedded in surgical drape packaging are digitizing real-time usage tracking. Large companion animal hospital chains in the United States are piloting RFID-enabled cabinets that auto-trigger purchase orders when stock hits reorder points. This infrastructure is digitizing distributor-client relationships from transactional supply toward embedded inventory partnerships.
EU MDR technical documentation requirements for Class I device reclassification are elevating sterilization traceability burdens. Manufacturers serving European markets must now submit biological evaluation reports per ISO 10993 series standards. Diagnostic consumable producers face the steepest compliance ramps as notified bodies scrutinize reagent stability claims.
Consolidated buying groups are displacing individual clinic purchasing across the United States. Multi-site operators now negotiate system-wide contracts bundling disposables with equipment service agreements. This concentration is most visible in metropolitan veterinary networks across Texas and Florida, where procurement committees standardize on single-source suppliers to extract volume rebates.
Veterinary Consumables Market Segmentation
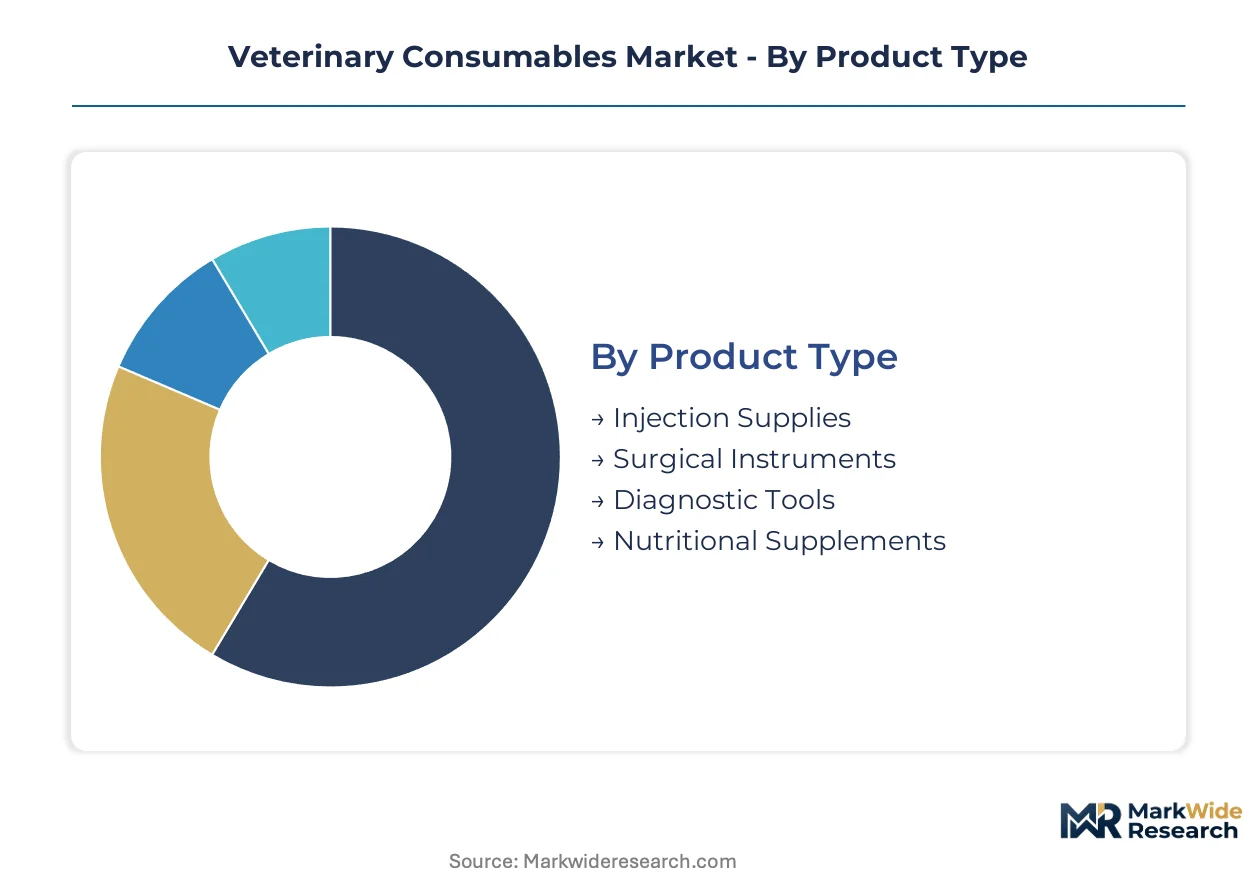
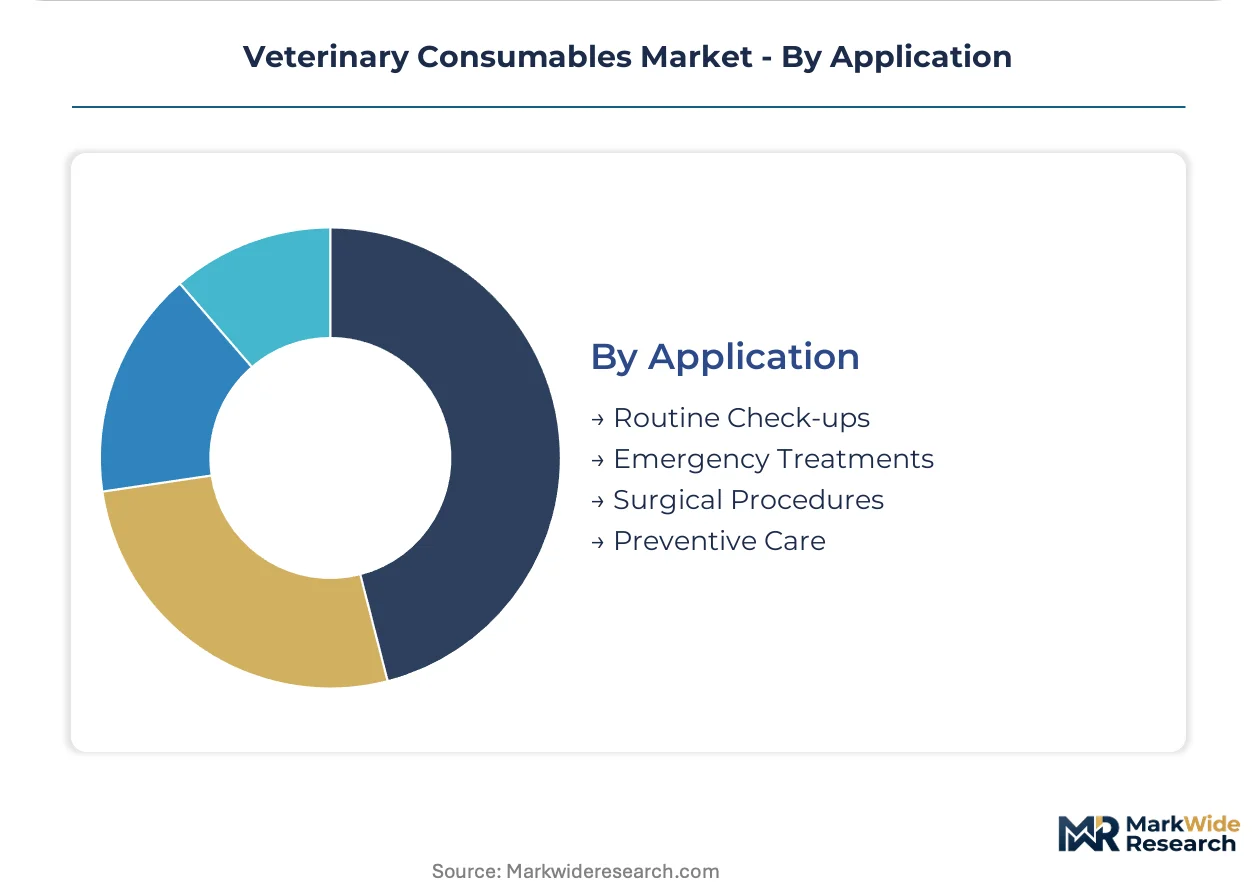
Veterinary consumables segmentation reveals distinct procurement patterns across product categories and customer types. Understanding these divisions exposes where margin concentrates and which channels are displacing traditional supply relationships.
Product Type:
Cost tier differentiation separates commodity injection supplies from premium diagnostic platforms requiring recurring reagent purchases.
- Injection Supplies:Polypropylene syringes and hypodermic needles manufactured to ISO 7886 standards dominate volume throughput. Demand clusters in high-frequency vaccination programs across United States companion animal practices where FDA sterility documentation mandates single-use protocols.
- Surgical Instruments:Limited-use scalpels, forceps, and retractors compete with reusable alternatives through convenience positioning. German and French veterinary hospitals are upgrading to pre-sterilized disposable kits under MDR traceability requirements, compressing traditional reprocessing workflows.
- Diagnostic Tools:Point-of-care test strips, culture media, and reagent cartridges.
- Nutritional Supplements:Prescription diets and therapeutic formulations.
Injection supplies command the established base. The steepest expansion runs through diagnostic tools.
End User:
Customer type determines contract structure, with consolidated buying groups extracting volume terms unavailable to independent operators.
- Veterinary Clinics:Small-to-midscale companion animal practices representing high transaction frequency, low order value procurement. Texas and Florida metropolitan networks are standardizing on single-source suppliers to secure system-wide rebates.
- Animal Hospitals:Multi-specialty referral centers with surgical suites and in-house laboratories. These facilities in Germany are piloting RFID-enabled inventory cabinets that auto-trigger replenishment orders.
- Research Institutions:Academic and pharmaceutical testing facilities.
- Pharmacies:Retail and compounding outlets serving livestock producers.
Veterinary clinics anchor volume throughput. The steepest expansion runs through animal hospitals.
Distribution Channel:
Channel selection reflects geographic concentration of veterinary infrastructure and regulatory complexity of product categories.
- Online Stores:E-commerce platforms serving independent clinics with next-day delivery on standardized consumables. United States distributors are bundling disposables with cloud inventory management software to embed recurring relationships.
- Direct Sales:Manufacturer field representatives negotiating multi-year agreements with hospital chains. B. Braun SE deploys this channel for sterilized procedure kits across German production captive to Malaysia manufacturing.
- Distributors:Regional and national wholesalers consolidating fragmented demand.
- Retail Outlets:Farm supply stores and co-ops serving food-animal producers.
Distributors retain the established base. The steepest expansion runs through online stores.
Application:
Application context dictates sterility grade, documentation burden, and replenishment urgency.
- Routine Check-ups:Standard vaccination and wellness examination consumables with predictable demand curves. United States companion animal clinics are expanding procurement of single-use drapes amid stricter FDA guidelines.
- Surgical Procedures:Sterile drapes, sutures, and procedure kits requiring validated ethylene oxide sterilization. EPA emissions restrictions on EtO gas are limiting contract sterilizer capacity for these products.
- Emergency Treatments:Trauma and critical care supplies with irregular demand spikes.
- Preventive Care:Parasiticides, dental kits, and screening tests.
Routine check-ups command the established base. The steepest expansion runs through surgical procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between companion animal economies and livestock-dominant veterinary systems. The United States concentrates spending on single-use surgical disposables and point-of-care diagnostics, while Germany and France drive hospital-grade consumable upgrades under EU MDR timelines. Malaysia and China serve as manufacturing anchors for sterilized kit production feeding Western markets.
United States
Companion animal clinics in Texas and Florida metropolitan networks are consolidating procurement through single-source supplier contracts bundling disposables with inventory software. FDA Quality System Regulation 21 CFR Part 820 mandates device-grade sterility documentation, compressing replenishment cycles for syringes and surgical drapes. Covetrus leverages its distribution infrastructure to embed recurring relationships with multi-site operators across these Sun Belt veterinary networks.
Germany
Veterinary hospitals in Baden-Württemberg and Bavaria are piloting RFID-enabled inventory cabinets that auto-trigger purchase orders when consumable stocks hit reorder points. EU MDR technical documentation requirements for Class I device reclassification elevate sterilization traceability burdens for suppliers serving these facilities. B. Braun SE anchors European production of sterilized procedure kits through captive manufacturing in Melsungen and complementary capacity in Malaysia.
France
Hospital-grade consumable upgrades concentrate in Île-de-France and Auvergne-Rhône-Alpes as veterinary referral centers expand surgical suite capacity. ANSM oversight of medical device vigilance systems reinforces ISO 13485 certification mandates for consumable suppliers. Diagnostic consumable producers face steep compliance ramps as notified bodies scrutinize reagent stability claims for point-of-care platforms entering these markets.
Malaysia
Contract sterilization and kit assembly operations in Penang and Selangor serve as critical supply nodes for European and North American veterinary distributors. EPA emissions restrictions on ethylene oxide gas in the United States have shifted some sterilization demand toward Malaysian contract facilities with validated ISO 11135 cycles. This geographic concentration exposes buyers to single-source risk during freight disruptions or regulatory audits.
China
Domestic production of polypropylene syringes and injection-molded consumables clusters in Guangdong and Jiangsu provinces, feeding both internal veterinary market expansion and export demand. NMPA medical device registration requirements are tightening for imported diagnostic consumables, creating incentives for local manufacturing partnerships. Shenzhen Mindray Bio-Medical Electronics exemplifies the vertically integrated model combining device production with captive consumable supply.
Veterinary Consumables Market Vendor Landscape
Capability concentration sits with specialized sterilization and diagnostics producers; scale advantage sits with diversified medical device conglomerates and distribution platforms. The market structures around three tiers: integrated device-consumable systems houses, pure-play veterinary distributors with inventory software attach, and regional contract manufacturers serving private-label programs. Competitive moves center on backward integration into sterilization capacity and forward integration into cloud-based replenishment platforms.
Among diversified medical technology conglomerates, BD and Cardinal Health occupy positions spanning human and veterinary consumable markets with established sterilization validation infrastructures. Within the veterinary-specialist tier, Covetrus exemplifies the distributor-software hybrid model, while Neogen Corporation represents the diagnostics-focused archetype tethering recurring consumable volumes to equipment placements. Shenzhen Mindray Bio-Medical Electronics anchors the Asia-Pacific manufacturing vector with integrated production of analyzers and matched reagent consumables.
| Leading Market Players |
|---|
| Shenzhen Mindray Bio-Medical Electronics |
| Midmark Corporation |
| Smiths Medical |
| Covetrus |
| B. Braun SE |
| BD |
| Cardinal Health |
| ICU Medical |
| Neogen Corporation |
| Others |
Supply Flow & Price Mechanics
Penang and Selangor sterilization clusters in Malaysia concentrate ethylene oxide capacity for veterinary procedure kits, granting contract manufacturers leverage over European and North American distributors facing EPA emissions constraints in their home markets. This geographic chokepoint translates into pricing power for validated ISO 11135 facilities, while buyers absorb freight premiums and single-source risk during supply disruptions.
Pricing Analysis
Long-term offtake contracts dominate procurement between multi-site veterinary chains and sterilized kit suppliers, though spot purchasing persists for independent clinics buying injection supplies through e-commerce platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated surgical drapes from basic polypropylene syringes and unbranded commodity needles. Cost compression in standard-grade consumables is intensifying because polypropylene feedstock volatility transfers directly to per-unit pricing. Consolidated buying groups in Texas and Florida metropolitan networks exhibit lowest price sensitivity due to volume rebate structures, while independent companion animal practices in rural United States markets face highest sensitivity to per-unit fluctuations.
Supply Chain Analysis
Extended payment terms from German distributors to Malaysian contract sterilizers have become standard practice, with supply-chain finance facilities bridging working capital gaps for kit assemblers facing 12-18 month ISO 11135 validation cycles. Manufacturing concentrates in Germany, Malaysia, and China, with Melsungen hosting B. Braun SE's captive production and Guangdong province feeding injection-molded consumables for domestic and export markets. Raw material dependencies center on medical-grade polypropylene, ethylene oxide gas, and sterilization-grade packaging films. Single-source vulnerability runs through Malaysian EtO capacity exposed to freight disruptions and regulatory audits. Distribution runs through national veterinary distributors bundling disposables with cloud inventory platforms for multi-site operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue attached to consumable replenishment cycles is expanding faster than hardware placements, repositioning veterinary supply relationships around recurring inventory partnerships rather than transactional product sales.
For Market Incumbents: Pre-empt consolidation of sterilization capacity by acquiring validated EtO facilities or securing exclusive toll-manufacturing agreements before EPA restrictions tighten further in the United States. Anchor backward integration into polymer compounding to defend margin position against polypropylene price volatility. Prioritize certification investment in EU MDR technical documentation to maintain premium tiering access as notified body scrutiny intensifies for Class I device reclassifications. For New Entrants and Emerging Players: Establish a beachhead in temperature-stable biologics packaging for refrigerated veterinary vaccines, a white space underserved by incumbent sterilized kit specialists. Target food-animal diagnostic consumables in United States livestock operations where USDA Center for Veterinary Biologics protocols drive recurring test volumes. Pursue a direct-to-clinic digital channel bundling RFID-enabled consumables with cloud replenishment software to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because consumable attach rates to in-house diagnostic analyzers create predictable reagent purchase streams decoupled from capital equipment cycles. Acquisition targets should display validated sterilization traceability systems and established notified body relationships under MDR frameworks. Monitor EPA ethylene oxide emissions rulemaking as the critical signal for capacity relocation timing and contract sterilizer valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sterilization Capacity | Captive EtO validation insulates margin from EPA emissions restrictions and contract sterilizer bottlenecks. |
| RFID-Enabled Inventory Platform Development | Cloud replenishment software embeds distributor relationships with multi-site veterinary chains in Texas and Florida. |
| EU MDR Technical Documentation Compliance | Early ISO 10993 biological evaluation submission secures premium tiering under CE-marking rules for Class I devices. |
| Biologics Packaging Specialization | Temperature-stable vial formats for refrigerated vaccines address underpenetrated white space in cold-chain veterinary products. |
| Diagnostic Consumable-Analyzer Bundling | Recurring reagent volumes tethered to point-of-care equipment placements displace laboratory-based testing workflows. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, and veterinary distributor financial disclosures preceded structured interviews with procurement directors at multi-site companion animal chains, sterilization validation engineers at contract manufacturers, and regulatory affairs leads at diagnostic consumable producers. Primary fieldwork with biomedical engineers and GPO contracts managers validated replenishment cycle assumptions and pricing tier structures. Secondary sources included USDA Center for Veterinary Biologics protocol documents, ISO 13485 certification registries, and trade data on polypropylene medical-grade resin imports. Bottom-up modeling of procedure volumes per veterinary practice category was cross-checked against top-down distributor revenue segmentation.
Assumptions around FDA sterility guideline enforcement timelines and EU MDR notified body capacity were held fixed across baseline scenarios, while polymer feedstock price trajectories and ethylene oxide emissions regulatory stringency were stress-tested in sensitivity variants. The forecast framework disaggregates revenue across product type, end user, distribution channel, and application dimensions, with additional segmentation by sterilization validation tier and geographic regulatory cluster. CAGRs were derived from procedure volume growth rates applied to per-procedure consumable intensity factors, incorporating point-of-care diagnostic migration patterns and consolidated buying group expansion in United States metropolitan markets.
Sensitivities concentrate around EPA ethylene oxide emissions rulemaking revisions, ISO 13485 notified body audit backlogs, and polypropylene price volatility spikes. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and sterilization capacity utilization rates. Macroeconomic contraction affecting veterinary visit frequency, accelerated MDR implementation timelines, or breakthroughs in reusable surgical instrument sterilization protocols would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
OTC Cat Medicines Market
Veterinary
Global Livestock Vaccines Market
Veterinary
Veterinary Wound Sprays Market
Veterinary
Veterinary Endodontics Market
Veterinary
Europe Veterinary Antibiotics Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
Global Animal Vaccine Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Bovine Collagen Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Global Canine Atopic Dermatitis Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Veterinary Hospitals Market
Veterinary
Veterinary Progesterone Testing Market
Veterinary
Clostridium Vaccine (Animal Health) Market