
 Global Autogenous Vaccines Market | 2026-2036
Global Autogenous Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autogenous Vaccines Market Foresight
Aftermarket service revenue from autogenous vaccine formulation and strain-specific diagnostics is reshaping how veterinary biopharmaceuticals capture value beyond product sales. Ceva Santé Animale leverages its European manufacturing network to sustain regional supply agreements with integrated poultry producers. Zoetis Inc. anchors North American demand through captive diagnostic-to-vaccine workflows that reduce turnaround times for farm-specific formulations.
Autogenous vaccines are custom immunological preparations derived from pathogens isolated at a specific farm or production facility, typically manufactured through fermentation or cell culture processes with adjuvant formulation to elicit targeted herd immunity against circulating local strains. Their primary purpose is to fill protection gaps where no commercial vaccine exists or where standard products fail against emergent bacterial or viral variants. Bacterins and live attenuated products occupy distinct margin tiers, with bacterins dominating volume in swine and poultry applications while recombinant approaches attract investment for aquaculture expansion. End-user concentration at veterinary clinics and large animal farms reflects a structural split between small-batch custom orders and high-volume contracts with integrated producers.
FDA's Center for Veterinary Medicine oversees autogenous vaccine production under memorandum-specific rules that limit interstate distribution but permit intrastate farm-directed use, while EMA guidelines across EU member states enforce batch consistency and pathogen traceability standards that shape manufacturing compliance costs. The WHO's Terrestrial Animal Health Code provides reference frameworks that national regulators in Brazil and India adapt for domestic autogenous programs. Stakeholders must monitor how regulatory divergence between major markets affects cross-border manufacturing partnerships and strain banking strategies.
Market Dynamics
Contract manufacturing concentration around large integrated livestock operations is compressing margins for small-batch producers while rewarding diagnostic-to-vaccine workflow investments that cut turnaround times.
Growth Catalysts
- Strain-specific diagnostics integration:Veterinary laboratories in the United States now embed pathogen sequencing directly into vaccine production pipelines, collapsing the time between isolation and formulation.
- EMA batch traceability standards:European harmonization of pathogen documentation requirements is reducing cross-border manufacturing friction for multi-site livestock corporations operating across Germany, France, and Spain.
- Aquaculture recombinant platforms:Norwegian salmon producers are driving investment in DNA-based autogenous approaches for viral hemorrhagic septicemia variants that commercial vaccines fail to neutralize.
Market Restraints
- Adjuvant raw material volatility:Aluminum hydroxide and oil-in-water emulsion inputs face price swings tied to mining and petrochemical supply chains, squeezing formulation economics for mid-tier bacterin manufacturers.
- FDA interstate distribution limits:Memorandum 800.116 restrictions prevent autogenous products from crossing state lines, fragmenting production scale and trapping volume within single-state veterinary jurisdictions.
- Live attenuated cold chain requirements:Temperature-sensitive transport infrastructure gaps in Brazil and India constrain shelf-life extension for farm-specific viral vaccines, privileging bacterin alternatives.
Strategic Opportunities
- India's untapped dairy sector:Foot-and-mouth disease variant circulation in Gujarat and Punjab herds lacks matching commercial vaccine coverage, opening autogenous formulation contracts for regional cooperatives.
- Digital strain banking networks:Cloud-based pathogen repositories are enabling veterinary biopharmaceuticals to resurrect archived isolates for recurring outbreaks without fresh field collection.
- USDA cost-share programs:Emerging animal disease preparedness initiatives are subsidizing diagnostic infrastructure that feeds directly into autogenous production workflows for small-to-mid-sized swine operations.
Industry Challenges
- Fermentation scale-up expertise:Custom vaccine producers struggle to recruit process engineers capable of translating bench-scale pathogen cultivation to industrial bioreactor output without strain drift.
- Multi-jurisdiction compliance staffing:Manufacturers serving both FDA and EMA markets must maintain parallel quality systems, duplicating documentation overhead for batch release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autogenous Vaccines Market |
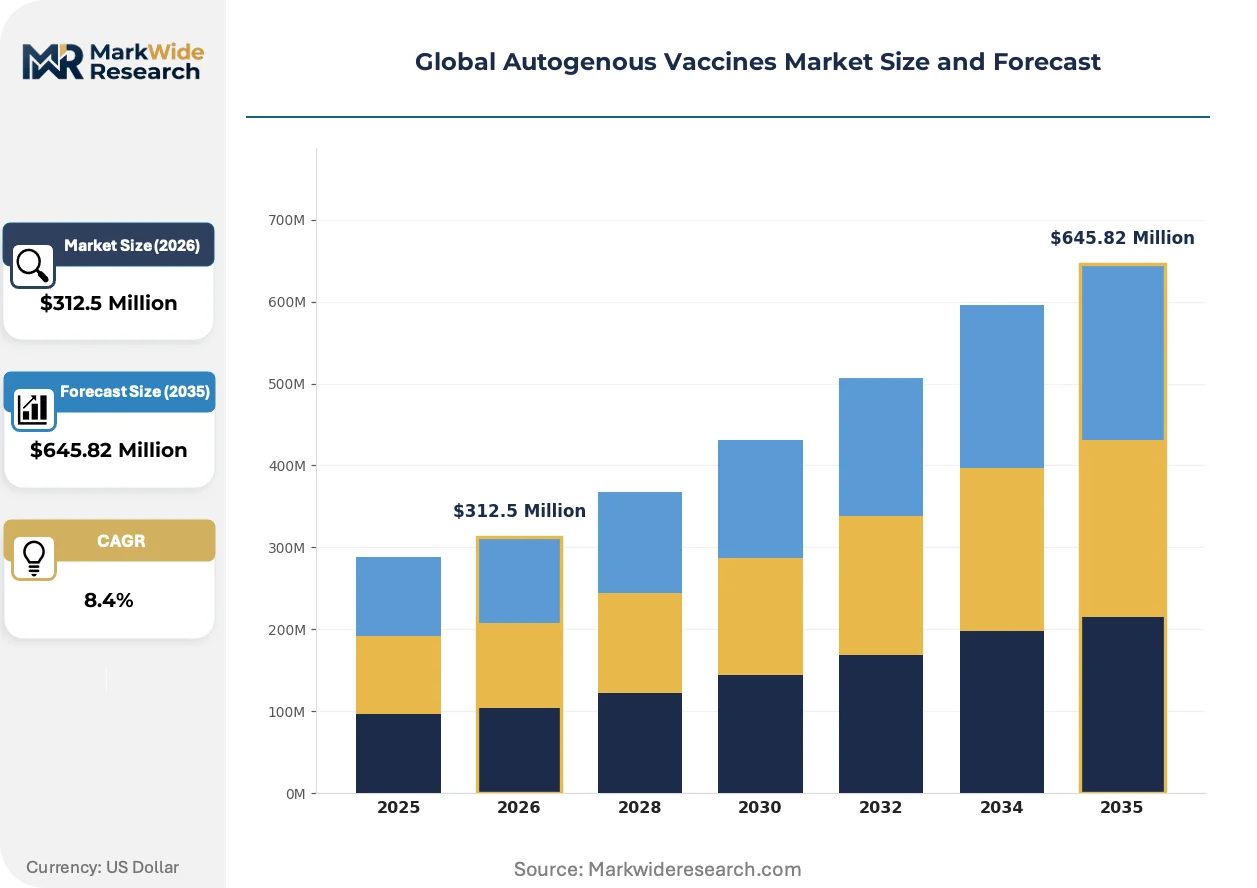
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterins, Toxoids, Live Attenuated, Recombinant, Conjugate Application: Poultry, Aquaculture, Swine, Companion Animals, Equine End User: Veterinary Clinics, Diagnostic Laboratories, Biopharmaceutical Firms, Animal Farms Production Technology: Fermentation, Cell Culture, Emulsification, Adjuvant Formulation |
| Companies Covered | Ceva Santé Animale, Hester Biosciences Limited, Vaxxinova GmbH, Vetoquinol SA, Virbac, Inc., Zoetis Inc., HIPRA, S.A., Bimeda Biologicals, Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autogenous Vaccines Market Shifts & Advancements
Next-generation sequencing and synthetic biology are compressing the development cycle for farm-specific immunologicals while regulatory sandboxes in major economies test adaptive approval frameworks.
CRISPR-guided attenuation is rendering obsolete conventional serial passage methods for live vaccine strain derivation. Danish swine integrators have adopted this platform for porcine reproductive and respiratory syndrome variants, cutting development timelines from months to weeks. The technology is compressing competitive advantage toward laboratories with in-house gene-editing capabilities rather than external service dependencies.
The EU's Veterinary Medicines Regulation 2019/6 created a dedicated autogenous product category with streamlined manufacturing authorization pathways. This framework is diverting investment toward centralized European production hubs capable of serving multi-national livestock corporations under single regulatory umbrellas. German and Dutch manufacturers are consolidating strain libraries to exploit this jurisdictional efficiency.
Integrated livestock corporations are unbundling diagnostic and vaccine procurement, awarding separate contracts to specialized laboratories and formulation facilities rather than single-source providers. This pattern is fragmenting volume concentration and elevating price transparency through competitive bidding. The shift is most pronounced in United States poultry operations running vertical coordination models across Mississippi, Arkansas, and North Carolina processing clusters.
Global Autogenous Vaccines Market Segmentation
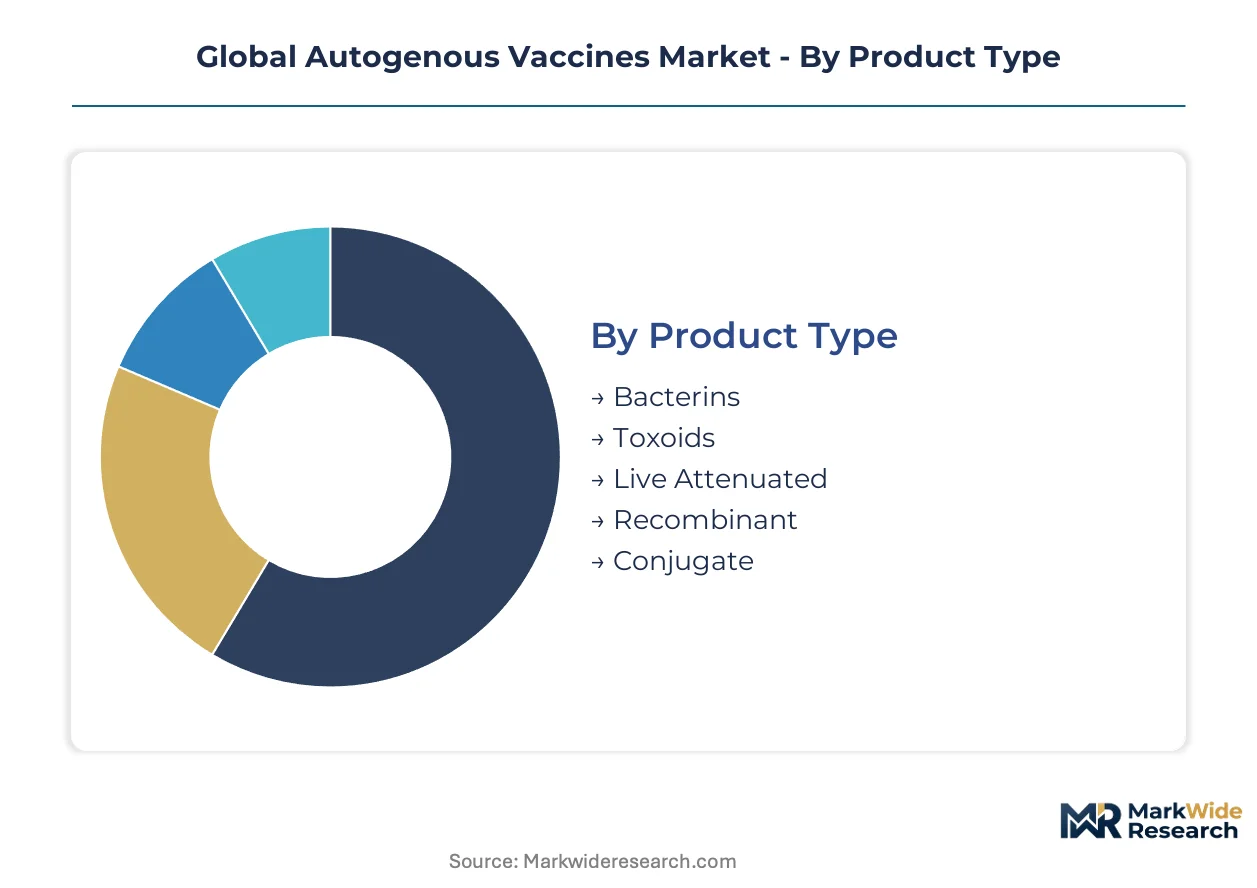
Segmentation in autogenous vaccines determines service intensity, regulatory pathway, and margin structure. Product type dictates formulation complexity, application shapes outbreak response velocity, end user concentration drives contract manufacturing scale, and production technology governs capital requirements.
Product Type:
After-sales service intensity peaks with live attenuated and recombinant platforms, where strain banking, cold chain validation, and potency monitoring extend revenue capture well beyond initial formulation.
- Bacterins:Inactivated bacterial suspensions with aluminum hydroxide or oil adjuvant deliver stable, room-temperature-tolerant formulations. Swine operations in Iowa and North Carolina contract for high-volume bacterin programs against farm-specific Haemophilus parasuis variants, with diagnostic-to-vaccine turnaround compressing to under 14 days.
- Live Attenuated:Weakened pathogen strains replicate briefly in vivo to stimulate cellular immunity. Poultry integrators across Mississippi and Arkansas favor live platforms for laryngotracheitis variants, though cold chain requirements and shortened shelf lives elevate field service intensity.
- Toxoids:Bacterial exotoxins inactivated by formalin or heat elicit antitoxin antibody production. Equine facilities in Kentucky and Florida maintain standing orders for Clostridium toxoid formulations.
- Recombinant:DNA-derived subunit vaccines bypass pathogen cultivation entirely. Norwegian salmon producers drive demand for viral hemorrhagic septicemia recombinants where commercial products fail.
- Conjugate:Polysaccharide-protein linkages enhance immunogenicity in young animals. Limited autogenous application due to manufacturing complexity.
By volume, bacterins lead. By growth pace, recombinant platforms are ahead.
Application:
Cost tier stratification separates commodity livestock applications with thin margins from companion animal and equine segments commanding formulation premiums.
- Poultry:Vertical integration across Georgia, Alabama, and Arkansas processing clusters generates concentrated contract volumes. Autogenous programs target variant infectious bronchitis and reovirus strains circulating within single-corporation production systems.
- Swine:Large integrated operations in Minnesota and Illinois sustain diagnostic-to-vaccine pipelines for porcine reproductive and respiratory syndrome variants. Farm-specific Streptococcus suis bacterins dominate volume.
- Aquaculture:Norwegian and Chilean salmon producers invest in autogenous approaches for pancreas disease and infectious salmon anemia variants escaping commercial vaccine coverage.
- Companion Animals:Canine and feline autogenous demand concentrates at specialty referral hospitals managing resistant Staphylococcus infections.
- Equine:Thoroughbred breeding operations in Kentucky and California commission custom Rhodococcus equi and Clostridium formulations.
Poultry and swine generate the contract volume; aquaculture commands the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with integrated producers consolidating diagnostic and manufacturing contracts while independent clinics fragment across small-batch suppliers.
- Animal Farms:Integrated livestock corporations in the United States unbundle diagnostic and vaccine procurement, awarding separate contracts to specialized laboratories and formulation facilities. This pattern elevates price transparency through competitive bidding.
- Diagnostic Laboratories:Veterinary reference labs embed pathogen sequencing directly into vaccine production pipelines, collapsing isolation-to-formulation timelines. Ceva Santé Animale leverages its European network to sustain regional supply agreements.
- Veterinary Clinics:Small animal and mixed practice clinics generate fragmented, low-volume orders for resistant bacterial infections.
- Biopharmaceutical Firms:Contract manufacturers serve as formulation partners for diagnostic laboratories lacking in-house GMP production capacity.
Animal farms concentrate procurement volume; diagnostic laboratories are climbing the fastest.
Production Technology:
Supply concentration in fermentation capacity shapes competitive access, with cell culture expertise scarcer and commanding premium positioning.
- Fermentation:Bacterial pathogen cultivation in bioreactors dominates bacterin production. Mid-tier manufacturers in Germany and the Netherlands struggle to recruit process engineers capable of scaling bench cultivation to industrial output without strain drift.
- Cell Culture:Viral propagation in mammalian or avian cell lines supports live attenuated and recombinant platforms. Cold chain infrastructure gaps in Brazil and India constrain shelf-life extension.
- Emulsification:Oil-in-water or water-in-oil adjuvant blending determines immunogenicity duration. Raw material volatility in petrochemical supply chains squeezes formulation economics.
- Adjuvant Formulation:Aluminum salt and saponin-based immune enhancers require precise concentration control. EMA batch traceability standards enforce documentation overhead for cross-border manufacturing.
Fermentation leads by installed capacity; cell culture is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturing capacity clusters in the United States, Germany, and the Netherlands, with diagnostic-to-vaccine workflows shortening turnaround times for farm-specific formulations. Regulatory divergence between FDA memorandum rules and EMA batch traceability standards fragments cross-border production scale.
United States
Large integrated pork and poultry operations in Iowa, North Carolina, and Minnesota drive contract volumes for farm-specific bacterins against Haemophilus parasuis and Streptococcus suis variants. FDA Center for Veterinary Medicine Memorandum 800.116 restricts interstate distribution, trapping production within single-state veterinary jurisdictions. The Mississippi-Arkansas poultry processing corridor sustains concentrated demand for autogenous programs targeting variant infectious bronchitis strains.
Germany
EMA Veterinary Medicines Regulation 2019/6 created a dedicated autogenous product category with streamlined manufacturing authorization pathways. German manufacturers are consolidating strain libraries to serve multi-national livestock corporations under single regulatory umbrellas. The Lower Saxony region anchors production hubs capable of cross-border supply to integrated producers operating across France and Spain.
Netherlands
Dutch swine integrators have adopted CRISPR-guided attenuation platforms for porcine reproductive and respiratory syndrome variants, compressing development timelines from months to weeks. EMA guidelines enforce batch consistency and pathogen traceability standards that shape manufacturing compliance costs. The Gelderland region concentrates fermentation expertise for industrial-scale bacterin production.
Norway
Salmon producers in the Bergen-Stavanger corridor drive investment in recombinant DNA-based autogenous approaches for viral hemorrhagic septicemia variants that commercial vaccines fail to neutralize. The country's national pharmaceutical regulator adapts WHO Terrestrial Animal Health Code frameworks for domestic aquaculture programs. Cold chain infrastructure investments support temperature-sensitive transport for farm-specific viral vaccines.
Brazil
Foot-and-mouth disease variant circulation in São Paulo and Minas Gerais herds lacks matching commercial vaccine coverage, opening autogenous formulation contracts for regional cooperatives. ANVISA adapts international reference frameworks for domestic autogenous programs. Temperature-sensitive transport infrastructure gaps constrain shelf-life extension for live attenuated products, privileging bacterin alternatives in the southern livestock belt.
Global Autogenous Vaccines Market Competitive Landscape
Integrated diagnostic-to-vaccine specialists and standalone formulation contractors split the market along workflow integration lines. The vendor base concentrates around laboratories with captive pathogen sequencing capabilities and manufacturers with multi-jurisdiction quality certifications. Two archetypes dominate: vertically integrated veterinary biopharmaceuticals controlling diagnostic-to-formulation pipelines, and contract manufacturers serving as formulation partners for external laboratories. Competitive moves center on diagnostic infrastructure acquisitions and strain banking network expansion.
Within the integrated tier, Ceva Santé Animale leverages its European manufacturing network to sustain regional supply agreements, while Zoetis Inc. anchors North American demand through diagnostic-to-vaccine workflows. Vaxxinova GmbH occupies a position among specialized autogenous producers with concentrated fermentation capacity. These three exemplify how geographic manufacturing footprint and regulatory jurisdiction coverage determine competitive access in fragmented national markets.
| Leading Market Players |
|---|
| Ceva Santé Animale |
| Hester Biosciences Limited |
| Vaxxinova GmbH |
| Vetoquinol SA |
| Virbac, Inc. |
| Zoetis Inc. |
| HIPRA, S.A. |
| Bimeda Biologicals |
| Boehringer Ingelheim International GmbH |
| Others |
Supply & Pricing Matrix
Aluminum hydroxide and oil-in-water emulsion volatility determines both pricing tier spreads and supply chain shape in autogenous vaccine manufacturing. Adjuvant raw material swings tied to mining and petrochemical feedstocks compress formulation economics for mid-tier bacterin producers while privileging vertically integrated manufacturers with captive chemical supply.
Pricing Analysis
FDA Memorandum 800.116 dictates the pricing tier structure by fragmenting production scale within single-state veterinary jurisdictions. Contract manufacturers serving large integrated pork and poultry operations in Iowa and North Carolina command premium positioning through diagnostic-to-vaccine workflow integration, while small-batch producers face cost compression from competitive bidding on unbundled procurement. Price differentiation hinges on volume scale and after-sales service bundling including strain banking and potency monitoring. Pricing pressure stems from adjuvant input volatility, with aluminum salt and saponin-based immune enhancers squeezing margins. Independent veterinary clinics demonstrate highest price sensitivity due to fragmented order volumes, whereas integrated livestock corporations prioritize turnaround reliability over unit cost.
Supply Chain Analysis
Extended payment terms from integrated livestock buyers strain working capital for contract manufacturers lacking supply-chain finance facilities. Production capacity concentrates in the United States, Germany, and the Netherlands, with fermentation expertise anchoring in the Gelderland region and cell culture capabilities scarcer and commanding premium positioning. Raw material dependencies rest on aluminum hydroxide mining outputs, petrochemical-derived emulsion stocks, and pathogen-specific culture media. Single-source vulnerability runs through adjuvant chemical suppliers concentrated in industrial chemical corridors. Distribution runs through veterinary diagnostic laboratories that embed sequencing directly into vaccine production pipelines, collapsing isolation-to-formulation timelines for farm-specific programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autogenous vaccines market is entering a cyclical recovery phase driven by livestock herd restocking cycles following disease outbreaks. Producer investment in biosecurity infrastructure and diagnostic capability expansion supports sustained contract manufacturing demand across the projection horizon.
For Market Incumbents: Entrench diagnostic-to-vaccine workflow dominance by acquiring regional veterinary reference laboratories with embedded sequencing capability, countering the threat of unbundled procurement patterns that fragment volume concentration. Add fermentation capacity in the Lower Saxony region to exploit EMA Veterinary Medicines Regulation 2019/6 jurisdictional efficiency for cross-border supply to multi-national livestock corporations. Deepen strain banking network density through cloud-based pathogen repository investments that resurrect archived isolates without fresh field collection.
For New Entrants and Emerging Players: Establish a beachhead in India's untapped dairy sector by securing autogenous formulation contracts with regional cooperatives in Gujarat and Punjab for foot-and-mouth disease variants lacking commercial vaccine coverage. Target aquaculture recombinant platforms in Norway and Chile where viral hemorrhagic septicemia and infectious salmon anemia variants escape standard immunological coverage. Pursue a go-to-market angle partnering with diagnostic laboratories lacking in-house GMP production capacity rather than competing directly for integrated producer contracts.
For Investors and Strategic Acquirers: EMA Veterinary Medicines Regulation 2019/6 reshapes the acquisition landscape by creating dedicated autogenous product categories with streamlined manufacturing authorization pathways that reward centralized European production hubs. Long-term viability over the five-to-ten year window hinges on regulatory jurisdiction coverage and diagnostic infrastructure ownership rather than standalone formulation capacity. Target acquisition archetypes are mid-tier contract manufacturers with multi-jurisdiction quality certifications and captive strain libraries. The signal to watch is USDA cost-share program expansion for emerging animal disease preparedness that subsidizes diagnostic infrastructure feeding directly into autogenous workflows.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Laboratory Acquisition | Ceva Santé Animale's European network demonstrates how captive sequencing capability secures regional supply agreements with integrated poultry producers. |
| CRISPR-Guided Attenuation Platform Investment | Dutch swine integrators have compressed porcine reproductive and respiratory syndrome variant development timelines from months to weeks using gene-editing capabilities. |
| Strain Banking Network Expansion | Cloud-based pathogen repositories enable veterinary biopharmaceuticals to resurrect archived isolates for recurring outbreaks without fresh field collection. |
| Multi-Jurisdiction Quality Certification | Manufacturers serving both FDA and EMA markets must maintain parallel quality systems, duplicating documentation overhead that rewards consolidated regulatory umbrellas. |
| Aquaculture Recombinant Capacity Buildout | Norwegian salmon producers drive investment in DNA-based autogenous approaches where commercial vaccines fail to neutralize viral hemorrhagic septicemia variants. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with veterinary diagnostic laboratory directors, livestock integration biosecurity officers, contract manufacturing quality assurance leads, and regulatory affairs specialists at FDA Center for Veterinary Medicine and EMA veterinary medicines divisions. Secondary validation drew from FDA Memorandum 800.116 filings, EMA Veterinary Medicines Regulation 2019/6 implementation guidance, USDA emerging animal disease preparedness program documentation, and WHO Terrestrial Animal Health Code reference frameworks. Bottom-up and top-down triangulation cross-checked pathogen-specific demand estimates against installed fermentation and cell culture capacity across major production hubs.
Calibration against historical diagnostic-to-vaccine turnaround compression and regulatory approval pathway evolution anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application species, end-user procurement sophistication, and production technology capital intensity. CAGRs were derived from pathogen variant emergence patterns, livestock herd dynamics, and regulatory sandbox adoption trajectories. Industry-specific forecast inputs incorporated CRISPR-guided attenuation platform penetration rates and digital strain banking network expansion curves.
Sensitivities concentrate around adjuvant raw material volatility, regulatory divergence between FDA interstate distribution limits and EMA batch traceability standards, and cold chain infrastructure investment gaps in emerging markets. Forecasts reflect assumptions on livestock integration consolidation pace and diagnostic infrastructure subsidy program durability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Blood Plasma Derivatives Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Latin America Biguanide Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Oligonucleotide Therapeutics Market