
 Global Porcine Vaccine Market | 2026-2036
Global Porcine Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Porcine Vaccine Market Foresight
Combination vaccine bundling is repositioning procurement patterns across large-scale pork operations. Zoetis leverages its integrated diagnostics-to-vaccine pipeline to anchor long-term supply contracts with integrated producers. Boehringer Ingelheim sustains dominance in respiratory disease portfolios through captive manufacturing of adjuvant technologies. Elanco competes by extending its reach into emerging markets via veterinary distributor networks.
Porcine vaccines are biological preparations containing inactivated, live attenuated, or recombinant antigenic material designed to induce active immunity against specific swine pathogens, with formulations typically requiring cold-chain storage between two and eight degrees Celsius to preserve immunogenicity. Their primary commercial purpose is to reduce morbidity, mortality, and productivity losses in pig populations while supporting herd health management in intensive production systems. Live attenuated vaccines capture the largest margin pools due to established efficacy profiles and producer familiarity, though recombinant platforms represent the fastest-growing category as nucleic acid delivery technologies mature. DNA vaccines remain structurally underdeveloped in commercial terms but attract R&D capital from specialists seeking differentiation in porcine circovirus and influenza segments.
The USDA and FDA jointly oversee veterinary biologic licensing through the Virus-Serum-Toxin Act, while the EU Green Deal and REACH frameworks impose escalating sustainability and residue-testing burdens on vaccine manufacturers seeking European market access. China's NMPA and Ministry of Agriculture enforce mandatory immunization protocols for classical swine fever that directly shape domestic procurement volumes. Stakeholders must monitor how divergent regulatory timelines for novel platform approvals will fragment competitive access across major producing jurisdictions.
Market Dynamics
Commercial pork producers across China, Germany, and Brazil are consolidating vaccination protocols under integrated health management systems, compressing procurement cycles and favoring suppliers with captive diagnostic-to-vaccine pipelines.
Growth Catalysts
- China's mandatory classical swine fever immunization:The NMPA and Ministry of Agriculture enforce nationwide vaccination protocols that lock in recurring procurement volumes for domestic and licensed foreign manufacturers.
- EU Green Deal veterinary pharmaceutical standards:REACH framework escalation and residue-testing mandates are accelerating farm-level biosecurity investment across member states, expanding addressable demand for premium vaccine formulations.
- Recombinant platform maturation:Nucleic acid delivery technologies are advancing commercial viability for porcine circovirus and influenza segments, opening margin pools previously captured by live attenuated alternatives.
Market Restraints
- Cold-chain infrastructure deficits:Temperature-controlled storage between two and eight degrees Celsius remains unavailable across substantial swine-producing regions in Southeast Asia and sub-Saharan Africa, capping market penetration.
- Adjuvant supply concentration:Captive manufacturing of proprietary adjuvant technologies by dominant respiratory portfolio holders creates supply bottlenecks for second-tier vaccine developers.
- Regulatory timeline divergence:Novel platform approval pathways vary sharply between USDA-Virus-Serum-Toxin Act procedures, EU centralized marketing authorization, and China's NMPA biological licensing, fragmenting competitive access.
Strategic Opportunities
- Vietnam and Philippines biosecurity investment:East Asian pork operations outside China are intensifying disease prevention capital deployment, creating underpenetrated demand for combination vaccine bundling.
- DNA vaccine commercialization:Specialists with differentiated R&D in nucleic acid platforms can capture first-mover position in segments where recombinant technologies remain structurally underdeveloped.
- Diagnostic-to-vaccine integration:Veterinary service providers are consolidating procurement around suppliers offering integrated health monitoring and immunization protocols, rewarding backward integration into diagnostics.
Industry Challenges
- Veterinary immunologist scarcity:Swine-specific vaccine development and field application expertise concentrates among aging specialists in Germany, Denmark, and the US, constraining R&D throughput and technical service capacity.
- Platform switching costs:Live attenuated vaccine familiarity among farm veterinarians creates adoption friction for recombinant and DNA alternatives despite superior efficacy profiles in controlled trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Porcine Vaccine Market |
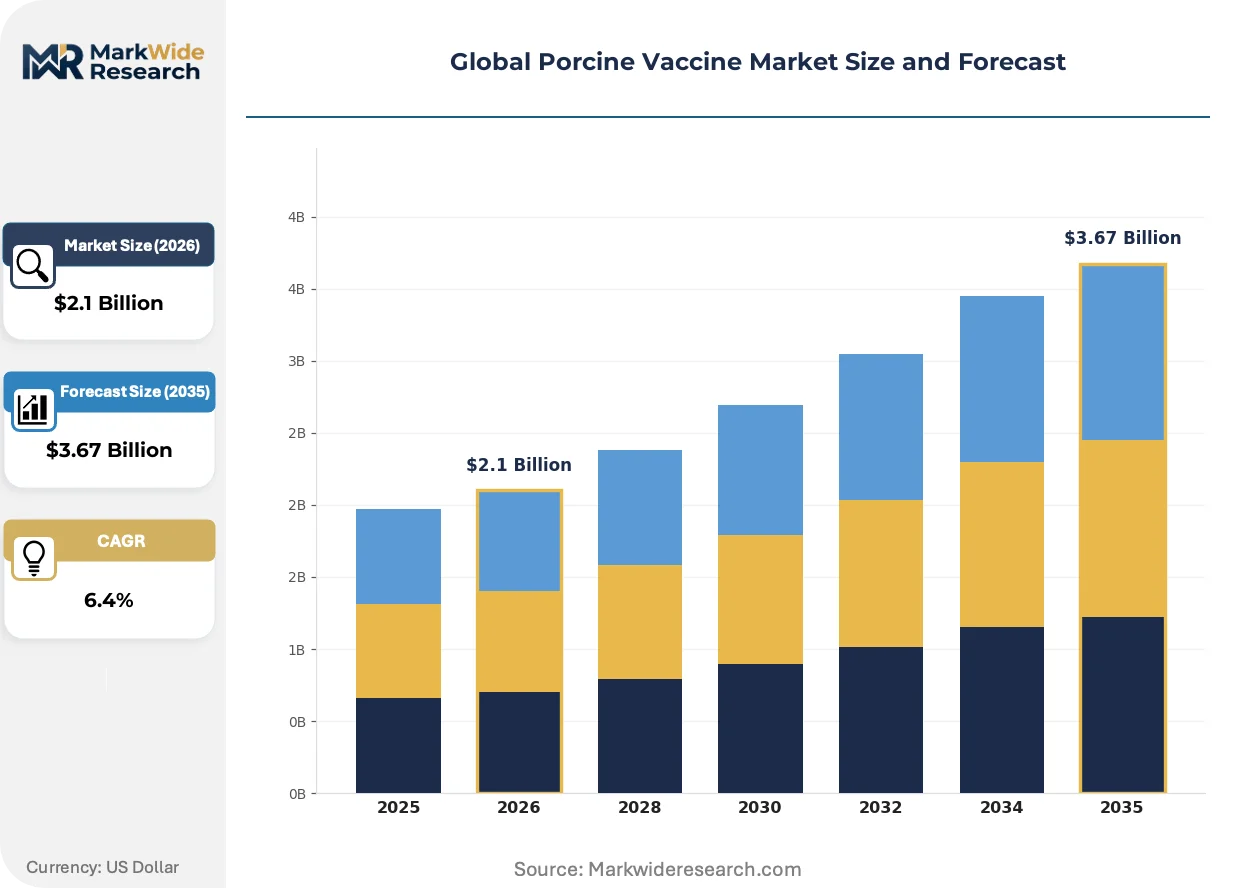
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Inactivated, Live Attenuated, Subunit, Recombinant, DNA Target Disease: Porcine Reproductive and Respiratory Syndrome, Swine Influenza, Classical Swine Fever, Porcine Circovirus, Aujeszky’s Disease End User: Commercial Farms, Smallholder Producers, Veterinary Clinics, Research Institutes Distribution Channel: Direct Sales, Veterinary Distributors, Online Platforms, Agricultural Cooperatives |
| Companies Covered | Zoetis, Boehringer Ingelheim, Elanco, Merck & Co., Inc., Ceva, HIPRA, Phibro Animal Health Corporation, Vetoquinol, Virbac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Porcine Vaccine Market Shifts & Advancements
Platform technology convergence and regulatory stringency are compressing product development timelines while elevating the strategic value of integrated health service capabilities over standalone vaccine supply.
mRNA delivery systems adapted from human pharmaceutical applications are electrifying porcine vaccine development timelines. Large-scale integrated producers in Iowa and North Carolina are piloting nucleic acid platforms for rapid-response influenza strain updates. This technology is electrifying competitive positioning by collapsing the traditional 18-24 month development cycle for variant-specific vaccines into sub-six-month windows.
The EU F-Gas Regulation and REACH chemical restriction frameworks are imposing escalating sustainability burdens on vaccine adjuvant and excipient sourcing. Manufacturers seeking European market access must now document carbon footprint and residue profiles across entire supply chains. Small and mid-tier developers without captive chemical manufacturing are most affected, driving consolidation toward vertically integrated suppliers with in-house formulation capabilities.
Integrated pork producers are unbundling after-sales technical service from product procurement, contracting directly with veterinary diagnostic networks for herd health monitoring. Traditional distributor channels in Brazil and Spain are losing share to direct manufacturer relationships with consolidated operations. This pattern is most visible in Denmark and the Netherlands, where cooperative slaughterhouse networks now centralize vaccination protocol design and negotiate supply contracts at processor rather than farm level.
Global Porcine Vaccine Market Segmentation
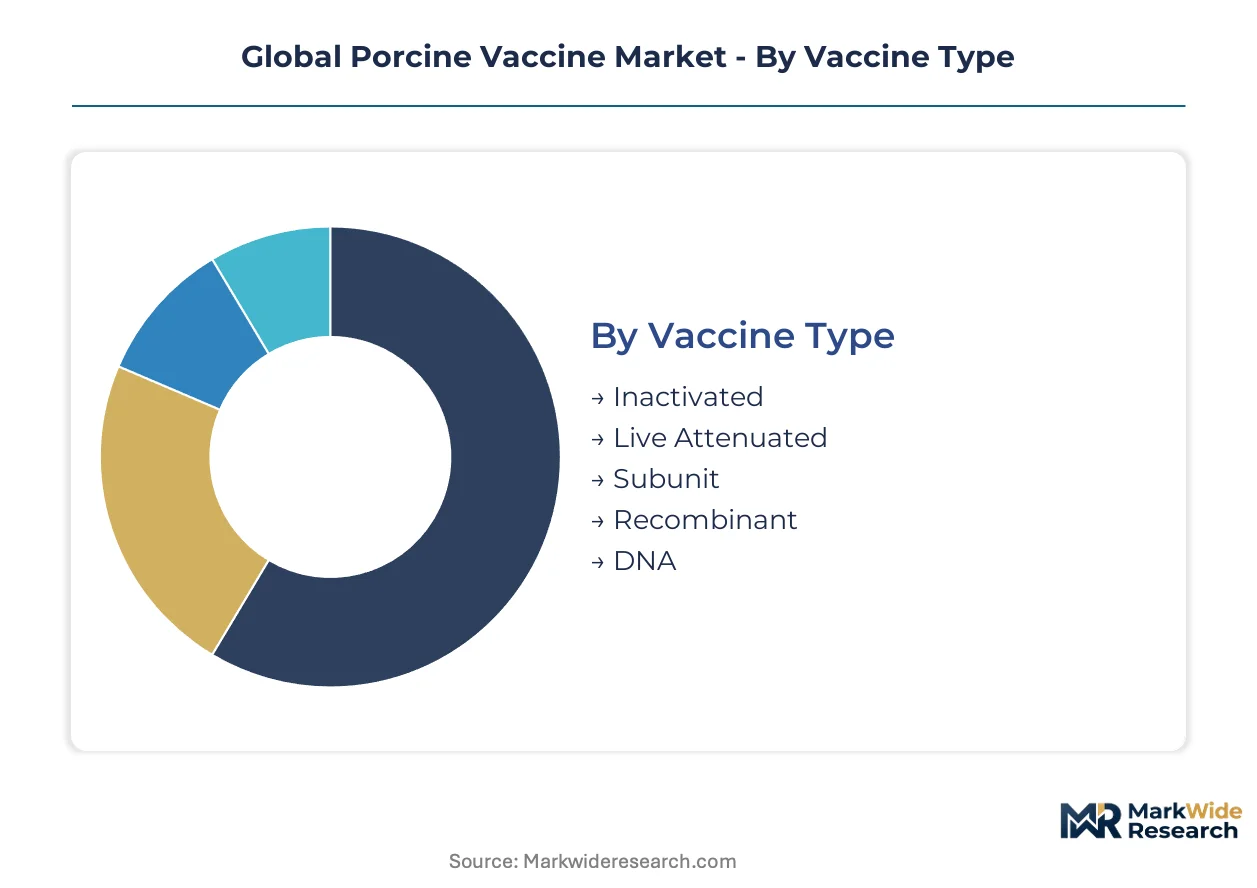
Porcine vaccine procurement patterns diverge sharply across technology platforms, disease targets, and customer scale. Regulatory pathways and cold-chain requirements fragment addressable demand, forcing suppliers to align formulation portfolios with specific end-user capabilities and geographic access constraints.
Vaccine Type:
USDA-Virus-Serum-Toxin Act licensing timelines stretch longest for novel nucleic acid platforms, while inactivated and live attenuated categories benefit from established approval precedents. REACH and EU Green Deal sustainability mandates now require carbon footprint documentation for adjuvant sourcing across all European-bound formulations.
- Inactivated:Pathogen particles rendered non-infectious through chemical or thermal treatment preserve immunogenic epitopes without replication risk. Large-scale commercial farms in Germany and Iowa specify these formulations for breeding stock due to zero shed potential and compatibility with diagnostic differentiation protocols.
- Live Attenuated:Weakened viral strains stimulate robust cellular immunity through limited replication in vaccinated animals. China's NMPA mandates these platforms for classical swine fever nationwide coverage, locking in recurring procurement volumes for domestic manufacturers and licensed importers.
- Subunit:Purified protein antigens eliminate extraneous viral material, reducing adverse reaction incidence in high-value genetic stock.
- Recombinant:Genetically engineered antigens produced in yeast or bacterial expression systems enable rapid strain matching for porcine circovirus variants.
- DNA:Plasmid-encoded antigens delivered intramuscularly trigger endogenous protein synthesis and MHC-I presentation, though commercial scale-up remains constrained by formulation stability challenges.
Live Attenuated sits at the top of the volume ranking, with Recombinant climbing the fastest.
Target Disease:
Cost tiers stratify across disease segments based on mortality impact and regulatory immunization status. Mandatory vaccination protocols compress price elasticity for classical swine fever, while discretionary protection against respiratory complexes permits premium formulation differentiation.
- Porcine Reproductive and Respiratory Syndrome:Arterivirus-induced reproductive failure and respiratory distress in growing pigs drives the largest absolute procurement spend across North American and European commercial operations. Boehringer Ingelheim's captive adjuvant manufacturing and Zoetis's diagnostic integration anchor supply contracts with integrated producers in Iowa, North Carolina, and Denmark.
- Swine Influenza:Type A influenza subtypes H1N1, H1N2, and H3N2 require frequent strain updates to match circulating field variants. mRNA platform pilots in large US operations are collapsing development timelines from eighteen months to under six, reshaping competitive positioning for rapid-response suppliers.
- Classical Swine Fever:Pestivirus eradication programs in EU member states and China's mandatory immunization regime sustain stable demand for C-strain and marker vaccine alternatives.
- Porcine Circovirus:Immunosuppressive PCV2 and emerging PCV3 strains drive subunit and chimeric product development, with recombinant platforms gaining trial adoption in Dutch and Spanish cooperatives.
- Aujeszky's Disease:Pseudorabies eradication in developed markets has shifted demand toward marker vaccines enabling serological differentiation, with residual need concentrated in Eastern European and Southeast Asian regions completing elimination programs.
Porcine Reproductive and Respiratory Syndrome commands the highest revenue concentration, with Swine Influenza expanding most quickly through platform technology displacement.
End User:
Customer type determines service bundling requirements and technical support intensity. Integrated operations negotiate direct manufacturer relationships, while fragmented smallholder bases sustain distributor intermediation despite margin compression.
- Commercial Farms:Operations exceeding five thousand sow equivalents centralize vaccination protocols within enterprise health management systems. These buyers demand diagnostic-to-vaccine integration, cold-chain verification, and batch-level traceability documentation for EU and US export compliance.
- Smallholder Producers:Sub-fifty-sow backyard and village-level operations in Vietnam, Philippines, and sub-Saharan Africa face cold-chain infrastructure deficits capping access to live attenuated and nucleic acid platforms. These producers rely on government subsidy programs and cooperative bulk purchasing for basic inactivated coverage.
- Veterinary Clinics:Mixed-animal practices and swine-specialist service providers administer vaccines as part of comprehensive health programs, capturing margin through technical service rather than product markup alone.
- Research Institutes:Academic and government veterinary laboratories procure experimental formulations and challenge study materials for efficacy evaluation and regulatory dossier preparation.
Commercial Farms generate the dominant procurement volume, with Veterinary Clinics gaining share fastest through diagnostic integration contracts.
Distribution Channel:
Supply concentration varies by channel, with direct sales rewarding captive manufacturing scale and distributor networks enabling emerging market penetration without infrastructure investment.
- Direct Sales:Manufacturer-to-producer relationships eliminate intermediary margins and enable protocol customization for integrated operations. Elanco and Zoetis leverage these channels in Brazil and Spain to displace traditional veterinary distributors.
- Veterinary Distributors:Regional wholesalers maintain cold-chain integrity and credit relationships with fragmented farm bases. These intermediaries retain relevance in Eastern Europe and Latin America where producer consolidation remains incomplete.
- Online Platforms:E-procurement portals serving smallholders and hobby farms facilitate price transparency and small-lot ordering, though temperature-controlled logistics constraints limit product range.
- Agricultural Cooperatives:Slaughterhouse-affiliated purchasing networks in Denmark and the Netherlands centralize vaccination decisions at processor level, negotiating supply contracts covering multiple member farms.
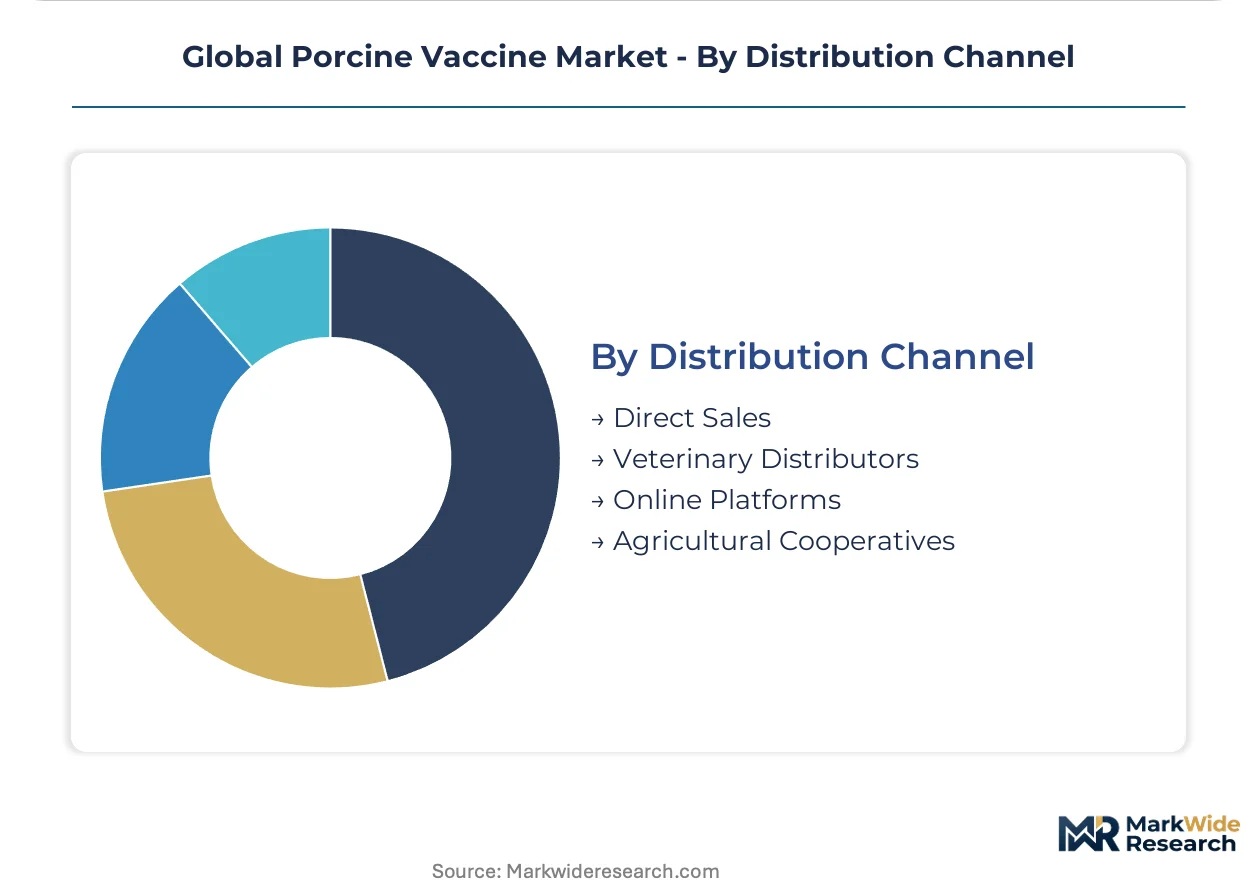
Veterinary Distributors still handle the largest transaction volume, with Direct Sales climbing fastest as producer consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Porcine vaccine production originated in European veterinary laboratories during the mid-twentieth century, with Germany and Denmark pioneering industrial-scale manufacturing for classical swine fever eradication programs. The industry subsequently expanded into North American integrated operations and East Asian commercial farming systems.
China
Commercial pork producers in Guangdong and Sichuan provinces are scaling vaccination protocols under NMPA-mandated classical swine fever immunization. The Ministry of Agriculture enforces nationwide coverage that locks in recurring procurement volumes for domestic manufacturers and licensed foreign suppliers. Biosecurity investment concentrates in the Yangtze River Delta where integrated operations exceed ten thousand sow equivalents.
United States
Iowa and North Carolina host the densest concentrations of large-scale sow operations deploying diagnostic-to-vaccine integration. USDA Virus-Serum-Toxin Act licensing governs all veterinary biologics, with mRNA platform pilots now collapsing influenza strain update cycles. The Corn Belt processing corridor centralizes procurement decisions at slaughterhouse-processor level rather than individual farm level.
Germany
Lower Saxony's cooperative slaughterhouse networks negotiate supply contracts covering multiple member farms under EU Green Deal sustainability mandates. REACH framework escalation requires carbon footprint documentation for adjuvant sourcing across all formulations. Bavarian veterinary service providers are unbundling technical service from product procurement, contracting directly with diagnostic networks.
Brazil
Santa Catarina and Rio Grande do Sul states drive South American demand through integrated export-oriented pork operations. ANVISA regulatory alignment with USDA standards facilitates technology transfer from North American suppliers. Producer consolidation in the southern region is accelerating direct manufacturer relationships that displace traditional veterinary distributor channels.
Vietnam
Dong Nai and Long An provinces in the Mekong Delta are intensifying biosecurity capital deployment for porcine reproductive and respiratory syndrome control. Cold-chain infrastructure deficits in northern highlands regions cap access to live attenuated platforms, favoring thermostable formulation development. Government subsidy programs support cooperative bulk purchasing among sub-fifty-sow backyard producers.
Global Porcine Vaccine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across adjuvant technology and diagnostic integration capabilities. The vendor base concentrates among integrated animal health conglomerates with captive manufacturing infrastructure and captive supply of proprietary formulation technologies. Three strategic archetypes dominate: vertically integrated pharmaceutical conglomerates with human-animal health crossover, regional specialists with deep veterinary service relationships, and emerging platform technology developers seeking nucleic acid differentiation. Competitive moves center on backward integration into diagnostics and strategic partnerships with slaughterhouse-processor networks.
Within the integrated conglomerate tier, Zoetis Inc. and Boehringer Ingelheim GmbH exemplify archetypes combining captive adjuvant manufacturing with diagnostic-to-vaccine pipeline integration. Elanco Animal Health Incorporated occupies a position representing the veterinary-distributor-network expansion model into emerging market penetration. These three entities anchor the competitive structure through differentiated access to integrated producer procurement channels and regulatory dossier capabilities across USDA, EMA, and NMPA jurisdictions.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim |
| Elanco |
| Merck & Co., Inc. |
| Ceva |
| HIPRA |
| Phibro Animal Health Corporation |
| Vetoquinol |
| Virbac |
| Others |
Supply & Pricing Matrix
Performance gaps between live attenuated and recombinant platforms split procurement budgets across premium efficacy tiers and economy coverage levels, with China's NMPA-mandated classical swine fever protocols locking in volume commitments that compress price elasticity for domestic manufacturers while EU REACH documentation burdens inflate formulation costs for European-bound supply.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between integrated producers and captive adjuvant manufacturers, with price differentiation anchored in cold-chain verification capabilities and diagnostic integration depth. Cost compression in standard inactivated tiers intensifies as Brazilian and Vietnamese distributors consolidate purchasing power through cooperative networks. Smallholder producers in Southeast Asia exhibit highest price sensitivity, while Iowa and North Carolina integrated operations prioritize efficacy guarantees over unit cost.
Supply Chain Analysis
Direct-to-producer channels handle hyperscale demand from Denmark and Netherlands cooperative slaughterhouse networks, while veterinary distributors retain relevance in fragmented Eastern European and Latin American farm bases. Manufacturing concentrates in Germany, Denmark, and the United States, with adjuvant chemistry sourcing drawn from captive production at Boehringer Ingelheim and Zoetis facilities. Single-source vulnerability in proprietary formulation technologies creates supply bottlenecks for second-tier developers seeking respiratory disease portfolio entry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value through escalating veterinary pharmaceutical standards, with EU Green Deal REACH frameworks and China's NMPA biological licensing collectively expanding addressable demand for documented carbon footprint and batch-traceable formulations.
For Market Incumbents: To counter recombinant platform displacement of live attenuated margins, Boehringer Ingelheim and Zoetis should deepen captive adjuvant manufacturing scale while securing diagnostic-to-vaccine integration contracts with Iowa and North Carolina processing corridors. Certification investment in EU F-Gas Regulation compliance preserves European market access against REACH escalation.
For New Entrants and Emerging Players: The premium-economy price gap in thermostable formulations for cold-chain-deficient Southeast Asian smallholders offers white-space entry through government subsidy program alignment. Vietnam and Philippines biosecurity capital deployment represents the most penetrable geography, with cooperative bulk purchasing as the viable go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where nucleic acid platform R&D concentrates among aging German and Danish veterinary immunologist networks. Five-to-ten-year viability favors acquisition targets with USDA-Virus-Serum-Toxin Act dossier capabilities and backward integration into diagnostic assay development. Watch mRNA influenza pilot outcomes in US Corn Belt operations as platform technology inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-to-Vaccine Integration | Zoetis anchors long-term supply contracts through integrated health monitoring protocols with Iowa integrated producers. |
| Captive Adjuvant Manufacturing Scale-Up | Boehringer Ingelheim defends respiratory portfolio dominance through proprietary formulation technology control. |
| Thermostable Formulation Development | Specialists unlock Vietnam and Philippines smallholder access by circumventing cold-chain infrastructure deficits. |
| REACH Carbon Footprint Documentation | European market access requires supply chain residue profiling under EU Green Deal sustainability mandates. |
| mRNA Platform Regulatory Dossier Preparation | USDA-Virus-Serum-Toxin Act pathway advancement captures rapid-response influenza strain update demand. |
Research Methodology
Multiple input streams — veterinary service provider interviews, regulatory dossier analysis, and procurement database reconciliation — were combined with secondary validation from USDA biologic licensing records, EMA centralized marketing authorization filings, and China NMPA biological product registrations. Bottom-up farm-level demand estimation and top-down manufacturer capacity assessment were triangulated through conversations with swine health directors at integrated operations, technical service veterinarians, and distributor procurement leads.
Historical volume trajectories were cross-referenced against expert panel inputs across vaccine type, target disease, and end-user scale dimensions over the projection horizon. CAGRs were derived from segmented growth rate modeling incorporating regulatory timeline divergence effects, cold-chain infrastructure expansion curves, and platform technology adoption S-cycles. Forecast inputs included NMPA immunization protocol enforcement patterns and EU F-Gas Regulation compliance cost pass-through assumptions.
Caveats apply where novel platform approval pathway delays or adjuvant supply concentration disruptions could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Supplements Market
Veterinary
Veterinary Software Market
Veterinary
Global Veterinary Holters Market
Veterinary
North America Veterinary Healthcare Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
Clonorchiasis Market
Veterinary
Compression Veterinary Bandages Market
Veterinary
Veterinary Excipients Market
Veterinary
Veterinary Parasiticides Market
Veterinary
Pet Cremation Market