
 CBD Pet Market | 2026-2036
CBD Pet Market Size, Share, and Industry Trends Forecast 2026-2036
CBD Pet Market Intelligence
Multi-source hemp procurement is broadening across the CBD Pet Market as manufacturers diversify beyond single-origin supply chains. cbdMD leverages vertically integrated extraction capabilities to control cannabinoid consistency from biomass through finished goods. Honest Paws anchors its competitive stance through subscription-driven direct-to-consumer channels that sustain recurring revenue. Pet Releaf differentiates via USDA Organic certification and specialized formulations targeting senior dogs with mobility concerns.
CBD pet products comprise hemp-derived cannabidiol formulations designed for non-human mammalian consumption, typically containing less than 0.3% THC by dry weight and processed through CO2 or ethanol extraction methods to ensure safety profiles suitable for companion animals. The primary commercial purpose centers on addressing anxiety, inflammation, pain management, and seizure control in pets without psychoactive effects. Oils dominate current revenue contribution due to dosing flexibility and rapid absorption kinetics, while treats represent the fastest-growing format as palatability engineering improves. Full Spectrum formulations command premium positioning, though isolate-based products attract risk-averse retailers navigating THC testing complexities.
The FDA maintains jurisdiction over CBD pet product safety claims, while the 2018 Farm Bill and subsequent USDA hemp rules govern interstate raw material commerce. State veterinary boards in California, Colorado, and New York impose varying restrictions on clinical recommendation of cannabinoid therapies. The National Animal Supplement Council provides voluntary quality benchmarks that increasingly function as de facto market access requirements. Stakeholders must monitor pending federal rulemaking on CBD as a dietary supplement ingredient, as any reclassification would cascade directly into pet product labeling and marketing permissions.
Market Dynamics
Pet humanization is compressing the traditional veterinary-pharmaceutical gatekeeping model, enabling direct-to-consumer cannabinoid brands to capture margin pools historically reserved for prescription therapeutics.
Growth Catalysts
- State Hemp Legislation:Colorado, California, and New York have enacted frameworks permitting veterinary cannabinoid discourse, reducing physician gatekeeping friction for CBD pet product adoption.
- CO2 Extraction:Supercritical CO2 methods deliver THC-compliant cannabinoid profiles below 0.3% dry weight, satisfying retailer liability concerns and enabling interstate commerce.
- Senior Dog Demographics:Aging companion animal populations in the United States drive demand for mobility-focused formulations targeting inflammation and joint degradation.
Market Restraints
- Biomass Input Volatility:Hemp fiber and seed markets compete for acreage with CBD-specific cultivars, creating raw material cost instability for extractors.
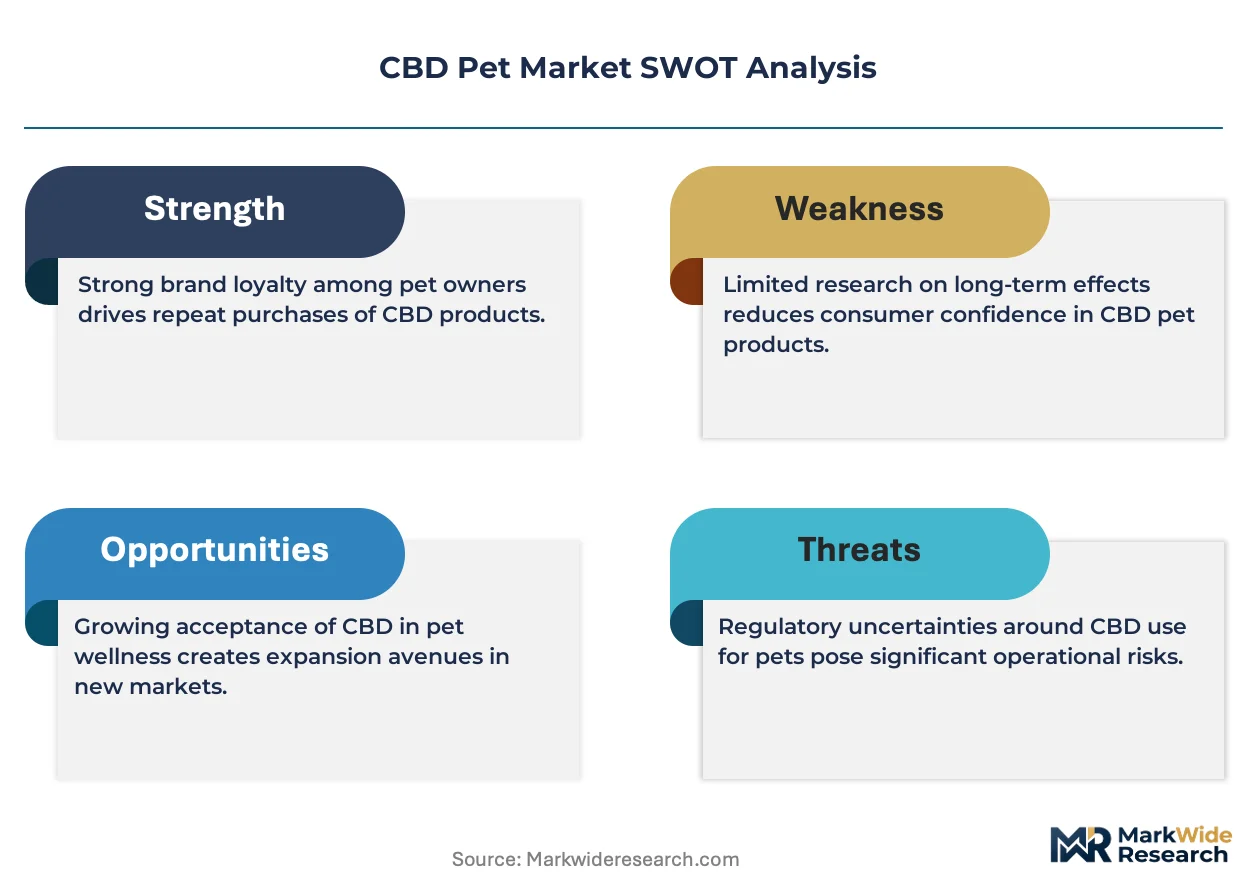
- FDA Jurisdictional Uncertainty:The agency's pending rulemaking on CBD as a dietary supplement ingredient creates labeling and marketing permission ambiguity that freezes retailer expansion.
- Prescription NSAID Substitution:Carprofen and meloxicam remain first-line veterinary recommendations for pain management, limiting cannabinoid trial rates in clinical settings.
Strategic Opportunities
- Subscription Commerce:Direct-to-consumer recurring revenue models bypass veterinary channel friction and capture lifetime value through automated replenishment.
- USDA Organic Certification:Certified organic positioning commands shelf space premiums in pet specialty retail and addresses pesticide residue concerns in hemp sourcing.
- Cat Segment Underpenetration:Feline anxiety and inflammatory conditions represent formulation white space with limited competitive saturation compared to canine SKUs.
Industry Challenges
- Veterinary Education Gap:Clinician training on endocannabinoid system pharmacology remains scarce, limiting recommendation confidence and dosing guidance quality.
- Third-Party Testing Consistency:Certificate of analysis variability across laboratories creates batch-to-batch potency uncertainty that erodes consumer trust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD Pet Market |
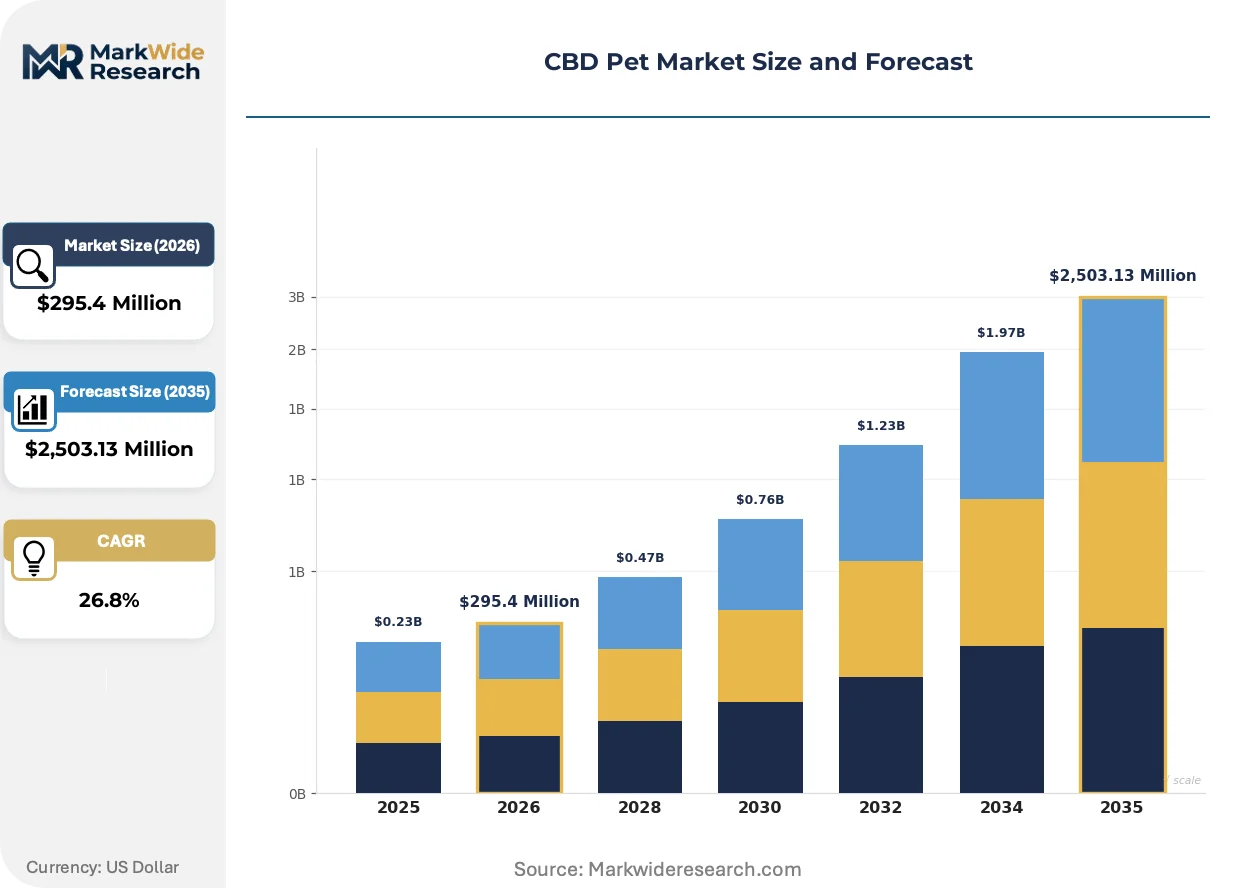
| Market Size in 2026 | $295.4 Million |
| Market Size in 2035 | $2,503.13 Million |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Treats, Capsules, Topicals Formulation: Full Spectrum, Broad Spectrum, Isolate, Water-Soluble Distribution Channel: Online Retail, Specialty Pet Stores, Veterinary Clinics, Grocery Chains Pet Type: Dogs, Cats, Small Animals, Horses |
| Companies Covered | HolistaPet, cbdMD, Honest Paws, Pet Releaf, Diamond CBD, Canna-Pet, Fomo Bones, Canopy Growth Corporation, Joy Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD Pet Market Strategic Shifts & Innovations
Formulation science and channel architecture are converging to reshape how cannabinoid products reach pet owners, with palatability engineering and compliance automation emerging as decisive competitive axes.
Nanoemulsion technology is overtaking conventional oil-based delivery in bioavailability-sensitive applications. The process reduces cannabinoid particle size below 100 nanometers, accelerating absorption kinetics. Premium pet owners in urban United States markets are adopting water-soluble tinctures at pace, compressing the efficacy perception gap between CBD and pharmaceutical alternatives.
The FDA's evolving enforcement discretion posture on hemp-derived ingredients is forcing label claim conservatism across the industry. Manufacturers are retreating from explicit therapeutic language toward structure-function positioning. This regulatory friction most acutely affects topical and transdermal formats, where absorption claims trigger heightened scrutiny.
Palatability engineering investments are redirecting R&D spend toward veterinary flavor masking and texture optimization. Treat formats are displacing oils in trial-to-repeat conversion, particularly among first-time cannabinoid buyers. This shift concentrates visible demand in United States pet specialty retail, where sampling programs and staff education support category education.
CBD Pet Market Segmentation
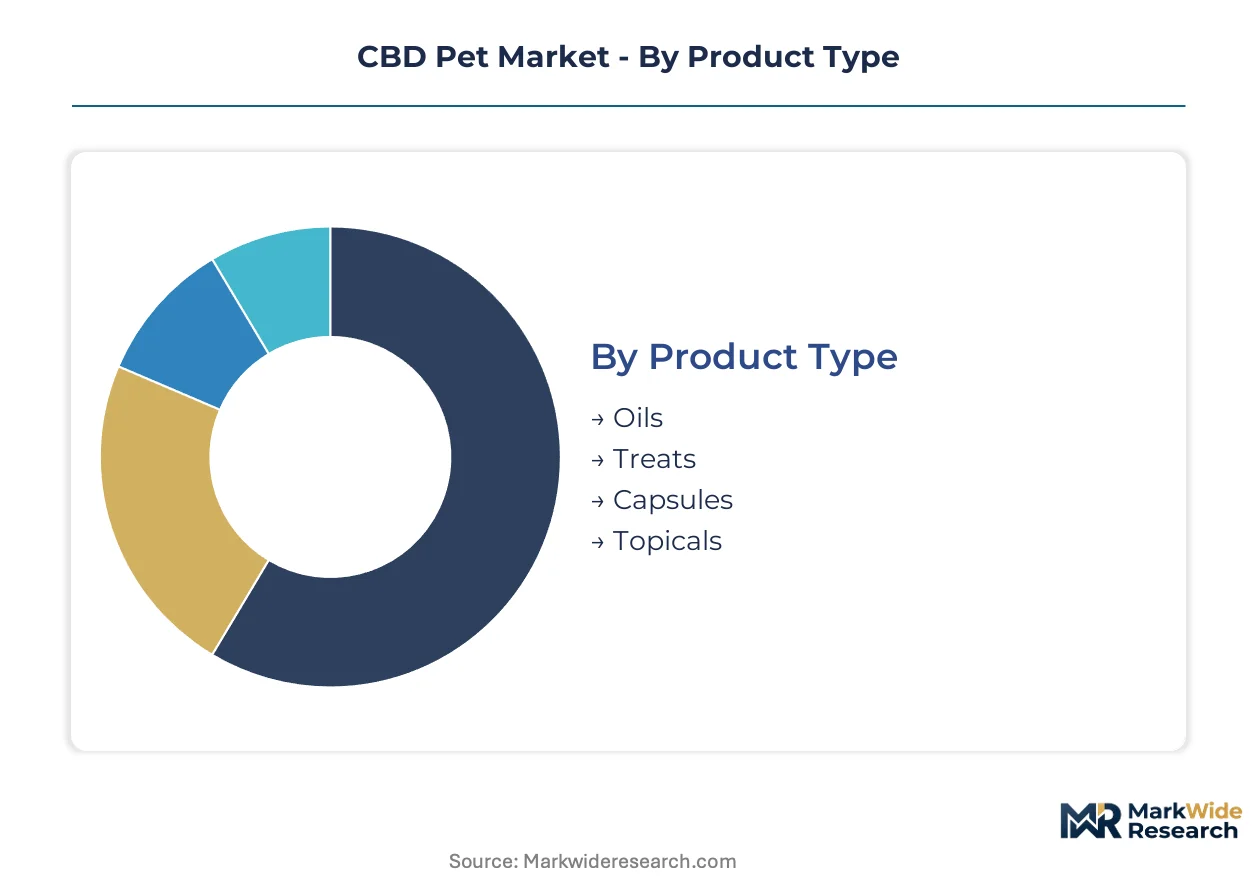
Segmentation in the CBD Pet Market reveals how dosing preferences, cannabinoid chemistry knowledge, and channel access shape purchasing behavior across owner demographics. Manufacturers calibrate formulation investments and distribution partnerships against these divides to capture margin pools and build recurring revenue streams.
Product Type:
Oils command volume leadership through dosing precision, while treats capture premium positioning via palatability engineering and trial-to-repeat conversion mechanics.
- Oils:Liquid formulations delivered via dropper or pump enable milligram-accurate titration for anxiety and inflammation protocols. Demand concentrates in United States urban markets where pet owners self-direct dosing without veterinary supervision, driven by sublingual absorption speed and SKU versatility across weight classes.
- Treats:Baked or extruded delivery vehicles mask hemp terpene bitterness through poultry, peanut, or salmon flavor systems. Palatability investments from Honest Paws and Pet Releaf are displacing oils in first-time buyer conversion, particularly among suburban dog owners seeking administration convenience.
- Capsules:Pre-measured gelatin or vegetable-based shells suit multi-pet households and travel contexts requiring spill-proof transport.
- Topicals:Transdermal balms and sprays target localized inflammation in senior dogs, though FDA claim scrutiny limits explicit therapeutic marketing.
Today's leader: Oils. Tomorrow's challenger: Treats.
Formulation:
Chemistry sophistication separates risk-tolerant early adopters from compliance-conscious retailers navigating THC testing protocols.
- Full Spectrum:Whole-plant extracts retaining trace cannabinoids and terpenes below 0.3% THC threshold leverage entourage effect hypotheses for efficacy positioning. Premium pet specialty retailers in Colorado and California stock these SKUs despite batch-to-batch variability concerns.
- Isolate:Crystalline CBD stripped of all other hemp compounds attracts veterinary clinics and mass-market chains requiring guaranteed THC-negative testing for liability insulation.
- Broad Spectrum:THC-free formulations preserving minor cannabinoids bridge efficacy perception and compliance requirements for risk-moderate buyers.
- Water-Soluble:Nanoemulsion or liposomal technologies achieving sub-100 nanometer particle size enable beverage and wet food integration with accelerated bioavailability claims.
Isolate anchors current shelf placement security. Full Spectrum climbs fastest on efficacy differentiation.
Distribution Channel:
Channel selection determines margin capture versus education burden, with direct-to-consumer models bypassing veterinary gatekeeping friction entirely.
- Online Retail:Subscription-driven replenishment platforms sustain lifetime value through automated delivery and dosage reminder systems. cbdMD and Honest Paws anchor competitive position here.
- Specialty Pet Stores:Independent and chain pet retailers provide sampling programs and staff training that accelerate category education among first-time cannabinoid buyers.
- Veterinary Clinics:Clinical recommendation channels remain constrained by state board restrictions on cannabinoid discourse, limiting penetration despite high trust transfer.
- Grocery Chains:Mass-market placement requires isolate-based formulations with conservative labeling to satisfy corporate risk management protocols.
Online Retail owns velocity. Specialty Pet Stores own education. Veterinary Clinics own unrealized authority.
Pet Type:
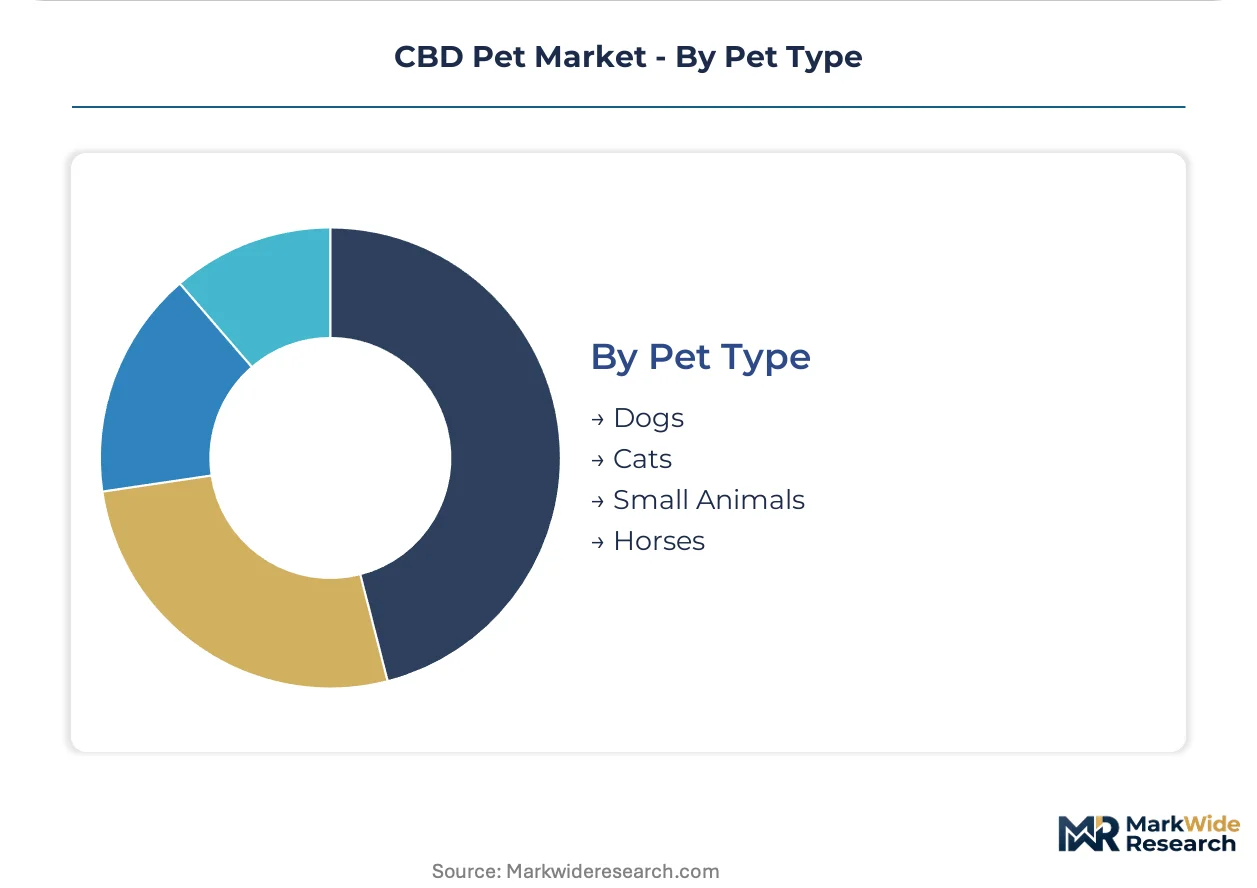
Species-specific physiology and owner spending patterns create divergent addressable market profiles across the companion animal spectrum.
- Dogs:Larger body mass enables meaningful per-dose revenue while aging demographics in the United States drive mobility and anxiety formulation demand. State hemp legislation in California and Colorado permits veterinary cannabinoid discussion, reducing adoption friction.
- Cats:Feline endocannabinoid system research lags canine studies, creating formulation white space with limited competitive saturation despite comparable anxiety prevalence.
- Small Animals:Rabbits, ferrets, and pocket pets represent micro-dose volume with specialized metabolic constraints limiting SKU development priority.
- Horses:Equine applications concentrate in performance and senior care segments with dosing scale an order of magnitude above companion animals, attracting specialized extractors.
Dogs dominate revenue concentration. Cats represent the steepest expansion trajectory for formulation-first entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping CBD pet product manufacturing as producers migrate toward jurisdictions with clearer hemp frameworks and lower compliance friction. Cost-of-compliance gaps between federal ambiguity and state-level clarity drive facility siting decisions.
United States
Dog owners in California, Colorado, and New York drive category velocity through direct-to-consumer subscription channels. The FDA maintains enforcement discretion over cannabinoid safety claims while the 2018 Farm Bill governs interstate hemp commerce. Denver and Los Angeles anchor extraction and formulation clusters where CO2 processing facilities cluster near biomass cultivation zones.
Canada
Health Canada and the PMRA regulate veterinary health products with stricter novel ingredient approval pathways than south of the border. Licensed cannabis producers in Ontario and British Columbia leverage existing extraction infrastructure to supply pet-specific SKUs. Toronto-based formulation labs serve cross-border private label contracts for US brands seeking THC-compliant isolate supply.
Germany
The BfArM and EFSA frameworks classify CBD as a novel food ingredient, creating veterinary product registration complexity that slows market entry. Pet humanization trends in Bavaria and North Rhine-Westphalia sustain demand for premium companion animal supplements. Munich specialty retailers stock imported full-spectrum oils through grey-market channels while domestic producers await regulatory harmonization.
United Kingdom
The FSA novel food authorization process has cleared select CBD suppliers for human consumption, creating spillover legitimacy for pet product positioning. London and Southeast England concentrate e-commerce fulfillment infrastructure serving EU markets post-Brexit. Veterinary practices in Greater Manchester participate in cannabinoid education pilots sponsored by supplement distributors.
Australia
The TGA schedules CBD as a prescription medicine for humans, forcing pet product marketers toward Schedule 4 veterinary exemption pathways. Sydney and Melbourne house the dominant import and distribution nodes for hemp-derived ingredients sourced from North American suppliers. Queensland-based equine specialists drive off-label cannabinoid experimentation in performance horse segments.
CBD Pet Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue USDA Organic certification and feline formulation white space. The vendor base spans vertically integrated extractors, subscription-platform direct-to-consumer brands, and private-label manufacturers serving mass-market retail. Three archetypes dominate: CO2 extraction specialists controlling biomass-to-finished-goods pipelines; digital-native brands capturing lifetime value through automated replenishment; and certified organic formulators commanding shelf space premiums. Competitive moves concentrate on backward integration into captive hemp supply and palatability engineering investments displacing oils with treat formats.
Within the vertically integrated tier, cbdMD anchors extraction-capable positioning while Honest Paws exemplifies subscription-driven recurring revenue architecture. Pet Releaf occupies the certified organic specialization vector. These three entities represent distinct strategic postures without implying specific market share or operational scale claims.
| Leading Market Players |
|---|
| HolistaPet |
| cbdMD |
| Honest Paws |
| Pet Releaf |
| Diamond CBD |
| Canna-Pet |
| Fomo Bones |
| Canopy Growth Corporation |
| Joy Organics |
| Others |
Cost & Logistics Intelligence
Captive hemp cultivation and in-house CO2 extraction anchor pricing power for vertically integrated CBD pet manufacturers, compressing input cost volatility while enabling premium positioning against toll-processing competitors dependent on spot biomass markets. This upstream control insulates margin structures from the acreage competition between fiber, seed, and cannabinoid-specific cultivars that destabilizes non-integrated extractors.
Pricing Analysis
Direct-to-consumer subscription margins bypass distributor markups and retail slotting fees, enabling price positioning that undercuts veterinary channel equivalents while preserving profitability. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified formulations from conventional full-spectrum SKUs and isolate-based economy lines. Cost compression in the standard tier intensifies because biomass input volatility feeds through toll-processing contracts. Mass-market grocery buyers exhibit highest price sensitivity, while urban pet specialty consumers absorb premiums for nanoemulsion bioavailability claims.
Supply Chain Analysis
USDA hemp rules mandating domestic cultivation compliance reshape sourcing toward United States, Canada, and Netherlands suppliers with certified THC-testing protocols. CBD-specific biomass, supercritical CO2 extraction equipment, and third-party laboratory certification draw from agricultural, precision manufacturing, and analytical services sectors. Single-source vulnerability concentrates in Colorado and Kentucky biomass regions exposed to climate yield variability. Distribution runs through direct-to-consumer fulfillment centers, pet specialty retail warehousing, and veterinary clinic wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CBD Pet Market functions as a stable compounder where recurring subscription revenue and pet humanization demographics generate predictable cash flow expansion without cyclical exposure.
For Market Incumbents: Anticipate FDA dietary supplement reclassification by building isolate-based SKU buffers and conservative label claim archives that satisfy mass-market retailer risk protocols. Defensive consolidation through captive hemp acreage in Kentucky and Colorado secures biomass priority access against toll-processing competitors. Subscription platform retention engineering represents the critical lever for lifetime value protection against emerging direct-to-consumer entrants. For New Entrants and Emerging Players: State hemp legislation in Colorado and California opens a window for veterinary education partnerships that bypass clinical recommendation friction. Feline formulation white space offers the most penetrable segment with limited incumbent R&D investment and comparable anxiety prevalence to canine populations. Direct-to-consumer sampling programs through pet specialty retail accelerate trial-to-repeat conversion without veterinary channel gatekeeping. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated mid-cap extractors because fragmented biomass sourcing and inconsistent third-party testing create scale advantages for consolidated quality control platforms. Acquisition targets should demonstrate captive hemp supply, subscription revenue concentration above threshold levels, and USDA Organic certification pipeline readiness. The signal to watch is FDA rulemaking clarity on CBD dietary supplement classification, which would trigger mass-market retail expansion and valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Hemp Cultivation | Colorado and Kentucky acreage control insulates biomass cost volatility from fiber-seed market competition. |
| USDA Organic Certification Pipeline | Certified organic positioning commands shelf space premiums in pet specialty retail and addresses pesticide residue concerns. |
| Nanoemulsion Technology Investment | Sub-100 nanometer particle size enables water-soluble formulations with accelerated absorption kinetics for urban premium buyers. |
| Subscription Platform Infrastructure | Automated replenishment and dosage reminder systems capture lifetime value while bypassing veterinary channel friction. |
| Feline Formulation R&D Expansion | Limited competitive saturation in cat anxiety and inflammatory applications creates first-mover advantage for efficacy-established entrants. |
Research Approach
Bottom-up pet owner demand modeling reconciled against top-down hemp biomass and extraction capacity tracking forms the analytical core. Primary interviews with veterinary clinic procurement managers, pet specialty retail category buyers, CBD manufacturer supply chain directors, and state agricultural extension hemp specialists combined with secondary validation. FDA enforcement discretion memoranda, USDA hemp cultivation reports, state veterinary board regulatory filings, and National Animal Supplement Council quality benchmarks anchored supply-side and compliance dimensions.
Historical trendline analysis of cannabinoid product adoption curves, subscription commerce penetration rates, and pet humanization expenditure indices informed projection frameworks across the analysis window. Segmentation dimensions modeled include product format, cannabinoid chemistry profile, distribution channel architecture, and companion animal species. CAGRs derived from regression analysis of demographic aging patterns, state legislative expansion trajectories, and veterinary discourse permission trends. Forecast inputs incorporated senior dog population growth and palatability engineering investment cycles.
Revisions become necessary when FDA dietary supplement reclassification, interstate hemp testing standard harmonization, or veterinary curriculum endocannabinoid education mandates materialize. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and biomass yield stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Parasiticides Market
Veterinary
Veterinary Respiratory Disease Treatment Market
Veterinary
Global Veterinary Electrosurgery Market
Veterinary
Global Veterinary Holters Market
Veterinary
Global Cattle Vaccines Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
Global Veterinary Telehealth Market
Veterinary
Veterinary Ultrasound Market
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Pet Light Therapy Devices Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Clonorchiasis Market
Veterinary
Europe Dog Dewormers Market
Veterinary
Canine Separation Anxiety Treatment Market