
 Influenza Home Testing Market | 2026-2036
Influenza Home Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Influenza Home Testing Market Foresight
Isothermal amplification is narrowing the performance gap between laboratory-grade PCR and consumer-accessible rapid diagnostics, enabling molecular accuracy at ambient temperatures without thermal cyclers. Abbott Laboratories leverages its established point-of-care infrastructure to sustain channel dominance across retail pharmacy networks. QuidelOrtho competes through integrated manufacturing scale that anchors cost positions in lateral flow production. Thermo Fisher Scientific specializes in reagent supply ecosystems that extend its influence into third-party kit development.
Influenza home testing encompasses self-administered diagnostic platforms that detect viral antigens, nucleic acids, or host antibodies from nasal swabs or saliva specimens, typically delivering results within ten to thirty minutes through visual readout or digital connectivity. These devices employ immunoassay chemistry or nucleic acid amplification to enable pre-clinical infection confirmation, reducing emergency department burden and accelerating antiviral treatment initiation. Rapid test kits occupy the dominant volume position due to established consumer familiarity and minimal training requirements, though digital test devices represent the fastest-expanding margin pool as connectivity features enable telehealth integration and epidemiological data capture. PCR test kits retain premium positioning for symptomatic households seeking laboratory-comparable sensitivity during peak seasonal circulation.
FDA Emergency Use Authorization pathways and subsequent de novo clearance standards shape product development timelines and evidentiary requirements for US market entry, while CE marking under the EU In Vitro Diagnostic Regulation governs commercial access across European member states. Japan's PMDA and MHLW enforce localized clinical validation protocols that filter which platforms achieve national reimbursement listing. Stakeholders must monitor evolving interoperability standards between home testing devices and electronic health record systems, as data portability becomes a decisive procurement criterion for integrated care networks and payer formulary inclusion.
Market Dynamics
Isothermal amplification chemistry is collapsing the cost and complexity barriers that historically separated laboratory PCR from consumer diagnostics, forcing incumbents to defend margin positions against molecular entrants.
Growth Catalysts
- Post-pandemic health monitoring habits:Households in the United States, Germany, and Japan now maintain routine diagnostic inventories, sustaining baseline demand beyond seasonal peaks.
- FDA de novo clearance pathways:The streamlined regulatory route for over-the-counter molecular tests compresses time-to-market for novel platforms.
- Telehealth integration mandates:Payer networks increasingly require digital connectivity for remote consultation eligibility, pulling connected devices into formularies.
Market Restraints
- Reimbursement fragmentation:Germany's BfArM and Japan's MHLW maintain divergent evidence standards, forcing manufacturers to duplicate clinical programs.
- Raw material concentration:Nitrocellulose membrane supply concentrates among Asian specialty chemical producers, exposing lateral flow manufacturers to input volatility.
- Performance ceiling of antigen chemistry:Lateral flow sensitivity plateaus below molecular methods during low-viral-load early infection windows.
Strategic Opportunities
- Underpenetrated French and Spanish households:Southern European markets lack the retail pharmacy density and direct-to-consumer infrastructure anchoring US and German adoption.
- Workplace screening programs:Employer-sponsored occupational health contracts represent a channel bypassing retail pharmacy gatekeepers.
- CRISPR-based detection convergence:Integration of gene-editing recognition with isothermal amplification promises specificity gains without thermal cycler hardware.
Industry Challenges
- Multiplex assay development complexity:Simultaneous influenza A/B and respiratory syncytial virus detection demands extended analytical validation timelines under FDA guidance.
- Interoperability standardization delays:HL7 FHIR implementation gaps between home testing devices and electronic health record systems obstruct seamless data portability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Influenza Home Testing Market |
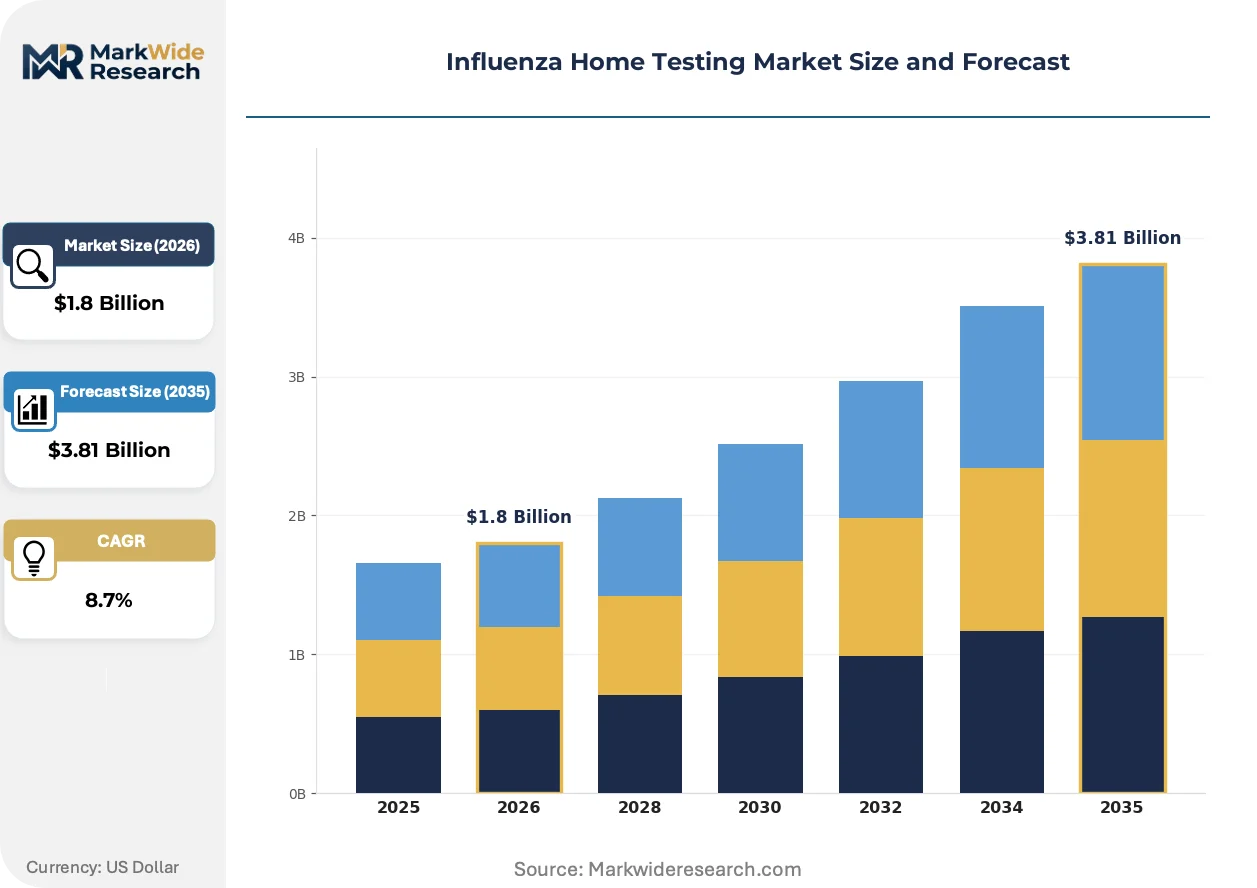
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Test Kits, PCR Test Kits, Antibody Test Kits, Digital Test Devices Technology: RT-PCR, Lateral Flow, Isothermal Amplification, Microfluidics End User: Households, Clinics, Pharmacies, Remote Monitoring Services Distribution Channel: Online Retail, Drugstores, Supermarkets, Medical Supply Stores |
| Companies Covered | Abbott Laboratories, Quidel Corporation, Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd, Becton, Dickinson and Company, QuidelOrtho, Lucira Health, Ellume, Cue Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Influenza Home Testing Market Shifts & Advancements
Digital connectivity and molecular miniaturization are converging to redefine performance expectations and commercial access models across consumer diagnostics.
Loop-mediated isothermal amplification is collapsing the sensitivity gap between rapid antigen tests and laboratory PCR. Symptomatic households seeking diagnostic certainty during early infection windows are adopting these platforms at accelerating rates. The technology is collapsing the traditional trade-off between speed and accuracy that has structured category segmentation for decades.
The EU In Vitro Diagnostic Regulation's performance surveillance requirements are tightening post-market accountability for CE-marked devices. Manufacturers must now maintain ongoing clinical evidence generation rather than front-loading validation studies. Lateral flow producers serving European markets are responding by building internal clinical affairs capabilities previously outsourced to contract research organizations.
Direct-to-consumer subscription models are displacing retail pharmacy as the primary acquisition channel for repeat purchasers. Urban households in Tokyo prefectures and select German metropolitan regions now prefer automated replenishment tied to influenza surveillance alerts. This behavioral shift concentrates customer lifetime value with platforms owning the digital relationship rather than the physical distribution endpoint.
Influenza Home Testing Market Segmentation
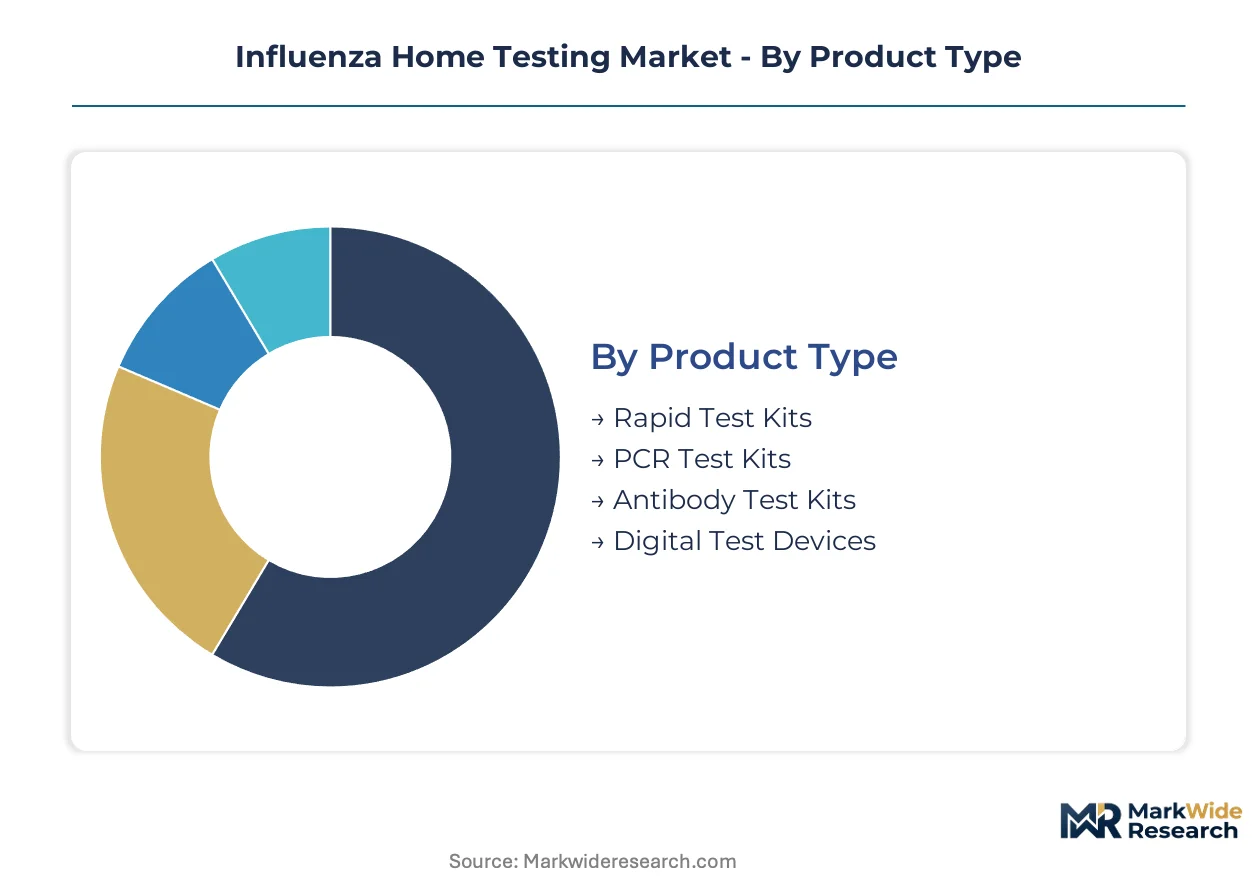
Influenza home testing spans multiple technical platforms and access pathways that shape user experience, clinical utility, and commercial economics. Segmentation reveals where molecular accuracy commands premium positioning versus where convenience and cost drive mass adoption.
Product Type:
The use-case spectrum stretches from symptomatic households seeking immediate results to precision-minded consumers demanding laboratory-grade sensitivity.
- Rapid Test Kits:Lateral flow immunoassays deliver visual results in ten to fifteen minutes without instrumentation. Households in the United States stock these as seasonal preparedness staples, sustaining baseline demand through retail pharmacy networks.
- PCR Test Kits:Nucleic acid amplification platforms requiring sample processing at home or mail-in laboratory analysis. Symptomatic users during early infection windows favor these for sensitivity during low-viral-load phases, though workflow friction limits repeat purchase frequency.
- Antibody Test Kits:Serological detection of post-infection immune response, typically via fingerstick blood samples. Post-pandemic curiosity about prior exposure maintains niche demand, though clinical utility for acute diagnosis remains limited.
- Digital Test Devices:Connected hardware platforms integrating optical readers with smartphone applications. Telehealth reimbursement frameworks in Germany and Japan are pulling these into formularies as eligible consultation prerequisites.
Established volume favors rapid test kits; emerging adoption favors digital test devices.
Technology:
Cost tier separates thermal cycler-dependent methods from ambient-temperature chemistry that collapses infrastructure requirements.
- RT-PCR:Reverse transcription polymerase chain reaction remains the sensitivity benchmark, utilizing thermal cycling to amplify viral RNA. Regulatory validation burdens and hardware costs constrain home deployment to premium kit formats.
- Lateral Flow:Capillary-driven immunoassay strips with visual endpoint detection dominate unit economics and manufacturing scale. Nitrocellulose membrane supply concentration in Asian chemical producers exposes producers to input volatility.
- Isothermal Amplification:Loop-mediated amplification and related chemistries achieve PCR-comparable sensitivity at constant temperature. Japanese prefectures and German metropolitan regions show accelerating uptake as FDA de novo pathways validate over-the-counter molecular claims.
- Microfluidics:Integrated cartridge systems automating sample preparation and detection in disposable formats. Development timelines concentrate in venture-backed platforms targeting multiplex respiratory panels beyond single-pathogen detection.
Mature manufacturing favors lateral flow; steepest expansion trajectory belongs to isothermal amplification.
End User:
Customer type determines whether procurement emphasizes convenience, clinical integration, or occupational compliance.
- Households:Individual consumers purchasing through retail or direct-to-consumer channels for personal health monitoring. Post-pandemic habit persistence in the United States, Germany, and Japan sustains inventory-based purchasing beyond acute symptomatic need.
- Clinics:Outpatient facilities utilizing home testing for pre-visit screening or post-discharge monitoring. Workflow efficiency gains drive adoption where telehealth integration reduces unnecessary in-person consultations.
- Pharmacies:Retail dispensaries offering point-of-sale testing with pharmacist-guided result interpretation. European pharmacy networks leverage professional credibility to differentiate from pure retail channels.
- Remote Monitoring Services:Subscription-based health platforms integrating home testing with continuous surveillance and alert systems. Tokyo prefectures demonstrate concentrated uptake where aging populations favor managed care relationships over episodic purchasing.
Volume concentration sits with households; margin expansion concentrates in remote monitoring services.
Distribution Channel:
Geography of fulfillment shapes customer acquisition economics and repeat purchase mechanics.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling subscription replenishment. Urban Japanese households and select German metropolitan regions prefer automated delivery tied to surveillance alerts.
- Drugstores:Pharmacy chains anchoring impulse and seasonal preparedness purchasing in the United States. Shelf placement and pharmacist recommendation drive trial among first-time users.
- Supermarkets:Mass merchandisers incorporating testing into general health and wellness aisles. Price positioning and co-merchandising with cold remedies sustain visibility during circulation peaks.
- Medical Supply Stores:Professional distributors serving occupational health programs and institutional purchasers. Bulk contracting and compliance documentation requirements filter which platforms achieve listing.
Physical retail anchors current volume; digital channels are gaining share fastest among repeat purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German-manufactured diagnostic components supply assembly operations across North American and Japanese consumer markets, establishing a trade corridor that channels European precision engineering into high-volume overseas distribution networks.
United States
Retail pharmacy chains anchor household purchasing patterns, while direct-to-consumer platforms capture subscription-based repeat orders. FDA de novo clearance pathways compress development timelines for over-the-counter molecular tests. Boston and San Francisco Bay Area clusters concentrate venture-backed digital health platforms integrating home diagnostics with telehealth infrastructure.
Germany
BfArM reimbursement frameworks determine commercial viability for connected diagnostic devices entering statutory health insurance formularies. The EU In Vitro Diagnostic Regulation's performance surveillance requirements tighten post-market accountability for CE-marked devices. Berlin and Munich metropolitan regions host clinical affairs capabilities serving European validation protocols.
Japan
Urban prefectures demonstrate concentrated uptake of subscription-based health platforms among aging populations favoring managed care relationships. PMDA and MHLW enforce localized clinical validation protocols filtering national reimbursement listing. Tokyo and Osaka clusters integrate home testing data with electronic health record systems for remote monitoring services.
United Kingdom
Pharmacy networks leverage professional credibility to differentiate point-of-sale testing from pure retail channels, sustaining visibility during seasonal circulation peaks. MHRA operates recognition routes for devices holding CE marks or FDA clearances, streamlining market entry. London and Southeast England concentrate telehealth platform development linking diagnostic results to NHS consultation pathways.
Influenza Home Testing Market Competitive Landscape
On the supply side, the industry is consolidating around established diagnostic conglomerates with point-of-care infrastructure, while molecular specialists and digital health entrants challenge margin positions through technology differentiation. Three archetypes dominate: diversified life science conglomerates leveraging channel scale, pure-play diagnostic specialists optimizing manufacturing cost positions, and venture-backed digital platforms integrating connectivity features. Competitive maneuvering concentrates on strategic partnerships with telehealth providers and portfolio diversification into multiplex respiratory panels.
Within the diversified conglomerate tier, Abbott Laboratories and Thermo Fisher Scientific occupy positions anchoring retail pharmacy and reagent supply ecosystems respectively. QuidelOrtho sits within the diagnostic specialist archetype, exemplifying integrated manufacturing scale in lateral flow production. These three entities represent the dominant competitive anchors shaping category economics.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Quidel Corporation |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd |
| Becton, Dickinson and Company |
| QuidelOrtho |
| Lucira Health |
| Ellume |
| Cue Health |
| Others |
Supply & Pricing Matrix
The trans-Pacific freight corridor linking Asian nitrocellulose membrane producers to North American lateral flow assembly plants transmits raw material cost volatility directly into downstream pricing tiers, forcing manufacturers to absorb margin compression or pass through to retail pharmacy chains and direct-to-consumer platforms.
Pricing Analysis
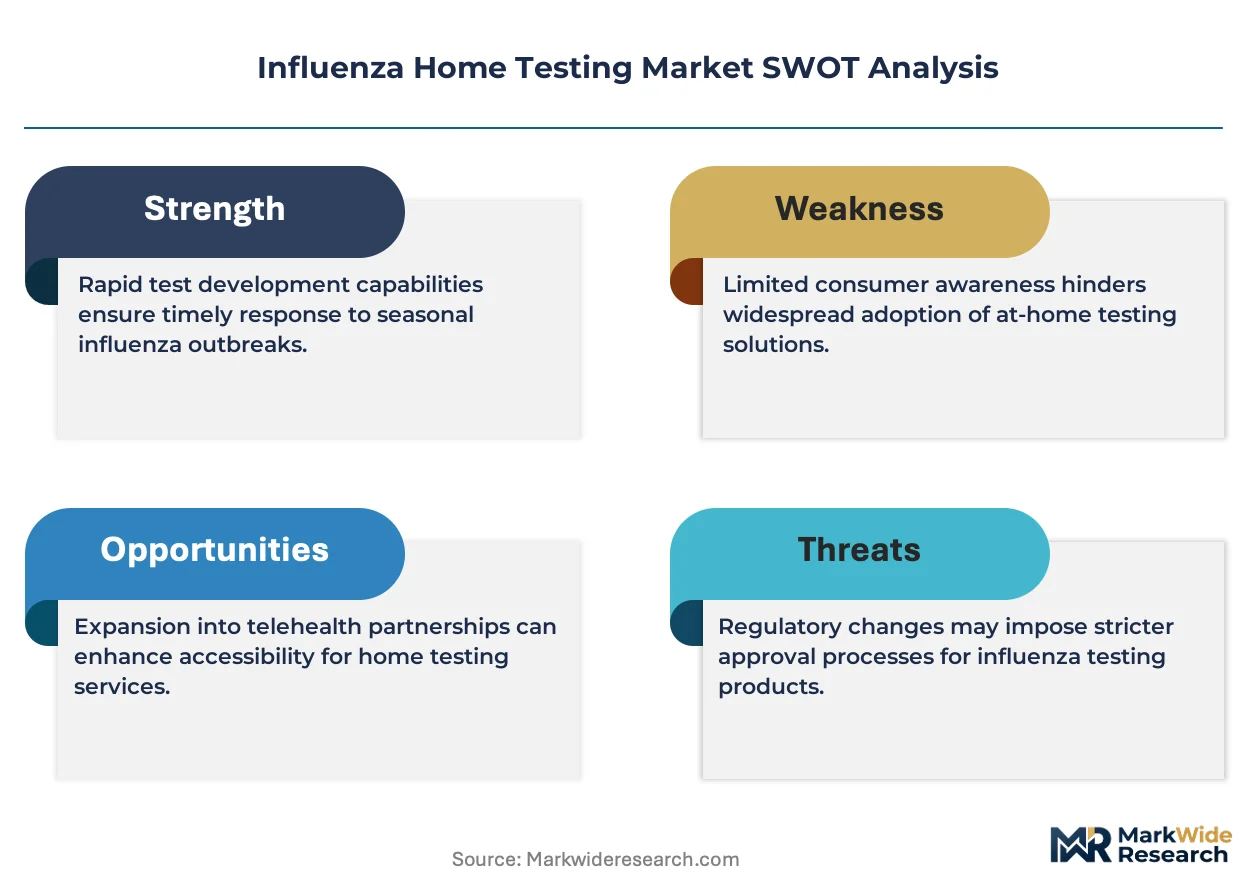
The technology-generation pricing gap between legacy lateral flow strips, emerging isothermal amplification kits, and laboratory-comparable PCR home platforms structures a three-tier pricing architecture across premium, standard, and economy levels. Certification grade under FDA de novo pathways and CE marking under the EU In Vitro Diagnostic Regulation differentiate price bands, with telehealth-integrated digital devices commanding subscription premiums. Cost compression in economy-tier rapid antigen tests is intensifying because of nitrocellulose membrane supply volatility and manufacturing scale competition between QuidelOrtho and Abbott Laboratories. Households in the United States exhibit highest price sensitivity for repeat seasonal purchases, while remote monitoring services in Japanese prefectures demonstrate lowest sensitivity due to reimbursement anchoring.
Supply Chain Analysis
Extended payment terms from Asian specialty chemical producers to European and North American diagnostic assemblers have tightened working capital requirements across the value chain. Nitrocellulose membrane production concentrates in China and South Korea, while precision plastic molding for cartridge housings sources from Germany and Japan. Lateral flow chemistry depends on antibody reagent supply from the United States and European Union member states. Single-source vulnerability in nitrocellulose substrate exposes producers to input disruption during regional logistics congestion. Distribution runs through retail pharmacy chains for impulse purchasing, direct-to-consumer platforms for subscription replenishment, and medical supply distributors for occupational health bulk contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of clinical affairs capabilities capable of navigating simultaneous FDA de novo, CE marking, and Japan PMDA validation protocols concentrates strategic advantage with platforms that have built internal regulatory infrastructure rather than outsourcing to contract research organizations.
For Market Incumbents: Entrench channel control through exclusive formulary positioning with retail pharmacy chains and direct-to-consumer platforms, while backward integration into nitrocellulose membrane supply hedges raw material volatility from Asian producers. Molecular entrants leveraging isothermal amplification threaten lateral flow margin positions; defend through certification investment in multiplex respiratory panels combining influenza A/B with respiratory syncytial virus detection. For New Entrants and Emerging Players: Build out clinical affairs capabilities in Berlin and Tokyo metropolitan regions to serve European and Japanese validation protocols simultaneously, bypassing the duplication burden that fragments incumbent resources. Southern European households in France and Spain represent the most penetrable geography given underdeveloped retail pharmacy density. Target workplace screening programs as a channel bypassing retail gatekeepers through employer-sponsored occupational health contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with demonstrated FDA de novo clearance and active CE marking surveillance systems under the EU In Vitro Diagnostic Regulation's performance accountability requirements. Long-term viability hinges on interoperability with electronic health record systems and telehealth reimbursement eligibility. Acquisition target archetype: venture-backed digital platforms with HL7 FHIR connectivity infrastructure. The signal to watch is BfArM and MHLW reimbursement listing velocity for connected diagnostic devices.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Respiratory Panel Development | Simultaneous influenza A/B and RSV detection commands premium positioning under FDA guidance. |
| Telehealth Platform Integration | HL7 FHIR connectivity enables reimbursement eligibility with German and Japanese payer networks. |
| Isothermal Amplification Scale-Up | Ambient-temperature molecular accuracy collapses the PCR cost barrier for household adoption. |
| Direct-to-Consumer Subscription Launch | Automated replenishment tied to surveillance alerts concentrates customer lifetime value in urban markets. |
| CE Marking Surveillance Investment | Ongoing clinical evidence generation satisfies EU In Vitro Diagnostic Regulation post-market accountability. |
Research Methodology
A standing panel of diagnostic platform engineers, regulatory affairs specialists at FDA and PMDA, retail pharmacy category managers, and telehealth reimbursement directors provided ongoing calibration across primary fieldwork and secondary validation. FDA 510(k) and de novo clearance databases, EU CE marking notifications under the In Vitro Diagnostic Regulation, Japan MHLW reimbursement listings, and hospital procurement contract aggregators supplied structured secondary inputs. Bottom-up unit demand modeling across product type, technology, and distribution channel triangulated against top-down market sizing from trade corridor analysis and customs data.
Scenario-bracketing around regulatory approval velocity, reimbursement listing timelines, and raw material supply disruption generated bounded projections across the analysis window. Segmentation dimensions modeled include product type (rapid test kits, PCR platforms, digital devices), technology generation (lateral flow, isothermal amplification, microfluidics), and end-user archetype (households, remote monitoring services, workplace programs). CAGRs derived from year-one installed base penetration rates and replacement cycle assumptions, with influenza seasonality patterns and antiviral treatment initiation protocols as disease-specific forecast inputs.
Sensitivities concentrate around FDA de novo pathway throughput, nitrocellulose membrane supply continuity, and telehealth reimbursement framework expansion in Germany and Japan. Forecasts embed assumptions regarding post-pandemic health monitoring habit persistence and isothermal amplification cost curves. Macroeconomic contraction affecting discretionary health spending, regulatory restriction on over-the-counter molecular claims, or technological breakthrough in CRISPR-based detection would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
Outsourced Testing Services Market
Testing Services
Viral Vector Integrity and Potency Analytics Test Instruments Market
Testing Services
Europe Newborn Screening Market
Testing Services
Apolipoprotein Testing Market
Testing Services
Blood Borne Testing Market
Testing Services
Asia-Pacific Newborn Screening Market
Testing Services
Global CA 125 Test Market
Testing Services
Antimicrobial Susceptibility Testing Market
Testing Services
Hbsag Testing Market
Testing Services
Lipase Testing Reagents Market
Testing Services
Global Sterility Testing Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Creatinine Testing Market
Testing Services
South America Endotoxin and Pyrogen Testing Market