
 Veterinary Reference Laboratories Market | 2026-2036
Veterinary Reference Laboratories Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Reference Laboratories Market Analysis
Equipment leasing and managed service contracts are fragmenting capital requirements across the veterinary reference laboratory sector. IDEXX Laboratories leverages its captive instrument placement model to lock in recurring reagent revenue. Zoetis anchors its position through backward integration into assay development and reference lab services. Laboklin GmbH & Co KG specializes in exotic and wildlife diagnostics, occupying a defensible niche with limited direct competition.
Veterinary reference laboratories are centralized diagnostic facilities that process complex specimens—blood, tissue, urine, and microbiological samples—using automated analyzers, mass spectrometry, and molecular platforms to deliver pathology and clinical chemistry results for animal health management. Their commercial purpose centers on enabling veterinarians to diagnose infectious diseases, metabolic disorders, and neoplasia with accuracy exceeding in-clinic capabilities. Clinical labs dominate service volume due to routine chemistry and hematology demand from companion animal hospitals, while microbiology represents the fastest-expanding test category as antimicrobial stewardship protocols tighten. Diagnostic labs command premium pricing for specialized histopathology and immunohistochemistry, where turnaround sensitivity and board-certified pathologist access create margin pools.
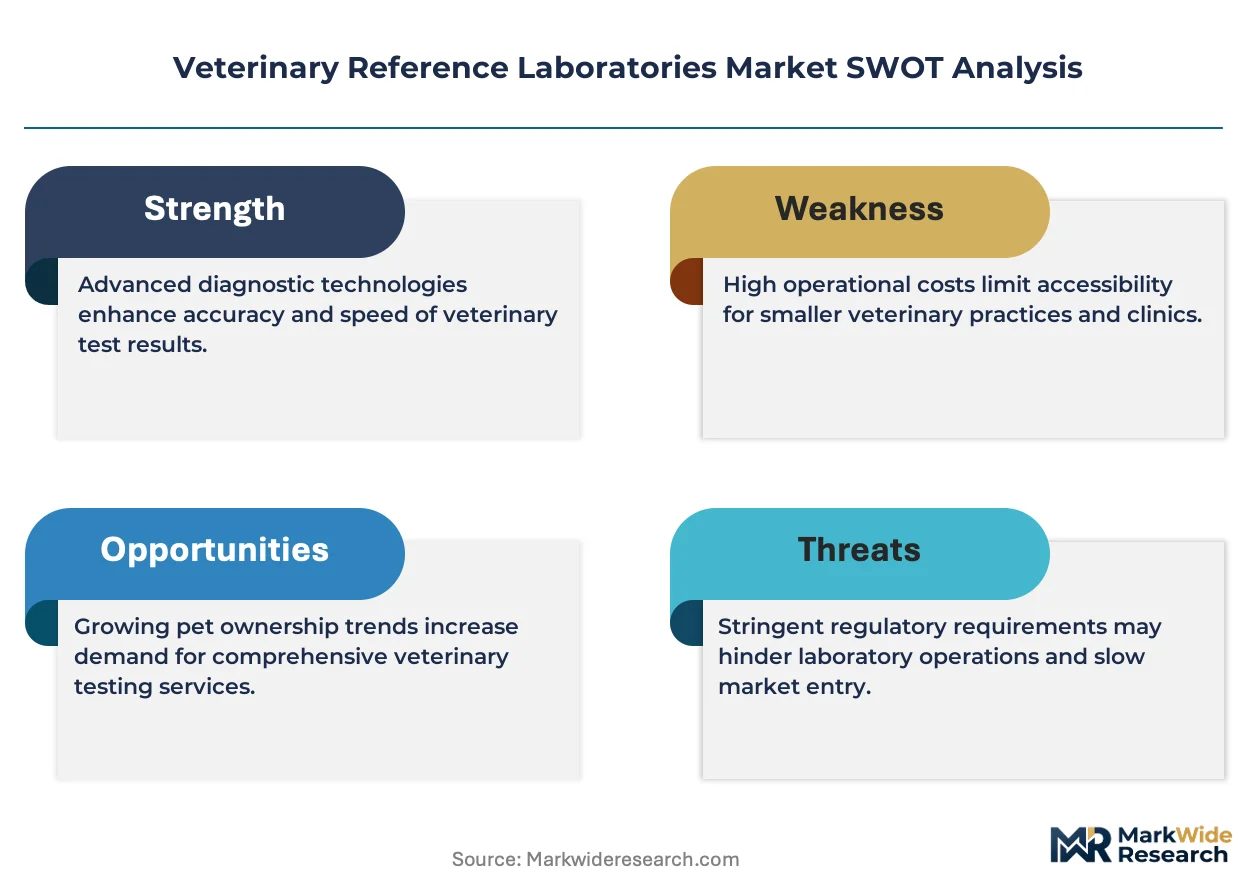
The FDA Center for Veterinary Medicine oversees diagnostic assay validation, while USDA APHIS regulates interstate movement of samples and notifiable disease reporting, collectively raising compliance costs but also creating barriers against unaccredited competitors. ISO 17025 accreditation requirements from laboratory quality bodies further differentiate tier-one providers from regional independents. Stakeholders must weigh capital deployment between automated high-throughput platforms and boutique specialty services as labor shortages in veterinary pathology constrain expansion timelines.
Market Dynamics
Veterinary practice consolidation is compressing purchasing power into fewer buyer entities while simultaneously fragmenting diagnostic service delivery across centralized reference labs and distributed point-of-care platforms.
Growth Catalysts
- Antimicrobial stewardship protocols:Regulatory mandates from the FDA Center for Veterinary Medicine and USDA APHIS are expanding microbiology testing volumes as veterinarians document susceptibility profiles before prescribing.
- Companion animal insurance penetration:Pet insurance carriers in the United States now reimburse reference laboratory diagnostics at higher rates than in-clinic testing, steering veterinary hospitals toward outsourced pathology.
- ISO 17025 accreditation expansion:Tier-one laboratories are leveraging quality certification to displace regional independents in contract bidding for multi-site veterinary hospital networks.
Market Restraints
- Board-certified pathologist scarcity:The pipeline of veterinary pathologists graduating from residency programs constrains histopathology capacity expansion regardless of capital availability.
- Interstate sample movement regulations:USDA APHIS permitting requirements for cross-border diagnostic specimen transport create friction for laboratories seeking national coverage from single facilities.
- Capital equipment depreciation cycles:Automated chemistry and hematology analyzers require replacement every five to seven years, locking laboratories into continuous reinvestment obligations.
Strategic Opportunities
- Wildlife and exotic species diagnostics:Zoological institutions and conservation programs represent an underserved segment with limited specialized competition and premium pricing tolerance.
- Telepathology platform integration:Digital slide scanning combined with remote pathologist consultation is virtualizing histopathology workflows and enabling 24-hour turnaround from distributed facilities.
- Point-of-care molecular testing convergence:PCR platform miniaturization is creating hybrid service models where reference laboratories manage quality control for in-clinic instruments.
Industry Challenges
- Multi-platform data integration:Veterinary hospitals operating both in-clinic analyzers and reference laboratory services face interoperability gaps between LIS and practice management software systems.
- Quality control standardization:Maintaining consistent assay performance across automated high-throughput lines and manual specialty procedures requires dedicated technical supervision that competes with revenue-generating activities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Reference Laboratories Market |
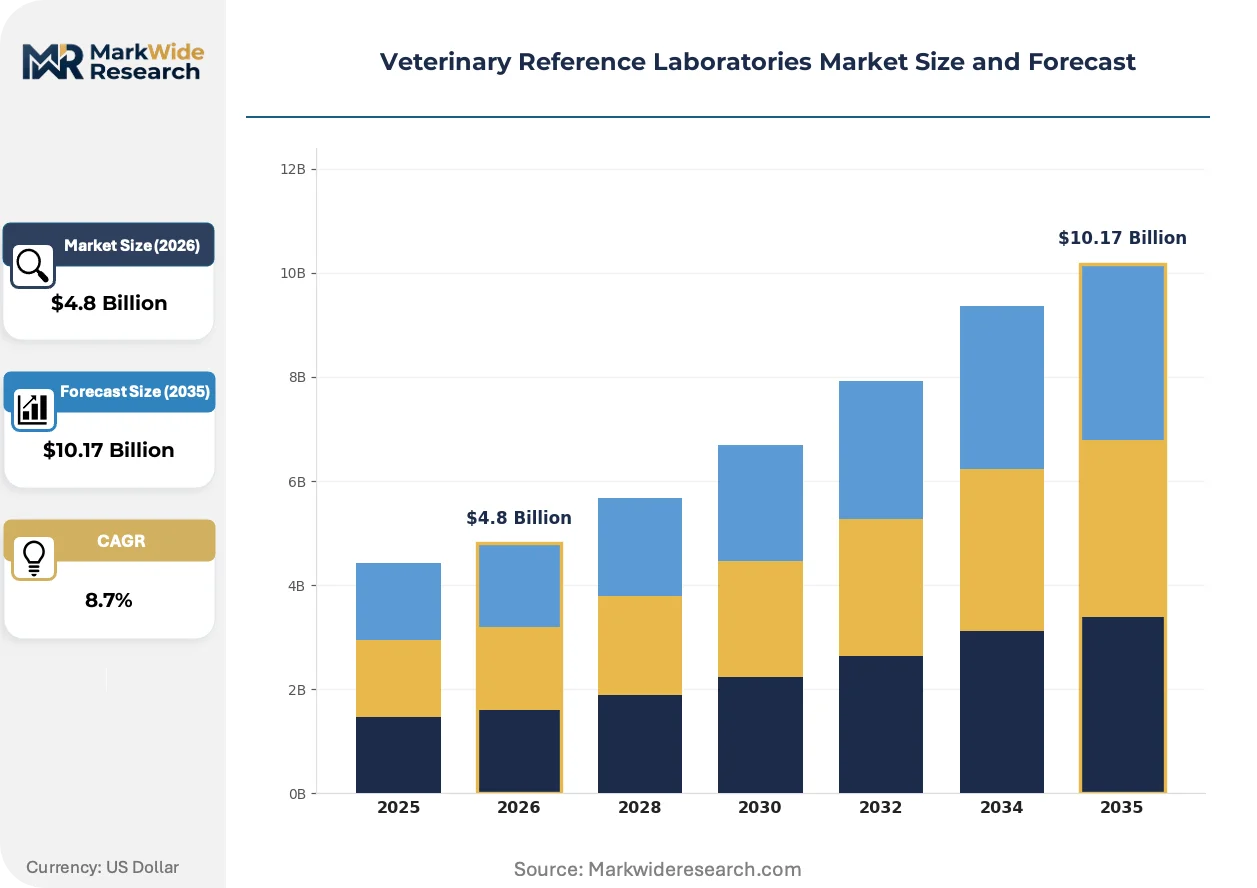
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lab Type: Clinical Labs, Diagnostic Labs, Research Labs, Environmental Labs Test Type: Serology, Hematology, Biochemistry, Microbiology Animal Type: Companion Animals, Livestock, Exotic Animals, Aquatic Species Service Type: Routine Testing, Specialized Testing, Consultation Services, Emergency Testing |
| Companies Covered | IDEXX Laboratories, Mars Incorporated, Zoetis, GD, Laboklin GmbH & Co KG, SYNLAB Group, Virbac, Boehringer Ingelheim, Neogen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Reference Laboratories Market Emerging Trajectories
Digital pathology infrastructure and artificial intelligence-assisted diagnostics are restructuring how veterinary laboratories process tissue specimens and deliver interpretive reports to clinical practitioners.
Whole-slide imaging systems combined with cloud-based storage architectures are virtualizing histopathology workflows across the sector. Multi-site veterinary hospital networks are deploying these platforms to centralize case review while maintaining geographic proximity to specimen collection. This virtualization is compressing the traditional tradeoff between turnaround speed and specialist pathologist access.
The FDA Center for Veterinary Medicine's evolving guidance on laboratory-developed tests is elevating validation documentation requirements for molecular diagnostics. Manufacturers must now demonstrate analytical and clinical performance across target species populations before commercial deployment. Reference laboratories with established quality management systems are absorbing these compliance costs more readily than emerging competitors.
Consolidated buying groups within veterinary practice management companies are unbundling diagnostic service contracts from instrument placement agreements. These entities now negotiate reference laboratory pricing separately from in-clinic analyzer supply arrangements, reversing the bundled procurement model that dominated the previous decade. The United States exhibits the most advanced manifestation of this pattern as corporate veterinary ownership penetrates major metropolitan markets.
Veterinary Reference Laboratories Market Segmentation
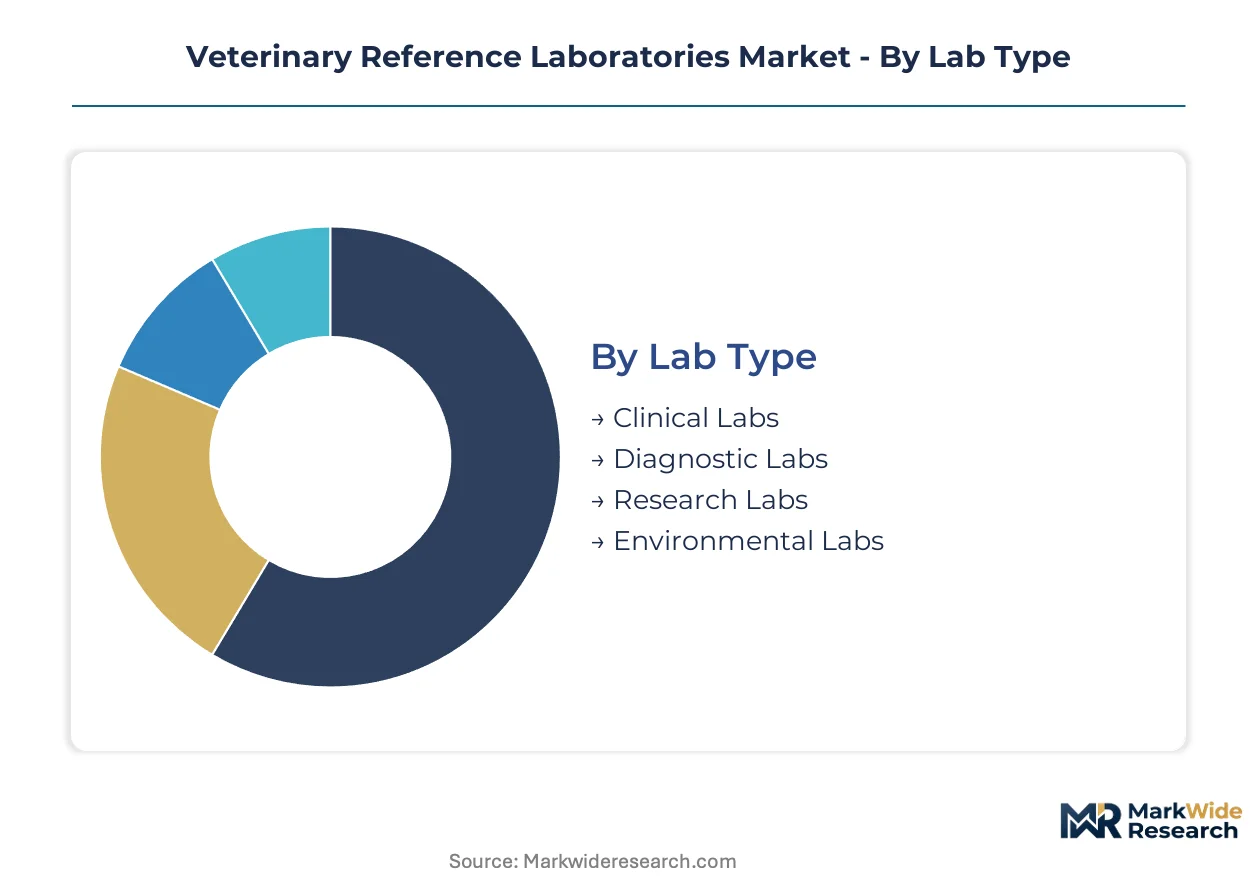
Veterinary reference laboratories segment across multiple dimensions that determine capital deployment, staffing models, and regulatory compliance obligations. Each segmentation axis reveals distinct margin structures and competitive dynamics that shape vendor positioning strategies.
Lab Type:
Cost tier differentiation separates facilities by equipment intensity and pathologist specialization levels.
- Clinical Labs:High-throughput facilities processing routine chemistry, hematology, and urinalysis on automated analyzer platforms. Demand concentrates in United States metropolitan corridors where corporate veterinary hospital chains consolidate specimen volumes for economies of scale.
- Diagnostic Labs:Specialized operations delivering histopathology, immunohistochemistry, and molecular diagnostics requiring board-certified veterinary pathologist interpretation. Revenue pools in specialty and emergency hospital networks that prioritize turnaround sensitivity over per-test cost.
- Research Labs:Academic and pharmaceutical contract facilities supporting drug development and epidemiological surveillance with GLP-compliant protocols.
- Environmental Labs:Niche providers analyzing feed, water, and facility samples for pathogen monitoring in agricultural and zoological settings.
Clinical Labs command the established base. The steepest expansion runs through Diagnostic Labs.
Test Type:
Application focus determines reagent consumption patterns and regulatory validation requirements.
- Microbiology:Bacterial culture, antimicrobial susceptibility testing, and molecular pathogen identification. FDA Center for Veterinary Medicine stewardship mandates are expanding volumes in United States companion animal practices as documentation requirements tighten before prescription.
- Hematology:Complete blood count and coagulation profiling using automated cell counters and manual differentials. Demand concentrates in emergency and critical care settings where rapid turnaround influences clinical decisions.
- Serology:Antibody detection for infectious disease screening and vaccine titer assessment.
- Biochemistry:Metabolic panel analysis for organ function monitoring and therapeutic drug level quantification.
Hematology commands the established base. Microbiology climbs the fastest as regulatory pressure intensifies.
Animal Type:
Customer type segmentation aligns laboratory capabilities with species-specific pathophysiology and specimen handling requirements.
- Companion Animals:Dogs and cats drive routine diagnostic volumes through primary care and specialty hospital networks. United States pet insurance reimbursement policies now favor reference laboratory testing over in-clinic alternatives, redirecting specimen flows.
- Livestock:Cattle, swine, and poultry diagnostics support herd health management and regulatory compliance for interstate movement and export certification.
- Exotic Animals:Avian, reptile, and small mammal testing requires specialized assay validation and interpretive expertise with limited qualified competition.
- Aquatic Species:Ornamental fish and aquaculture diagnostics represent an emerging segment with developing standardization.
Companion Animals command the established base. Exotic Animals gain share fastest through pricing power and limited specialist availability.
Service Type:
Volume and urgency profiles separate predictable revenue streams from premium-priced capacity reserves.
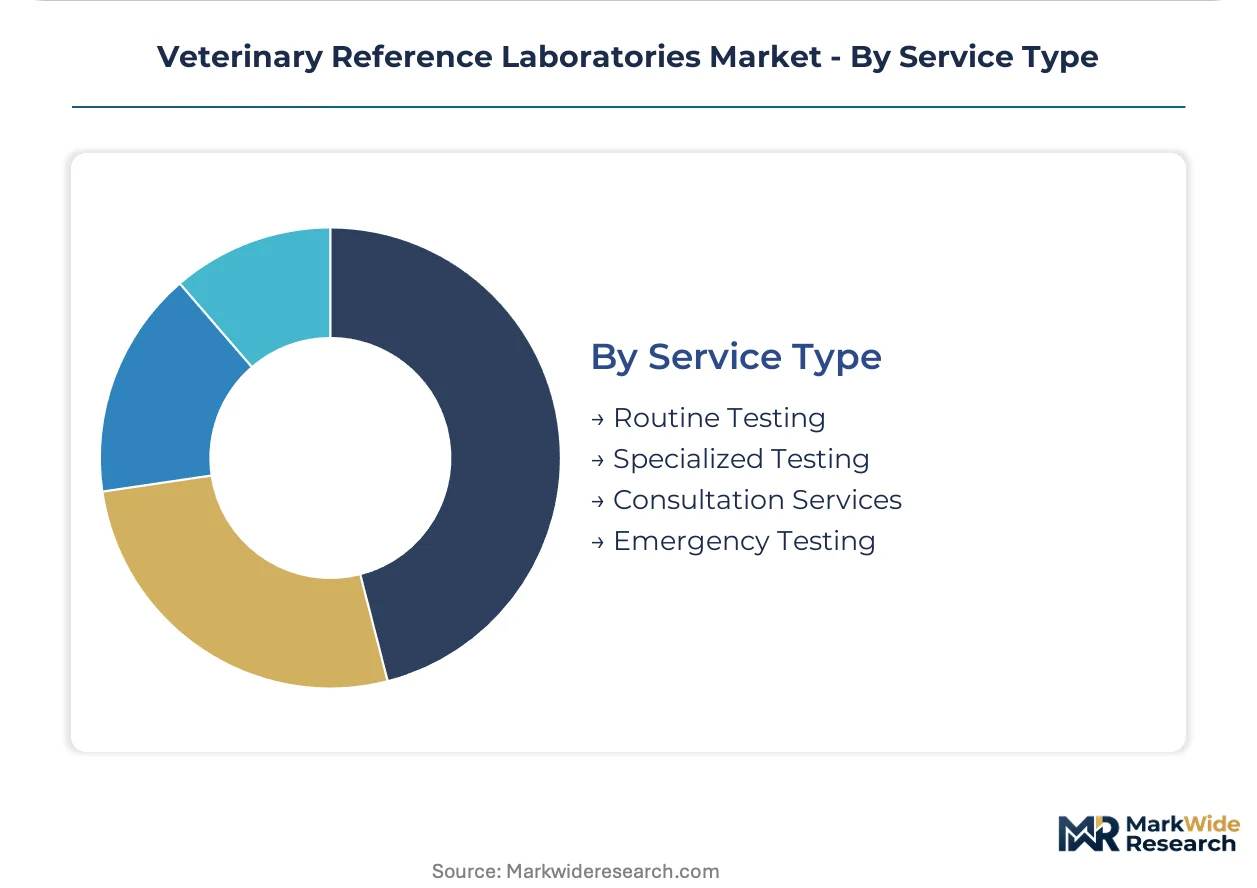
- Routine Testing:Scheduled wellness panels and chronic disease monitoring with standardized turnaround windows. Demand concentrates in high-volume corporate practice networks negotiating annual contracts with reference laboratory vendors.
- Specialized Testing:Complex molecular diagnostics, toxicology, and advanced imaging with extended turnaround justified by technical complexity.
- Consultation Services:Remote pathologist review and case discussion supporting veterinary practitioners with interpretive guidance.
- Emergency Testing:Stat processing with accelerated turnaround for critical care cases, commanding substantial price premiums.
Routine Testing commands the established base. Emergency Testing expands most quickly as specialty hospital networks extend operating hours.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet insurance reimbursement policies and veterinary practice consolidation are redirecting diagnostic specimen flows toward centralized reference laboratories in markets with mature companion animal healthcare infrastructure.
United States
Corporate veterinary hospital chains in metropolitan corridors negotiate annual contracts with reference laboratory vendors for high-volume routine testing. The FDA Center for Veterinary Medicine oversees diagnostic assay validation requirements. The Greater Boston and Pacific Northwest clusters host specialty diagnostic networks serving emergency and critical care hospitals with stat processing capabilities.
Germany
Specialized histopathology and immunohistochemistry demand concentrates in specialty and emergency hospital networks prioritizing turnaround sensitivity. ISO 17025 accreditation requirements from laboratory quality bodies differentiate tier-one providers from regional independents. The North Rhine-Westphalia region anchors multiple reference laboratory facilities serving the Benelux corridor and domestic veterinary networks.
United Kingdom
Antimicrobial stewardship protocols from veterinary regulators are expanding microbiology testing volumes as practitioners document susceptibility profiles. The country's national veterinary pharmaceutical regulator enforces documentation requirements before prescription. The Southeast England cluster around London supports reference laboratory networks processing specimens from corporate practice groups.
Japan
Companion animal insurance penetration is steering veterinary hospitals toward outsourced pathology with favorable reimbursement differentials. METI guidelines influence quality management system adoption across diagnostic service providers. The Kanto region surrounding Tokyo concentrates reference laboratory capacity serving the densest metropolitan veterinary hospital networks.
Australia
Wildlife and exotic species diagnostics from zoological institutions and conservation programs represent an underserved segment with premium pricing tolerance. The TGA oversees veterinary therapeutic goods regulation including diagnostic devices. The New South Wales and Victoria corridor supports specialized reference laboratories serving both companion animal hospitals and agricultural export certification requirements.
Veterinary Reference Laboratories Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around multi-site veterinary hospital networks and fragmented regional independents. Tier-one laboratories leverage ISO 17025 accreditation to displace smaller competitors in contract bidding, while equipment manufacturers deploy captive instrument placement models to secure recurring reagent revenue. Two strategic archetypes dominate: integrated diagnostic-platform vendors combining instrument supply with reference laboratory services, and pure-play specialty laboratories focusing on exotic species or advanced pathology. Competitive moves center on M&A activity absorbing regional independents into national networks, and strategic partnerships between reference laboratories and veterinary practice management companies.
Within the integrated diagnostic-platform tier, IDEXX Laboratories and Zoetis exemplify archetypes combining captive instrument ecosystems with reference laboratory service networks. Mars Incorporated represents the corporate veterinary ownership model where consolidated buying groups unbundle diagnostic contracts from supply arrangements. Laboklin GmbH & Co KG occupies a specialist position in exotic and wildlife diagnostics with limited direct competition.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| Mars Incorporated |
| Zoetis |
| GD |
| Laboklin GmbH & Co KG |
| SYNLAB Group |
| Virbac |
| Boehringer Ingelheim |
| Neogen Corporation |
| Others |
Supply Flow & Price Mechanics
USDA APHIS interstate sample movement permitting creates a regulatory chokepoint that simultaneously widens pricing spreads between accredited tier-one laboratories and regional independents while forcing supply chain fragmentation across multiple distributed facilities rather than centralized national hubs.
Pricing Analysis
Certification level creates the primary spread between ISO 17025-accredited tier-one providers and unaccredited regional competitors. Three-tier pricing structure across premium, standard, and economy levels segments by pathologist specialization depth and turnaround guarantees. Cost compression in the economy tier is intensifying because corporate veterinary buying groups unbundle diagnostic contracts from instrument supply arrangements. Emergency and specialty hospital networks exhibit the least price sensitivity, while primary care clinics in consolidated practice groups drive the hardest volume-based negotiations.
Supply Chain Analysis
Export-control restrictions on advanced mass spectrometry and digital pathology platforms limit equipment flows from Germany, Japan, and the United States into emerging diagnostic markets. Supply concentration in these three countries for automated hematology analyzers, molecular PCR systems, and whole-slide imaging hardware creates single-source vulnerability for laboratories seeking to expand high-throughput capacity. Distribution runs through captive instrument placement models from integrated diagnostic-platform vendors that lock in recurring reagent revenue through long-term service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary reference laboratory sector rewards ownership of scarce board-certified pathologist capacity and ISO 17025 accreditation infrastructure, with competitive advantage accruing to entities that secure these constrained credentials ahead of demand inflection.
For Market Incumbents: Build pathologist network density as the core moat by acquiring residency-trained specialists before practice consolidation accelerates hiring competition. Anchor geographic coverage through distributed specimen collection hubs that circumvent USDA APHIS interstate transport friction. Defensive consolidation of regional independents absorbs volume that would otherwise migrate to corporate veterinary buying groups. For New Entrants and Emerging Players: Australia's wildlife and exotic species diagnostics segment offers the most penetrable white-space opportunity, with zoological institutions and conservation programs currently underserved by limited specialist competition. Telepathology platform integration enables 24-hour turnaround without resident pathologist infrastructure, lowering capital barriers to entry. A go-to-market angle targeting conservation NGOs and aquarium networks bypasses entrenched corporate veterinary supply relationships. For Investors and Strategic Acquirers: FDA Center for Veterinary Medicine evolving guidance on laboratory-developed tests reshapes the acquisition landscape by elevating compliance costs that favor scaled quality management systems. Target laboratories with established molecular diagnostic validation documentation and multi-species assay portfolios. The signal to watch is pet insurance carrier reimbursement policy shifts that redirect specimen flows toward reference laboratories over in-clinic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Investment | Quality certification displaces regional independents in corporate veterinary network bidding. |
| Telepathology Platform Deployment | Digital slide scanning virtualizes histopathology workflows across distributed facilities. |
| Wildlife Diagnostics Specialization | Exotic species expertise commands premium pricing with limited qualified competition. |
| Point-of-Care Molecular Partnership | Reference laboratories manage quality control for in-clinic PCR instrument networks. |
| Pathologist Network Acquisition | Board-certified veterinary pathologist scarcity constrains capacity expansion regardless of capital. |
Methodological Framework
Operator-level perspectives from veterinary practice managers, reference laboratory operations directors, diagnostic platform sales executives, and pet insurance reimbursement specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, USDA APHIS interstate movement regulations, ISO 17025 accreditation body records, and corporate veterinary practice SEC filings. Bottom-up specimen volume modeling and top-down market sizing triangulated across clinical lab, diagnostic lab, and research lab service categories.
Scenario-bracketing framed projections across antimicrobial stewardship mandate intensity and veterinary practice consolidation velocity. Segmentation dimensions modeled encompassed lab type, test type, animal type, and service type across the analysis window. CAGRs derived from instrument placement trends, reagent consumption patterns, and pathologist workforce pipeline data. Industry-specific forecast inputs incorporated pet insurance penetration curves and corporate veterinary ownership expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated diagnostic-platform vendors to unbundle reference laboratory services from instrument supply would shift outcomes. Material shifts in FDA Center for Veterinary Medicine laboratory-developed test guidance stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
LIMS Market
Laboratory Services
Central Lab Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
Pathology Services Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
US Laboratory Disposable Products Market