
 Karyotyping Service Market | 2026-2036
Karyotyping Service Market Size, Share, and Industry Trends Forecast 2026-2036
Karyotyping Service Market Insights
Modular service bundling is recalibrating how buyers structure cytogenetics contracts. Thermo Fisher Scientific leverages its instrument-to-service pipeline to anchor high-volume hospital accounts. Creative Bioarray specializes in custom karyotyping protocols for pharmaceutical toxicology studies. Labcorp dominates commercial reference testing through its national logistics footprint and payer contracts.
Karyotyping services encompass chromosome analysis through G-banding, fluorescence in situ hybridization, and microarray-based comparative genomic hybridization to detect aneuploidy, translocations, and submicroscopic copy-number variants at resolutions reaching 5-10 megabases. Conventional karyotyping retains utility for constitutional abnormality detection where whole-chromosome architecture matters, though fluorescence techniques capture expanding oncology and prenatal volume as FISH probes target gene fusions in leukemia panels. Diagnostic centers now generate margin pools from rapid turnaround karyotyping for infertility workups, while stem cell research applications pull demand for specialized spectral karyotyping services.
FDA oversight of analyte-specific reagents and laboratory-developed tests shapes service validation requirements for clinical karyotyping laboratories. CAP accreditation standards and CLIA certification govern analytical performance and reporting protocols across US testing facilities. ISO 15189 medical laboratory standards influence quality management for laboratories seeking international recognition. Stakeholders must monitor evolving regulatory distinctions between research-use-only and diagnostic-grade karyotyping workflows as reimbursement pathways solidify for integrated genomic testing strategies.
Market Dynamics
Next-generation sequencing integration is compressing turnaround times for chromosomal abnormality detection while simultaneously eroding reimbursement premiums for conventional G-banded karyotyping workflows. This technological displacement is forcing service laboratories to restructure assay menus and retrain cytogenetic technologists.
Growth Catalysts
- CMS reimbursement alignment:United States Medicare coverage determinations for non-invasive prenatal testing create downstream demand for confirmatory diagnostic karyotyping services in high-risk pregnancies.
- Fertility clinic consolidation:Large reproductive health networks in Spain and Denmark now mandate pre-implantation genetic screening protocols that bundle karyotyping with PGT-A workflows.
- Microarray resolution advances:SNP array platforms detecting copy-number variants below 400 kilobases capture submicroscopic abnormalities invisible to conventional microscopy.
Market Restraints
- Reagent supply concentration:Fluorophore-conjugated probe manufacturing concentrates among three German chemical suppliers, exposing service laboratories to input cost volatility.
- Technical obsolescence curve:Conventional karyotyping's 2-3 week turnaround cannot match the 48-hour reporting windows now standard in oncology cytogenetics.
- CLIA certification barriers:United States laboratories face 12-18 month validation timelines for laboratory-developed test modifications, freezing assay innovation.
Strategic Opportunities
- Direct-to-consumer channel emergence:Telehealth platforms in California and Texas now prescribe karyotyping as follow-up to at-home carrier screening, bypassing traditional genetics referral pathways.
- ISO 15189 accreditation arbitrage:Laboratories achieving international quality recognition access contract research organization work from Singapore and Switzerland-based pharmaceutical sponsors.
- AI-assisted karyotype analysis:Deep learning classifiers trained on G-band pattern libraries reduce scorer inter-observer variability and enable technologist workforce expansion.
Industry Challenges
- Cytogenetic technologist shortage:United States training programs graduate fewer than 150 board-eligible specialists annually against replacement demand for 400 retiring professionals.
- LIMS integration complexity:Legacy laboratory information management systems require custom middleware development to interface with cloud-based image analysis platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Karyotyping Service Market |
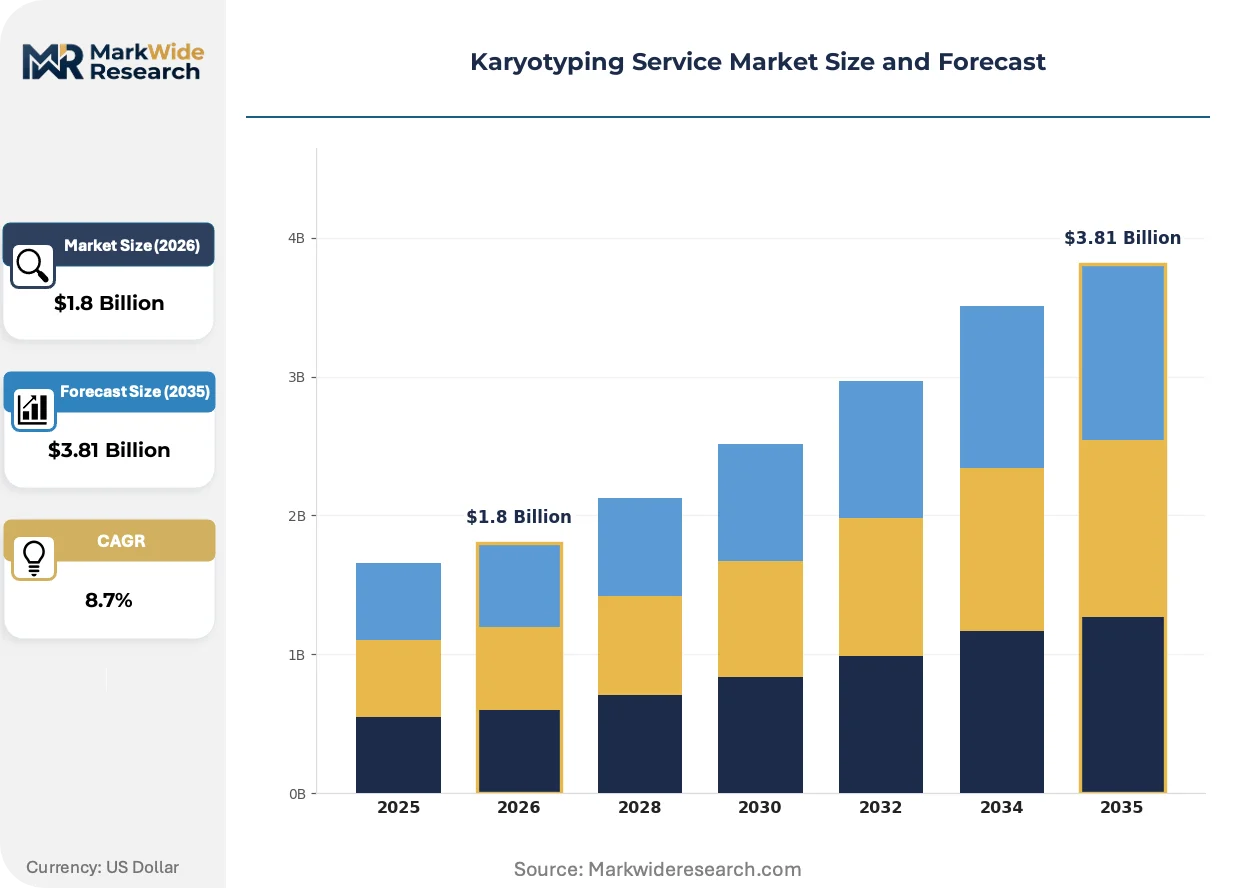
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Conventional Karyotyping, FISH, Comparative Genomic Hybridization, Next-Generation Sequencing End User: Hospitals, Research Laboratories, Diagnostic Centers, Fertility Clinics Application: Cancer Diagnosis, Genetic Disorder Screening, Prenatal Diagnosis, Stem Cell Research Technology: Microscopy, Bioinformatics, Fluorescence Techniques, Software Analysis |
| Companies Covered | Thermo Fisher Scientific, Creative Bioarray, Applied StemCell, Cell Guidance Systems, KaryoLogic, Labcorp, Agilent Technologies, Bio-Rad Laboratories, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Karyotyping Service Market Trends and Innovations
Automation of chromosome enumeration and structural abnormality detection is collapsing the labor intensity that historically defined cytogenetics service economics. Laboratories now compete on computational infrastructure rather than technologist headcount.
Optical genome mapping is electrifying constitutional disorder diagnostics by detecting structural variants and repeat expansions without cell culture requirements. Clinical laboratories in Massachusetts and North Carolina have adopted Bionano Genomics platforms for pediatric developmental delay workups. The technology is compressing diagnostic odyssey timelines from months to days while simultaneously cannibalizing revenue from traditional FISH probe panels.
CAP checklist revisions for cytogenetics laboratories now mandate electronic image capture and remote case review capabilities, accelerating cloud-based pathology platform adoption. European laboratories seeking EQA participation must demonstrate inter-laboratory digital slide sharing proficiency. This regulatory pressure is forcing mid-volume service providers to abandon on-premise storage architectures.
Hospital systems now unbundle karyotyping from comprehensive genetics contracts and source rapid-turnaround infertility testing through standalone purchase orders. Fertility networks in New Jersey and Illinois negotiate direct service agreements with specialized reference laboratories, bypassing integrated health system laboratory channels. This channel fragmentation concentrates volume among laboratories offering sub-72-hour reporting guarantees.
Karyotyping Service Market Segmentation
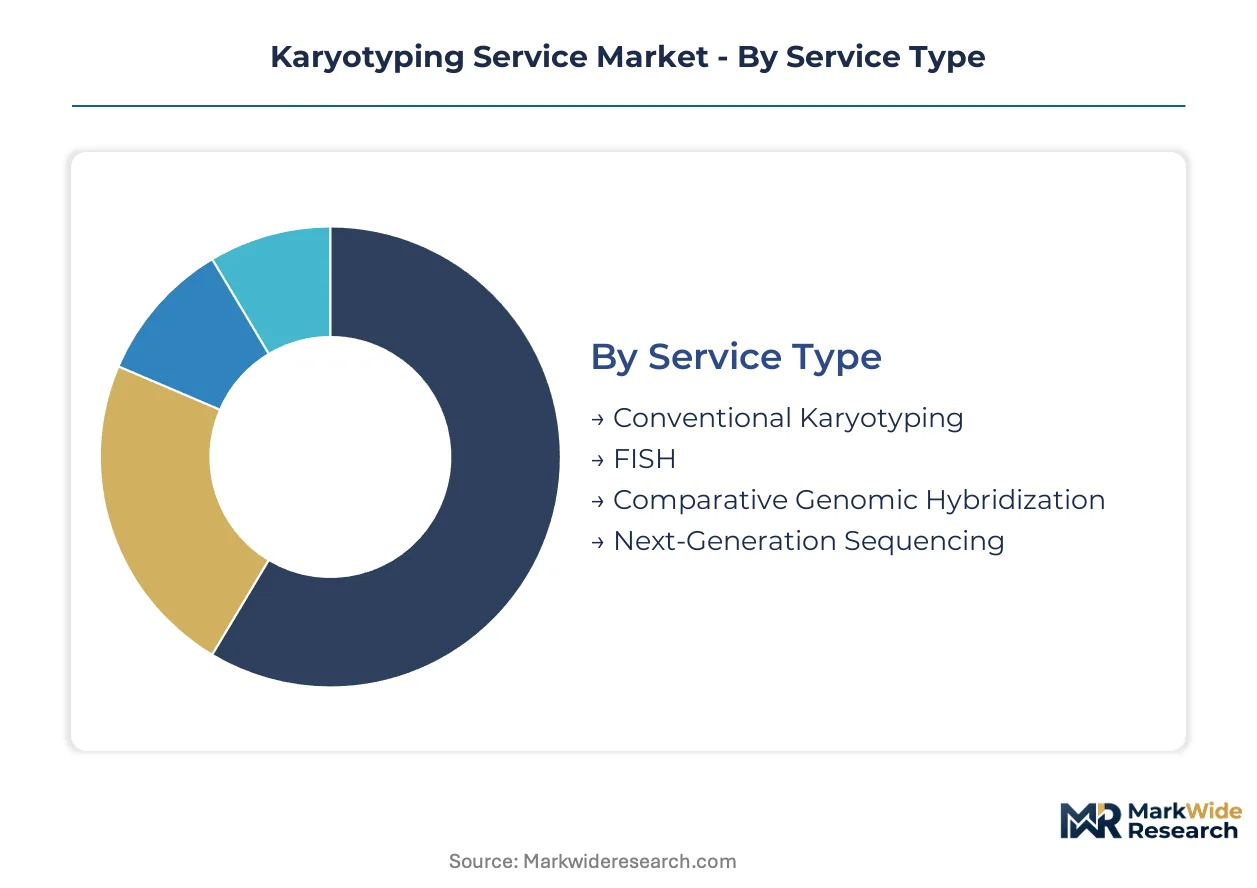
Service differentiation in karyotyping hinges on capital deployment intensity, with automated platforms demanding seven-figure instrument investments while manual microscopy workflows require specialized labor pools. Procurement managers structure vendor contracts around these cost hierarchies, bundling high-throughput services for hospital systems and reserving boutique protocols for research sponsors.
Service Type:
Capital intensity varies dramatically across assay platforms, with next-generation sequencing installations requiring substantial upfront sequencing capacity and bioinformatics infrastructure compared to legacy microscopy-based methods.
- Conventional Karyotyping:G-banding protocols on metaphase chromosomes remain the reference standard for constitutional abnormality detection. Clinical laboratories in the United States deploy these workflows for prenatal diagnosis and pediatric developmental delay workups where whole-chromosome architecture assessment proves essential.
- FISH:Fluorescence in situ hybridization employs locus-specific probes to detect gene fusions, microdeletions, and aneuploidy in interphase nuclei. Oncology cytogenetics laboratories in Massachusetts and North Carolina leverage rapid turnaround FISH panels for leukemia classification, compressing diagnostic timelines to 48 hours.
- Comparative Genomic Hybridization:Microarray-based platforms detect submicroscopic copy-number variants below 400 kilobases resolution. SNP array installations concentrate in reference laboratories serving prenatal and postnatal constitutional disorder markets.
- Next-Generation Sequencing:Chromosomal analysis via NGS integrates with broader genomic testing menus, displacing standalone karyotyping in prenatal screening workflows. Sequencing infrastructure investments now anchor service laboratory competitive positioning.
Conventional karyotyping absorbs the bulk of installed capacity; next-generation sequencing is expanding most quickly.
End User:
Customer procurement sophistication determines contract structure complexity, with integrated health systems negotiating enterprise pricing against standalone fertility clinics purchasing through purchase orders.
- Hospitals:Academic medical centers and community hospital systems operate CLIA-certified cytogenetics laboratories or outsource to national reference networks. CMS reimbursement policies shape service availability across Medicare-dependent patient populations.
- Research Laboratories:Pharmaceutical toxicology studies and stem cell characterization projects demand custom protocol development. Contract research organizations in Singapore and Switzerland source ISO 15189-accredited partners for regulatory submission support.
- Diagnostic Centers:Independent reference laboratories compete on turnaround time guarantees and payer contract breadth. Labcorp's national logistics footprint dominates commercial testing volume through direct insurer relationships.
- Fertility Clinics:Reproductive health networks in Spain and Denmark mandate pre-implantation genetic screening bundling karyotyping with PGT-A workflows. New Jersey and Illinois fertility networks negotiate direct service agreements bypassing health system laboratory channels.
Hospital systems command the largest contract values; fertility clinics are climbing the fastest as reproductive health networks consolidate.
Application:
Clinical utility and reimbursement pathways segment demand, with oncology and prenatal applications capturing distinct margin profiles based on test complexity and medical necessity documentation requirements.
- Cancer Diagnosis:Hematologic malignancy classification relies on karyotyping for chromosomal translocation detection guiding therapy selection. FISH probe panels for BCR-ABL, PML-RARA, and MLL rearrangements anchor leukemia diagnostic workflows.
- Genetic Disorder Screening:Constitutional abnormality detection for developmental delay, autism spectrum disorders, and multiple congenital anomalies drives pediatric cytogenetics volume. Optical genome mapping platforms in Massachusetts compress diagnostic odyssey timelines.
- Prenatal Diagnosis:Amniocentesis and chorionic villus sampling karyotyping serves as confirmatory testing following positive non-invasive prenatal screening. CMS coverage determinations for NIPT create downstream demand for invasive diagnostic confirmation.
- Stem Cell Research:Characterization of induced pluripotent stem cell lines and embryonic stem cell banks requires spectral karyotyping for quality control. Pharmaceutical sponsors fund specialized service protocols for regenerative medicine development.
Cancer diagnosis captures the deepest reimbursement; stem cell research is gaining share fastest as regenerative medicine investment accelerates.
Technology:
Platform automation intensity separates capital-heavy computational approaches from labor-dependent manual interpretation workflows.
- Microscopy:Conventional brightfield and fluorescence microscopy infrastructure underpins G-banding and FISH protocols. Zeiss and Olympus instrument installations anchor mid-volume service laboratory operations.
- Bioinformatics:Sequence alignment, variant calling, and copy-number analysis pipelines require computational infrastructure and specialized personnel. Cloud-based platforms now interface with legacy laboratory information management systems through custom middleware.
- Fluorescence Techniques:Probe hybridization, signal amplification, and imaging systems enable rapid interphase analysis. Fluorophore-conjugated probe manufacturing concentrates among German chemical suppliers.
- Software Analysis:AI-assisted karyotype classifiers trained on G-band pattern libraries reduce scorer inter-observer variability. Deep learning deployment enables technologist workforce expansion amid specialist shortage.
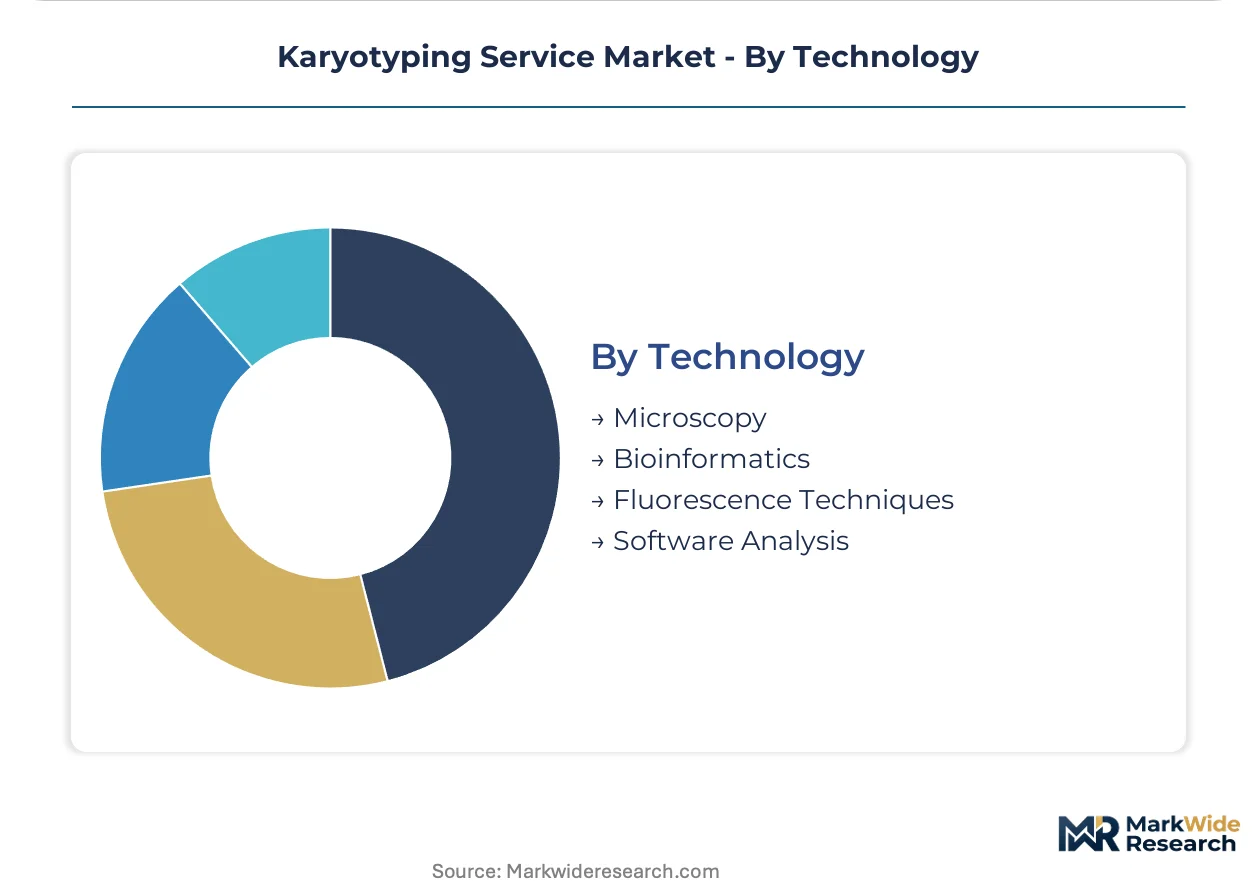
Microscopy retains the largest installed base; bioinformatics is expanding most steeply as NGS integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for life sciences in Singapore and Research Triangle Park in North Carolina concentrate karyotyping service infrastructure through tax abatements and streamlined regulatory pathways. These zones anchor regional demand clusters for cytogenetics outsourcing.
United States
CMS reimbursement policies for non-invasive prenatal testing create downstream demand for confirmatory karyotyping in high-risk pregnancies. FDA oversight of analyte-specific reagents shapes service validation requirements for clinical laboratories. The Research Triangle Park corridor in North Carolina hosts specialized reference laboratories serving fertility networks across the Southeast.
Germany
Fluorophore-conjugated probe manufacturing concentrates among chemical suppliers in the Rhine-Ruhr industrial region, exposing service laboratories to input cost volatility. REACH regulations govern chemical reagent registration and safety documentation for diagnostic applications. The Munich biotech cluster integrates karyotyping services with pharmaceutical toxicology studies for regulatory submission support.
Spain
Large reproductive health networks mandate pre-implantation genetic screening protocols that bundle karyotyping with PGT-A workflows. The country's national pharmaceutical regulator enforces quality standards for laboratory-developed tests in fertility applications. Barcelona's medical technology corridor hosts specialized cytogenetics providers serving consolidated fertility clinic chains across Catalonia and Madrid.
Switzerland
Contract research organizations based in Basel and Zurich source ISO 15189-accredited karyotyping partners for regulatory submission support. Swissmedic oversees diagnostic-grade service validation for clinical trial support applications. The Basel pharmaceutical hub drives demand for spectral karyotyping in stem cell characterization for regenerative medicine development.
Singapore
Biopolis and one-north special economic zones attract cytogenetics service providers through ten-year tax holidays and expedited business licensing. The Health Sciences Authority regulates laboratory-developed tests for clinical applications across Southeast Asian markets. Singapore-based contract research organizations channel pharmaceutical toxicology karyotyping work to accredited regional partners.
Karyotyping Service Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument, reagent, and service segments. The market structure tiers around capital deployment intensity, with automated platform providers anchoring high-volume hospital accounts and boutique laboratories capturing specialized research protocols. Three archetypes dominate: diversified life sciences conglomerates with instrument-to-service pipelines, independent reference laboratories with national logistics footprints, and specialized cytogenetics boutiques with custom protocol capabilities. Consolidation pressures favor acquisition of regional laboratories by national reference networks, while technology licensing agreements proliferate between platform developers and service providers.
Among diversified instrument-to-service conglomerates, Thermo Fisher Scientific occupies a position exemplifying vertical integration from sequencing infrastructure through clinical service delivery. Labcorp represents the scale-driven reference laboratory archetype, anchoring commercial testing volume through direct payer relationships and logistics density. Creative Bioarray sits within the specialized boutique tier, occupying a position tied to custom protocol development for pharmaceutical toxicology applications. These three entities collectively illustrate the competitive spectrum from capital-heavy platform dominance to agile specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Creative Bioarray |
| Applied StemCell |
| Cell Guidance Systems |
| KaryoLogic |
| Labcorp |
| Agilent Technologies |
| Bio-Rad Laboratories |
| PerkinElmer |
| Others |
Pricing and Supply Chain Analysis
ISO 15189 accreditation mandates gate both qualified laboratory supply partnerships and premium-tier service pricing access across the karyotyping service market, as fertility networks and pharmaceutical sponsors increasingly require documented quality management systems as a procurement precondition.
Pricing Analysis
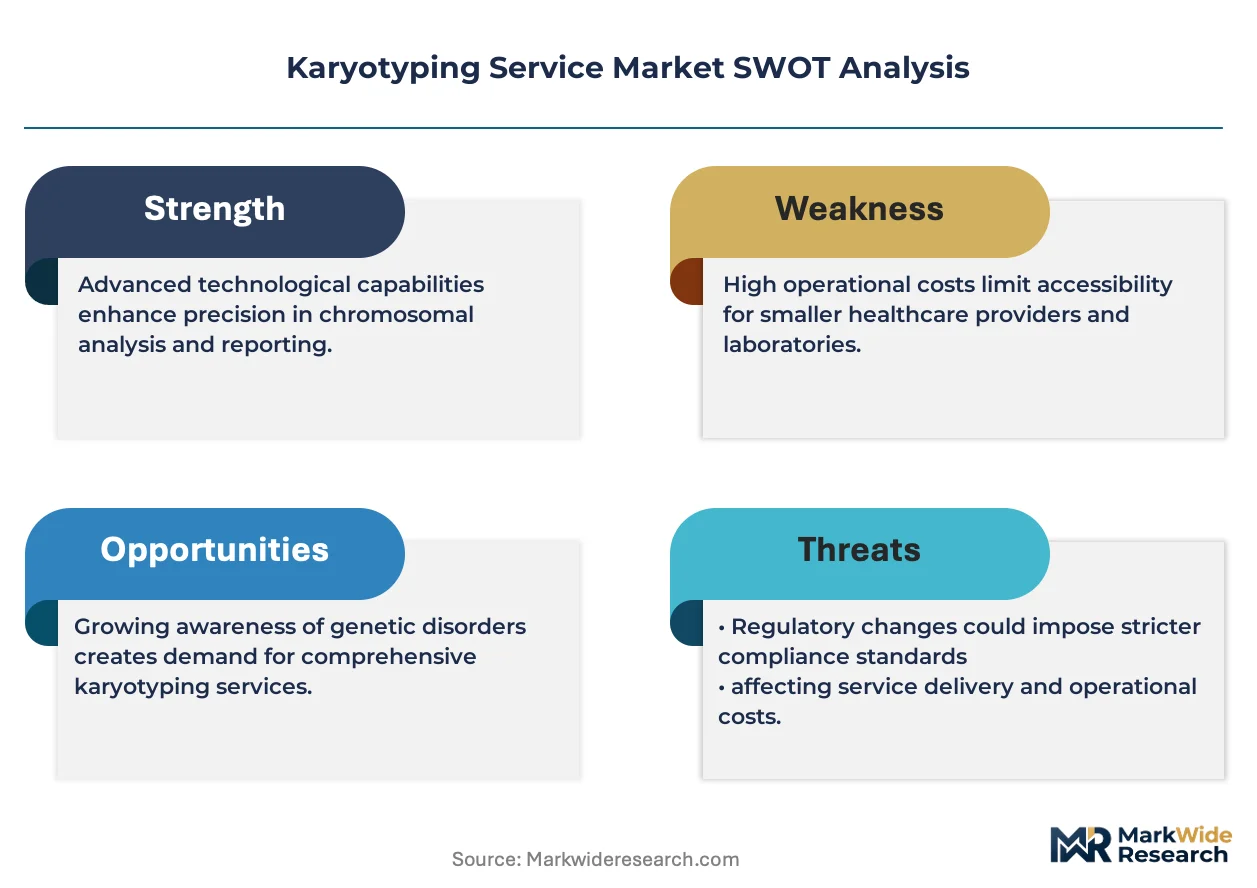
Margin tightening in rapid-turnaround infertility testing reflects fertility clinic consolidation demanding sub-72-hour reporting guarantees. Three-tier pricing structure across premium, standard, and economy levels separates CAP-accredited reference laboratories from regional diagnostic centers and unaccredited research service providers. Price differentiation rests on ISO 15189 certification status and CLIA complexity level. Academic medical centers show lowest price sensitivity; standalone fertility clinics in competitive markets exhibit highest.
Supply Chain Analysis
German domestic-content concentration in fluorophore-conjugated probe manufacturing is reshaping sourcing strategies for US and Singapore-based service laboratories. Reagent supply draws from Germany, Switzerland, and the United States. Critical dependencies include fluorophore dyes, synthetic oligonucleotides, and cell culture media. Single-source vulnerability concentrates in Rhine-Ruhr chemical suppliers. Distribution runs through direct manufacturer-laboratory contracts and specialized life sciences distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The karyotyping service market functions as a vertical-integration race where control over sequencing infrastructure and bioinformatics pipelines determines contract capture at high-volume hospital accounts.
For Market Incumbents: Anticipate optical genome mapping displacement of conventional FISH revenue by securing Bionano Genomics platform partnerships and retraining cytogenetic technologists on computational interpretation workflows. Consolidate regional reference laboratories to deepen CLIA-certified capacity in Research Triangle Park and New Jersey corridor fertility networks. Channel control through direct payer contracts remains the priority defensive lever.
For New Entrants and Emerging Players: Telehealth platforms prescribing karyotyping as follow-up to at-home carrier screening represent the most penetrable channel, particularly in California and Texas where direct-to-consumer genetics bypasses traditional referral pathways. Target AI-assisted karyotype analysis software development as a go-to-market angle, addressing the 400-annual-graduate technologist shortage with deep learning classifiers that reduce scorer inter-observer variability.
For Investors and Strategic Acquirers: CAP checklist revisions mandating electronic image capture and remote case review capabilities are the leading indicator that cloud-based pathology platform adoption will concentrate volume among laboratories with computational infrastructure investments. Long-term viability favors acquisition of ISO 15189-accredited mid-volume providers in Singapore and Switzerland serving contract research organization demand. Watch for fertility network direct service agreement announcements as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Karyotype Analysis Deployment | Deep learning classifiers trained on G-band pattern libraries reduce scorer inter-observer variability amid technologist shortage. |
| Optical Genome Mapping Platform Adoption | Bionano Genomics installations in Massachusetts and North Carolina compress diagnostic odyssey timelines from months to days. |
| ISO 15189 Accreditation Investment | Singapore and Switzerland-based pharmaceutical sponsors channel toxicology work to internationally recognized quality laboratories. |
| Direct-to-Consumer Channel Partnership | Telehealth platforms in California and Texas bypass traditional genetics referral pathways for at-home screening follow-up. |
| Fertility Network Direct Contracting | New Jersey and Illinois reproductive health networks negotiate standalone purchase orders bypassing integrated health system laboratory channels. |
Research Methodology
FDA 510(k) filings, CAP laboratory accreditation records, and CMS reimbursement determinations formed the secondary backbone, combined with primary interviews with cytogenetics laboratory directors, fertility clinic procurement managers, pharmaceutical toxicology study leads, and CLIA certification consultants. Bottom-up service volume estimates triangulated against top-down addressable market calculations derived from installed sequencing capacity and hospital system contract coverage.
Bottom-up modeling segmented demand across conventional karyotyping, FISH, microarray-based comparative genomic hybridization, and next-generation sequencing service types, further disaggregated by cancer diagnosis, genetic disorder screening, prenatal diagnosis, and stem cell research applications. CAGRs were derived from regression analysis of historical service volume trends and technology displacement curves. Forecast inputs incorporated CMS coverage determination timelines and fertility clinic consolidation patterns.
Several conditions sit outside the modeled scope, including potential FDA reclassification of laboratory-developed tests and unforeseen technological disruption from long-read sequencing platforms. Forecasts reflect documented assumptions regarding reimbursement stability and technologist training program graduation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
LIMS Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Assessment Services Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Sera and Reagents Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
Histopathology Services Market