
 US Laboratory Disposable Products Market | 2026-2036
US Laboratory Disposable Products Market Size, Share, and Industry Trends Forecast 2026-2036
US Laboratory Disposable Products Market Intelligence
Aftermarket service revenue for equipment validation and single-use assembly qualification is tilting toward specialized distributors. Thermo Fisher Scientific Inc. leverages its integrated supply chain to capture recurring consumable pull-through. Becton, Dickinson and Company anchors its position through deep catheter and syringe manufacturing scale. Medline Industries, Inc. competes aggressively on hospital and clinical laboratory channel control.
US Laboratory Disposable Products encompass single-use implements—pipettes, gloves, tubing, petri dishes, and containment vessels—fabricated from USP Class VI-certified plastics, medical-grade papers, borosilicate glass, or anodized aluminum, primarily through injection molding, extrusion, and gamma-sterilization processes designed to eliminate cross-contamination in analytical and therapeutic workflows. Plastic materials dominate unit economics due to thermoformability and disposability, while glass retains structural importance in high-temperature sterilization and solvent-resistant applications. Pharmaceutical companies represent the fastest-growing end-user segment as outsourced manufacturing and cell therapy production expand, whereas research laboratories remain the mature volume anchor with predictable procurement cycles.
FDA oversight of single-use bioprocessing equipment, USP Class VI biological reactivity testing, and OSHA bloodborne pathogen standards collectively elevate barrier-to-entry and compliance costs for domestic manufacturers. EPA hazardous waste rules for contaminated laboratory plastics further shape disposal logistics and material selection criteria. Stakeholders must monitor evolving USP and FDA guidance on extractables and leachables to anticipate qualification burden shifts.
Market Dynamics
Single-use bioprocessing adoption is compressing multi-step sterilization workflows into integrated disposable assemblies, forcing capital equipment suppliers to reposition around consumable pull-through and qualification services.
Growth Catalysts
- Cell Therapy Manufacturing Scale-Up:Autologous and allogeneic cell therapy producers in Massachusetts and North Carolina corridors are converting stainless steel suites to flexible single-use trains, driving pipette, tubing, and bag demand.
- FDA Single-Use System Guidance:The 2023 guidance on extractables and leachables qualification is standardizing validation protocols, reducing buyer uncertainty and accelerating procurement cycles for USP Class VI-certified assemblies.
- Outsourced Pharmaceutical Production:Contract development and manufacturing organizations are expanding captive single-use capacity to serve biopharma clients, concentrating demand for gamma-sterilized containment vessels and connectors.
Market Restraints
- Resin Supply Concentration:Medical-grade polypropylene and polycarbonate feedstock production concentrates among a handful of Gulf Coast petrochemical complexes, exposing converters to force majeure risk and input cost volatility.
- Gamma Sterilization Capacity Bottleneck:Cobalt-60 sourcing constraints and limited irradiation facility availability in the Midwest and Southeast are extending lead times for sterile-ready products.
- Plastic Waste Regulatory Pressure:EPA hazardous waste rules for contaminated laboratory plastics are elevating disposal logistics costs and complicating material selection for multi-layer film constructions.
Strategic Opportunities
- Advanced Therapy CDMO Expansion:Texas and California biotech clusters are underpenetrated relative to Massachusetts and North Carolina, offering greenfield site opportunities for integrated single-use suppliers.
- Closed-System Aseptic Processing:Convergence of single-use bioreactors with isolator technology is opening qualification service revenue streams for distributors with in-house validation engineering.
- Domestic Manufacturing Incentives:IRA clean energy and domestic production provisions are subsidizing US-based injection molding and extrusion capacity expansion for medical-grade polymers.
Industry Challenges
- Extractables Testing Talent Scarcity:Analytical chemists with USP Class VI and ISO 10993 biocompatibility expertise command premium compensation, constraining quality department scaling at mid-size converters.
- Legacy Equipment Integration:Single-use assemblies must interface with existing stainless steel infrastructure at research laboratories, requiring custom adapter development and extended validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Laboratory Disposable Products Market |
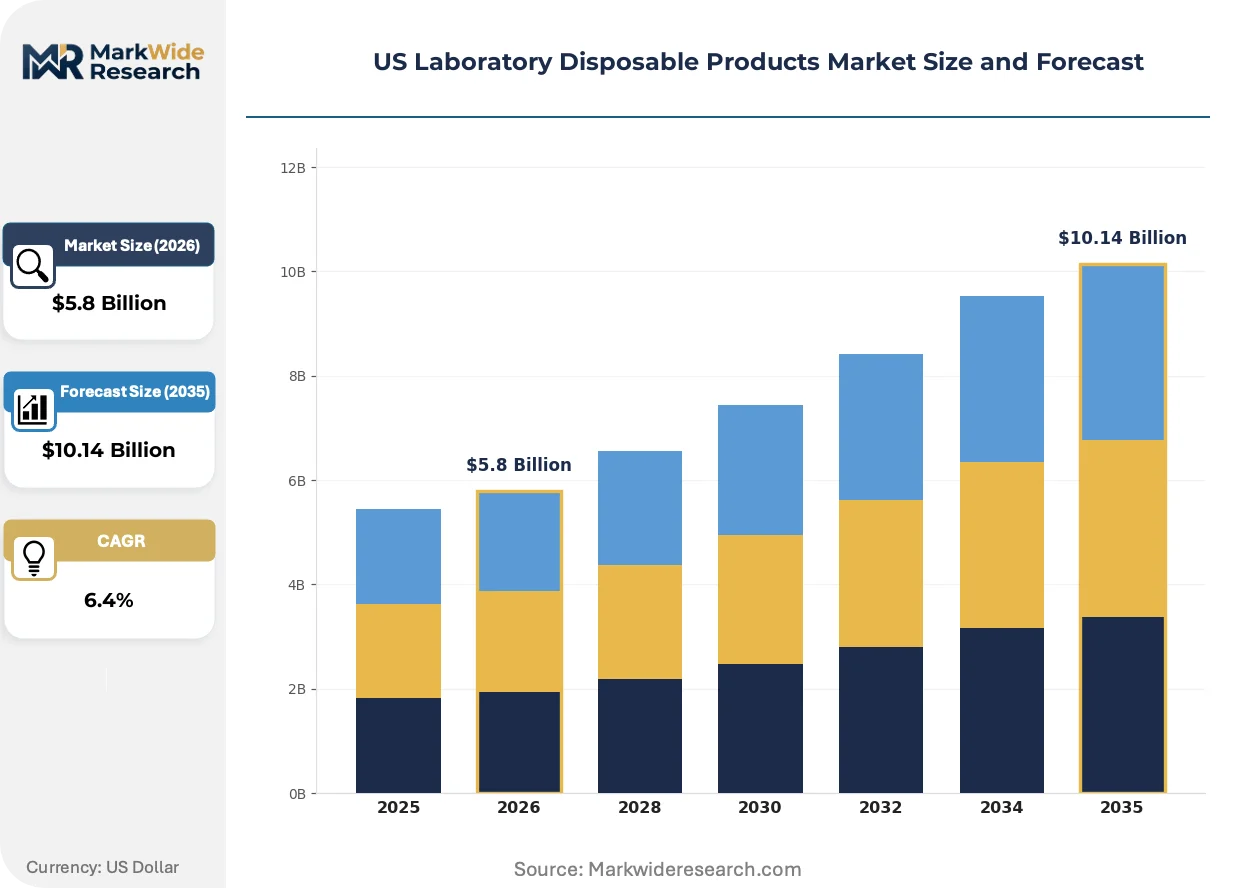
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipettes, Gloves, Tubing, Petri Dishes Material: Plastic, Paper, Glass, Aluminum End User: Research Laboratories, Clinical Laboratories, Educational Institutions, Pharmaceutical Companies Application: Sample Collection, Sterilization, Preservation, Testing |
| Companies Covered | Becton, Dickinson and Company, Agilent Technologies, Inc., Cardinal Health, Inc., Dynarex Corporation, McKesson Corporation, Thermo Fisher Scientific Inc., Medline Industries, Inc., Thomas Scientific LLC, Avantor, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Laboratory Disposable Products Market Strategic Shifts & Innovations
Pre-sterilized, ready-to-use assemblies are displacing in-house processing workflows, compressing facility capital requirements and redefining supplier-customer relationships around technical service rather than equipment ownership.
Multi-layer coextruded films with ethylene vinyl alcohol oxygen barriers are collapsing the distinction between glass and plastic containment for cell culture applications. Biopharma manufacturers in North Carolina are adopting these films for extended-duration perfusion processes. The technology is collapsing upstream material qualification burdens by consolidating barrier, strength, and extractables performance into single-source film structures.
FDA's evolving guidance on single-use bioprocessing equipment extractables profiles is tightening documentation requirements for polymer additives and processing aids. Manufacturers must now submit comprehensive migration data across pH and temperature ranges. Pharmaceutical companies in Massachusetts are responding by pre-qualifying suppliers with established extractables libraries, favoring incumbents with historical testing investment.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships at hospital-affiliated laboratories. Texas and California health systems are centralizing disposable purchasing through specialized distributors with inventory management capabilities. Academic research institutions remain fragmented, creating a two-speed channel structure with diverging service intensity requirements.
US Laboratory Disposable Products Market Segmentation
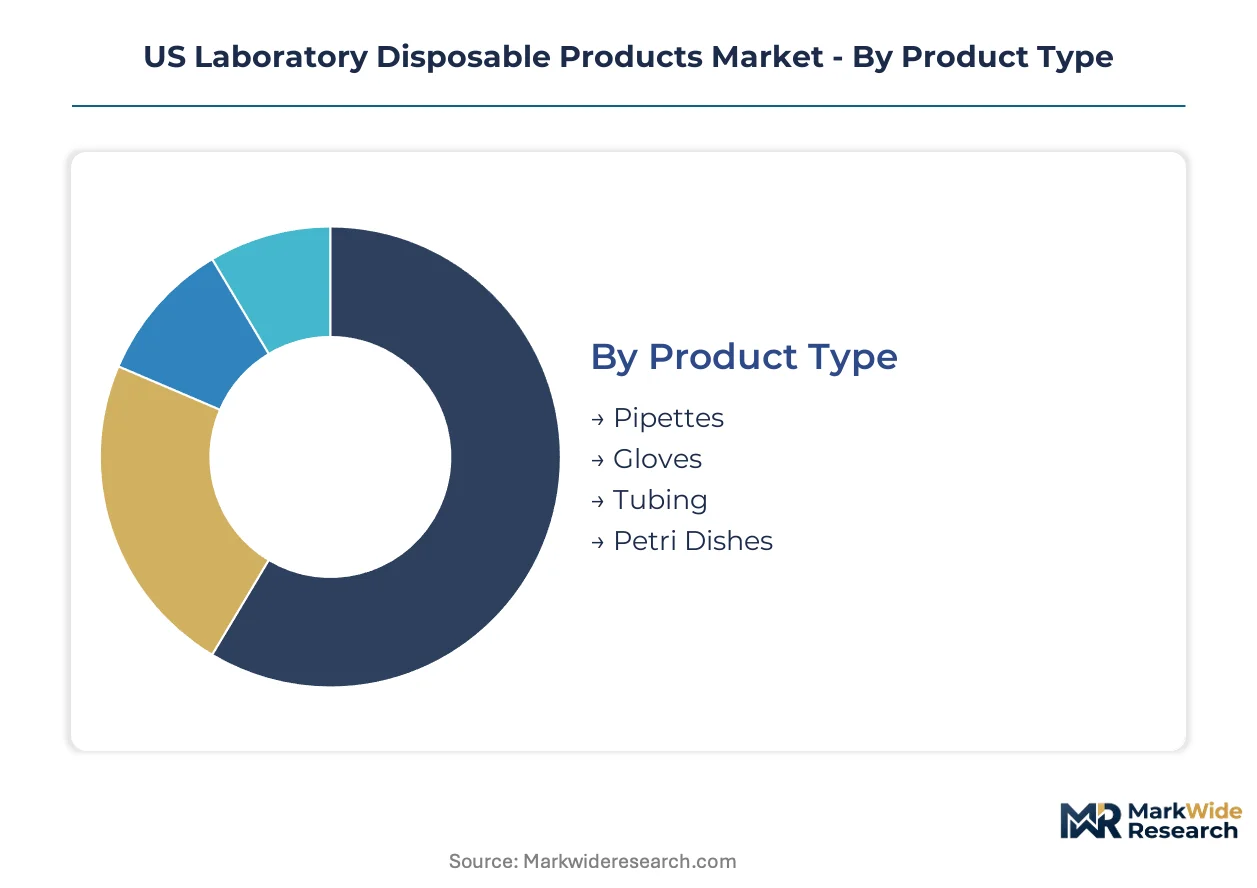
Segmentation in the US laboratory disposable products market reveals divergent procurement rhythms and qualification burdens across product categories. Cycle times for consumables range from daily glove replacement to multi-year validation of single-use bioprocessing assemblies.
Product Type:
Gloves and pipettes turn over fastest with daily consumption in high-throughput facilities, while tubing assemblies and petri dishes operate on longer replenishment cycles tied to batch validation protocols.
- Pipettes:Polypropylene and polystyrene single-channel and multi-channel designs dominate analytical workflows. Massachusetts biotech clusters drive demand for calibrated disposable pipettes that eliminate cross-contamination in cell therapy production.
- Gloves:Nitrile and latex formulations meeting OSHA bloodborne pathogen standards protect laboratory personnel. North Carolina pharmaceutical manufacturing facilities consume bulk quantities through automated dispenser systems integrated with inventory management platforms.
- Tubing:Medical-grade silicone and thermoplastic elastomer configurations serve fluid transfer in bioprocessing.
- Petri Dishes:Polystyrene and borosilicate glass formats support cell culture and microbiological applications.
Pipettes anchor the volume base while tubing gains share at the steepest rate.
Material:
Cost tiers separate commodity thermoplastics from specialized barrier films and inert substrates, with pricing stratifying across performance requirements rather than brand differentiation.
- Plastic:Polypropylene, polycarbonate, and polystyrene formulations certified to USP Class VI standards constitute the dominant substrate category. FDA extractables guidance is compressing supplier qualification timelines for Massachusetts biopharma manufacturers adopting multi-layer coextruded film technologies.
- Glass:Borosilicate and soda-lime compositions retain structural importance in high-temperature sterilization and solvent-resistant applications. Research laboratories in North Carolina maintain glass petri dish inventories for legacy protocol compliance.
- Paper:Medical-grade cellulose substrates serve filtration and sterilization wrap functions.
- Aluminum:Anodized foil configurations provide barrier protection and thermal conductivity.
Plastic commands the procurement volume base while glass preserves niche positioning in specialized applications.
End User:
Customer type determines service intensity, with pharmaceutical companies demanding qualification documentation and research laboratories prioritizing catalog breadth and price efficiency.
- Pharmaceutical Companies:Biopharma manufacturers and contract development organizations require gamma-sterilized single-use assemblies with comprehensive extractables documentation. North Carolina and Massachusetts corridors concentrate demand for USP Class VI-certified containment vessels.
- Research Laboratories:Academic and government institutions operate on predictable procurement cycles with established vendor relationships. Fragmented purchasing patterns across Texas and California institutions resist consolidation through group purchasing organizations.
- Clinical Laboratories:Hospital-affiliated diagnostic facilities source through specialized distributors with inventory management capabilities.
- Educational Institutions:University teaching laboratories prioritize cost efficiency over qualification depth.
Research laboratories anchor the volume base while pharmaceutical companies expand most quickly.
Application:
Application scope spans the specimen lifecycle from acquisition through archival, with each phase imposing distinct material and sterility requirements.
- Sample Collection:Swabs, collection vessels, and transport media maintain chain of custody integrity. FDA oversight of specimen handling elevates barrier requirements for clinical diagnostic workflows.
- Sterilization:Autoclave bags, indicator strips, and wrap materials support terminal sterilization processes. Gamma irradiation capacity constraints in the Midwest and Southeast extend lead times for sterile-ready configurations.
- Preservation:Cryogenic vials and barrier films protect specimen viability during storage.
- Testing:Assay plates, reaction vessels, and diagnostic consumables enable analytical procedures.
Testing anchors the volume base while sterilization applications climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade resin conversion clusters along the Gulf Coast feed injection molding operations across the Midwest and Southeast, while gamma sterilization infrastructure concentrates in Ohio and Illinois corridors. Massachusetts and North Carolina biotech manufacturing anchors demand for USP Class VI-certified assemblies.
Massachusetts
Cell therapy manufacturers in Cambridge and Worcester drive calibrated pipette and single-use bioreactor bag consumption. FDA extractables guidance compliance costs elevate supplier qualification barriers for Boston-area biopharma facilities. The Route 128 corridor concentrates autologous therapy production converting stainless steel suites to disposable trains.
North Carolina
Research Triangle Park pharmaceutical manufacturing consumes bulk gamma-sterilized tubing and containment vessels through automated procurement systems. OSHA bloodborne pathogen standards shape nitrile glove specifications for Durham and Chapel Hill clinical operations. The Piedmont Triad anchors contract development organization expansion with captive single-use capacity.
Texas
Houston and Dallas-Fort Worth health systems centralize disposable purchasing through specialized distributors with inventory management platforms. EPA hazardous waste rules for contaminated laboratory plastics complicate disposal logistics for Gulf Coast petrochemical research facilities. The Texas Medical Center represents underpenetrated demand relative to Northeast corridors.
California
Bay Area biotech clusters and San Diego life science hubs source multi-layer coextruded films for extended-duration cell culture processes. California environmental regulations on plastic waste accelerate material selection scrutiny for Los Angeles and San Francisco metropolitan laboratories. The state's academic research institutions resist group purchasing organization consolidation.
Illinois
Chicago metropolitan clinical laboratories and pharmaceutical distribution centers anchor Midwest demand for sterile-ready petri dishes and assay plates. Gamma irradiation facility capacity constraints in the state extend lead times for sterilization-dependent products. The region's logistics infrastructure supports distribution to secondary Midwest markets.
US Laboratory Disposable Products Market Key Industry Players
Diversified life science conglomerates and specialized medical supply distributors split the market into distinct competitive spheres. Three strategic archetypes dominate: integrated conglomerates with captive polymer conversion, specialized distributors with validation engineering capabilities, and commodity-scale manufacturers competing on hospital channel control. Consolidation through acquisition of regional sterilization facilities and backward integration into medical-grade resin sourcing represent the dominant competitive moves.
Within the integrated conglomerate tier, Thermo Fisher Scientific Inc. and Becton, Dickinson and Company exemplify archetypes combining manufacturing scale with distribution infrastructure. Medline Industries, Inc. occupies a position emphasizing hospital and clinical laboratory channel density. These three entities anchor competitive positioning around distinct vectors: conglomerates leverage supply chain integration, specialists concentrate qualification services, and scale players optimize procurement relationships with group purchasing organizations.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Agilent Technologies, Inc. |
| Cardinal Health, Inc. |
| Dynarex Corporation |
| McKesson Corporation |
| Thermo Fisher Scientific Inc. |
| Medline Industries, Inc. |
| Thomas Scientific LLC |
| Avantor, Inc. |
| Others |
Cost & Logistics Intelligence
Gamma sterilization capacity bottlenecks in the Midwest and Southeast determine both the pricing tier spreads for sterile-ready products and the geographic shape of US laboratory disposable supply chains, forcing buyers into longer-term contract commitments or premium spot purchases.
Pricing Analysis
FDA extractables and leachables guidance dictates the pricing tier structure for USP Class VI-certified assemblies, separating suppliers with historical testing investment from commodity converters. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and validation documentation completeness. Cost compression in economy-grade gloves and pipettes is intensifying because hospital group purchasing organizations consolidate procurement volumes. Research laboratories exhibit highest price sensitivity due to fragmented purchasing and grant-funded budgets, while pharmaceutical companies prioritize qualification depth over unit cost.
Supply Chain Analysis
Medical-grade polypropylene and polycarbonate feedstock production concentrates in Gulf Coast petrochemical complexes, with secondary conversion clusters across the Midwest and Southeast. Raw material sourcing draws from domestic resin producers, cobalt-60 suppliers for gamma irradiation, and specialized additive compounders for USP Class VI compliance. Single-source vulnerability in gamma sterilization infrastructure exposes converters to extended lead times during facility maintenance or isotope supply disruptions. Distribution runs through specialized medical supply distributors with validation engineering capabilities, bypassing direct manufacturer relationships for hospital-affiliated laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable glass and stainless steel alternatives threaten single-use plastic incumbents as EPA hazardous waste rules tighten disposal economics, compelling suppliers to demonstrate irreplaceable contamination control value.
For Market Incumbents: Pre-empt regulatory qualification barriers by investing in extractables library expansion ahead of FDA guidance evolution. Consolidate gamma sterilization capacity through acquisition of regional irradiation facilities in Ohio and Illinois corridors. Backward integration into medical-grade resin sourcing mitigates Gulf Coast petrochemical concentration risk. For New Entrants and Emerging Players: Establish a beachhead in Texas and California biotech clusters where group purchasing organization penetration remains incomplete relative to Northeast corridors. Target academic research institutions with catalog breadth and price efficiency rather than qualification depth. A distributor partnership model with inventory management platforms accelerates channel access without captive manufacturing investment. For Investors and Strategic Acquirers: FDA single-use system guidance evolution reshapes the acquisition landscape toward suppliers with established USP Class VI testing infrastructure and documented extractables profiles. Mid-size converters with analytical chemistry capabilities present consolidation targets as qualification burdens escalate. Watch gamma sterilization capacity utilization rates as the inflection signal for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Extractables Library Expansion | FDA guidance compliance favors incumbents with historical biocompatibility testing investment. |
| Gamma Sterilization Facility Acquisition | Cobalt-60 sourcing constraints make regional irradiation capacity a strategic chokepoint asset. |
| Multi-Layer Coextruded Film Development | Ethylene vinyl oxygen barriers collapse glass-plastic performance distinctions in cell culture. |
| CDMO Partnership Structuring | Contract development organization captive capacity concentrates demand for qualified assemblies. |
| Closed-System Aseptic Processing Integration | Isolator convergence with single-use bioreactors opens qualification service revenue streams. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with bioprocessing engineers, laboratory procurement managers, regulatory affairs specialists, and gamma sterilization facility operators; and secondary validation against FDA guidance documents, USP monographs, EPA hazardous waste regulations, and hospital group purchasing organization contract databases. Bottom-up demand modeling across end-user segments triangulated with top-down market sizing from resin consumption and sterilization capacity data.
Forecast inputs considered product type segmentation, material certification tiers, end-user procurement patterns, and application-specific validation requirements across the analysis window. CAGRs derived from segment-level volume trajectories weighted by pricing tier mixes. Industry-specific inputs incorporated cell therapy manufacturing scale-up curves, outsourced pharmaceutical production expansion rates, and regulatory qualification timeline compression effects.
Stress conditions across resin price volatility, gamma sterilization capacity constraints, and EPA disposal rule enforcement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against third-party medical supply distributor inventory turnover benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
Cytotoxicity Assays Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
Histopathology Services Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market