
 Global Cell Viability Assays Market | 2026-2036
Global Cell Viability Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Viability Assays Market Foresight
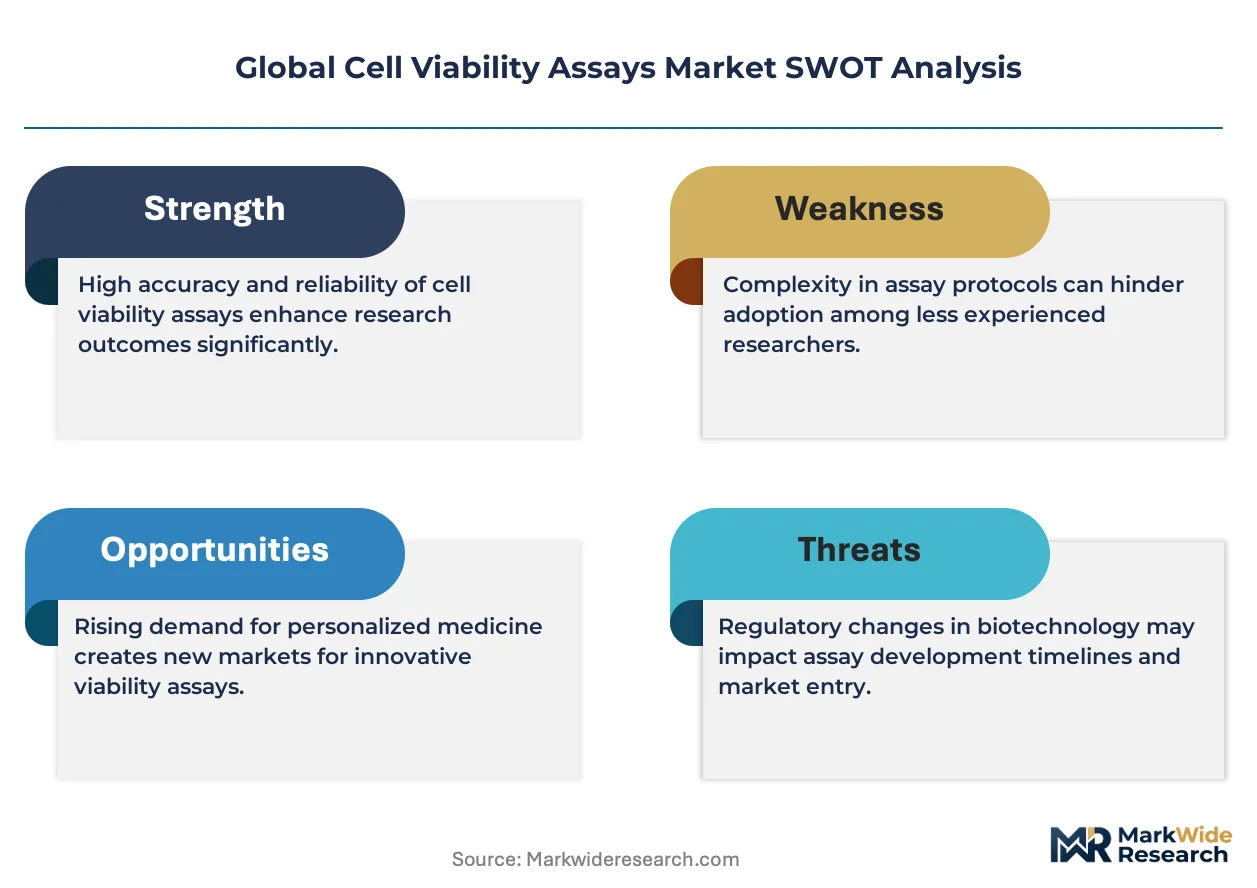
Resazurin-based reagents is broadening access to real-time kinetic monitoring without cell lysis steps. Thermo Fisher Scientific leverages its reagent-manufacturing scale to supply standardized alamarBlue formulations across diagnostic and research channels. Promega Corporation differentiates through bioluminescent ATP detection chemistry that sustains premium positioning in high-sensitivity drug-screening panels.
Cell viability assays are biochemical methods that quantify metabolic activity, membrane integrity, or cellular proliferation to determine living cell populations in a sample; these techniques typically rely on colorimetric, fluorometric, or luminescent readouts measured at defined wavelength ranges using microplate spectrophotometers. Their primary commercial purpose is to generate reproducible dose-response data for pharmaceutical toxicology, oncology drug discovery, and regenerative medicine quality control. ATP Assay formats command the strongest margin pools due to reagent-consumable recurring revenue and instrument lock-in effects. Automated deployment configurations represent the fastest-expanding segment as pharmaceutical companies replace manual pipetting stations to compress compound-screening cycle times.
The FDA's in vitro toxicology guidelines and the EPA's ToxCast program collectively elevate assay validation standards for regulatory submission packages. ISO 10993 biocompatibility testing protocols further standardize viability method selection across medical device developers and contract laboratories. Stakeholders must weigh reagent cost against data reproducibility when selecting between colorimetric and bioluminescent platforms for multiplexed screening workflows.
Market Dynamics
Automated liquid-handling platforms are compressing assay turnaround times from days to hours, forcing reagent suppliers to standardize kit formats for robotic compatibility and real-time data capture.
Growth Catalysts
- FDA Modernization Act 2.0:The mandate for in vitro toxicology data accelerates contract research organization investment in validated viability platforms for preclinical submission packages.
- Biopharmaceutical pipeline expansion:Oncology and cell therapy developers in Boston and San Diego clusters sustain high-throughput screening consumption for lead optimization.
- Resazurin chemistry:Non-lytic kinetic monitoring enables longitudinal studies without endpoint destruction, broadening access for regenerative medicine quality control.
Market Restraints
- Reagent cost volatility:Luciferase and specialized fluorophores concentrate supply among three contract fermentation houses, exposing buyers to batch-to-batch pricing swings.
- Technical limitation:ATP assays remain incompatible with certain antibiotic classes, forcing parallel method validation and redundant workflow design.
- Substitution threat:Label-free impedance sensing platforms bypass consumable dependencies entirely for proliferation monitoring in adherent cultures.
Strategic Opportunities
- India biopharma manufacturing:CDSCO's streamlined IND review timelines attract multinational sponsors seeking regional CRO partnerships for toxicology screening.
- 3D organoid models:Spheroid viability workflows demand specialized reagent penetration and z-stack imaging integration not served by legacy 2D kits.
- EU Green Deal chemistry:REACH restrictions on hazardous dye intermediates create first-mover advantage for aqueous-formulation innovators.
Industry Challenges
- Multiplexing expertise gap:Simultaneous ATP and membrane integrity readouts require rare cross-training in fluorescence lifetime instrumentation and assay biochemistry.
- ISO 10993 certification timelines:Biocompatibility testing protocol validation extends 18-24 months, delaying product launch windows for device-adjacent reagent lines.
- Legacy LIMS integration:Automated plate readers generate structured data formats incompatible with decade-old pharmaceutical data architecture, requiring middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Viability Assays Market |
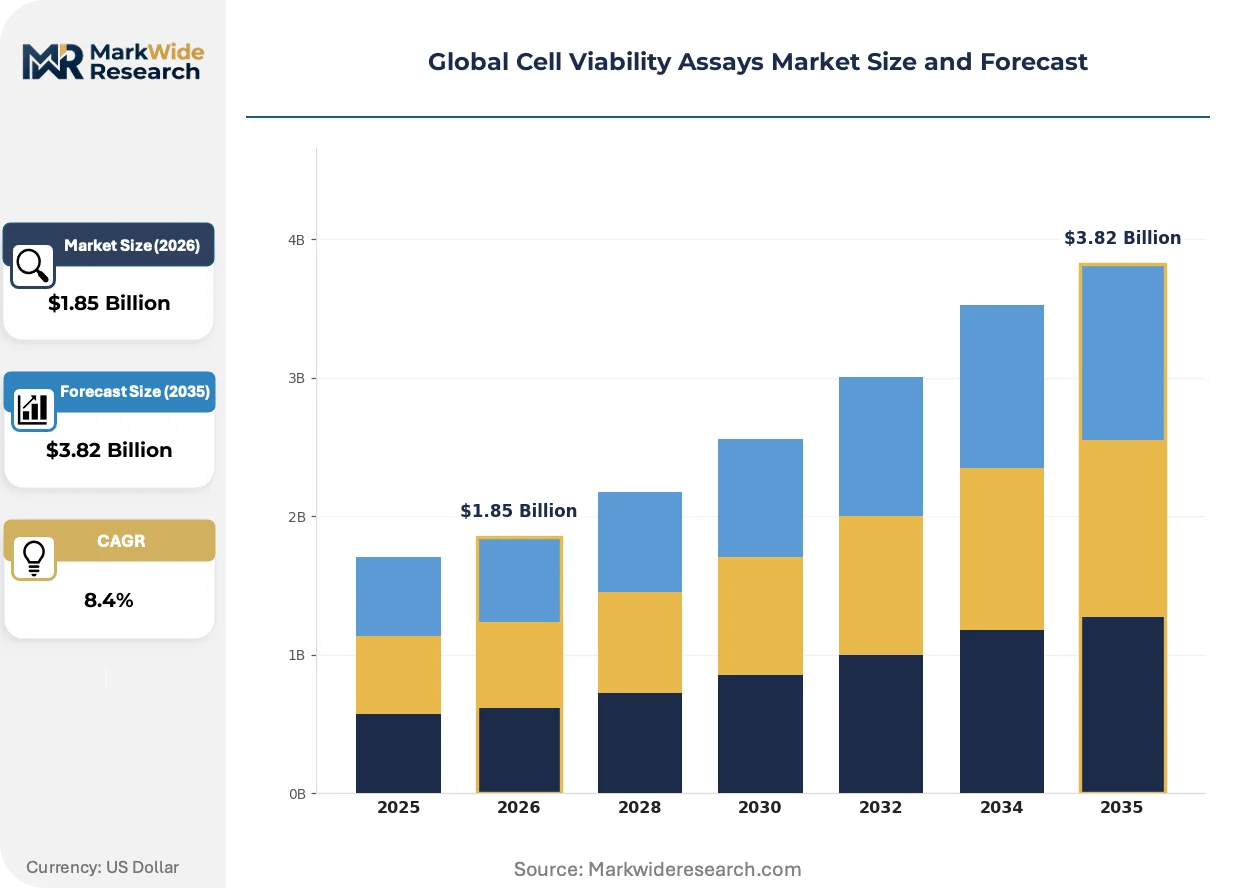
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MTT Assay, Trypan Blue, Resazurin, ATP Assay, LDH Assay Application: Drug Screening, Toxicity Testing, Cancer Research, Cell Proliferation, Genotoxicity End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research, Contract Research Organizations, Diagnostic Labs Deployment: Manual, Semi-automated, Automated, High-throughput Screening, Multiplex Assays |
| Companies Covered | Thermo Fisher Scientific, Merck, Bio-Rad Laboratories, Becton Dickinson and Company, GE Healthcare, PerkinElmer, Promega Corporation, Abcam plc, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Viability Assays Market Shifts & Advancements
Real-time kinetic readouts and miniaturized reaction volumes are displacing endpoint assays across toxicology workflows, compressing compound characterization cycles while demanding new instrument-reagent bundling strategies.
Bioluminescent ATP detection is overtaking colorimetric MTT reduction for high-sensitivity drug screening panels. Large-molecule discovery groups at contract research organizations in the United States and Germany are adopting the format for picomolar detection limits. The shift is overtaking legacy absorbance-based workflows and locking buyers into reagent-instrument ecosystems with recurring consumable commitments.
REACH authorization requirements for certain tetrazolium salt precursors are restricting formulation options for European manufacturers. The regulation forces reformulation toward aqueous-stable alternatives or regional supply chain segmentation. Toxicology service providers in Germany and the Netherlands are accelerating validation of resazurin substitutes to maintain regulatory submission readiness.
Consolidated procurement through single-source reagent-instrument contracts is displacing standalone kit purchasing at top-twenty pharmaceutical sponsors. The model bundles annual consumable commitments with preferred vendor status and technical support tiers. This concentration is most visible in United States and Swiss biopharma clusters where procurement functions centralize screening infrastructure decisions.
Global Cell Viability Assays Market Segmentation
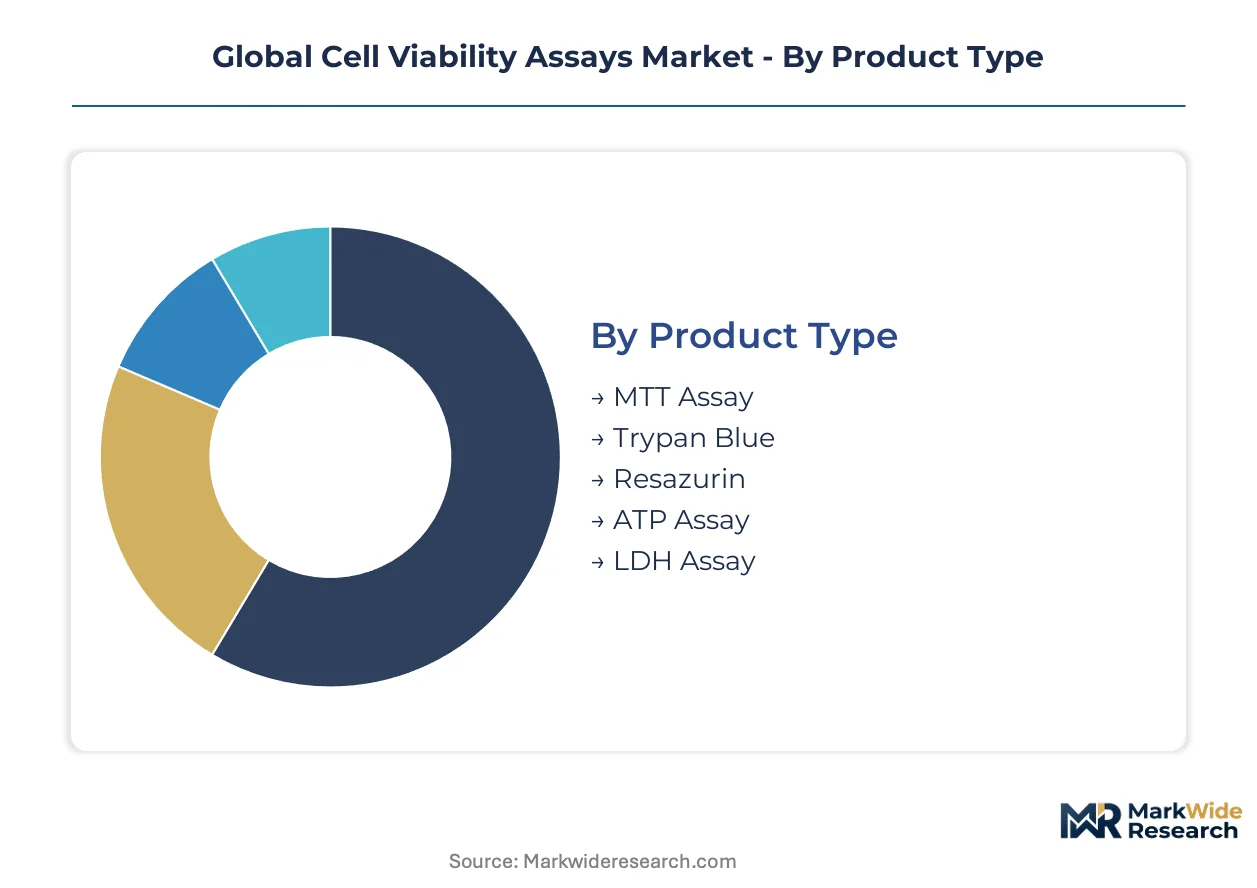
Cell viability assay segmentation reveals distinct technology-performance tradeoffs that dictate procurement patterns across pharmaceutical workflows. Reagent chemistry, automation readiness, and end-user scale each create separate purchasing decision trees with divergent margin structures.
Product Type:
Colorimetric and bioluminescent detection chemistries differentiate on sensitivity thresholds, reagent stability, and consumable economics.
- ATP Assay:Bioluminescent detection of adenosine triphosphate delivers picomolar sensitivity for high-throughput oncology screening. Contract research organizations in the United States and Germany concentrate procurement here for lead optimization panels where signal-to-noise ratios determine compound progression decisions.
- Resazurin:Non-lytic reduction chemistry enables real-time kinetic monitoring across multi-day regenerative medicine studies. Boston and San Diego biotech clusters favor this format for cell therapy quality control where endpoint destruction compromises longitudinal sample integrity.
- MTT Assay:Tetrazolium salt reduction remains the reference standard for ISO 10993 biocompatibility submissions despite longer incubation protocols.
- Trypan Blue:Manual hemocytometer counting persists in academic settings with limited capital equipment budgets.
- LDH Assay:Membrane integrity detection via lactate dehydrogenase release serves cytotoxicity workflows requiring orthogonal validation.
ATP Assay leads on scale; Resazurin leads on momentum.
Application:
Workflow complexity and regulatory stringency segment demand across discovery, safety, and quality control functions.
- Drug Screening:High-throughput compound libraries require standardized viability readouts for dose-response quantification. Large-molecule discovery groups at United States-based contract research organizations drive format standardization to compress cycle times from hit identification to lead nomination.
- Toxicity Testing:FDA Modernization Act 2.0 compliance mandates in vitro data packages for IND submissions. Preclinical service providers in Germany and the Netherlands validate assay panels against EPA ToxCast reference compounds to maintain regulatory submission readiness.
- Cancer Research:3D spheroid models demand specialized reagent penetration and z-stack imaging integration.
- Cell Proliferation:Label-free impedance alternatives threaten consumable-dependent formats in adherent culture monitoring.
- Genotoxicity:Ames test adjuncts require multiplexed viability controls for metabolic activation protocols.
Drug Screening captures the largest volume commitment; Toxicity Testing faces the steepest regulatory tailwinds.
End User:
Capital intensity and outsourcing strategy separate in-house screening infrastructure from externalized service consumption.
- Contract Research Organizations:Toxicology and pharmacology service providers aggregate demand across sponsor portfolios. United States and Swiss clusters centralize procurement through single-source reagent-instrument contracts that bundle annual consumable commitments with preferred vendor status.
- Pharmaceutical Companies:Top-twenty sponsors maintain internal high-throughput platforms for proprietary target classes while outsourcing routine safety screening.
- Biotechnology Firms:Cell therapy developers in Boston and San Diego sustain specialized regenerative medicine assay consumption.
- Academic Research:Grant-funded laboratories prioritize cost-per-assay over throughput sensitivity.
- Diagnostic Labs:Clinical reference standards drive ISO-certified reagent procurement for companion diagnostic development.
Contract Research Organizations lead on aggregate volume; Biotechnology Firms expand most quickly.
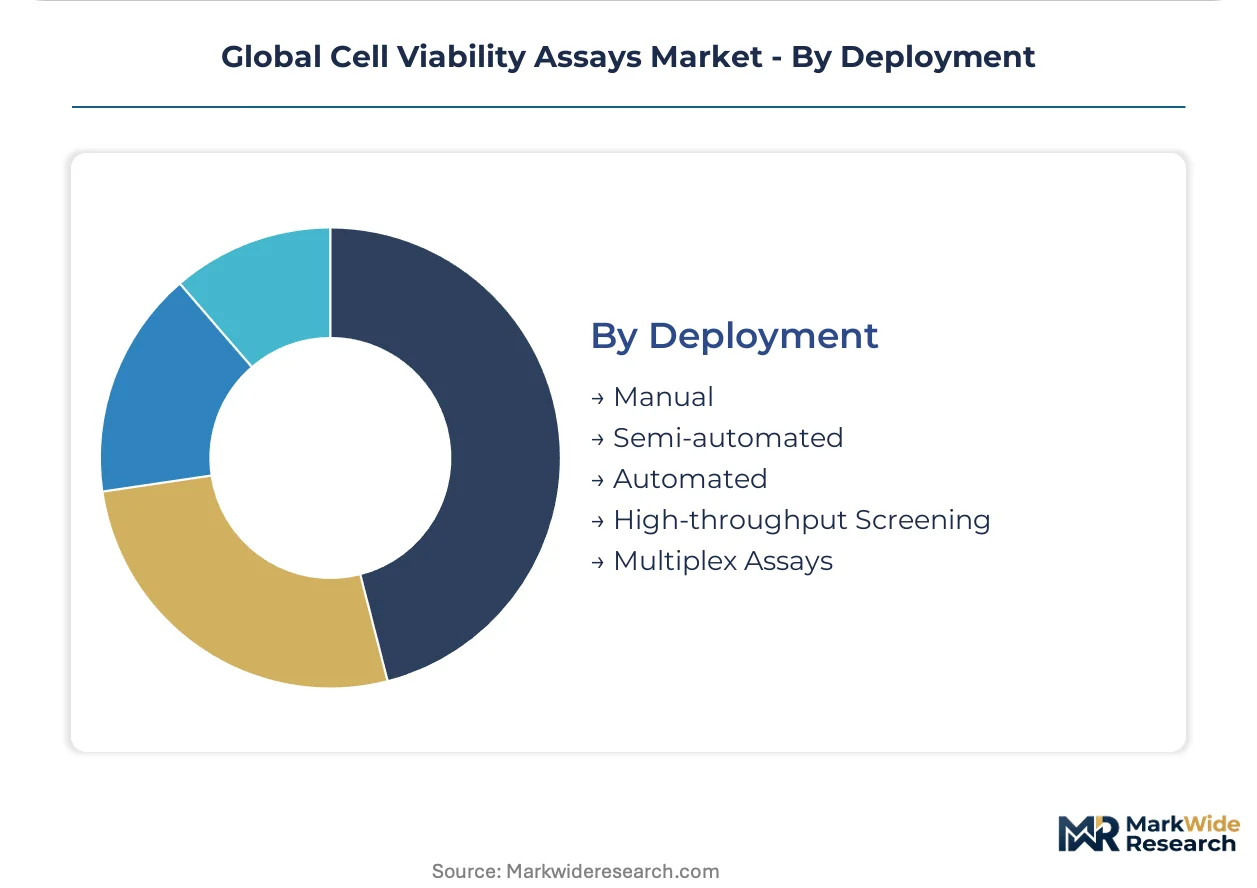
Deployment:
Automation depth determines throughput ceiling, data reproducibility, and labor cost structure.
- Automated:Integrated liquid-handling platforms compress assay turnaround from days to hours. Pharmaceutical procurement functions in the United States and Switzerland displace manual pipetting stations to reduce compound-screening cycle times and operator-dependent variability.
- High-throughput Screening:1536-well miniaturization and acoustic dispensing enable ultra-parallel compound characterization. Large-molecule discovery groups adopt this configuration for primary screening campaigns where well density directly correlates with library coverage economics.
- Semi-automated:Plate washer and reader modules bridge manual and fully integrated workflows.
- Manual:Low-volume academic settings retain multichannel pipetting for method development flexibility.
- Multiplex Assays:Simultaneous ATP and membrane integrity readouts demand cross-training in fluorescence lifetime instrumentation.
Automated deployment leads on installed base expansion; High-throughput Screening gains share fastest in new capital allocations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and San Diego biotech clusters sustain the highest throughput assay consumption globally, driven by concentrated cell therapy development and oncology drug discovery pipelines. FDA Modernization Act 2.0 compliance requirements redirect contract research investment toward validated in vitro toxicology platforms across multiple jurisdictions.
United States
Biopharmaceutical pipeline expansion in Massachusetts and California drives demand for high-sensitivity ATP detection formats. FDA toxicology data mandates under Modernization Act 2.0 accelerate contract research organization investment in validated viability platforms. Boston and San Diego clusters concentrate procurement through single-source reagent-instrument contracts.
Germany
Toxicology service providers validate assay panels against EPA ToxCast reference compounds for regulatory submission readiness. ECHA REACH authorization requirements for tetrazolium salt precursors force reformulation toward aqueous-stable alternatives. Frankfurt and Heidelberg laboratory clusters accelerate resazurin substitute validation.
China
NMPA streamlined IND review timelines attract multinational sponsors seeking regional contract research partnerships. Dual carbon goals under national environmental policy drive aqueous-formulation chemistry adoption. Shanghai and Suzhou biotech parks expand high-throughput screening infrastructure.
Switzerland
Swissmedic biocompatibility standards elevate ISO 10993 protocol validation requirements for medical device-adjacent reagent lines. Basel pharmaceutical procurement functions centralize screening infrastructure decisions through consolidated vendor contracts. Zurich contract laboratories specialize in regenerative medicine quality control workflows.
India
CDSCO streamlined IND review timelines attract multinational sponsors seeking regional contract research organization partnerships for toxicology screening. Hyderabad and Bangalore biotech clusters expand automated liquid-handling platform deployment. National pharmaceutical regulator mandates align with international validation standards.
Global Cell Viability Assays Market Competitive Landscape
Consolidated procurement through single-source reagent-instrument contracts dominates the current landscape, displacing standalone kit purchasing at top-twenty pharmaceutical sponsors. The vendor base stratifies across three tiers: diversified life science conglomerates with captive reagent manufacturing, specialized biochemical assay developers, and regional distribution intermediaries. Technology licensing and portfolio diversification represent the principal competitive moves, with players bundling annual consumable commitments into preferred vendor status agreements.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck occupy positions anchored by reagent-manufacturing scale and diagnostic channel reach. Promega Corporation exemplifies the specialized biochemical developer archetype, differentiated by bioluminescent detection chemistry for high-sensitivity applications. These three entities collectively represent the competitive structure: scale-driven supply security, premium sensitivity positioning, and integrated instrument-reagent ecosystems.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck |
| Bio-Rad Laboratories |
| Becton Dickinson and Company |
| GE Healthcare |
| PerkinElmer |
| Promega Corporation |
| Abcam plc |
| Agilent Technologies |
| Others |
Supply & Pricing Matrix
Contract research organizations in the United States and Germany concentrate procurement volumes through single-source reagent-instrument contracts, anchoring a three-tier pricing structure across premium, standard, and economy levels. This buyer concentration enables vendors to bundle annual consumable commitments with preferred vendor status, while smaller biotech clusters face transactional per-kit pricing without volume leverage.
Pricing Analysis
Luciferase and specialized fluorophore fermentation costs pass through to buyers via batch-to-batch pricing swings at three dominant contract fermentation houses. Pricing stratifies across premium, standard, and economy tiers based on sensitivity thresholds and ISO 10993 certification status. Cost compression in the standard tier is intensifying because REACH restrictions on tetrazolium salt precursors force European reformulation. Academic laboratories exhibit the highest price sensitivity due to grant-funded capital constraints, while pharmaceutical sponsors prioritize data reproducibility over per-assay cost.
Supply Chain Analysis
Specialized biochemistry PhD talent availability in Massachusetts, California, and Baden-Württemberg determines contract manufacturing location decisions for bioluminescent reagent production. Supply concentrates in the United States, Germany, and Switzerland for high-sensitivity ATP detection formats. Raw material dependencies center on luciferase enzymes, resazurin precursors, and aqueous-stable dye intermediates. Single-source vulnerability runs through the three contract fermentation houses supplying enzyme feedstocks. Distribution runs through direct vendor relationships with top-twenty pharmaceutical sponsors and regional distribution intermediaries serving academic and mid-tier biotech accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cell Viability Assays Market functions as a geographic-arbitrage play where CDSCO's streamlined IND review timelines in India attract multinational sponsors seeking lower-cost toxicology screening alternatives to FDA-regulated domestic workflows.
For Market Incumbents: Extend instrument-reagent ecosystem lock-in by bundling automated liquid-handling platforms with exclusive consumable supply agreements. Incumbents should deepen backward integration into luciferase fermentation capacity to neutralize supply concentration risk among the three dominant contract houses. Label-free impedance sensing platforms threaten consumable-dependent revenue streams; defensive patent positioning around kinetic readout algorithms preserves differentiation. For New Entrants and Emerging Players: Capture the 3D organoid viability workflow gap where legacy 2D kits fail at reagent penetration and z-stack imaging integration. India biopharma manufacturing clusters offer the most penetrable geography given CDSCO regulatory alignment with international validation standards. A go-to-market angle anchored in aqueous-formulation chemistry addresses EU Green Deal REACH restrictions while positioning against incumbent tetrazolium-dependent portfolios. For Investors and Strategic Acquirers: Life science conglomerates with captive diagnostic channels are the most active acquirers in this space, seeking specialized biochemical assay developers to fill portfolio gaps. The long-term viability window hinges on regenerative medicine quality control expansion and automated deployment penetration. Acquisition target archetypes include resazurin substitute innovators with validated aqueous formulations and regional CROs with established CDSCO submission track records. Practitioners should monitor EPA ToxCast program expansion and NMPA IND timeline compression for early demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | CDSCO streamlined IND reviews attract multinational sponsors to Indian CRO partnerships. |
| Backward Integration | In-house luciferase fermentation capacity neutralizes supply concentration among contract houses. |
| Green Manufacturing Transition | Aqueous-formulation chemistry aligns with EU Green Deal REACH restrictions on hazardous dyes. |
| Platform Integration | Automated liquid-handling bundling compresses assay turnaround from days to hours. |
| Geographic Expansion | Boston and San Diego biotech clusters sustain highest-throughput assay consumption globally. |
Research Methodology
Multiple input streams — executive interviews with drug development leads and regulatory affairs directors, procurement pattern analysis at contract research organizations, and secondary validation against FDA Modernization Act 2.0 implementation timelines — were reconciled to construct segment-level demand estimates. Primary fieldwork captured perspectives from toxicology service providers in Germany and the Netherlands, regenerative medicine quality control specialists in Boston and San Diego, and academic laboratory managers. Secondary sources included EPA ToxCast reference compound databases, ECHA REACH authorization status registers, CDSCO IND review procedural documents, and ISO 10993 biocompatibility testing protocol publications. Bottom-up reagent-consumable demand modeling was cross-checked against top-down pharmaceutical R&D expenditure allocation patterns.
Historical ATP assay and resazurin chemistry adoption curves were cross-referenced against expert panel assessments of automated deployment penetration and 3D organoid model transition timelines across the analysis window. Segmentation dimensions modeled encompassed detection chemistry type, application workflow, end-user capital intensity, and automation depth. CAGRs were derived from compound annual growth rate calculations applied to vendor-reported consumable shipment volumes and instrument placement data. Forecast inputs included FDA toxicology data mandate compliance deadlines, NMPA regulatory harmonization progress, and biopharmaceutical pipeline expansion in oncology and cell therapy.
Underlying measurement precision varies by segment; automated deployment and contract research organization procurement carry tighter precision than academic manual assay consumption. Forecasts reflect assumptions regarding regulatory timeline adherence and reagent chemistry substitution elasticities. Practitioners should monitor ECHA REACH authorization expansions, CDSCO IND review efficiency metrics, and label-free impedance sensing platform technical advancement for early signals warranting forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
UAE Clinical Laboratory Services Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Cytotoxicity Assays Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
LIMS Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
Laboratory Disposable Products Market