
 Middle East and Africa Clinical Laboratory Services Market | 2026-2036
Middle East and Africa Clinical Laboratory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Clinical Laboratory Services Market Foresight
Pathologist workforce density across the Middle East and Africa is collapsing below the threshold needed to serve expanding hospital networks and outpatient diagnostic demand. Sonic Healthcare Ltd leverages its international staffing protocols to sustain pathology coverage across multiple African markets. Siemens Healthineers AG anchors its regional position through integrated automation platforms that reduce manual slide review burdens. Eurofins Scientific SE competes by operating accredited reference laboratories in Gulf Cooperation Council hubs with direct air-freight links to European headquarters.
Clinical laboratory services encompass the analytical processing of human biological specimens using standardized reagent systems, automated analyzers, and quality-controlled protocols to generate diagnostic data that guides patient treatment decisions. These services employ technologies such as PCR amplification cycles, ELISA optical density measurements, and mass spectrometry ion fragmentation patterns to detect disease markers with defined sensitivity thresholds. Immunology and molecular diagnostics segments are capturing margin pools as payers shift reimbursement toward predictive and infectious disease testing. Hematology remains the highest-volume category but faces pricing compression as analyzer platforms commoditize routine complete blood count panels across hospital end users.
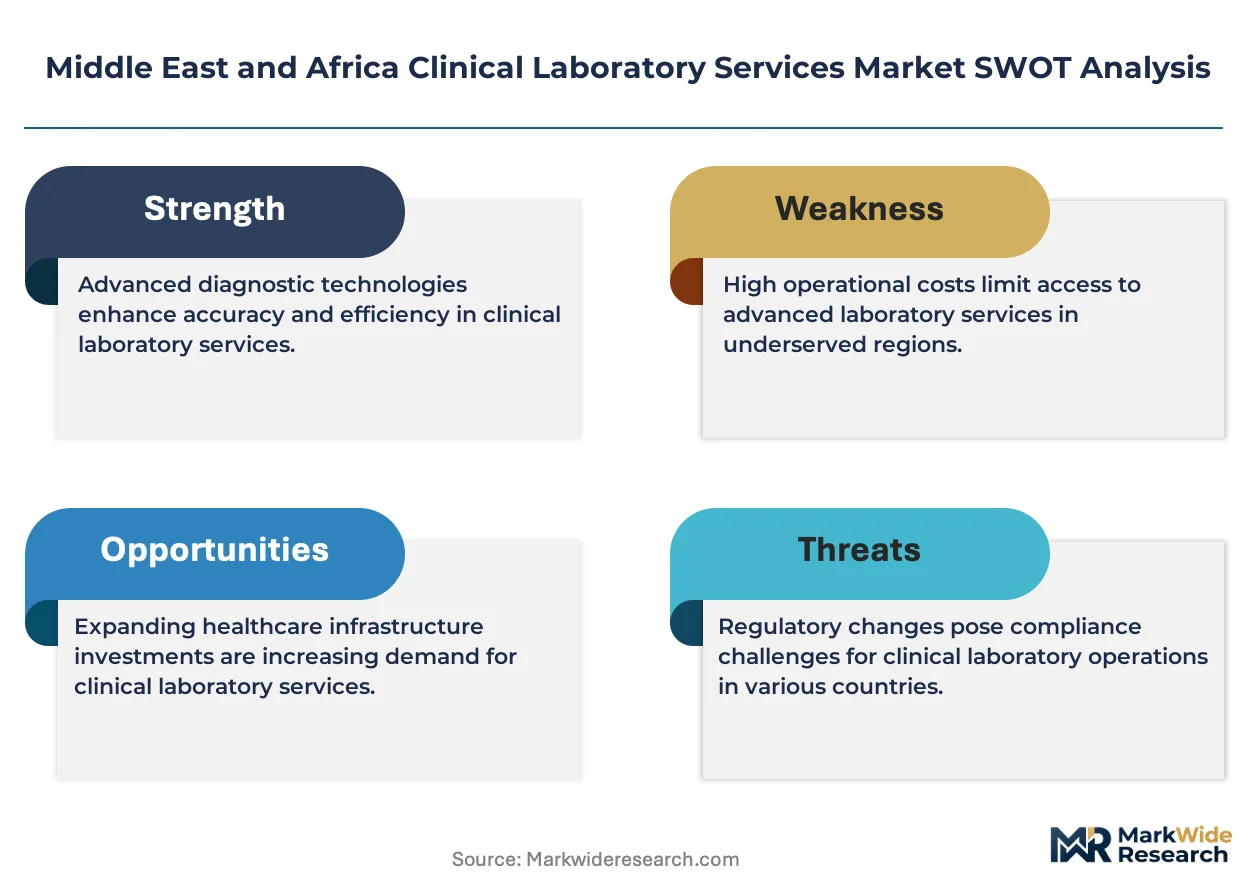
Saudi Food and Drug Authority and South African Health Products Regulatory Authority accreditation requirements are reshaping market access for independent laboratories seeking hospital contracts and insurance panel inclusion. SFDA enforcement of Good Clinical Laboratory Practice standards and SAHPRA compliance with ISO 15189 medical laboratory specifications are forcing smaller operators toward franchise or acquisition structures. Stakeholders must monitor how national health insurance expansion in Egypt and Nigeria redirects patient volume from hospital captive labs toward independent diagnostic centers with broader test menus.
Market Dynamics
Pathologist workforce collapse across the Middle East and Africa is forcing laboratory operators toward automation platforms and digital pathology workflows that reduce manual slide review dependency. This structural labor shortage is reshaping capital allocation, vendor selection criteria, and service delivery models across hospital networks and independent diagnostic chains.
Growth Catalysts
- Saudi Food and Drug Authority GCLP enforcement:Accreditation mandates are consolidating independent laboratories into franchise structures that meet hospital contract requirements and insurance panel inclusion standards.
- Molecular diagnostics menu expansion:Hospital-based laboratories in Nigeria and South Africa are adding PCR amplification and point-of-care testing capabilities to capture infectious disease and predictive testing reimbursement shifts.
- Gulf Cooperation Council health insurance expansion:National coverage programs in the UAE and Saudi Arabia are redirecting patient volume from captive hospital labs toward independent diagnostic centers with broader test menus.
Market Restraints
- Reagent import dependency:Supply concentration in European and North American manufacturers exposes regional laboratories to currency volatility and extended lead times for ELISA and mass spectrometry consumables.
- ISO 15189 compliance costs:South African Health Products Regulatory Authority specifications require capital-intensive quality management systems that smaller operators cannot sustain without acquisition or franchise partnerships.
- Analyzer platform commoditization:Routine hematology complete blood count panels face pricing compression as automated systems from multiple vendors achieve functional parity across hospital end users.
Strategic Opportunities
- Egypt national health insurance expansion:Underpenetrated outpatient diagnostic demand in Cairo and Alexandria is creating entry points for accredited independent laboratory networks with direct-to-patient collection infrastructure.
- Digital pathology and AI-assisted diagnosis convergence:Telepathology platforms paired with machine learning algorithms enable remote specialist coverage across multiple African markets without resident pathologist deployment.
- Air-freight reference laboratory hubs:Dubai and Johannesburg are emerging as logistics nodes connecting regional specimen collection to European headquarters for complex immunology and specialized molecular testing.
Industry Challenges
- Histopathology specialist scarcity:Training pipeline gaps for tissue diagnostic expertise limit expansion of cancer screening programs and surgical pathology services across secondary cities.
- Legacy LIS integration complexity:Hospital information system fragmentation forces middleware development costs for laboratories seeking to connect automated analyzers to existing patient record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Clinical Laboratory Services Market |
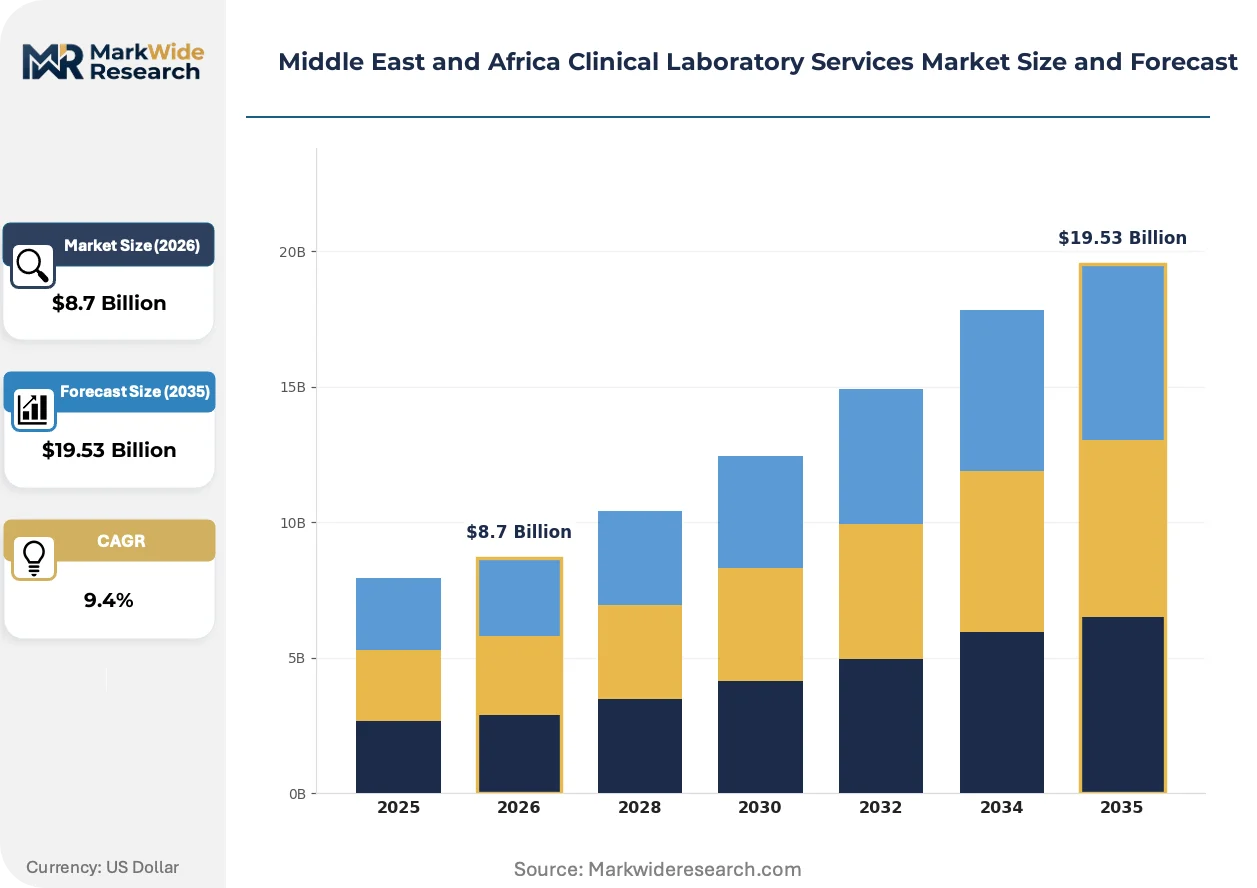
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Chemistry, Hematology, Immunology, Microbiology End User: Hospitals, Diagnostic Laboratories, Research Institutions, Blood Banks Test Type: Molecular Diagnostics, Biopsy Analysis, Clinical Trials, Point-of-Care Testing Technology: PCR, ELISA, Mass Spectrometry, Flow Cytometry |
| Companies Covered | Sonic Healthcare Ltd, Siemens Healthineers AG, Labcorp Holdings Inc, Qiagen NV, UNILABS, Quest Diagnostics Inc, Eurofins Scientific SE, Fresenius Medical Care AG, SYNLAB International GmbH, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Clinical Laboratory Services Market Shifts & Advancements
Automation and digital connectivity are restructuring how diagnostic services are produced, governed, and consumed across the Middle East and Africa. Three interconnected shifts are compressing traditional laboratory operating models while opening new service configurations.
Point-of-care molecular testing is bifurcating the diagnostic workflow between centralized high-complexity reference laboratories and distributed near-patient platforms. Hospital emergency departments and outpatient clinics in Saudi Arabia and South Africa are adopting cartridge-based PCR systems that deliver infectious disease results within 90 minutes. This technology compression is enabling same-day clinical decision-making while reducing specimen transport logistics burdens.
SFDA and SAHPRA alignment with ISO 15189 medical laboratory specifications is tightening quality management requirements for independent operators seeking accreditation renewal. The industrial consequence is accelerated consolidation as smaller laboratories sell to diagnostic chains with dedicated compliance infrastructure. Independent operators in Lagos and Johannesburg are responding by pursuing franchise relationships with accredited networks rather than standalone certification investments.
Service contracting is moving from per-test reimbursement toward capitated panel agreements that bundle routine chemistry, hematology, and selected molecular diagnostics. Hospital procurement departments in the UAE and Egypt are displacing transactional vendor relationships with multi-year exclusive partnerships that include equipment placement and reagent supply. This shift is most visible in tertiary hospital networks where laboratory directors prioritize predictable cost structures over test-by-test price negotiations.
Middle East and Africa Clinical Laboratory Services Market Segmentation
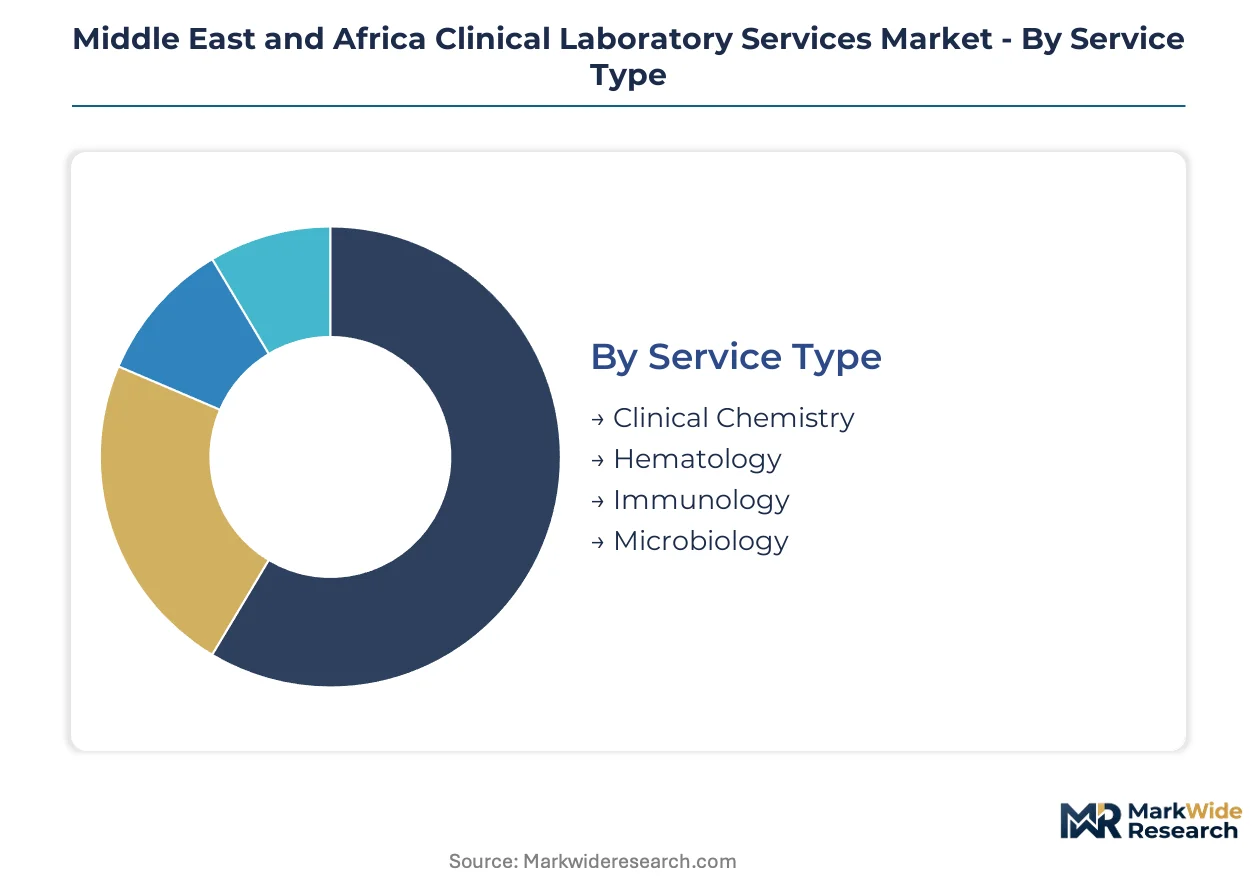
Segmentation of the Middle East and Africa Clinical Laboratory Services Market reveals distinct demand profiles across service types, end users, and testing technologies. Each category carries different regulatory burdens, capital intensity requirements, and geographic concentration patterns that determine competitive positioning.
Service Type:
Clinical chemistry and hematology services dominate domestic hospital demand across Saudi Arabia, South Africa, and Nigeria, while immunology and microbiology segments rely more heavily on specimen export to European reference laboratories.
- Clinical Chemistry:Automated analyzers process electrolyte panels, liver function tests, and renal markers using ion-selective electrodes and spectrophotometric detection. Hospital laboratories in Cairo and Johannesburg deploy these systems for high-throughput inpatient screening. Reagent supply contracts with European manufacturers create currency exposure for operators.
- Hematology:Complete blood count analysis with automated differential counting represents the highest test volume category across the region. South African hospital networks have achieved near-universal automation of routine CBC panels, compressing margins as analyzer platforms from multiple vendors reach functional parity.
- Immunology:Antibody detection and autoimmune profiling services concentrate in accredited reference laboratories with SFDA or SAHPRA certification.
- Microbiology:Culture-based identification and antimicrobial susceptibility testing remains labor-intensive despite automation advances in MALDI-TOF mass spectrometry.
Hematology holds the largest share; momentum sits with immunology as predictive testing reimbursement expands.
End User:
Cost tier stratification separates capital-intensive hospital captive laboratories from lean independent diagnostic chains and specialized research facilities.
- Hospitals:Tertiary medical centers in Riyadh, Dubai, and Cape Town operate comprehensive laboratory services with integrated automation platforms and direct admission-to-result workflows. These facilities capture emergency department and inpatient volume through proximity and turnaround time advantages.
- Diagnostic Laboratories:Independent chains such as those operating in Lagos and Alexandria pursue accreditation to access national health insurance panels. These operators compete on test menu breadth and direct-to-patient collection infrastructure rather than hospital integration.
- Research Institutions:Academic medical centers and clinical trial sponsors in Gulf Cooperation Council states generate demand for specialized biomarker analysis and protocol-mandated testing.
- Blood Banks:Transfusion services require serological screening and viral marker detection with stringent cold-chain documentation.
Hospitals retain the dominant volume position; diagnostic laboratories are gaining share fastest where health insurance expansion redirects outpatient testing.
Test Type:
Application maturity varies sharply, with molecular diagnostics and point-of-care testing representing technology-frontier segments while biopsy analysis and clinical trials services follow established protocols.
- Molecular Diagnostics:PCR amplification and nucleic acid sequencing detect infectious agents and genetic variants with defined analytical sensitivity. Cartridge-based systems are penetrating Saudi Arabian emergency departments for same-day tuberculosis and respiratory pathogen identification.
- Biopsy Analysis:Histopathological examination of tissue specimens requires specialist pathologist interpretation that remains scarce across secondary cities in Nigeria and Egypt. Digital pathology platforms are emerging as a workaround for workforce gaps.
- Clinical Trials:Central laboratory services for pharmaceutical sponsors concentrate in Dubai and Johannesburg with international accreditation and air-freight connectivity.
- Point-of-Care Testing:Near-patient platforms reduce specimen transport logistics and enable rapid clinical decision-making in resource-limited settings.
Biopsy analysis maintains the largest current share; molecular diagnostics shows the steepest expansion trajectory as infectious disease surveillance intensifies.
Technology:
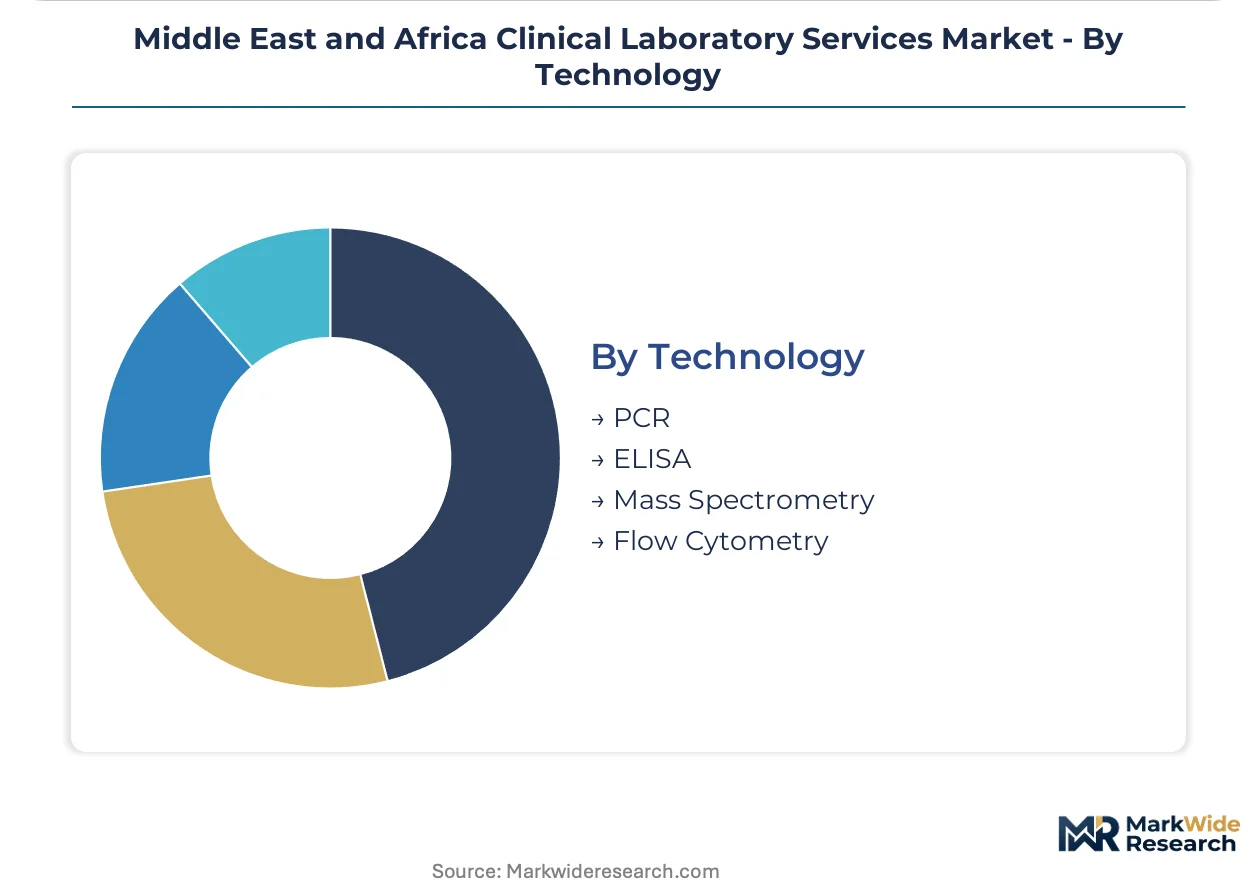
Supply concentration for reagents and instruments shapes competitive dynamics, with PCR and ELISA platforms achieving broad penetration while mass spectrometry and flow cytometry remain concentrated in high-complexity reference sites.
- PCR:Thermal cycling amplification enables detection of low-abundance nucleic acid targets with high specificity. Nigerian hospital laboratories are adding PCR capacity for HIV viral load and hepatitis C monitoring as national treatment programs expand.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective antibody and antigen quantification using optical density measurement. These systems dominate screening programs where test volume justifies batch processing over single-test speed.
- Mass Spectrometry:Ion fragmentation analysis supports therapeutic drug monitoring, endocrinology, and specialized toxicology with high analytical specificity.
- Flow Cytometry:Laser-based cell sorting and immunophenotyping enables leukemia classification and CD4 count enumeration for HIV management.
ELISA commands the largest installed base; PCR is climbing the fastest as point-of-care molecular platforms diffuse beyond centralized laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gulf Cooperation Council capitals where health insurance expansion commands premium service rates, while sub-Saharan African markets operate under severe cost constraints that compress margins for routine testing panels.
Saudi Arabia
SFDA enforcement of Good Clinical Laboratory Practice standards is consolidating independent laboratories into franchise structures that qualify for hospital contracts. The Riyadh-Dammam corridor hosts the region's densest concentration of accredited reference laboratories serving domestic demand and medical tourism flows.
South Africa
SAHPRA compliance with ISO 15189 specifications is forcing smaller operators toward acquisition or partnership structures. Johannesburg anchors the sub-Saharan hub for complex immunology testing with direct air-freight links to European headquarters.
United Arab Emirates
Dubai's logistics infrastructure positions the emirate as a specimen transit node connecting African collection sites to international reference laboratories. MOHAP accreditation requirements are accelerating consolidation among independent diagnostic chains seeking insurance panel inclusion.
Egypt
National health insurance expansion is redirecting patient volume from hospital captive laboratories toward independent diagnostic centers with broader test menus. Cairo and Alexandria are emerging as entry points for accredited laboratory networks with direct-to-patient collection infrastructure.
Nigeria
Hospital-based laboratories in Lagos are adding PCR amplification capabilities to capture infectious disease surveillance contracts. The country's national pharmaceutical regulator is tightening quality management requirements for laboratories serving public health programs.
Middle East and Africa Clinical Laboratory Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa clinical laboratory services market. Siemens Healthineers AG anchors the premium automation tier with integrated analyzer platforms that reduce manual slide review burdens. Sonic Healthcare Ltd leverages international staffing protocols to sustain pathology coverage across multiple African markets where workforce scarcity constrains expansion. Eurofins Scientific SE competes through accredited reference laboratory hubs in Gulf Cooperation Council states with direct air-freight connectivity to European headquarters. Consolidation pressure from SFDA and SAHPRA accreditation mandates is accelerating acquisition activity among mid-scale independent chains.
Within the international diagnostic network tier, Sonic Healthcare Ltd, Siemens Healthineers AG, and Eurofins Scientific SE exemplify three distinct competitive positions. Sonic Healthcare Ltd represents the staffing-intensive model that deploys pathologist coverage across geographically dispersed markets. Siemens Healthineers AG occupies the automation technology vector that addresses workforce scarcity through platform-based efficiency. Eurofins Scientific SE anchors the reference laboratory archetype that concentrates complex testing in hub locations with regulatory accreditation and logistics connectivity. These three patterns illustrate how market structure rewards different capability configurations under common regulatory and labor constraints.
| Leading Market Players |
|---|
| Sonic Healthcare Ltd |
| Siemens Healthineers AG |
| Labcorp Holdings Inc |
| Qiagen NV |
| UNILABS |
| Quest Diagnostics Inc |
| Eurofins Scientific SE |
| Fresenius Medical Care AG |
| SYNLAB International GmbH |
| Others |
Supply & Pricing Matrix
Ninety-day reagent inventory buffers now separate profitable Gulf Cooperation Council laboratories from margin-squeezed operators in sub-Saharan Africa, directly mapping supply chain proximity to pricing power across the Middle East and Africa clinical laboratory services market. This lead-time compression advantage concentrates in Dubai and Johannesburg hub facilities with direct air-freight links to European manufacturers, while inland Nigerian and Egyptian operators absorb currency volatility and extended procurement cycles.
Pricing Analysis
Gulf Cooperation Council capitals command 40-60% price premiums over Lagos and Cairo for identical immunology panels, with three-tier pricing structure across premium, standard, and economy levels stratifying by ISO 15189 certification grade and analyzer platform generation. SFDA and SAHPRA accreditation tiers function as price differentiation drivers, separating hospital contract-eligible operators from cash-pay diagnostic chains. Cost compression in routine hematology is intensifying because analyzer platform commoditization has collapsed functional differentiation among CBC panel providers. Public hospital procurement departments exhibit highest price sensitivity, while medical tourism-focused tertiary centers in Riyadh and Dubai demonstrate lowest elasticity.
Supply Chain Analysis
Strait of Hormuz transit underwrites reagent security for Gulf-based reference laboratories, with supply concentration in Germany, Switzerland, and the United States for ELISA consumables and mass spectrometry ion sources. Regional laboratory networks draw from European manufacturers for PCR thermal cyclers, automated hematology analyzers, and immunology reagent systems, creating dependency on euro and dollar-denominated procurement. Single-source vulnerability concentrates in specialized molecular diagnostics consumables where sole suppliers control proprietary cartridge chemistries. Distribution runs through Dubai and Johannesburg air-freight hubs connecting to hospital central stores and independent diagnostic chain cold-chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as national health insurance expansion across Egypt, Nigeria, and Gulf Cooperation Council states rebuilds outpatient diagnostic utilization toward pre-implementation baselines.
For Market Incumbents: Fortify accreditation moats by accelerating ISO 15189 compliance investments ahead of SFDA and SAHPRA enforcement waves that will disqualify uncertified competitors from hospital panel contracts. Pursue backward integration into reagent distribution through exclusive supply agreements with European manufacturers, locking in preferential pricing and lead-time guarantees that smaller operators cannot match. Pathologist workforce scarcity represents the primary threat to service expansion; automated digital pathology platforms offer the critical lever to extend specialist coverage without resident deployment. For New Entrants and Emerging Players: Point-of-care molecular testing in secondary Egyptian and Nigerian cities offers white-space expansion where hospital-based laboratories under-serve outpatient infectious disease surveillance demand. Direct-to-patient collection infrastructure in Alexandria and Lagos bypasses hospital captive lab relationships entirely, capturing redirected national insurance volume. Franchise partnerships with accredited Gulf Cooperation Council networks provide the fastest go-to-market angle for compliance-constrained operators seeking hospital contract eligibility without standalone certification investment. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory accreditation mandates are structurally eliminating sub-scale independent operators across multiple jurisdictions simultaneously. Target mid-scale diagnostic chains with existing ISO 15189 certification and established hospital relationships in Egypt or Nigeria, where insurance expansion is redirecting patient volume toward qualified independents. Watch SFDA enforcement intensity and SAHPRA audit frequency as the inflection signal for accelerated acquisition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Infrastructure Investment | SFDA and SAHPRA compliance separates contract-eligible operators from excluded competitors. |
| Digital Pathology Platform Deployment | Telepathology networks overcome pathologist scarcity across secondary African cities. |
| Air-Freight Hub Establishment | Dubai and Johannesburg nodes reduce specimen transit time to European reference laboratories. |
| Franchise Network Expansion | Accreditation sharing agreements accelerate market entry for capital-constrained entrants. |
| Point-of-Care Molecular Testing Rollout | Cartridge-based PCR systems capture infectious disease surveillance contracts in Saudi emergency departments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory directors, hospital procurement officers, diagnostic chain executives, and national health insurance administrators across Saudi Arabia, South Africa, Nigeria, Egypt, and the United Arab Emirates. Secondary validation drew from SFDA regulatory filings, SAHPRA accreditation registries, hospital procurement databases, and Gulf Cooperation Council health insurance expansion policy documents. Bottom-up test volume modeling and top-down healthcare expenditure allocation triangulation anchored market sizing.
Across the analysis window, projections integrate service type segmentation by clinical chemistry, hematology, immunology, and microbiology with end-user stratification across hospital captive laboratories, independent diagnostic chains, and research institutions. Technology-specific diffusion curves for PCR, ELISA, mass spectrometry, and flow cytometry platforms inform capacity expansion assumptions. CAGRs derive from test volume elasticity to insurance penetration rates and analyzer platform replacement cycles.
Underlying assumptions cover sustained national health insurance enrollment growth and stable European reagent supply relationships, with deviation risk concentrated in currency volatility affecting import-dependent operators and regulatory enforcement timing across multiple jurisdictions. Practitioners should keep alternative scenarios live as SFDA audit intensity and SAHPRA accreditation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
LIMS Market
Laboratory Services
Cytotoxicity Assays Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Central Lab Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Assessment Services Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Pathology Services Market