
 US Clinical Laboratory Services Market | 2026-2036
US Clinical Laboratory Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Clinical Laboratory Services Market Insights
Test bundling into disease-specific panels is rebalancing buyer choice away from standalone assays toward integrated diagnostic workflows. Laboratory Corporation of America Holdings leverages its national collection infrastructure to anchor high-volume routine testing contracts. Quest Diagnostics differentiates through consumer-direct access portals that bypass traditional physician ordering channels. Sonic Healthcare sustains margin discipline by operating regional laboratory networks with standardized instrumentation platforms.
Clinical laboratory services encompass the analytical processing of human biological specimens using automated analyzers, immunoassay systems, and molecular amplification techniques to generate diagnostic data that guides treatment decisions. These services operate under strict analytical performance specifications including coefficient of variation thresholds, turnaround time guarantees, and proficiency testing compliance. Clinical chemistry and molecular diagnostics represent the most structurally advantaged segments, with molecular diagnostics capturing premium pricing for oncology companion assays while clinical chemistry generates stable, high-throughput revenue from chronic disease monitoring. Immunology testing occupies a mature position with limited pricing power, whereas microbiology faces growth pressure from rapid point-of-care alternatives.
FDA oversight of laboratory-developed tests, CLIA certification requirements, and CMS reimbursement determinations collectively shape market access and service economics for independent and hospital-affiliated laboratories. The Protecting Access to Medicare Act (PAMA) pricing mechanisms directly compress margins on high-volume tests while creating volume incentives for advanced diagnostic categories. Stakeholders must monitor evolving FDA guidance on in vitro diagnostic regulation and state-level scope-of-practice laws that could expand or constrain direct-to-consumer testing channels.
Market Dynamics
CMS reimbursement compression through PAMA pricing mechanisms is forcing independent laboratories to restructure test menus toward higher-margin molecular categories while hospital systems consolidate reference testing partnerships.
Growth Catalysts
- Texas and Florida Demographics:Aging populations in these states concentrate demand for chronic disease monitoring and oncology companion diagnostics, driving specimen volume growth for regional laboratory networks.
- Protecting Access to Medicare Act:PAMA's advanced diagnostic laboratory test pathway creates reimbursement incentives for next-generation sequencing panels, accelerating adoption of precision medicine workflows.
- Next-Generation Sequencing Platforms:Automated library preparation and bioinformatics pipelines are reducing per-sample processing costs for somatic mutation profiling, expanding clinical utility beyond academic medical centers.
Market Restraints
- Reagent Supply Concentration:Polymerase chain reaction master mixes and nucleic acid extraction kits depend on concentrated supplier bases in California and Massachusetts, exposing laboratories to allocation risk during demand surges.
- CLIA Proficiency Burden:Complex molecular assay validation requirements under Clinical Laboratory Improvement Amendments extend time-to-market for novel biomarker tests, compressing commercialization windows.
- Point-of-Care Substitution:Rapid antigen and molecular platforms deployed in physician offices and retail clinics are displacing low-complexity send-out testing for infectious disease categories.
Strategic Opportunities
- Rural Health Integration:Federally qualified health centers in Appalachian and Mississippi Delta regions remain underserved by specialty reference testing, creating white space for hub-and-spoke collection models.
- Pharmacogenomics Expansion:FDA table of pharmacogenomic associations is driving payer coverage for pre-emptive genotyping panels, opening reimbursement pathways for psychiatric and cardiovascular medication management programs.
- Direct-to-Consumer Channel:State scope-of-practice liberalization in Arizona and Colorado permits independent laboratory access without physician intermediation, enabling consumer-ordered wellness and carrier screening panels.
Industry Challenges
- Bioinformatics Talent Scarcity:Variant interpretation and clinical reporting for complex molecular assays require specialized computational biology expertise that remains concentrated in coastal metropolitan labor markets.
- Legacy LIS Integration:Hospital information system interoperability gaps between aging laboratory information systems and modern cloud-based analytics platforms impede real-time results delivery for precision oncology programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Clinical Laboratory Services Market |
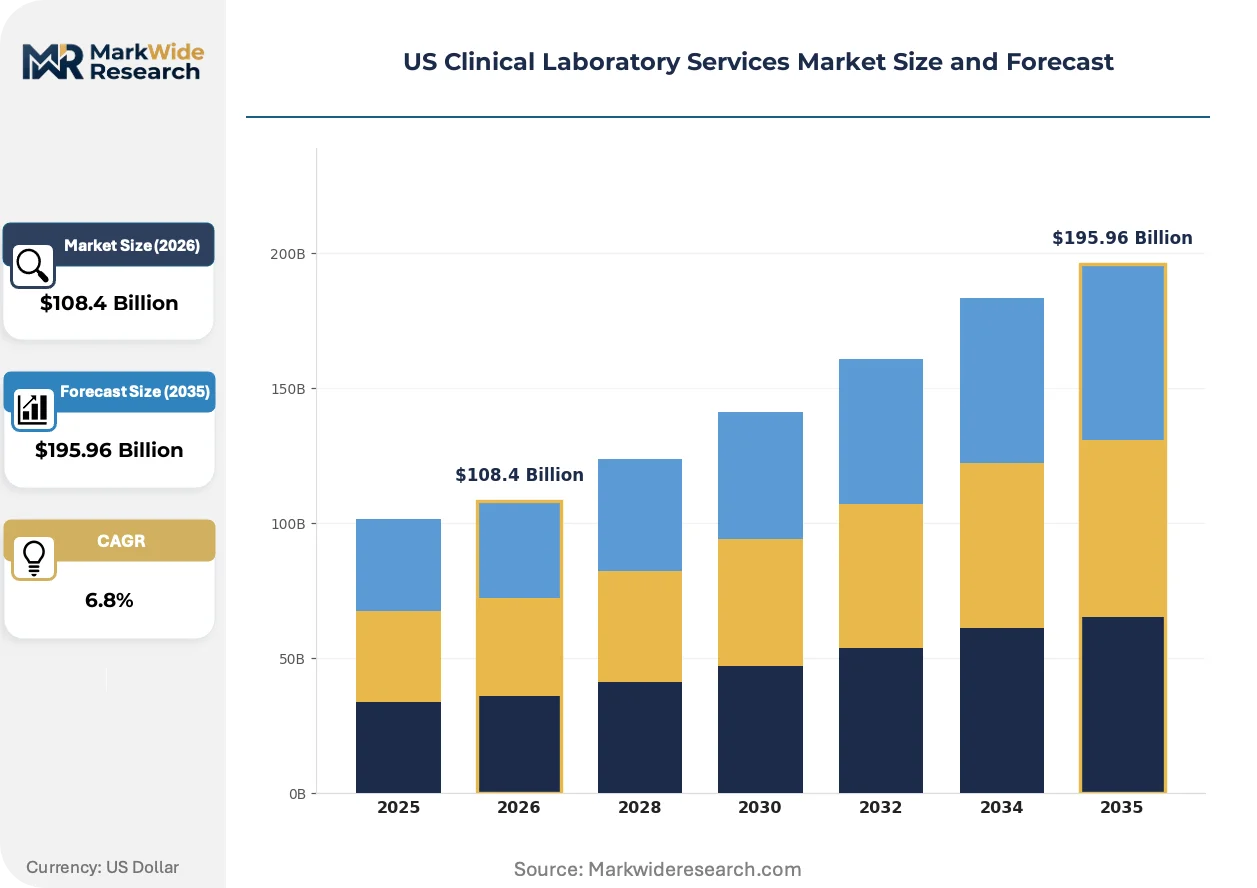
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $195.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Chemistry, Microbiology, Hematology, Immunology End User: Hospitals, Diagnostic Centers, Academic Institutions, Research Laboratories Testing Method: Molecular Diagnostics, Cytogenetics, Biopsy, Blood Tests Sample Type: Blood, Urine, Saliva, Tissue |
| Companies Covered | Laboratory Corporation of America Holdings, Quest Diagnostics Incorporated, Eurofins Scientific SE, ARUP Laboratories, NeoGenomics Laboratories, Sonic Healthcare, Mayo Clinic Laboratories, OPKO Health, Inc., Siemens Medical Solutions USA, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Clinical Laboratory Services Market Trends and Innovations
Liquid biopsy technology is migrating from research applications into routine cancer surveillance, restructuring competitive advantage around bioinformatics capabilities rather than analytical hardware alone.
Cell-free DNA methylation profiling is expanding into minimal residual disease monitoring for solid tumors. Community oncology practices in Texas and Florida are adopting these assays at accelerating pace as Medicare coverage determinations stabilize. The technology is expanding into longitudinal patient management workflows, displacing tissue-based sequencing for recurrence surveillance.
FDA guidance on in vitro diagnostic regulation is tightening oversight of laboratory-developed tests previously operating under enforcement discretion. The agency's premarket review requirements for high-risk oncology companion assays are extending development timelines. High-complexity molecular laboratories are responding by prioritizing FDA-cleared platform partnerships over proprietary assay development.
Self-insured employers are contracting directly with national laboratory networks for employee health screening programs, bypassing traditional health plan intermediaries. These arrangements bundle routine chemistry panels with genetic risk assessments at negotiated rates. The purchasing pattern is most visible in technology and financial services sectors concentrated in Austin, Dallas, and Miami metropolitan areas.
US Clinical Laboratory Services Market Segmentation
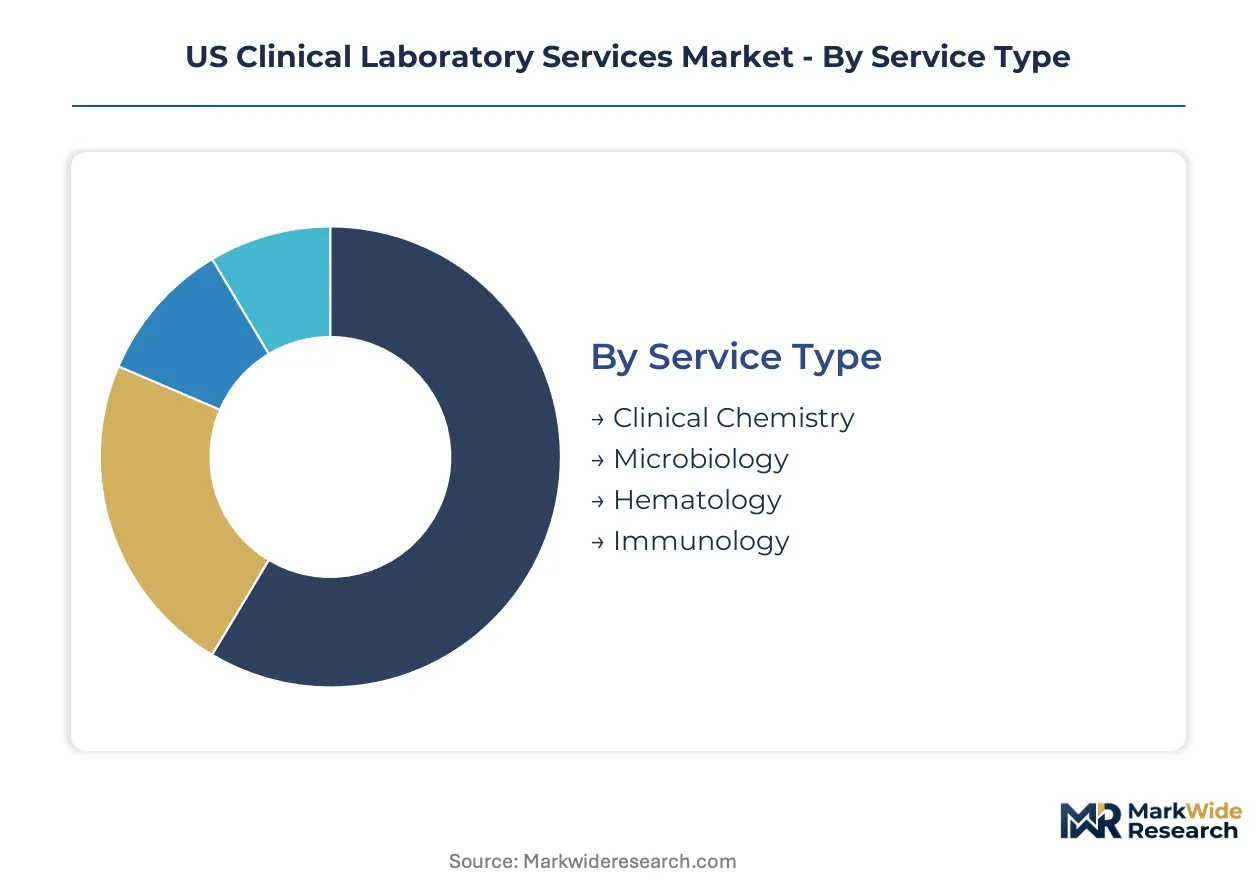
Segmentation in clinical laboratory services reveals how regulatory burden, reimbursement tiers, and technical complexity concentrate margin across distinct operational models. Each dimension carries implications for CLIA certification requirements, CMS coverage pathways, and capital deployment priorities.
Service Type:
CLIA categorization assigns complexity tiers that directly determine proficiency testing frequency, personnel qualification requirements, and inspection intervals for each segment.
- Clinical Chemistry:Automated analyzers process electrolytes, enzymes, and metabolic markers under moderate complexity CLIA rules. Hospital laboratories in Texas and Florida deploy these systems for high-frequency chronic disease monitoring, with stable Medicare reimbursement supporting predictable revenue.
- Microbiology:Culture-based identification and antimicrobial susceptibility testing require specialized biosafety containment and extended incubation protocols. Demand concentrates in hospital-based laboratories managing surgical site infections and sepsis protocols, though rapid point-of-care molecular alternatives are compressing send-out volume for routine respiratory panels.
- Hematology:Cell counting and coagulation assays operate under standardized CLIA moderate complexity designations with well-established quality control frameworks.
- Immunology:Autoantibody and allergy testing panels face pricing pressure from consolidated purchasing by integrated delivery networks.
Clinical Chemistry sits at the top of the volume ranking, with Molecular Diagnostics climbing the fastest.
End User:
Procurement authority and reimbursement capture vary sharply across institutional settings, shaping contract structure and service line prioritization.
- Hospitals:Inpatient and emergency department testing commands premium pricing through facility fee mechanisms, though value-based contracting is narrowing margin spreads. Academic medical centers in Houston and Miami anchor reference testing partnerships that feed downstream revenue to affiliated regional networks.
- Diagnostic Centers:Independent ambulatory facilities compete on turnaround time and patient access convenience, with Medicare reimbursement compression forcing consolidation into multi-site regional platforms.
- Academic Institutions:Research-clinical hybrid operations under NIH funding cycles drive early adoption of novel assay platforms before commercial scale-up.
- Research Laboratories:Pharma-sponsored clinical trial testing operates outside standard CLIA reimbursement frameworks, requiring separate CAP accreditation and protocol-specific validation.
Hospitals capture the largest revenue share, while Diagnostic Centers are expanding most quickly through retail clinic partnerships.
Testing Method:
Technical sophistication determines capital intensity, personnel requirements, and reimbursement tier placement across methodology categories.
- Molecular Diagnostics:Nucleic acid amplification and next-generation sequencing platforms command premium pricing under PAMA's advanced diagnostic laboratory test pathway. Oncology companion diagnostics and infectious disease subtyping concentrate demand in Florida's specialty cancer centers and Texas medical complexes.
- Cytogenetics:Karyotyping and fluorescence in situ hybridization support prenatal and hematologic malignancy workups with specialized technical staffing requirements.
- Biopsy:Histopathology services integrate with surgical workflows, with dermatopathology and gastrointestinal subspecialties showing strongest volume growth.
- Blood Tests:Routine phlebotomy and processing infrastructure underpins all other categories, with automation reducing per-sample labor cost.
Blood Tests maintain the highest specimen throughput, with Molecular Diagnostics gaining share fastest on precision medicine adoption.
Sample Type:
Collection logistics and stability requirements shape geographic reach and processing location economics for each material category.
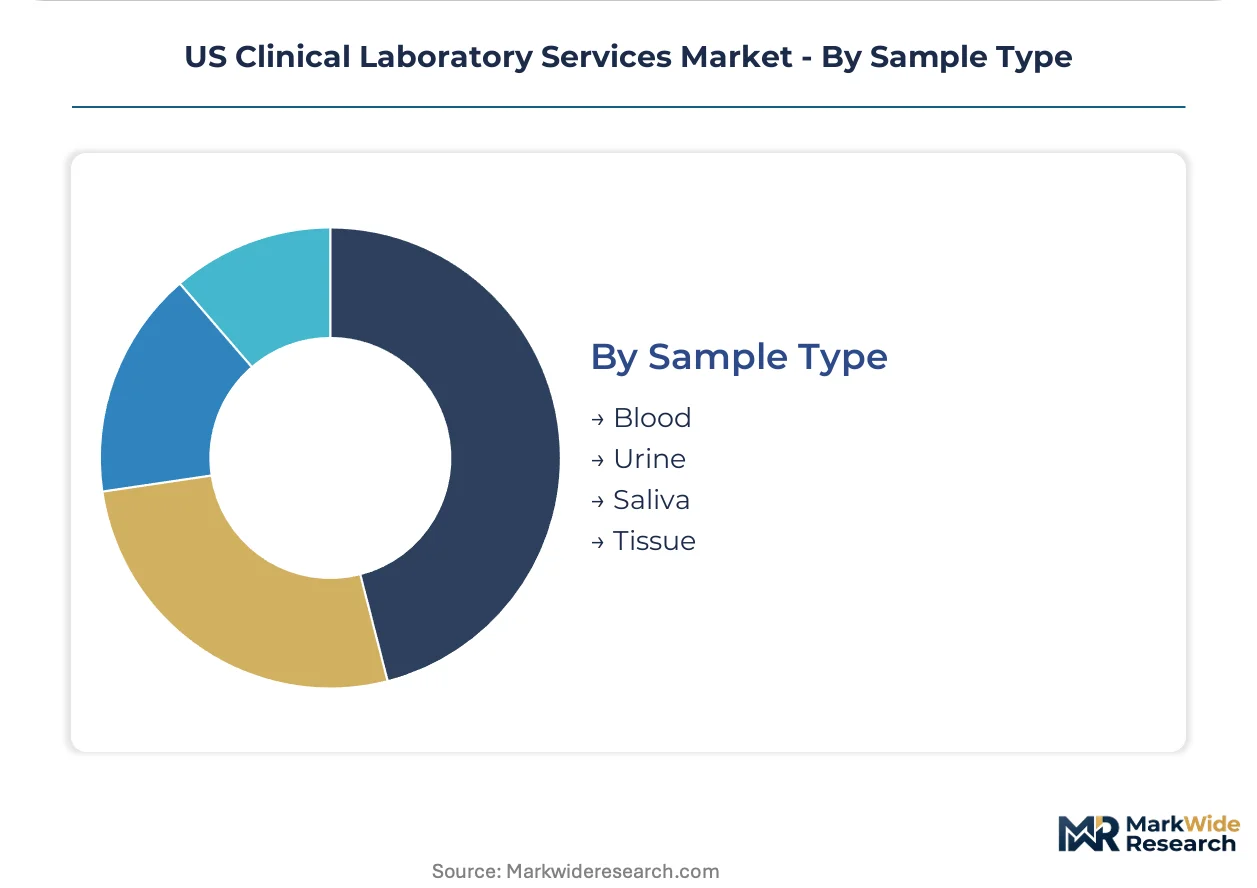
- Blood:Serum and plasma specimens dominate routine chemistry and hematology panels, with dried blood spot alternatives expanding remote collection options for rural health integration.
- Urine:Drug monitoring and metabolic screening applications concentrate in occupational health and pain management clinic networks.
- Saliva:Non-invasive collection is displacing buccal swabs for pharmacogenomics and carrier screening in direct-to-consumer channels permitted under Arizona and Colorado scope-of-practice laws.
- Tissue:Formalin-fixed paraffin-embedded blocks require specialized histology infrastructure, with centralized processing at academic medical centers supporting community oncology practices through courier networks.
Blood draws constitute the majority of specimen volume, with Saliva collection expanding most rapidly on consumer-direct access liberalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US clinical laboratory services industry traces its modern scale to the post-World War II expansion of hospital systems and the 1967 founding of the College of American Pathologists laboratory accreditation program, which established quality frameworks that enabled nationwide standardization.
Texas
Aging demographics in Houston and Dallas-Fort Worth concentrate demand for chronic disease monitoring and oncology companion diagnostics. CMS value-based reimbursement models are reshaping procurement priorities for hospital-based laboratories expanding outsourced testing partnerships. The Texas Medical Center in Houston anchors one of the nation's densest specialty cancer center clusters, driving molecular diagnostics volume growth for regional laboratory networks.
Florida
Retiree population density in Miami, Tampa, and Orlando generates sustained specimen volume for routine chemistry and hematology panels. Florida's state laboratory licensing requirements operate alongside federal CLIA certification, creating dual compliance frameworks for independent operators. The Moffitt Cancer Center in Tampa and Sylvester Comprehensive Cancer Center in Miami feed high-complexity molecular testing demand that spills into affiliated reference laboratory networks.
California
Biotechnology concentration in San Francisco and San Diego produces reagent supply chain gravity for PCR master mixes and nucleic acid extraction kits. FDA oversight of laboratory-developed tests and premarket review requirements for high-risk oncology companion assays extend development timelines for Bay Area molecular laboratories. Stanford Medicine and UCSF Health anchor academic medical center reference testing partnerships that cascade specimen volume to regional collection networks.
New York
Integrated delivery networks in New York City and Long Island consolidate purchasing authority for immunology and microbiology testing panels. State-level scope-of-practice laws and direct-to-consumer testing regulations create regulatory variation that affects laboratory access channel strategies. Memorial Sloan Kettering Cancer Center and NewYork-Presbyterian Hospital maintain in-house molecular diagnostics capabilities while contracting selective reference testing to national networks.
Illinois
Chicago's central logistics position supports hub-and-spoke collection models serving rural health integration opportunities in neighboring states. The Protecting Access to Medicare Act pricing mechanisms compress margins on high-volume tests while creating volume incentives for advanced diagnostic categories that benefit academic medical center laboratories. Northwestern Medicine and University of Chicago Medicine anchor precision oncology programs that drive bioinformatics capability investment.
US Clinical Laboratory Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across test complexity tiers, with molecular diagnostics and oncology companion assays commanding pricing power that routine chemistry panels cannot match. The market structure concentrates around three national-scale integrated networks, a tier of regional hospital-affiliated laboratories, and specialized oncology-focused operators. Strategic archetypes include high-volume routine testing consolidators, precision medicine specialty platforms, and academic medical center reference laboratories. M&A activity targets regional collection network density, while strategic partnerships focus on bioinformatics pipeline integration for liquid biopsy expansion.
Among national-scale operators, Laboratory Corporation of America Holdings and Quest Diagnostics occupy positions as volume-driven routine testing anchors with broad collection infrastructure. Sonic Healthcare exemplifies the regional network archetype through standardized instrumentation platforms that sustain margin discipline across distributed laboratory footprints. These three represent distinct strategic postures within a market where scale economies in logistics and reimbursement negotiation power separate tier-one consolidators from mid-cap regional specialists.
| Leading Market Players |
|---|
| Laboratory Corporation of America Holdings |
| Quest Diagnostics Incorporated |
| Eurofins Scientific SE |
| ARUP Laboratories |
| NeoGenomics Laboratories |
| Sonic Healthcare |
| Mayo Clinic Laboratories |
| OPKO Health, Inc. |
| Siemens Medical Solutions USA, Inc. |
| Others |
Pricing and Supply Chain Analysis
Three-tier pricing stratification across molecular diagnostics, clinical chemistry, and microbiology segments manifests simultaneously in reimbursement capture and reagent sourcing configurations. PAMA's advanced diagnostic laboratory test pathway concentrates pricing power in high-complexity molecular categories while clinical chemistry margins compress through volume-based procurement, with supply chain gravity for PCR master mixes and nucleic acid extraction kits clustering in California and Massachusetts production hubs.
Pricing Analysis
Three-tier pricing structure across premium molecular diagnostics, standard clinical chemistry, and economy microbiology panels dominates contract negotiations. Price differentiation hinges on CLIA complexity certification and CMS reimbursement tier placement. Pricing pressure stems from PAMA-mandated fee schedule reductions on high-volume routine tests. Hospital systems demonstrate lowest price sensitivity due to facility fee mechanisms, while independent diagnostic centers face acute margin compression.
Supply Chain Analysis
CLIA certification and FDA premarket review requirements gate supplier qualification, concentrating approved reagent vendors in California, Massachusetts, and North Carolina biotechnology corridors. Raw material dependencies include polymerase chain reaction enzymes, sequencing flow cells, and specialized transport media. Single-source vulnerability runs through concentrated nucleic acid extraction kit manufacturers. Distribution runs through hub-and-spoke courier networks anchored at academic medical centers in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory operators exploit geographic arbitrage between Texas and Florida's favorable scope-of-practice environments versus New York and California's restrictive direct-to-consumer testing regulations, capturing margin expansion through channel structure optimization.
For Market Incumbents: Deepen bioinformatics capability investment to defend molecular diagnostics pricing against point-of-care substitution threats. Consolidate reference testing partnerships with Florida cancer centers and Texas medical complexes to lock in high-margin oncology companion diagnostic volume. Prioritize CLIA high-complexity certification maintenance as regulatory moat against mid-cap regional competitors. For New Entrants and Emerging Players: Federally qualified health centers in Appalachian and Mississippi Delta regions offer underpenetrated collection network expansion opportunities. Target rural health integration through dried blood spot remote collection logistics. Pursue pharmacogenomics panel commercialization under Arizona and Colorado's liberalized direct-to-consumer access statutes. For Investors and Strategic Acquirers: Consolidation pressure builds where regional laboratory networks lack standardized instrumentation platforms and bioinformatics pipelines. Long-term viability favors precision medicine specialists with FDA-cleared platform partnerships over proprietary assay developers. Watch Medicare coverage determinations for liquid biopsy minimal residual disease monitoring as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Certification Investment | FDA premarket review alignment for oncology companion assays extends commercialization runway under enforcement discretion tightening. |
| Bioinformatics Pipeline Integration | Liquid biopsy methylation profiling capabilities differentiate community oncology service contracts in Texas and Florida markets. |
| Hub-and-Spoke Collection Network Expansion | Federally qualified health center partnerships in underserved regions capture white-space specimen volume outside consolidated urban markets. |
| Direct-to-Consumer Channel Development | Arizona and Colorado scope-of-practice liberalization enables wellness and carrier screening panel access without physician intermediation. |
| Pharmacogenomics Panel Commercialization | FDA table of pharmacogenomic associations drives payer coverage expansion for psychiatric and cardiovascular medication management programs. |
Research Methodology
Bottom-up hospital and diagnostic center procurement modeling reconciled against top-down CLIA-certified laboratory capacity tracking forms the analytical core of this study. Primary interviews with laboratory directors, hospital purchasing committee members, GPO contracts managers, and CMS reimbursement policy specialists combined with secondary validation from FDA 510(k) filings, CMS Medicare claims data, hospital procurement databases, and state laboratory licensing records. Triangulation across these sources ensures coverage of both operational testing volume and regulatory pathway constraints.
Historical trendline analysis of molecular diagnostics adoption rates and clinical chemistry panel utilization established baseline growth patterns across the projection horizon. Segmentation modeling incorporated service type complexity tiers, end-user institutional settings, testing method technical sophistication, and sample type collection logistics. CAGRs derived from specimen volume trajectory analysis weighted against reimbursement schedule evolution under PAMA implementation. Forecast inputs included precision medicine adoption curves and point-of-care substitution rates for infectious disease categories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA laboratory-developed test enforcement discretion shifts and Medicare coverage determination timing for novel biomarker categories. Model outputs reflect assumptions regarding stable CLIA certification requirements and continued PAMA reimbursement pathway stability. A model refresh is warranted upon material change in FDA premarket review guidance or state-level scope-of-practice liberalization acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Myoglobin Reagents Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Clinical Laboratory Services Market
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Assessment Services Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
Sera and Reagents Market
Laboratory Services
Frozen Tissues Samples Market