
 Lab Mailers Market | 2026-2036
Lab Mailers Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Mailers Market Foresight
Temperature-monitoring subscription services is consolidating around reusable data-logger programs that convert one-time packaging sales into recurring revenue relationships. Sealed Air Corporation leverages its Cryovac cold-chain infrastructure to bundle IoT-enabled tracking with insulated mailer contracts. Sonoco ThermoSafe Brands, Inc. anchors its position through pharmaceutical-validated rental shipper programs that reduce total cost of ownership for high-volume lab networks. 3M competes across the diagnostic specimen segment with sorbent-lined pouch systems that integrate absorption chemistry directly into mailer construction.
Lab mailers are engineered shipping enclosures designed to maintain specimen integrity across temperature excursions, mechanical shock, and biohazard containment requirements, typically constructed with multi-layer foam, reflective metallized films, or vacuum-insulated panels rated for specific thermal duration limits. Their primary commercial purpose is to satisfy DOT, IATA, and CDC packaging instructions for Category A and Category B infectious substances while minimizing dimensional weight penalties in parcel networks. Insulated mailers command the largest revenue share within product type categories due to their dominance in PCR sample, reagent, and temperature-sensitive diagnostic workflows, though biohazard mailers are expanding fastest as home-collection and direct-to-consumer testing protocols multiply. Among end users, pharmaceutical companies represent the most concentrated margin pool because their clinical trial logistics require custom-validated configurations with chain-of-custody documentation that standard laboratory contracts rarely demand.
FDA 21 CFR Part 820 quality system regulations and IATA Dangerous Goods standards jointly shape product validation burdens, forcing mailer manufacturers to maintain extensive testing documentation for every SKU destined for biological specimen transport. OSHA Bloodborne Pathogens standards and CDC packaging guidelines for infectious substances further constrain material selection and closure system design, particularly for mailers handling diagnostic samples from clinical settings. Stakeholders must monitor how EPA sustainable packaging mandates and state-level extended producer responsibility frameworks will alter material specifications before their next product platform refresh cycles.
Market Dynamics
Diagnostic laboratories are consolidating logistics contracts around temperature-monitoring subscription services that convert one-time packaging sales into recurring revenue relationships, restructuring supplier-buyer power dynamics across the cold-chain specimen transport value chain.
Growth Catalysts
- FDA 21 CFR Part 820:Quality system regulations tighten packaging validation requirements for biological specimen transport, forcing diagnostic laboratories to upgrade mailer specifications and expand procurement volumes.
- Home-collection protocols:Direct-to-consumer testing workflows multiply demand for biohazard mailers engineered with Category B infectious substance containment and simplified end-user handling.
- PCR sample workflows:Temperature-sensitive diagnostic testing concentrates purchasing power among reference labs and hospital networks seeking validated insulated mailer configurations.
Market Restraints
- Petrochemical input volatility:Multi-layer foam and metallized film constructions depend on petroleum-derived feedstocks, compressing margin stability when resin prices fluctuate.
- Supplier concentration risk:Vacuum-insulated panel manufacturing clusters in East Asian production zones, exposing mailer assemblers to single-source geographic dependency.
- Extended producer responsibility frameworks:State-level mandates in the United States impose material recovery obligations that increase compliance overhead before product platform refresh cycles.
Strategic Opportunities
- Rental shipper programs:Pharmaceutical-validated reusable systems reduce total cost of ownership for high-volume lab networks, opening recurring revenue streams beyond disposable mailer sales.
- IoT-enabled tracking bundles:Integration of data-loggers with insulated mailer contracts captures diagnostic specimen chain-of-custody documentation requirements.
- Sorbent-lined pouch systems:Absorption chemistry integrated directly into mailer construction addresses biohazard containment for clinical setting diagnostic samples.
Industry Challenges
- DOT and IATA dangerous goods certification timelines:Every SKU destined for biological specimen transport requires extensive testing documentation, elongating product development cycles.
- OSHA Bloodborne Pathogens standard compliance:Material selection and closure system design face strict constraints for mailers handling infectious substances from clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Mailers Market |
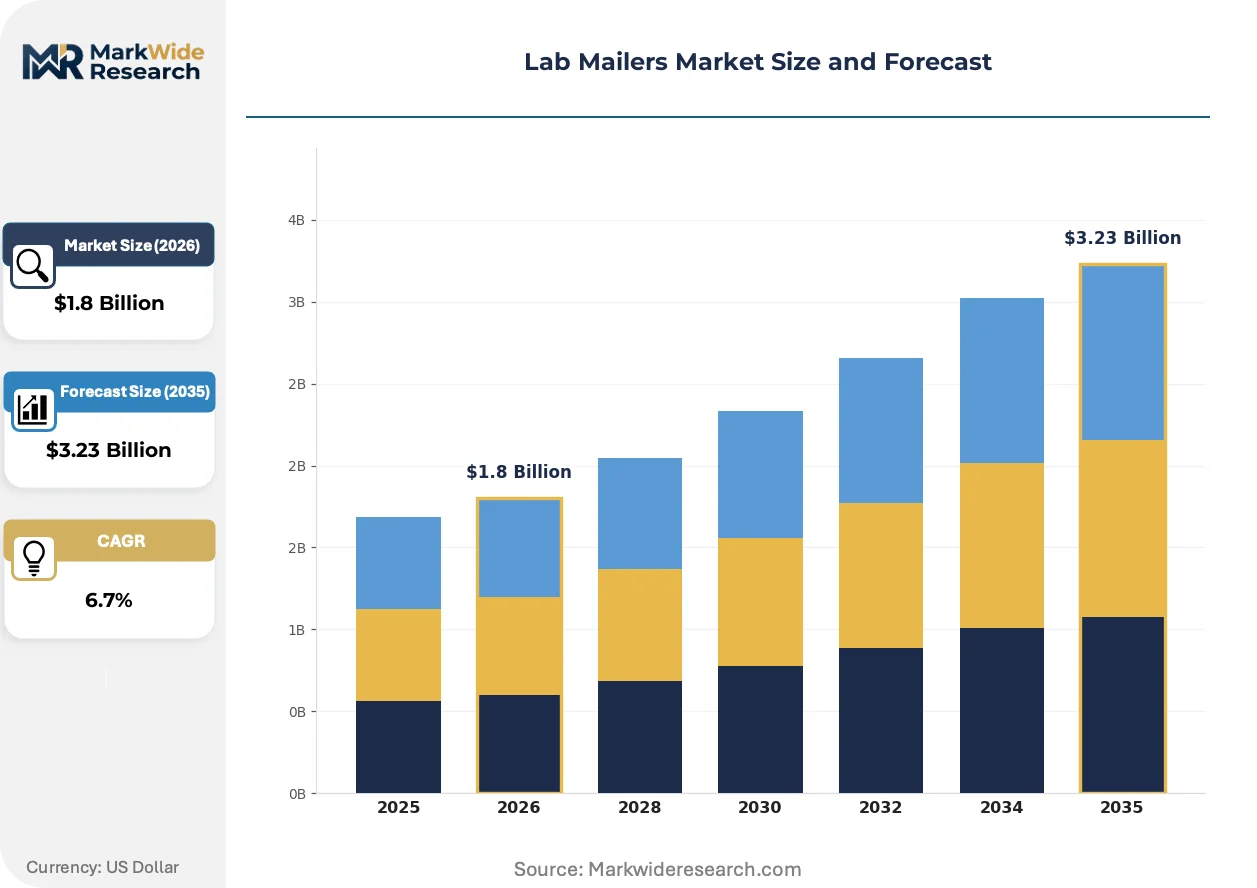
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mailers, Insulated Mailers, Biohazard Mailers, Custom Mailers End User: Laboratories, Research Institutions, Healthcare Facilities, Pharmaceutical Companies Material: Plastic, Paper, Cardboard, Foam Feature: Temperature Control, Leak Proof, Tamper Evident, Recyclable |
| Companies Covered | Sonoco ThermoSafe Brands, Inc., Sealed Air Corporation, Electron Microscopy Sciences Inc., Polar Tech Industries, Inc., Pregis, Storopack, 3M, ProAmpac, Uline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Mailers Market Shifts & Advancements
Reusable data-logger programs are restructuring competitive positioning by converting transactional packaging sales into platform-based service relationships with diagnostic laboratories.
Phase-change material inserts with precise thermal duration ratings are decentralizing cold-chain infrastructure requirements for mid-volume specimen transport. Regional hospital networks and independent diagnostic laboratories are adopting these modular thermal packs at accelerating rates. This technology is decentralizing temperature control from centralized refrigeration assets to distributed point-of-use packaging systems.
EPA sustainable packaging mandates are forcing material specification changes across mailer manufacturing platforms. Industrial consequence includes accelerated substitution of petroleum-derived foams with cellulose-based insulation and recycled content films. United States-based diagnostic laboratories face the most immediate compliance pressure, with procurement teams now requiring environmental product declarations in supplier qualification processes.
Consolidated logistics contracts are compressing supplier bases for reference labs and hospital networks. Traditional distributor intermediaries face displacement as buyers negotiate direct multi-year agreements with mailer manufacturers offering integrated temperature monitoring. This concentration is most visible in the United States, where health system mergers have aggregated purchasing power into fewer procurement decision centers.
Lab Mailers Market Segmentation
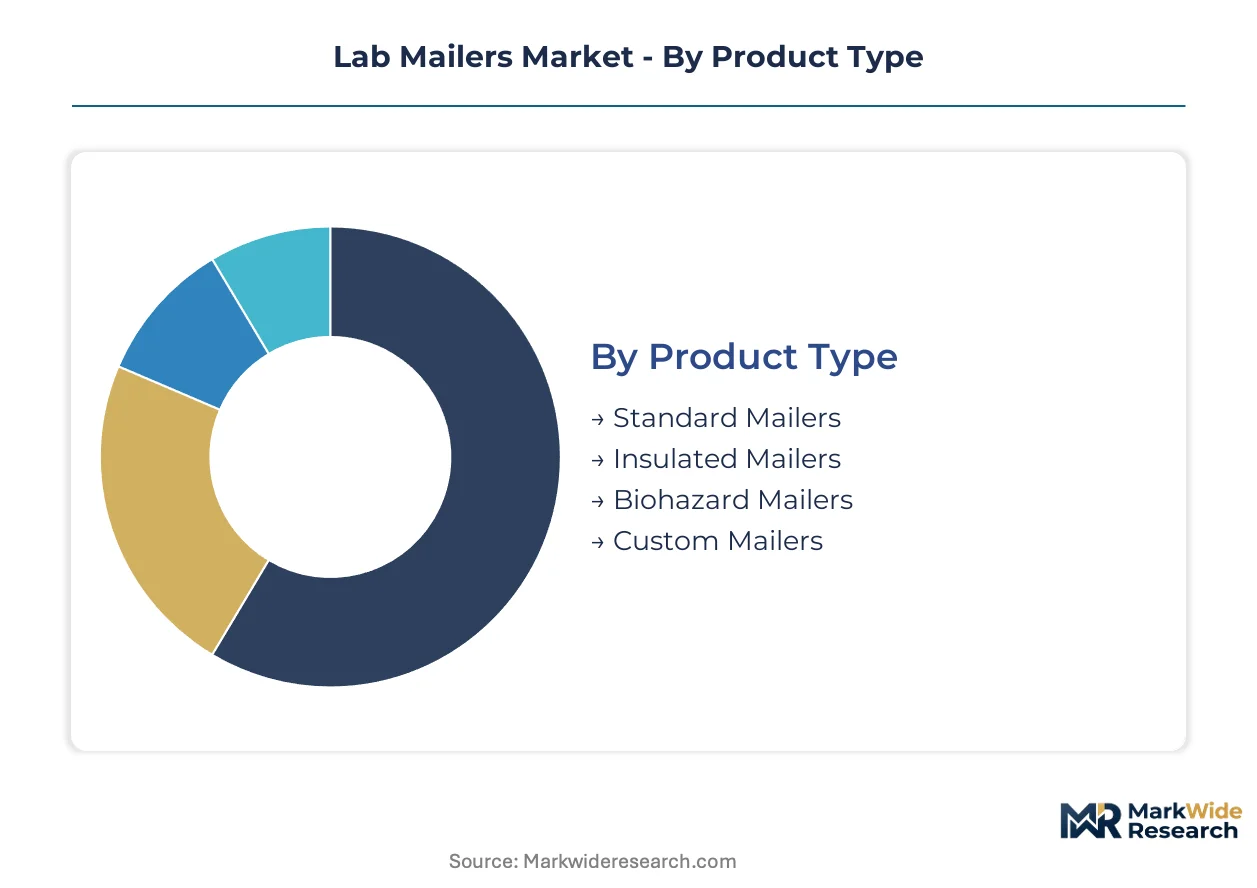
Lab mailer segmentation directly determines which regulatory frameworks apply to procurement decisions. Certification requirements for Category A infectious substances versus standard diagnostic specimens create divergent supplier qualification pathways across product categories.
Product Type:
FDA 21 CFR Part 820 quality system regulations impose tiered validation burdens: insulated mailers require thermal duration documentation, while biohazard mailers demand infectious substance containment testing under DOT and IATA protocols.
- Insulated Mailers:Multi-layer foam or vacuum-insulated panel constructions rated for specific thermal duration limits. PCR sample workflows at United States reference labs and hospital networks concentrate purchasing power for validated configurations with chain-of-custody documentation.
- Biohazard Mailers:Engineered with Category B infectious substance containment, absorption chemistry, and simplified end-user handling. Direct-to-consumer testing protocols multiply demand as home-collection workflows expand.
- Standard Mailers:Basic shipping enclosures without thermal or biohazard specifications for non-regulated specimen transport.
- Custom Mailers:Client-validated configurations with proprietary closure systems and branding for pharmaceutical clinical trial logistics.
Insulated Mailers sits at the top of the volume ranking, with Biohazard Mailers climbing the fastest.
End User:
Margin concentration varies sharply across customer types, with pharmaceutical clinical trial logistics commanding premium pricing for custom-validated configurations.
- Pharmaceutical Companies:Clinical trial logistics require custom-validated configurations with chain-of-custody documentation that standard laboratory contracts rarely demand.
- Laboratories:Reference labs and hospital networks in the United States consolidate logistics contracts around temperature-monitoring subscription services.
- Healthcare Facilities:OSHA Bloodborne Pathogens standards constrain material selection for mailers handling diagnostic samples from clinical workflows.
- Research Institutions:Academic and government labs prioritize cost efficiency over custom validation for non-regulated specimen transport.
Pharmaceutical Companies capture the highest margin tier, while Laboratories represent the deepest volume pool.
Material:
EPA sustainable packaging mandates and state-level extended producer responsibility frameworks are accelerating substitution timelines across material platforms.
- Foam:Petroleum-derived multi-layer constructions face displacement pressure as procurement teams require environmental product declarations.
- Plastic:Sorbent-lined pouch systems integrate absorption chemistry directly into mailer construction for biohazard containment.
- Paper:Cellulose-based insulation substitutes accelerate as United States diagnostic laboratories face immediate compliance pressure.
- Cardboard:Recycled content films and fiber-based constructions address dimensional weight penalties in parcel networks.
Foam retains dominant share in thermal applications, with Paper gaining share fastest on sustainability mandates.
Feature:
Feature bundling determines competitive positioning as suppliers convert one-time packaging sales into recurring revenue relationships.
- Temperature Control:IoT-enabled data-logger integration captures diagnostic specimen chain-of-custody requirements for pharmaceutical and high-volume lab networks.
- Leak Proof:Absorption chemistry and sealed closure systems satisfy OSHA and CDC packaging guidelines for infectious substances.
- Tamper Evident:Security features address chain-of-custody documentation for clinical trial logistics and forensic applications.
- Recyclable:Material recovery specifications respond to state-level extended producer responsibility frameworks in the United States.
Temperature Control commands the highest attach rate, with Recyclable features expanding most quickly on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates diagnostic specimen logistics spending at roughly triple the intensity of Germany, where pharmaceutical cold-chain exports drive a distinct procurement pattern. National regulatory frameworks and healthcare system structures shape divergent mailer specification requirements across major markets.
United States
Reference lab consolidation and hospital network mergers aggregate purchasing power into fewer procurement centers demanding validated insulated configurations. FDA 21 CFR Part 820 quality system regulations mandate extensive testing documentation for every biological specimen transport SKU. The Research Triangle Park cluster in North Carolina and Greater Boston biotech corridor concentrate cold-chain logistics operations serving clinical trial networks.
Germany
Pharmaceutical export volumes sustain demand for high-performance thermal packaging with extended duration ratings. ECHA REACH compliance and EU MDR requirements impose material disclosure obligations that accelerate sustainable packaging substitution timelines. The Rhine-Main region around Frankfurt anchors pharmaceutical logistics hubs handling temperature-sensitive clinical trial materials for European distribution.
China
Domestic diagnostic testing expansion and biopharmaceutical manufacturing growth multiply specimen transport volumes across hospital networks. NMPA medical device regulations and GB standards for biological substance shipping tighten packaging validation requirements for both domestic use and export. The Yangtze River Delta around Shanghai concentrates contract manufacturing organizations driving standardized mailer procurement at scale.
Japan
Aging demographics and precision medicine initiatives expand molecular diagnostic testing requiring temperature-controlled specimen workflows. PMDA pharmaceutical regulations and METI industrial standards enforce rigorous cold-chain documentation for clinical trial logistics. The Kansai region around Osaka hosts specialized packaging manufacturers serving domestic pharmaceutical distribution networks.
United Kingdom
NHS laboratory consolidation and private diagnostic testing growth reshape procurement patterns for insulated and biohazard mailers. MHRA post-Brexit regulatory alignment with EU standards maintains validation requirements while enabling distinct national procurement frameworks. The Cambridge-London corridor concentrates biotech research institutions demanding custom-validated shipper configurations for specimen transport.
Lab Mailers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with diagnostic laboratories favoring integrated service relationships while pharmaceutical buyers prioritize validated rental programs. The vendor base organizes into three tiers: diversified packaging conglomerates with cold-chain infrastructure, temperature-control specialists with pharmaceutical validation expertise, and regional fabricators serving cost-sensitive laboratory networks. Two dominant competitive moves define current positioning: bundling IoT-enabled tracking with mailer contracts to capture recurring revenue, and expanding rental shipper programs that reduce total cost of ownership for high-volume buyers.
Within the diversified packaging tier, Sealed Air Corporation and Sonoco ThermoSafe Brands, Inc. exemplify contrasting strategic positions. Sealed Air leverages Cryovac cold-chain infrastructure to anchor integrated service relationships. Sonoco ThermoSafe occupies a position defined by pharmaceutical-validated rental programs. 3M represents a materials science archetype competing through sorbent-lined pouch systems that integrate absorption chemistry directly into mailer construction.
| Leading Market Players |
|---|
| Sonoco ThermoSafe Brands, Inc. |
| Sealed Air Corporation |
| Electron Microscopy Sciences Inc. |
| Polar Tech Industries, Inc. |
| Pregis |
| Storopack |
| 3M |
| ProAmpac |
| Uline |
| Others |
Supply & Pricing Matrix
EPA sustainable packaging mandates gate both qualified supply and premium-tier pricing access, forcing mailer manufacturers to certify cellulose-based insulation and recycled content films before procurement teams at United States diagnostic laboratories will award multi-year contracts.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for vacuum-insulated panels, compressing margins for legacy suppliers while creating entry points for mid-tier competitors. Three-tier pricing structure across pharmaceutical-validated, diagnostic-standard, and economy non-regulated levels separates buyers by certification burden and volume commitment. Cost compression in the economy tier is intensifying because hospital networks are consolidating logistics contracts around subscription-based temperature monitoring. Research institutions represent the most price-sensitive segment, while pharmaceutical clinical trial logistics show minimal price elasticity due to chain-of-custody documentation requirements.
Supply Chain Analysis
Reverse-logistics flows for rental shipper programs are reconfiguring downstream economics, with refurbishment centers in Germany and the United States extending asset life cycles and reducing per-use costs for high-volume lab networks. Vacuum-insulated panel manufacturing concentrates in China, South Korea, and Germany, while multi-layer foam production feeds from petrochemical complexes in the United States and the Netherlands. Raw material dependencies span petroleum-derived resins, metallized films, and phase-change material formulations. Single-source geographic vulnerability in East Asian VIP production exposes mailer assemblers to disruption. Distribution runs through direct manufacturer agreements with reference labs and hospital networks, bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through rental shipper programs that convert capital expenditure into recurring service revenue, capturing total cost-of-ownership reductions that disposable mailer sales cannot match.
For Market Incumbents: Deploy IoT-enabled tracking bundles to lock in multi-year subscription relationships with consolidating hospital networks. Deepen backward integration into phase-change material formulations to secure supply and capture margin upstream. Counter emerging temperature-control specialists by accelerating pharmaceutical validation timelines for custom mailer configurations. For New Entrants and Emerging Players: Launch via direct-to-consumer testing channel partnerships, where biohazard mailer demand multiplies fastest and incumbent service infrastructure remains thin. Target independent diagnostic laboratories in the United States that lack purchasing scale for rental programs but require validated insulated configurations. Differentiate through rapid-turn custom validation services that large conglomerates cannot match. For Investors and Strategic Acquirers: Roll-up economics work for regional temperature-control specialists because FDA 21 CFR Part 820 documentation burdens create switching costs that protect acquired customer bases. Five-to-ten year viability hinges on platform consolidation around reusable data-logger ecosystems rather than disposable mailer commoditization. Monitor NMPA regulatory alignment progress in China as inflection indicator for export-oriented manufacturing targets.| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Tracking Integration | Sealed Air's Cryovac infrastructure bundles data-loggers with insulated mailer contracts to capture recurring revenue. |
| Pharmaceutical-Validated Rental Programs | Sonoco ThermoSafe reduces total cost of ownership for high-volume lab networks through reusable shipper assets. |
| Sorbent-Lined Pouch Development | 3M integrates absorption chemistry directly into mailer construction for OSHA-compliant biohazard containment. |
| Cellulose-Based Insulation Substitution | EPA mandates accelerate material platform refreshes ahead of state-level extended producer responsibility deadlines. |
| Direct Logistics Contract Negotiation | Hospital network mergers aggregate purchasing power into fewer procurement centers demanding integrated service relationships. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and the United Kingdom, with primary inputs from each market triangulated against secondary validation. Primary interviews engaged cold-chain logistics directors at reference laboratories, procurement managers at hospital networks, regulatory affairs specialists at mailer manufacturers, pharmaceutical clinical trial supply officers, and sustainability compliance leads at diagnostic testing companies. Secondary sources included FDA 21 CFR guidance documents, IATA Dangerous Goods regulations, EPA sustainable packaging mandates, hospital GPO contract databases, and customs trade data for insulated packaging imports. Bottom-up SKU-level volume estimates were cross-checked against top-down market size calculations.
Rate-of-change decomposition across the analysis window separated volume drivers from price-mix effects to isolate true demand expansion. Segmentation dimensions modeled include product type, end user, material platform, and feature bundling, with additional granularity on thermal duration rating tiers and certification level. CAGRs were derived from logistic curve fitting to adoption saturation limits, calibrated against historical penetration patterns in adjacent cold-chain packaging markets. Forecast inputs incorporated PCR testing volume trajectories, home-collection protocol expansion rates, and pharmaceutical clinical trial pipeline density.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt petrochemical price spikes or accelerated EPA mandate timelines. Forecasts reflect assumptions about regulatory enforcement consistency and laboratory consolidation velocity. Practitioners should monitor NMPA implementation timelines in China and state-level extended producer responsibility enactments in the United States for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
UAE Clinical Laboratory Services Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Autosampler Vials Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Clinical Laboratory Services Market
Laboratory Services
Myoglobin Reagents Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Histopathology Services Market
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
Cytotoxicity Assays Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market