
 Veterinary Medicine Market | 2026-2036
Veterinary Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Medicine Market Intelligence
Aftermarket service revenue around diagnostics and chronic disease management is rewriting profit architecture across the sector. Zoetis Inc. leverages its integrated diagnostics-to-therapeutics platform to capture recurring clinic spending. Merck Animal Health anchors its position through vaccine manufacturing scale across multiple species. Boehringer Ingelheim Animal Health differentiates via its specialized equine and swine portfolios.
Veterinary medicine encompasses pharmacologically active substances formulated for the prevention, diagnosis, and treatment of diseases in animals, with products ranging from small-molecule antibiotics to recombinant vaccines requiring cold-chain distribution at two to eight degrees Celsius. These agents serve commercial livestock operations seeking herd productivity protection and companion animal owners pursuing longevity for pets. Vaccines command durable margin pools due to mandatory immunization schedules and regulatory barriers to biosimilar entry, while nutritional supplements gain traction as clinics integrate wellness protocols. Anti-parasitic formulations retain volume leadership in livestock channels where endectocides address multi-pathogen burdens.
The FDA Center for Veterinary Medicine governs approval pathways and residue tolerance limits for food animal products, while the USDA Animal and Plant Health Inspection Service regulates veterinary biologics manufacturing and interstate shipment. The EPA additionally oversees ectoparasiticide environmental fate, creating a multi-agency compliance landscape that elevates development costs and extends timelines for new entrants. Stakeholders must monitor evolving antimicrobial stewardship mandates and their cascading effects on product portfolios and prescriber behavior.
Market Dynamics
Companion animal therapeutics now command margin premiums that livestock segments cannot match, redrawing capital allocation across pharmaceutical portfolios. FDA residue protocols and antimicrobial stewardship mandates are compressing antibiotic development pipelines while accelerating vaccine and biologic investment.
Growth Catalysts
- Antimicrobial Stewardship Mandates:FDA Center for Veterinary Medicine guidelines restrict prophylactic antibiotic use in food animals. Vaccine and biologic developers capture displaced therapeutic demand.
- Companion Animal Humanization:Pet owners in the United States and Western Europe now spend per-capita on preventive oncology and chronic disease management. Specialty veterinary clinics expand service menus accordingly.
- Cold-Chain Infrastructure Expansion:Brazil, India, and China deploy refrigerated distribution networks reaching rural livestock operations. MRNA and recombinant vaccine penetration accelerates in previously underserved regions.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for veterinary antibiotics clusters in China and India. Geopolitical friction or export restrictions threaten formulation continuity.
- Regulatory Timeline Friction:USDA APHIS biologics licensing requires 3-5 year approval cycles with facility inspection backlogs. Development costs escalate before revenue realization.
- Generic Erosion in Small Molecules:Patent-expired antibiotics and anti-parasitics face price compression from multi-source generic competition. Originators retreat from commoditized categories.
Strategic Opportunities
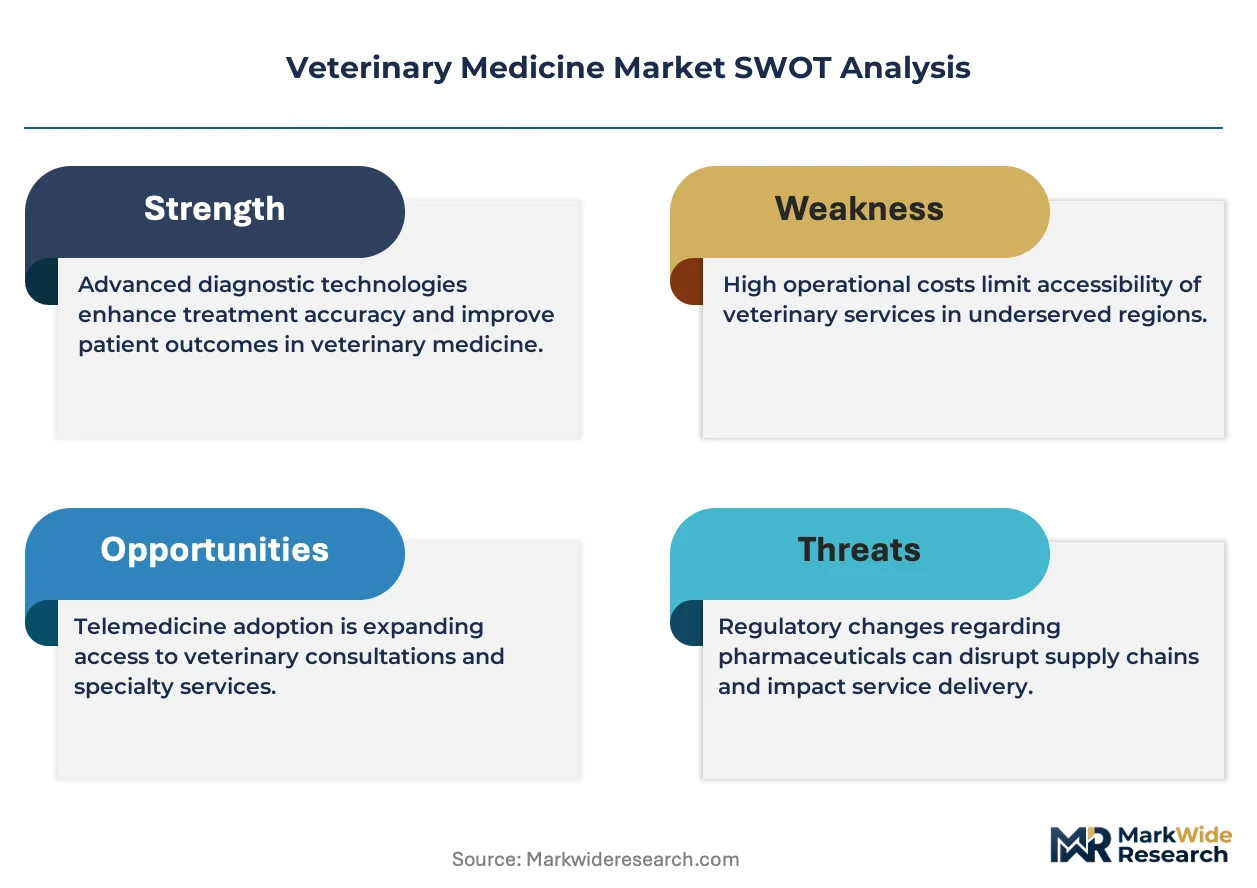
- One Health Diagnostic Convergence:Zoonotic disease surveillance programs in sub-Saharan Africa and Southeast Asia create demand for portable, species-agnostic testing platforms. Veterinary and human health budgets merge procurement.
- Digital Prescription Platforms:Telemedicine-enabled veterinary consultations in Australia and Canada expand pharmacy fulfillment through centralized compounding. Regulatory frameworks adapt to remote prescribing.
- Precision Nutrition Integration:Microbiome-targeted supplements and metabolomic profiling enter wellness protocols at specialty clinics. Nutraceutical margins approach pharmaceutical levels without equivalent development burden.
Industry Challenges
- Veterinary Specialist Shortage:Board-certified oncologists, neurologists, and surgeons concentrate in urban corridors. Rural and exurban clinics cannot staff advanced service lines.
- Legacy Practice Management Integration:Independent clinics operate disconnected electronic health record systems. Consolidated diagnostic-to-pharmacy platforms face adoption friction.
- Biologics Manufacturing Scale-Up:Cell culture and fermentation capacity for veterinary vaccines requires dedicated facilities. Cross-contamination protocols prevent human pharmaceutical asset sharing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Medicine Market |
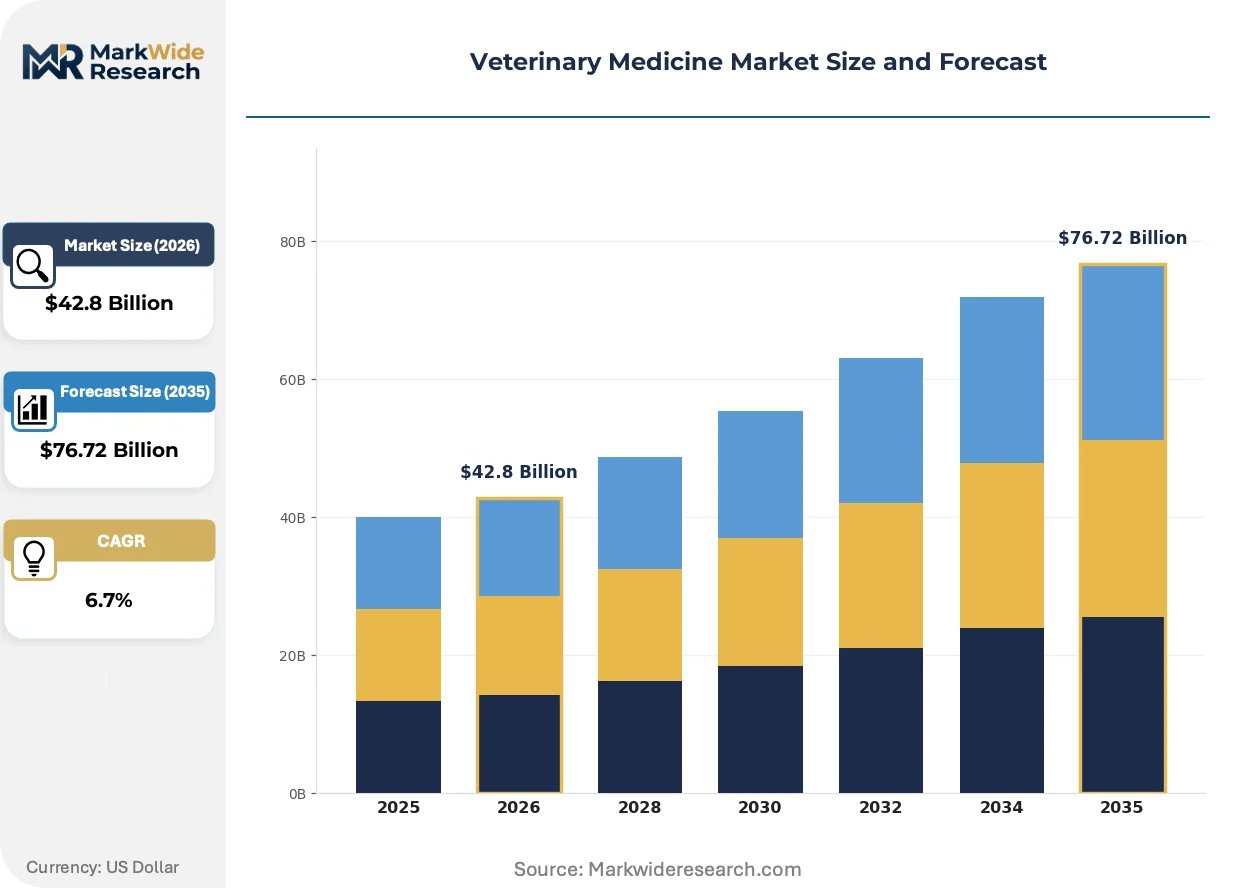
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $76.72 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Anti-parasitic, Nutritional Supplements, Hormones Therapy Area: Infectious Diseases, Reproductive Health, Gastrointestinal Disorders, Dermatology, Respiratory Conditions End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Zoos, Livestock Farms Distribution Channel: Veterinary Pharmacies, Online Retailers, Direct Sales, Wholesalers, Animal Feed Stores |
| Companies Covered | Zoetis Inc., Merck Animal Health, Boehringer Ingelheim Animal Health, Elanco Animal Health, Ceva Santé Animale, Virbac, Dechra Pharmaceuticals PLC, Phibro Animal Health Corporation, IDEXX Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Medicine Market Strategic Shifts & Innovations
mRNA platform technology is collapsing development timelines for veterinary vaccines while enabling rapid strain-matched updates previously impossible with inactivated approaches. Regulatory and procurement frameworks scramble to accommodate accelerated approval pathways.
Recombinant vector vaccines expressing pathogen antigens in harmless viral backbones now reach commercial livestock and companion animal markets simultaneously. Brazilian cattle operations and German small-animal clinics adopt identical platform architectures. This convergence is collapsing the historical separation between production animal and pet therapeutic innovation cycles.
EU Green Deal agricultural sustainability targets now extend to veterinary pharmaceutical environmental fate. ECHA REACH registrations require ectoparasiticide degradation pathway documentation. Nordic and Benelux livestock operations face procurement restrictions on persistent soil contaminants, forcing reformulation investments.
Subscription-based preventive care plans now displace fee-for-service billing at United States companion animal practices. Younger pet owners in coastal metropolitan areas prefer predictable monthly expenditures covering vaccines, diagnostics, and chronic monitoring. Clinic revenue models restructure around retention metrics rather than episodic transaction volume.
Veterinary Medicine Market Segmentation
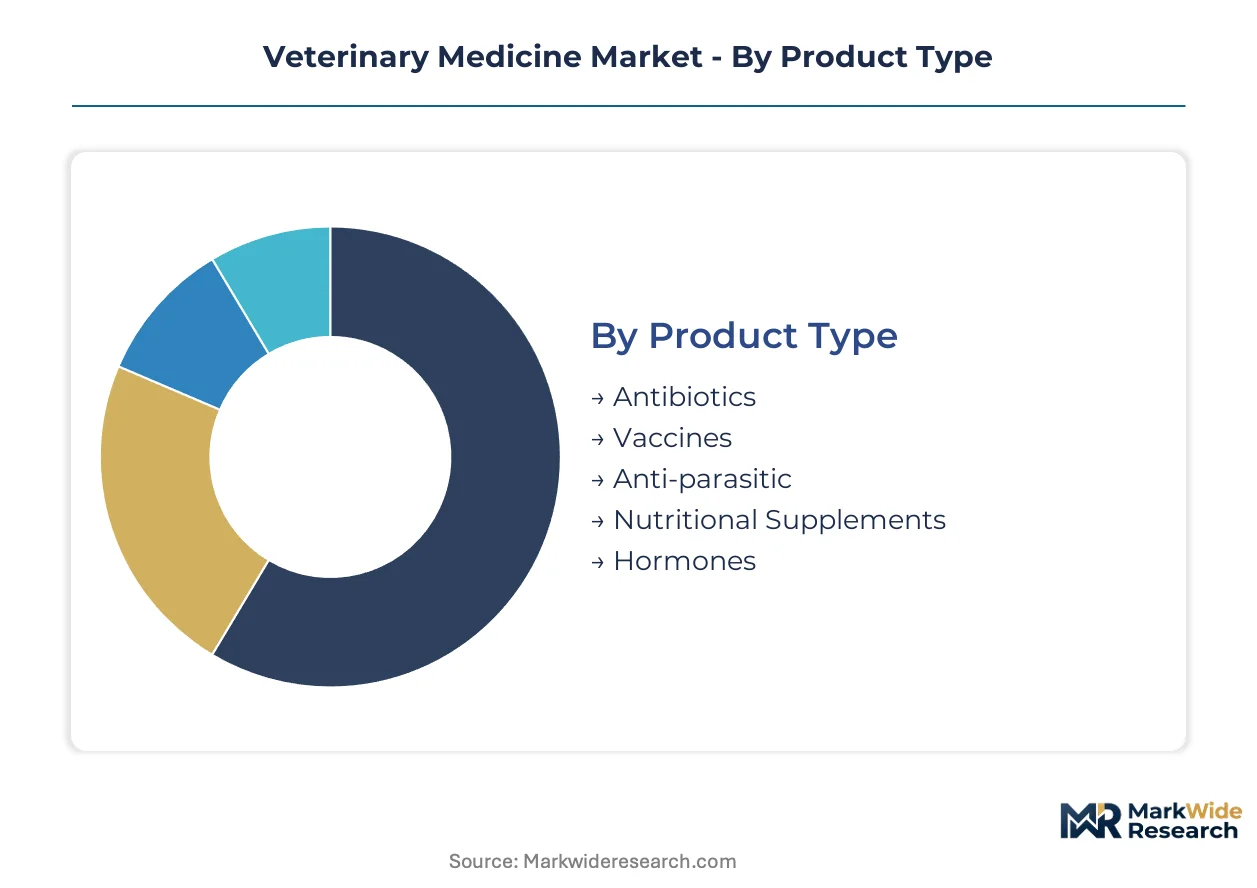
Veterinary medicine segmentation reveals divergent margin architectures across product categories and customer channels. Understanding these divisions illuminates where capital deployment yields sustainable returns versus commoditized pressure.
Product Type:
Use-case spectrum spans preventive biologics for herd immunity through therapeutic interventions for established disease states.
- Vaccines:Recombinant and mRNA formulations require cold-chain distribution at two to eight degrees Celsius. Brazilian cattle operations and German companion animal clinics drive demand for strain-matched updates that inactivated platforms cannot deliver.
- Anti-parasitic:Endectocides address multi-pathogen burdens in commercial livestock. India and China concentrate procurement of pour-on formulations and injectable macrocyclic lactones for small ruminant and cattle operations.
- Antibiotics:FDA residue protocols and antimicrobial stewardship mandates compress development pipelines for food animal applications.
- Nutritional Supplements:Microbiome-targeted formulations enter wellness protocols at specialty clinics in the United States.
- Hormones:Reproductive synchronization products serve dairy and beef breeding programs with regulatory restrictions varying by export market.
The dominant share belongs to Anti-parasitic, while Vaccines is closing the gap fastest.
Therapy Area:
Cost tier separation distinguishes commodity prophylaxis from premium specialty interventions.
- Infectious Diseases:Viral and bacterial pathogen management commands the largest therapeutic expenditure across species. Companion animal owners in Western Europe spend per-capita on preventive protocols while Brazilian livestock operations prioritize foot-and-mouth and brucellosis control.
- Dermatology:Chronic allergy management and otitis externa protocols generate recurring clinic visits. United States specialty practices expand service menus for atopic dermatitis in canines.
- Gastrointestinal Disorders:Nutritional and pharmacological interventions address production losses in feedlot cattle and companion animal gastric pathologies.
- Respiratory Conditions:Bovine respiratory disease complexes drive antibiotic and vaccine expenditure in North American feedyards.
- Reproductive Health:Synchronization protocols and fertility therapeutics support artificial insemination programs in dairy operations.
Infectious Diseases captures the largest revenue pool, with Dermatology expanding most quickly through specialty clinic channel development.
End User:
Customer type determines purchasing sophistication and price elasticity across the value chain.
- Veterinary Clinics:Independent and corporate small-animal practices generate recurring pharmaceutical demand through wellness plan subscriptions. Coastal metropolitan areas in the United States show highest per-patient expenditure on preventive oncology and chronic monitoring.
- Animal Hospitals:Emergency and referral centers concentrate advanced surgical and medical oncology cases. Board-certified specialist shortages limit service expansion in rural and exurban corridors.
- Livestock Farms:Commercial cattle, swine, and poultry operations purchase vaccines and anti-parasitics through direct sales and feed store channels.
- Research Laboratories:Contract research organizations and academic institutions procure specialized compounds for toxicology and efficacy studies.
- Zoos:Exotic species collections require customized formulations with limited regulatory pathways.
Veterinary Clinics retain the dominant position, though Animal Hospitals gain share through consolidation and specialty service expansion.
Distribution Channel:
Supply concentration varies from manufacturer-direct relationships to fragmented retail networks.
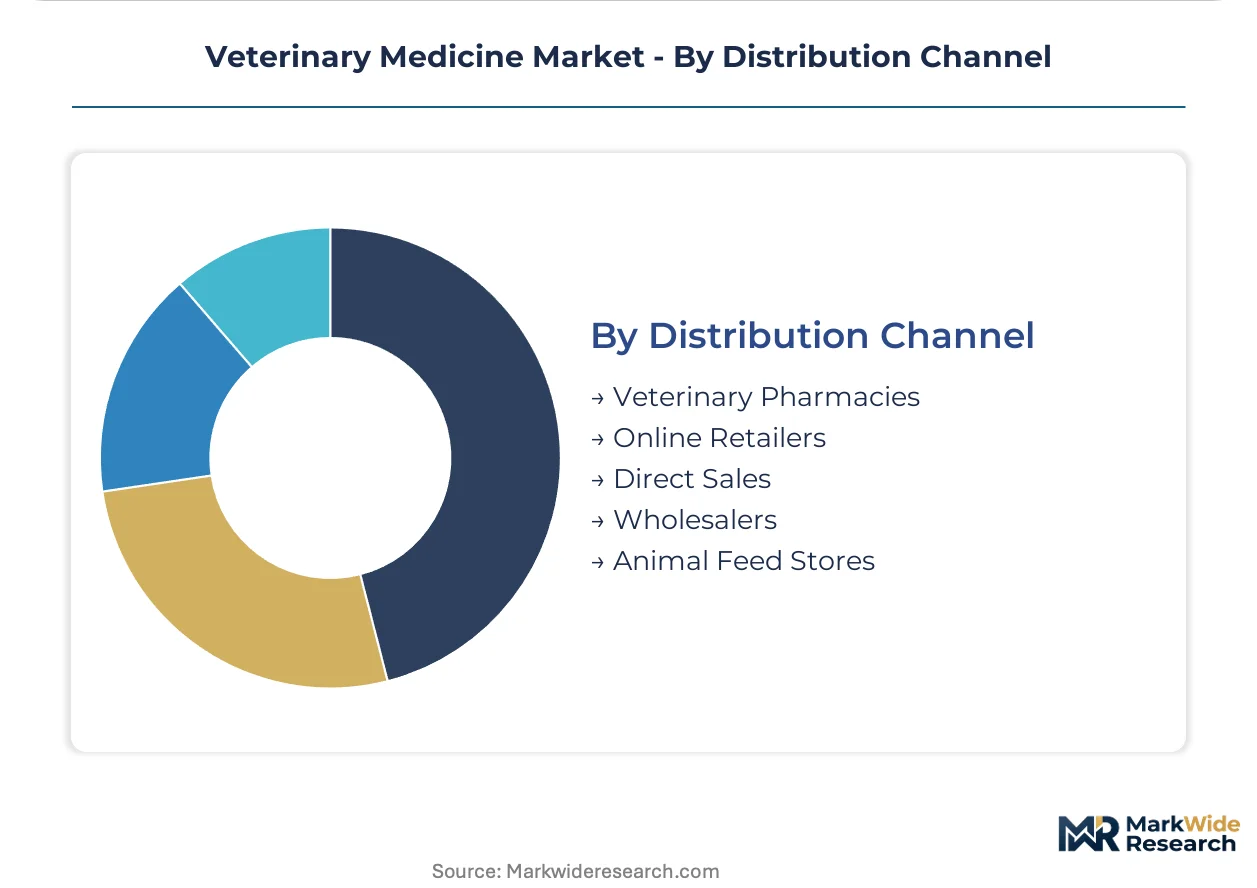
- Veterinary Pharmacies:Clinic-integrated dispensing captures prescription fulfillment at point-of-care. Australia and Canada adapt regulatory frameworks for telemedicine-enabled remote prescribing.
- Direct Sales:Vaccine manufacturers maintain field technical service teams for large livestock operations. Merck Animal Health and Boehringer Ingelheim deploy species-specific specialists to major dairy and feedyard accounts.
- Online Retailers:E-commerce platforms expand in companion animal OTC categories with prescription verification challenges.
- Wholesalers:Regional distributors serve independent clinics with inventory financing and logistics support.
- Animal Feed Stores:Rural retail channels supply over-the-counter anti-parasitics and nutritional supplements to producer customers.
Veterinary Pharmacies command the largest volume, while Direct Sales climbs fastest through livestock biologics procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing for veterinary antibiotics clusters heavily in China and India, while finished formulation and biologics production concentrates in the United States, Germany, and Brazil. Cold-chain distribution networks now extend into previously underserved rural corridors across emerging economies.
United States
Companion animal owners in coastal metropolitan areas drive per-capita spending on preventive oncology and chronic disease management. The FDA Center for Veterinary Medicine tightened residue-monitoring protocols for food-producing animals in 2023. Specialty veterinary clinics in California and New York expand service menus for atopic dermatitis and diagnostic imaging.
Brazil
Commercial cattle operations concentrate demand for foot-and-mouth and brucellosis vaccines alongside pour-on anti-parasitic formulations. ANVISA coordinates with the Ministry of Agriculture on veterinary pharmaceutical registration pathways. São Paulo state hosts the largest concentration of feedlot operations adopting mRNA vaccine platforms for rapid strain-matched updates.
Germany
Equine and swine portfolios generate premium margins through specialized therapeutic formulations. EU Green Deal agricultural sustainability targets extend to veterinary pharmaceutical environmental fate under ECHA REACH registrations. Baden-Württemberg harbors precision livestock farming clusters integrating diagnostic-to-therapeutics platforms.
China
Domestic livestock vaccine manufacturing scales to serve pork and poultry operations recovering from African swine fever disruptions. The NMPA governs veterinary drug approval pathways with residue tolerance limits for export-oriented producers. Sichuan province concentrates small ruminant operations procuring anti-parasitic agents through provincial veterinary stations.
India
Small ruminant and dairy cooperatives drive volume procurement of generic antibiotics and nutritional supplements. CDSCO regulates veterinary drug manufacturing with state-level livestock departments managing distribution. Gujarat and Maharashtra host the densest networks of veterinary polyclinics adopting telemedicine-enabled consultation platforms.
Veterinary Medicine Market Key Industry Players
Integrated pharmaceutical conglomerates and specialized animal health pure-plays split the market between scale-driven vaccine manufacturing and targeted therapeutic development. Consolidation pressures intensify as antimicrobial stewardship mandates compress antibiotic revenue pools while biologics command premium valuations. Three archetypes dominate: diversified human-animal health hybrids, species-focused specialists, and diagnostics-anchored platform integrators. Competitive maneuvering centers on M&A to acquire recombinant vaccine capabilities and strategic partnerships to secure cold-chain distribution in emerging markets.
Among diversified pharmaceutical hybrids, Zoetis Inc. and Merck Animal Health exemplify the integrated diagnostics-to-therapeutics model capturing recurring clinic spending. Boehringer Ingelheim Animal Health occupies a position within the species-specialist tier, differentiated by concentrated equine and swine portfolios. These three entities represent the dominant competitive anchors, with their strategic positioning reflecting broader industry migration toward preventive biologics and away from commoditized small-molecule antibiotics.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Boehringer Ingelheim Animal Health |
| Elanco Animal Health |
| Ceva Santé Animale |
| Virbac |
| Dechra Pharmaceuticals PLC |
| Phibro Animal Health Corporation |
| IDEXX Laboratories |
| Others |
Cost & Logistics Intelligence
Cold-chain corridors connecting São Paulo to rural Brazilian feedlots concentrate freight costs that stratify vaccine pricing between metropolitan clinics and remote livestock operations. This logistics architecture feeds back into manufacturer decisions on formulation stability investments versus distribution subsidies, compressing margins on temperature-sensitive biologics while elevating price premiums for cold-chain-independent small-molecule alternatives.
Pricing Analysis
FDA residue tolerance protocols dictate the pricing tier structure across veterinary therapeutics, separating premium-grade biologics with full regulatory documentation from economy-tier generics operating under abbreviated approval pathways. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with companion animal oncology biologics commanding brand premiums and livestock antibiotics facing cost compression from volume procurement. Price differentiation hinges on cold-chain requirements and species-specific formulation complexity, with dairy cooperatives in India exhibiting highest sensitivity and specialty equine clinics in Germany showing lowest elasticity.
Supply Chain Analysis
Upstream fermentation feedstocks for veterinary vaccine production draw from corn-derived glucose and soy-based peptone suppliers concentrated in the United States Corn Belt and Brazilian Cerrado. Active pharmaceutical ingredient manufacturing for antibiotics clusters in China and India, while finished biologics formulation concentrates in Germany, Brazil, and the United States. Single-source vulnerability pervades recombinant protein production, where dedicated cell culture facilities prevent cross-utilization with human pharmaceutical assets. Distribution runs through veterinary pharmacy networks in developed markets and provincial veterinary stations in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary medicine sits in early-cycle expansion as mRNA platform adoption accelerates strain-matched vaccine development timelines and subscription-based preventive care models penetrate metropolitan companion animal markets.
For Market Incumbents: Pre-empt generic erosion in small-molecule anti-parasitics by accelerating recombinant vaccine pipeline investments and securing captive cold-chain distribution in Brazilian and Indian rural corridors. Backward integration into API fermentation capacity mitigates geopolitical exposure from China and India supply concentration. Regulatory stewardship mandates present consolidation leverage against mid-tier antibiotic-dependent competitors.
For New Entrants and Emerging Players: Establish a beachhead in microbiome-targeted nutritional supplements, where development burdens trail pharmaceutical thresholds and specialty clinic channel access remains fragmented. Precision nutrition protocols at United States coastal metropolitan practices offer the most penetrable entry vector. Telemedicine-enabled prescription platforms in Australia and Canada provide regulatory-adaptable go-to-market infrastructure without brick-and-clinic capital requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diagnostics-anchored platform integrators with recurring revenue models over transactional pharmaceutical pure-plays. Long-term viability across the projection horizon rests on species-diversified biologics portfolios and cold-chain logistics ownership. Watch FDA antimicrobial stewardship enforcement intensity as the inflection signal for antibiotic revenue pool compression velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| mRNA Vaccine Platform Expansion | Collapsing development timelines for foot-and-mouth and avian influenza strain updates rewards first-movers with regulatory precedence. |
| Cold-Chain Infrastructure Partnership | Refrigerated distribution networks reaching Indian dairy cooperatives and Brazilian feedlots unlock previously inaccessible biologics demand. |
| Diagnostic-to-Therapeutics Integration | Wellness plan subscriptions at United States specialty clinics capture recurring pharmaceutical spend through point-of-care testing. |
| Precision Nutrition Portfolio Buildout | Microbiome-targeted supplements bypass equivalent development burdens while approaching pharmaceutical margin profiles. |
| Telemedicine Prescription Platform Launch | Remote veterinary consultations in Canada and Australia expand pharmacy fulfillment through centralized compounding regulatory adaptation. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine approval databases, USDA APHIS biologics licensing records, and trade flow customs data. Interviews with veterinary pharmaceutical development executives, regulatory affairs specialists at animal health conglomerates, specialty clinic practice owners, and livestock cooperative procurement managers informed demand-side assumptions. Bottom-up modeling of product-level shipments triangulates against top-down expenditure estimates from national veterinary association surveys.
Forecast inputs span product type segmentation across vaccines, anti-parasitics, antibiotics, and nutritional supplements; therapy area splits between infectious disease prophylaxis and chronic condition management; and end-user channels distinguishing companion animal clinics from livestock operations. CAGRs derive from regression analysis against antimicrobial stewardship policy intensity indices and cold-chain infrastructure penetration curves. Species-specific immunization schedule compliance rates and subscription plan adoption velocity in metropolitan United States markets anchor companion animal projections.
Sensitivities concentrate around FDA enforcement trajectory on residue protocols, geopolitical disruption to API export flows from China and India, and mRNA platform regulatory acceptance timelines outside OECD jurisdictions. Cross-checking against national veterinary expenditure surveys from AVMA and FVE is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Global Veterinary Eye Care Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
US Veterinarians Market
Veterinary Medicine
Middle East Veterinary Vaccines Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
Global Newcastle Disease Vaccine Market
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
Veterinary Dental Elevators Market
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
United States Veterinary Healthcare Market
Veterinary Medicine
Veterinary Forceps Market
Veterinary Medicine
Veterinary Palliative Care Management Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
South Africa Veterinary Medicine Market
Veterinary Medicine
Global Companion Animal Pharmaceuticals Market
Veterinary Medicine
US Veterinary Diagnostics Market