
 Veterinary Hospitals Market | 2026-2036
Veterinary Hospitals Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Hospitals Market Intelligence
FDA Center for Veterinary Medicine guidance on compounded animal drugs is rebalancing capital deployment toward in-house pharmacy infrastructure and staff credentialing. Mars Veterinary Health leverages its multi-specialty platform to sustain referral density across major metropolitan corridors. VetCor anchors regional networks through disciplined clinic aggregation in secondary markets. Ethos Veterinary Health differentiates via 24-hour emergency capacity and residency-trained specialist staffing.
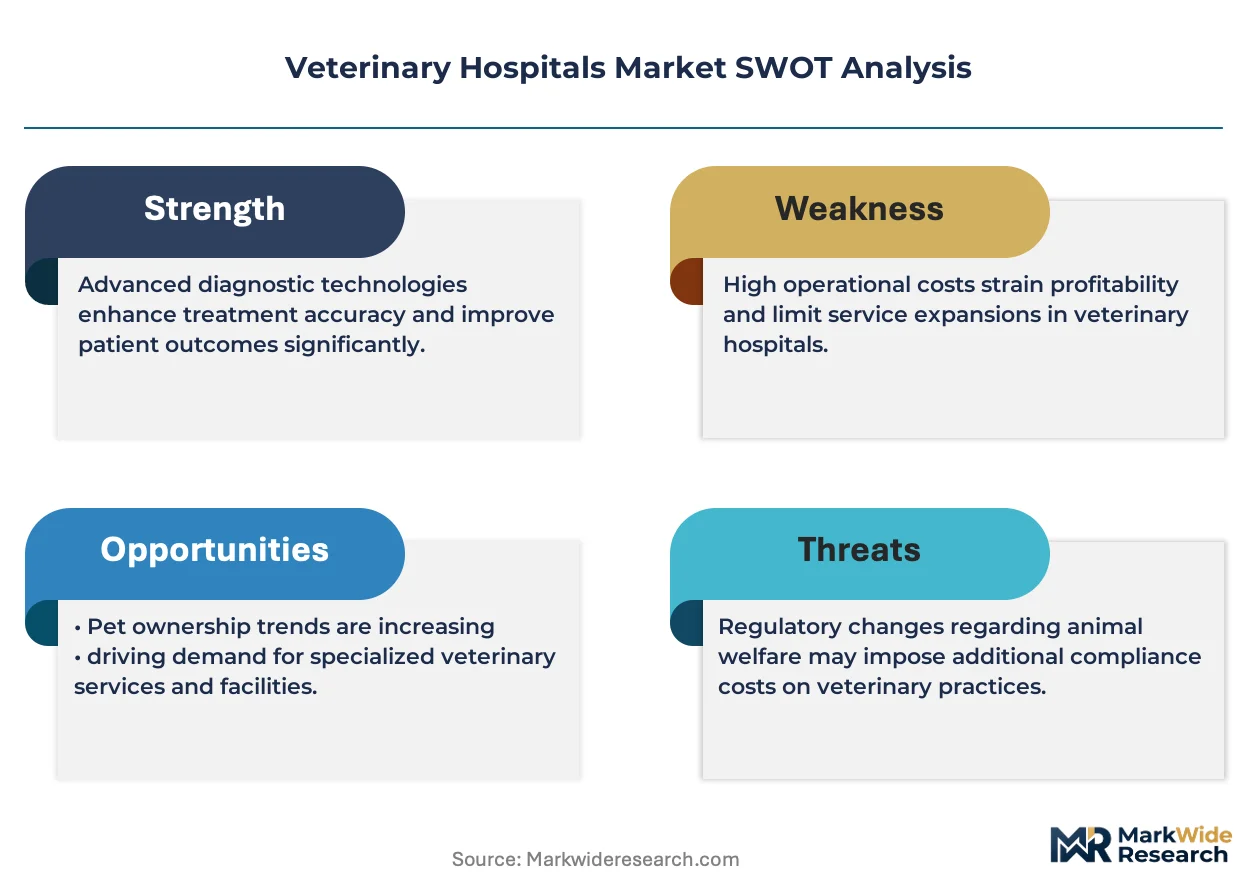
Veterinary hospitals are licensed medical facilities providing diagnostic, surgical, and therapeutic services to companion and production animals, typically operating with imaging suites, sterile surgical theaters, and on-site laboratory capabilities. Surgical procedures and emergency care command premium pricing due to equipment intensity and specialist labor requirements. Small clinics occupy the volume base but face margin compression from rising pharmacy compliance costs. Specialty centers capture disproportionate profit pools through oncology, neurology, and orthopedic referral networks that concentrate high-acuity cases.
USDA Animal and Plant Health Inspection Service biosecurity protocols shape facility design for hospitals treating farm animal patients, while state veterinary practice acts govern corporate ownership limits and telemedicine scope. The EU Veterinary Medicines Regulation mandates pharmacovigilance reporting that elevates IT infrastructure requirements across European hospital chains. Stakeholders must weigh specialty credentialing investments against the operational leverage of consolidated multi-site platforms as labor scarcity intensifies across the sector.
Market Dynamics
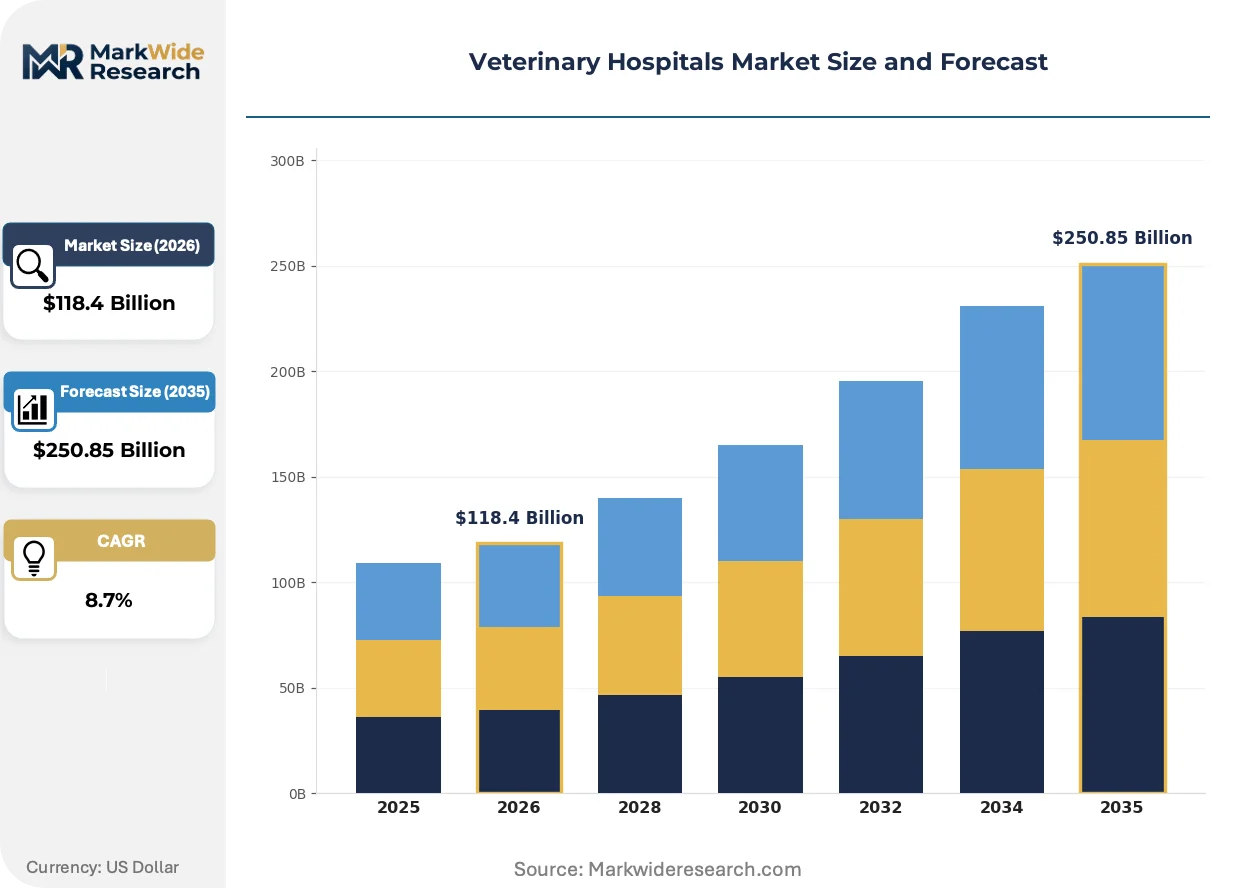
Corporate consolidation is restructuring how veterinary hospitals deploy capital, with specialty referral networks capturing high-acuity cases while independent clinics face pharmacy compliance cost inflation that compresses operating margins.
Growth Catalysts
- FDA Center for Veterinary Medicine compounded drug guidance:The 2023 policy clarification is redirecting hospital investment toward in-house sterile compounding suites and credentialed pharmacy staff.
- Emergency and specialty service volume:Pet owner willingness to pay for 24-hour critical care and board-certified specialists is expanding revenue per case across major metropolitan corridors.
- Diagnostic imaging modality upgrades:MRI and CT installation in regional referral centers is enabling complex neurology and oncology case retention that previously transferred to academic institutions.
Market Restraints
- Veterinary specialist labor scarcity:Residency-trained surgeons and internists command compensation premiums that strain hospital EBITDA, particularly in secondary markets outside major academic feeder zones.
- Pharmaceutical supply concentration:Limited FDA-registered 503B outsourcing facilities for animal drugs creates vulnerability when compounding ingredient sourcing faces disruption.
- EU Veterinary Medicines Regulation pharmacovigilance mandates:European hospital chains must deploy IT infrastructure for adverse event reporting that diverts capital from clinical service expansion.
Strategic Opportunities
- Telemedicine scope expansion:State veterinary practice act modifications in the United States are enabling remote consultation models that extend specialist reach into underserved rural counties.
- Production animal hospital services:USDA biosecurity protocol expertise positions large-animal facilities to capture federal and state contract work for disease surveillance and export certification.
- Oncology service line development:Pet owner demand for radiation therapy and chemotherapy is driving greenfield specialty center construction in markets lacking board-certified veterinary oncologists.
Industry Challenges
- Legacy practice management system integration:Consolidated hospital platforms face data migration complexity when absorbing independent clinics operating on non-interoperable software architectures.
- Sterile compounding facility certification timelines:State board of pharmacy inspections for USP 800 compliance create 12-18 month delays between capital deployment and revenue-generating pharmacy operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Hospitals Market |
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $250.85 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultation, Emergency Care, Surgical Procedures, Rehabilitation Facility Size: Small Clinic, Large Hospital, Specialty Center, Mobile Unit Animal Type: Dogs, Cats, Exotic Pets, Farm Animals End User: Pet Owners, Breeders, Rescue Organizations, Veterinary Professionals |
| Companies Covered | Mars Veterinary Health, National Veterinary Associates, VetCor, Pathway Veterinary Alliance, PetVet Care Centers, BluePearl Pet Hospital, CVS Group, Ethos Veterinary Health, MedVet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Hospitals Market Strategic Shifts & Innovations
Digital pathology and artificial intelligence are compressing diagnostic turnaround times while regulatory harmonization efforts reshape cross-border veterinary pharmaceutical commerce.
Artificial intelligence-assisted radiographic interpretation is overtaking traditional teleradiology workflows in emergency settings. Point-of-care machine learning algorithms now flag critical findings within minutes of image acquisition. Specialty hospitals are deploying this capability to reduce overnight specialist staffing costs while maintaining diagnostic confidence.
EU Veterinary Medicines Regulation implementation is forcing European hospital chains to standardize pharmacovigilance reporting across multi-country networks. The mandate elevates IT infrastructure requirements and creates compliance cost disparities between integrated platforms and independent operators. German and French hospital groups are responding through shared service center consolidation for regulatory reporting functions.
Pet owner payment behavior is fragmenting across subscription wellness plans, third-party financing platforms, and traditional fee-for-service models. Emergency and specialty hospitals are unbundling after-hours surcharges from base procedure pricing to improve price transparency. This shift is most visible in United States coastal metropolitan markets where consumer financial services penetration is highest.
Veterinary Hospitals Market Segmentation
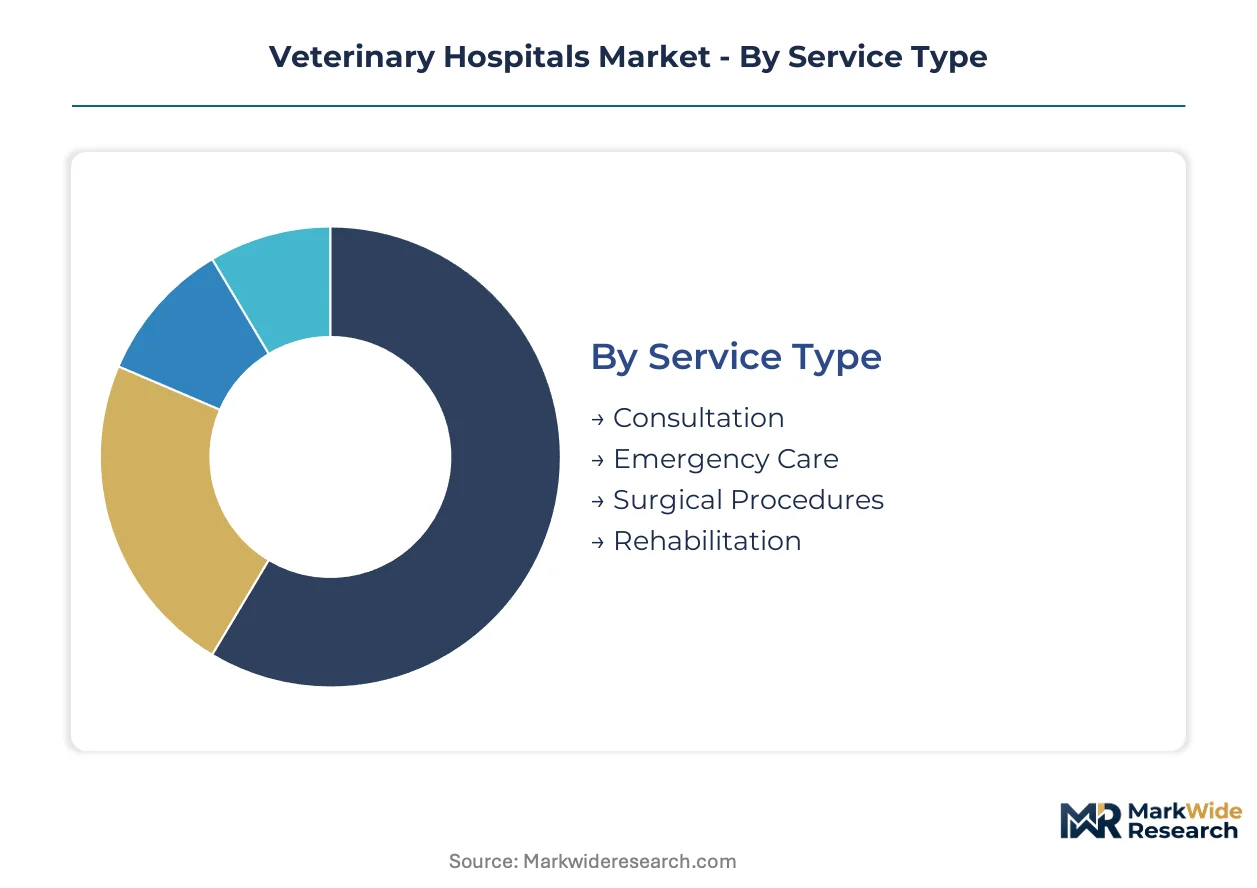
Veterinary hospital segmentation reveals divergent capital requirements and margin profiles across service lines and facility configurations. Understanding these structural differences enables targeted investment allocation and competitive positioning within distinct customer ecosystems.
Service Type:
Emergency care and surgical procedures demand the heaviest upfront capital deployment for imaging suites, sterile theaters, and specialist staffing.
- Surgical Procedures:Orthopedic, soft tissue, and neurological interventions require dedicated sterile theaters with positive pressure ventilation and advanced anesthesia monitoring. Demand concentrates in metropolitan United States corridors where pet insurance penetration and disposable income support premium pricing for board-certified surgical specialists.
- Emergency Care:24-hour critical care operations mandate overnight staffing ratios and continuous monitoring equipment that elevate fixed cost bases. United States coastal markets show the strongest demand concentration as pet owners prioritize immediate access to trauma and toxicology management.
- Consultation:Routine wellness and diagnostic appointments form the volume foundation across general practice networks.
- Rehabilitation:Post-surgical physical therapy and pain management services leverage underwater treadmills and therapeutic laser systems.
Surgical procedures absorb the bulk of installed capacity; emergency care is expanding most quickly.
Facility Size:
Specialty centers and large hospitals capture disproportionate profit pools through high-acuity case concentration and referral network density.
- Specialty Center:Multi-disciplinary referral hubs integrating oncology, cardiology, and neurology under one roof require MRI and CT infrastructure alongside residency-trained specialists. These facilities dominate complex case retention in United States markets with established veterinary school feeder relationships.
- Large Hospital:Full-service campuses combining general practice, emergency, and specialty functions achieve operational leverage through shared imaging and laboratory assets. Secondary United States markets outside major metropolitan cores show rising construction activity as corporate consolidators seek geographic coverage.
- Small Clinic:General practice operations serving routine wellness and minor illness management face margin pressure from rising pharmacy compliance costs.
- Mobile Unit:Deployable surgical and vaccination services address access gaps in rural United States counties with limited permanent veterinary infrastructure.
Large hospitals dominate capital deployment; specialty centers gain share fastest through referral network consolidation.
Animal Type:
Companion animal segments drive revenue concentration while production animal services offer contract stability through regulatory relationships.
- Dogs:Canine patients generate the highest per-case revenue through orthopedic surgery, oncology, and chronic disease management. United States urban and suburban markets concentrate demand for advanced therapeutic interventions and preventive care subscriptions.
- Cats:Feline-specific medicine has emerged as a distinct specialty with dedicated equipment and handling protocols that reduce stress-induced diagnostic artifacts. United States household penetration supports standalone feline-only practices in competitive metropolitan corridors.
- Exotic Pets:Avian, reptile, and small mammal care requires species-specific pharmacology knowledge and anesthesia techniques.
- Farm Animals:Cattle, equine, and swine services tie to USDA biosecurity protocols and export certification workflows that generate recurring government contract revenue.
Dogs anchor volume and value across the sector; exotic pets show the steepest expansion trajectory as ownership demographics shift.
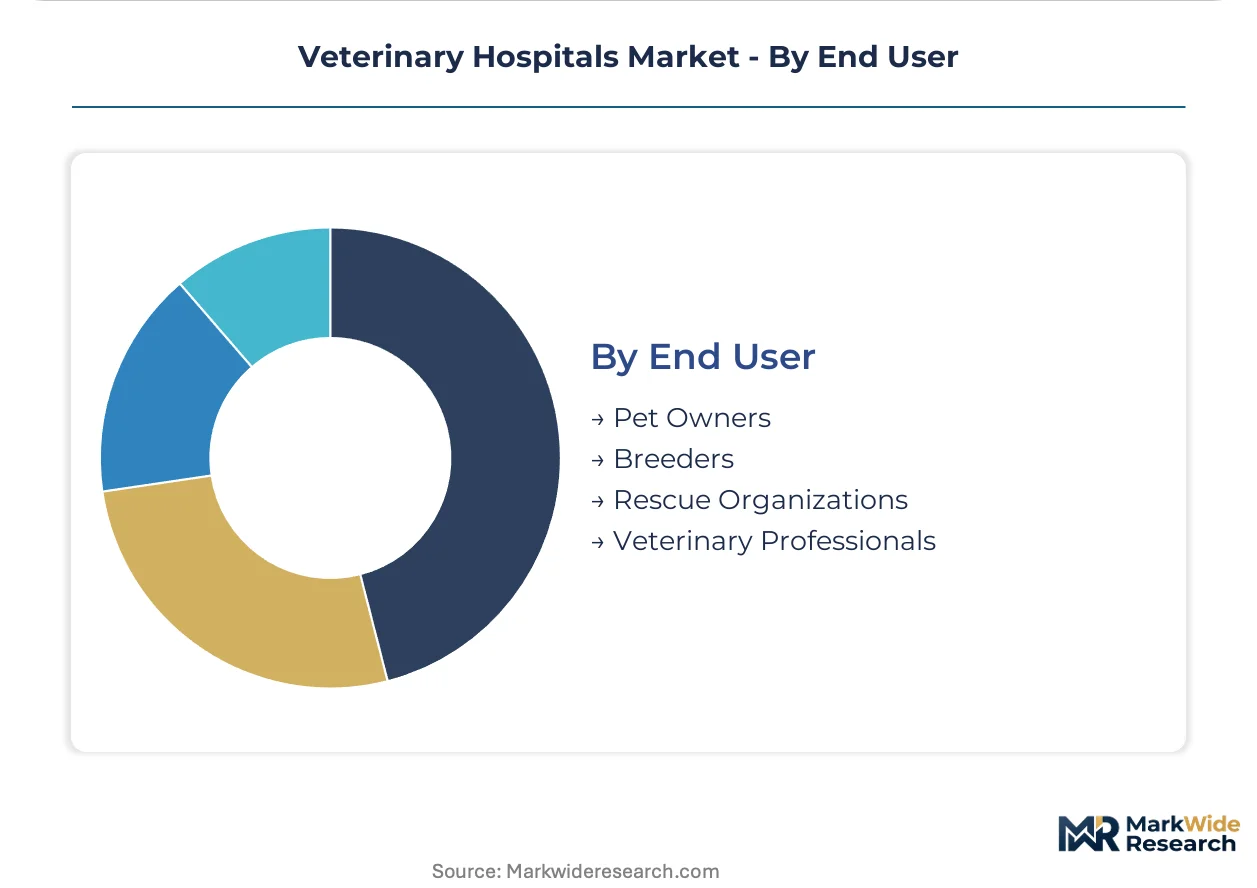
End User:
Payment behavior and case complexity vary sharply between individual pet owners and institutional clients.
- Pet Owners:Individual households drive demand for elective procedures and premium services through third-party financing and wellness plan subscriptions. United States coastal metropolitan markets show the highest willingness to pay for advanced oncology and rehabilitation protocols.
- Veterinary Professionals:Referring general practitioners and specialist consultants create demand for teleradiology, pathology, and continuing education services that support clinical decision-making.
- Breeders:Commercial breeding operations require reproductive services and genetic screening at scale.
- Rescue Organizations:Non-profit shelters generate high-volume surgical and medical cases with constrained reimbursement schedules.
Pet owners command the dominant revenue share; veterinary professionals represent the fastest-climbing segment through teleconsultation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates and Saudi Arabia's economic cities are accelerating veterinary infrastructure investment through customs exemptions and land subsidies for medical facility construction.
United States
Pet insurance penetration exceeding 4 million policies drives specialty referral demand in metropolitan corridors. FDA Center for Veterinary Medicine oversight of compounded drugs elevates pharmacy compliance costs for independent operators. The Dallas-Fort Worth metroplex anchors multi-specialty hospital construction as corporate consolidators target Texas population growth.
Germany
Small animal specialty medicine commands premium pricing in affluent southern states. EU Veterinary Medicines Regulation pharmacovigilance mandates force hospital chains into shared service center consolidation. The Munich-Stuttgart corridor concentrates board-certified specialist training programs that feed regional referral networks.
United Kingdom
Corporate veterinary group acquisition activity reshapes practice ownership structures in England and Scotland. The Royal College of Veterinary Surgeons maintains credentialing standards that limit rapid specialist workforce expansion. Greater London hosts the densest concentration of 24-hour emergency facilities competing for high-acuity cases.
Japan
Declining birth rates and aging demographics elevate companion animal status in urban households. Ministry of Agriculture, Forestry and Fisheries regulations govern animal drug importation and veterinary facility licensing. The Tokyo-Osaka corridor drives demand for advanced oncology and cardiology services as pet owner willingness to pay rises.
Australia
Geographic isolation intensifies reliance on telemedicine for rural veterinary access across vast interior regions. Australian Pesticides and Veterinary Medicines Authority registration requirements create pharmaceutical supply bottlenecks. Sydney and Melbourne metropolitan areas concentrate specialty hospital investment as urban pet ownership rates climb.
Veterinary Hospitals Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market segments. The sector exhibits moderate consolidation with corporate platforms capturing referral network density while independent clinics retain volume share in secondary markets. Three archetypes dominate: multi-specialty referral hubs, regional clinic aggregators, and emergency-focused operators. M&A activity and in-house pharmacy infrastructure deployment constitute the primary competitive vectors reshaping capital allocation.
Within the corporate consolidator tier, Mars Veterinary Health, VetCor, and Ethos Veterinary Health exemplify divergent scale strategies. Mars Veterinary Health occupies a position as the diversified conglomerate archetype with multi-specialty platform breadth. VetCor represents the disciplined regional aggregator model targeting secondary market density. Ethos Veterinary Health anchors the emergency-specialty hybrid segment with 24-hour capacity as a core differentiator.
| Leading Market Players |
|---|
| Mars Veterinary Health |
| National Veterinary Associates |
| VetCor |
| Pathway Veterinary Alliance |
| PetVet Care Centers |
| BluePearl Pet Hospital |
| CVS Group |
| Ethos Veterinary Health |
| MedVet |
| Others |
Cost & Logistics Intelligence
Residency-trained veterinary specialists concentrated in the United States coastal metropolitan corridors drive labor-cost differentials that widen pricing-tier spreads between emergency-specialty hubs and general practice clinics. Board-certified surgeon scarcity in secondary markets forces premium wage premiums that hospitals pass through to pet owners, while FDA pharmacy compliance investments compress margins at independent operators unable to amortize fixed costs across multi-site platforms.
Pricing Analysis
Lead-time-driven pricing stratifies across emergency, urgent, and scheduled appointment tiers, with 24-hour critical care commanding substantial premiums over daytime specialist consultations. Three-tier pricing structure across premium specialty, standard general practice, and economy wellness plan levels reflects equipment intensity and credentialing depth. Pricing pressure stems from pharmaceutical ingredient sourcing volatility and specialist labor inflation. Individual pet owners financing elective oncology procedures show lowest price sensitivity; rescue organizations and high-volume breeding operations exhibit highest.
Supply Chain Analysis
Direct-to-hospital distribution channels handle compounded drug and controlled substance flows under FDA Center for Veterinary Medicine oversight, while group purchasing organizations aggregate consumables for corporate hospital networks. Active pharmaceutical ingredient sourcing concentrates in India and China, with finished dosage form manufacturing anchored in the United States and Western Europe. Supply chain risk centers on single-source vulnerability for FDA-registered 503B outsourcing facilities producing sterile compounded preparations. Cold-chain logistics for biologics and radiopharmaceuticals feed from specialized distributors into hospital pharmacy infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial intelligence-assisted diagnostic platforms are displacing traditional teleradiology workflows and overnight specialist staffing models across emergency and specialty hospital networks. This technology transition rewards early adopters with labor cost leverage while stranding legacy-dependent operators.
For Market Incumbents: Deepen in-house pharmacy infrastructure deployment to capture FDA compounding guidance compliance premiums before independent competitors consolidate. Invest in residency-trained specialist recruitment pipelines anchored to United States veterinary school feeder relationships. Vertical integration into sterile compounding suites defends margin position against 503B outsourcing facility supply disruptions. For New Entrants and Emerging Players: Capture telemedicine-enabled specialist consultation white space in rural United States counties where state practice act modifications now permit remote diagnostic support. Target secondary metropolitan markets outside major academic corridors where emergency-specialty capacity scarcity concentrates demand. Deploy mobile surgical units as a go-to-market angle for production animal contract services tied to USDA biosecurity protocols. For Investors and Strategic Acquirers: The window for entry favors multi-site specialty platforms with embedded pharmacy infrastructure and established referral network density. Long-term viability hinges on consolidated platforms achieving operational leverage through shared imaging and laboratory assets across metropolitan corridors. Watch state board of pharmacy USP 800 certification timelines as an inflection indicator for pharmacy revenue realization delays.| Strategic Initiative | Industry Significance |
|---|---|
| In-House Sterile Compounding Suite Deployment | FDA Center for Veterinary Medicine compliance investments redirect capital from outsourced pharmacy toward captive infrastructure. |
| Residency-Trained Specialist Recruitment | Board-certified surgeon and internist hiring anchors referral network density in high-acuity metropolitan markets. |
| AI-Assisted Diagnostic Platform Integration | Machine learning radiographic interpretation reduces overnight staffing costs while maintaining emergency diagnostic confidence. |
| Telemedicine Scope Expansion | State veterinary practice act modifications enable remote specialist reach into underserved rural counties. |
| Oncology Service Line Development | Radiation therapy and chemotherapy capacity construction captures pet owner willingness to pay for advanced cancer protocols. |
Research Approach
Independent corroboration across hospital operations executives, veterinary pharmacy directors, and state board of pharmacy regulators underwrites the qualitative findings on compliance cost trajectories. Primary fieldwork with specialty referral network administrators, corporate consolidator strategy leads, and academic veterinary school faculty combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, EU Veterinary Medicines Regulation implementation notices, and state veterinary practice act legislative records. Bottom-up service line volume modeling and top-down macroeconomic demand indicators were triangulated to anchor segmentation outputs.
Rate-of-change decomposition across service type, facility size, animal type, and end user dimensions structured the analytical framework over the projection horizon. CAGRs were derived from installed capacity trajectories, referral network density evolution, and pet owner payment behavior shifts. Specialist labor supply constraints and pharmaceutical regulatory compliance timelines served as industry-specific forecast inputs alongside corporate consolidation velocity indicators.
The model holds under steady-state regulatory enforcement and stable pet ownership demographics; deviation in FDA compounding policy stringency or state corporate practice of veterinary medicine restrictions would shift trajectory assumptions. Periodic stress-testing of base assumptions against specialist workforce graduation rates and pharmacy certification backlog durations is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Animal Microchip Implant Market
Veterinary
Global Veterinary MRI Market
Veterinary
Veterinary Software Market
Veterinary
Veterinary Vaccines Market
Veterinary
Global Veterinary Infusion Pumps Market
Veterinary
Canine Flu Therapeutics Market
Veterinary
Global Equine Supplement Products Market
Veterinary
Global Veterinary Grooming Aids Market
Veterinary
France Veterinary Healthcare Market
Veterinary
Global Veterinary Telemetry Systems Market
Veterinary
Global Livestock Vaccines Market
Veterinary
Europe Veterinary Antibiotics Market
Veterinary
Veterinary Ultrasound Market
Veterinary
Canine Arthritis Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Veterinary Excipients Market