
 Global Urinalysis Test Market | 2026-2036
Global Urinalysis Test Market Size, Share, and Industry Trends Forecast 2026-2036
Global Urinalysis Test Market Foresight
The urinalysis test market is restructuring around a sharp split between premium automated analyzer systems and commodity dipstick consumables. Siemens Healthineers anchors the high-throughput laboratory segment with integrated workflow platforms. Sysmex Corporation differentiates through flow cytometry-based particle analysis technology. Cardinal Health competes on distribution scale and private-label reagent economics across mid-tier clinical laboratories.
Urinalysis tests encompass chemical and microscopic examination of urine specimens using reagent-impregnated strips, automated photometric analyzers, or particle-counting instruments to detect analytes including glucose, protein, blood, and leukocytes with defined sensitivity thresholds. Automated analyzers command the largest installed base in centralized labs, while point-of-care facilities drive the fastest expansion for CLIA-waived strip readers and handheld devices. Home care settings represent an emerging margin pool as direct-to-consumer monitoring protocols gain reimbursement traction for diabetes and chronic kidney disease management.
FDA CLIA categorization, EU MDR device classification, and Japan PMDA quality management standards collectively shape product registration timelines and market access costs for manufacturers. These frameworks favor companies with established quality systems and predicate device portfolios, raising barriers for new entrants in automated analyzer segments. Stakeholders must weigh capital intensity against consumable recurring revenue when evaluating platform investments across decentralized care models.
Market Dynamics
The urinalysis test market pivots on CLIA-waived device proliferation, which fragments testing authority from centralized laboratories toward point-of-care sites and retail clinics. This regulatory reclassification compresses capital requirements while expanding addressable test volume.
Growth Catalysts
- CLIA-waived pathway expansion:FDA streamlined categorization for waived complexity devices accelerates deployment in physician offices, urgent care chains, and retail health settings across the United States.
- Chronic disease screening protocols:Diabetes and chronic kidney disease management guidelines in Germany and Japan mandate more frequent urine monitoring, driving reagent strip consumption.
- Flow cytometry particle analysis:Automated particle-counting technology reduces manual microscopy labor while standardizing sediment analysis results in high-throughput hospital laboratories.
Market Restraints
- Reagent raw material concentration:Specialty indicator dyes and cellulose matrices depend on concentrated chemical suppliers in China, exposing margins to input volatility and export licensing delays.
- Analyzer platform lock-in:Proprietary reagent-cartridge pairing in automated systems creates switching costs that entrench incumbent vendors and deter mid-tier laboratory migration.
- Limited test menu breadth:Urinalysis remains confined to basic metabolic and infection markers, unable to capture molecular diagnostic revenue streams that attract hospital laboratory capital allocation.
Strategic Opportunities
- Direct-to-consumer home monitoring:Reimbursement traction for diabetes self-management in the United States creates a channel bypassing traditional clinical procurement entirely.
- EU MDR quality system leverage:Manufacturers with established European regulatory infrastructure can expedite registration in Middle Eastern and Southeast Asian markets that recognize CE marking precedents.
- AI-assisted image analysis:Machine learning classification of microscopic urine sediment converges with smartphone camera hardware to enable laboratory-grade interpretation at point-of-care sites lacking trained technologists.
Industry Challenges
- Cross-trained technologist scarcity:Combined hematology-urinalysis competency requirements strain laboratory staffing in Japan and Germany, where vocational pipeline throughput lags instrument installation rates.
- Legacy middleware integration:Newer automated analyzers face protocol translation friction with hospital information systems running decades-old laboratory information management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Urinalysis Test Market |
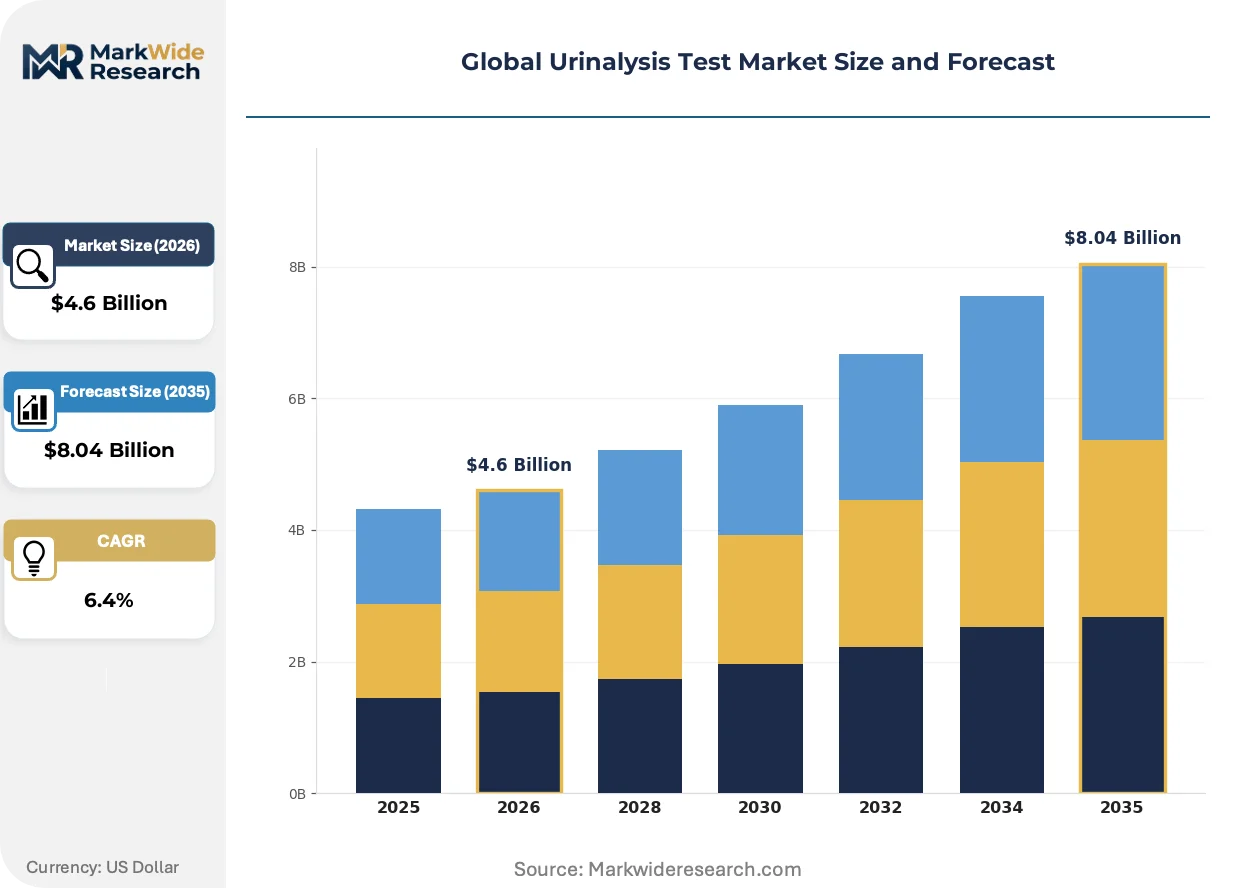
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $8.04 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Strips, Automated Analyzers, Reagent Kits, Microalbumin Test, Dipstick Test Application: Chronic Kidney Disease Detection, Urinary Tract Infection Analysis, Diabetes Monitoring, Drug Screening, Pregnancy Testing End User: Clinical Laboratories, Diagnostic Centers, Research Institutes, Point of Care Facilities, Home Care Settings Technology: Photometry, Electrochemical Analysis, Flow Cytometry, Microscopy, Immunoassay |
| Companies Covered | Siemens Healthineers AG, F. Hoffmann-La Roche Ltd, Cardinal Health Inc., Abbott Laboratories, Danaher Corporation, Sysmex Corporation, Becton, Dickinson and Company, Bio-Rad Laboratories Inc., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Urinalysis Test Market Shifts & Advancements
Digital connectivity and miniaturization are collapsing the physical footprint required for laboratory-grade urinalysis, enabling test migration into non-traditional settings previously unreachable by conventional analyzer platforms.
Smartphone-based dipstick readers is rewriting how point-of-care sites execute urinalysis. These devices use calibrated camera arrays and cloud-hosted algorithms to deliver quantitative results comparable to photometric analyzers. Urgent care chains in the United States are adopting them at scale to reduce send-out volume. The technology is rewriting competitive boundaries between handheld device manufacturers and traditional laboratory instrument vendors.
EU MDR device classification tightening is elevating quality system documentation requirements for in vitro diagnostic manufacturers seeking European market access. Technical file scrutiny now demands extended clinical performance evidence even for established reagent strip categories. Mid-sized manufacturers without predicate device portfolios face elongated registration timelines, while larger entities with dedicated regulatory affairs functions capture accelerated review pathways.
Subscription reagent provisioning is replacing capital purchase models in mid-tier clinical laboratories. Rather than acquiring analyzers outright, facilities lease instruments in exchange for multi-year consumable commitments. This pattern is most visible in Germany, where hospital procurement cooperatives negotiate consolidated supply agreements spanning dozens of member institutions.
Global Urinalysis Test Market Segmentation
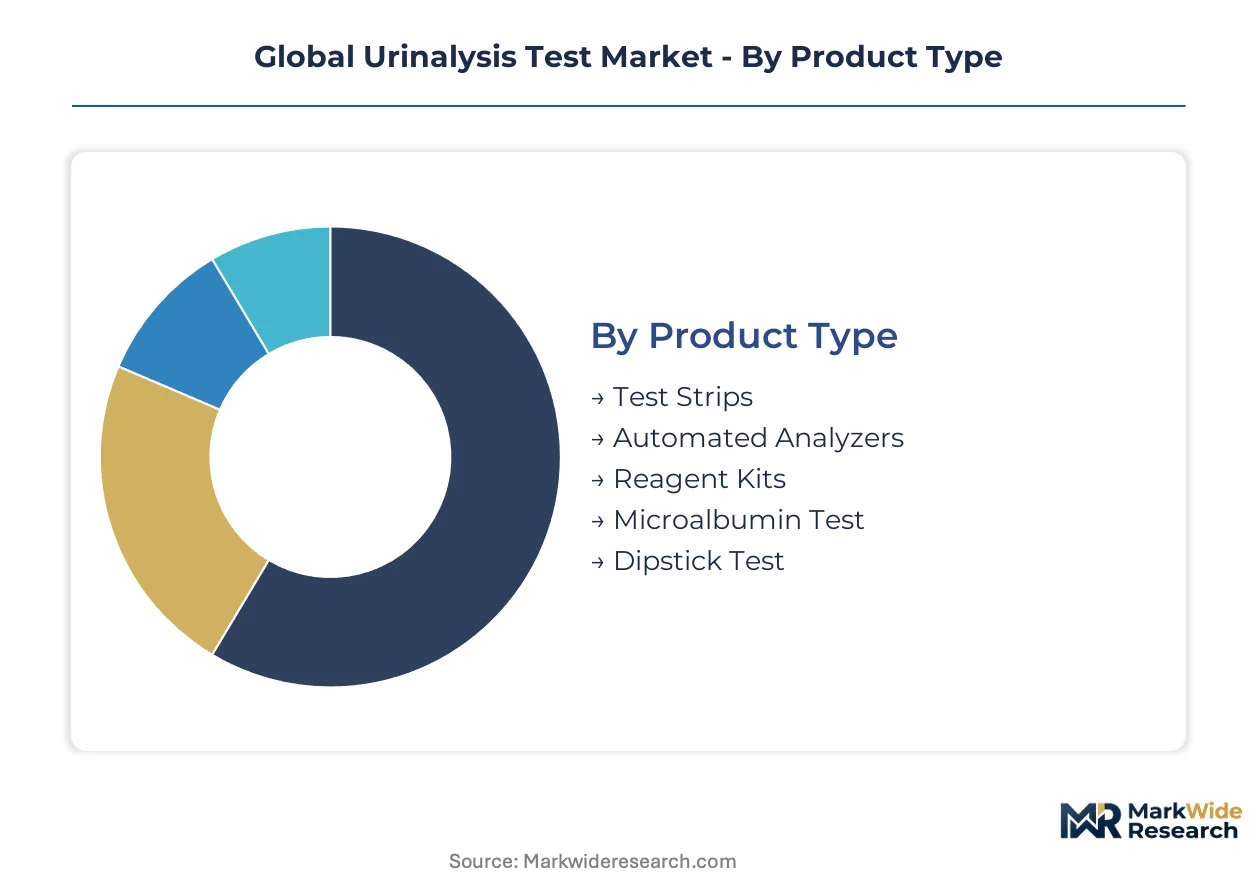
Urinalysis test segmentation reflects a fundamental tension between high-volume consumables and premium instrument platforms. Manufacturers optimize portfolios across this divide, balancing reagent strip economics against analyzer capital intensity.
Product Type:
Volume concentration favors single-use consumables while premium capture concentrates in automated instrumentation.
- Test Strips:Reagent-impregnated cellulose matrices detect glucose, protein, blood, and leukocytes through colorimetric reaction. Demand concentrates in physician offices across the United States where CLIA-waived protocols expand point-of-care deployment. Raw material exposure to Chinese specialty dye suppliers creates margin volatility.
- Automated Analyzers:Photometric and particle-counting instruments process 100-800 samples hourly with standardized sediment classification. Germany's hospital procurement cooperatives drive consolidated leasing arrangements for these platforms. Capital requirements and proprietary cartridge lock-in entrench incumbent vendors.
- Reagent Kits:Calibrated liquid reagents for quantitative analyte measurement in laboratory settings.
- Microalbumin Test:Specialized immunoassay detection for early diabetic nephropathy screening in Japan's chronic disease protocols.
- Dipstick Test:Basic multi-parameter strips for rapid qualitative screening in urgent care chains.
Today's leader: Automated Analyzers. Tomorrow's challenger: Test Strips.
Application:
Disease surveillance priorities in developed economies concentrate procurement around metabolic and infectious markers.
- Chronic Kidney Disease Detection:Albumin-to-creatinine ratio monitoring enables early intervention before glomerular filtration decline. Japan's Ministry of Health mandates annual screening for diabetic populations, driving microalbumin test consumption through national health insurance reimbursement.
- Urinary Tract Infection Analysis:Leukocyte esterase and nitrite detection strips provide rapid bacterial presence indication. Urgent care expansion in the United States displaces send-out culture volume toward same-day diagnosis.
- Diabetes Monitoring:Glucose and ketone tracking for glycemic control assessment in home and clinical settings.
- Drug Screening:Employment and forensic toxicology panels for amphetamine, opioid, and cannabinoid detection.
- Pregnancy Testing:Human chorionic gonadotropin detection for over-the-counter and clinical confirmation use.
Chronic Kidney Disease Detection commands premium pricing. Diabetes Monitoring scales fastest.
End User:
Site-of-care migration fragments traditional laboratory concentration toward distributed testing nodes.
- Clinical Laboratories:High-throughput hospital and reference labs running 500+ daily samples on integrated workflow platforms. Germany's technologist shortage strains operational capacity despite analyzer automation.
- Point of Care Facilities:Physician offices, retail clinics, and urgent care sites executing CLIA-waived protocols with handheld readers. FDA streamlined categorization accelerates United States deployment.
- Diagnostic Centers:Independent outpatient facilities processing referred specimens on mid-tier analyzers.
- Research Institutes:Academic and pharmaceutical research applications requiring specialized analyte panels.
- Home Care Settings:Direct-to-consumer monitoring for diabetes self-management with smartphone-connected dipstick readers.
Clinical Laboratories retain revenue concentration. Home Care Settings gain share fastest.
Technology:
Measurement modality determines accuracy, throughput, and capital requirements for platform selection.
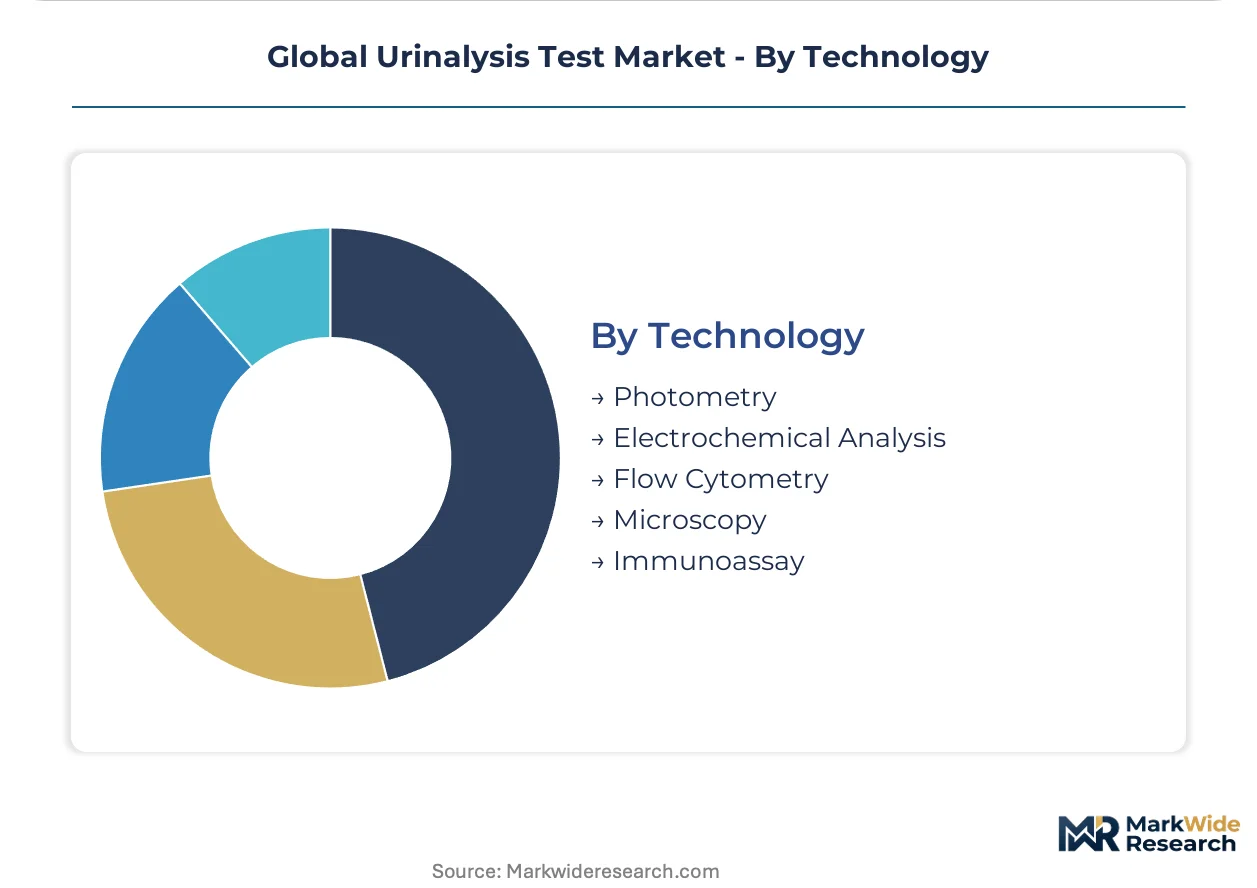
- Flow Cytometry:Laser-based particle counting standardizes sediment analysis without manual microscopy. Sysmex Corporation anchors this segment in Japanese and German hospital laboratories where technologist scarcity demands full automation.
- Photometry:Light absorbance measurement for colorimetric reagent strip quantification. United States mid-tier laboratories favor these systems for reagent cost flexibility.
- Electrochemical Analysis:Ion-selective electrode detection for specific analyte measurement.
- Microscopy:Manual and automated sediment examination for cellular morphology assessment.
- Immunoassay:Antibody-based detection for microalbumin and specialized markers.
Photometry dominates installed base. Flow Cytometry climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized laboratory technologists concentrate in Germany, Japan, and the United States, anchoring automated analyzer deployment and creating regional capacity constraints that shape procurement patterns.
United States
Physician office expansion and urgent care chain proliferation drive CLIA-waived device consumption. FDA streamlined categorization protocols accelerate point-of-care deployment timelines. The Dallas-Fort Worth metroplex hosts major distribution hubs serving retail health networks.
Germany
Hospital procurement cooperatives negotiate consolidated leasing arrangements for high-throughput platforms. EU MDR device classification tightening elevates quality system documentation requirements for reagent strip registration. The Rhine-Ruhr metropolitan region concentrates analyzer maintenance and technical service operations.
Japan
Ministry of Health mandates for diabetic population screening sustain microalbumin test volume through national health insurance. PMDA quality management standards shape product registration timelines for automated sediment classification systems. The Osaka-Kobe industrial corridor anchors flow cytometry particle analysis manufacturing.
China
Domestic reagent strip production scales to serve mid-tier clinical laboratories seeking cost flexibility. NMPA medical device registration pathways determine market access timelines for imported automated platforms. The Yangtze River Delta clusters specialty indicator dye suppliers serving cellulose matrix manufacturers.
United Kingdom
NHS chronic kidney disease surveillance protocols sustain albumin-to-creatinine ratio monitoring demand across primary care networks. MHRA post-Brexit regulatory alignment with EU MDR technical file standards influences registration strategies. The Cambridge-Oxford-London triangle concentrates digital health startups developing smartphone-based dipstick readers.
Global Urinalysis Test Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the urinalysis test market, with integrated workflow platform vendors facing pressure from modular point-of-care specialists. The vendor base concentrates around three tiers: multinational conglomerates with predicate device portfolios, mid-sized regional manufacturers with distribution scale, and emerging digital health entrants with software-centric business models. Dominant competitive moves include strategic partnerships between instrument manufacturers and cloud-based analytics providers, plus portfolio diversification into adjacent diagnostic modalities.
Within the multinational conglomerate tier, Siemens Healthineers AG and Sysmex Corporation exemplify divergent technology anchoring strategies. Danaher Corporation occupies a position spanning both analytical instrumentation and life sciences consumables. Among these, the German AG-structured entity and the Japanese Corporation-structured entity represent contrasting geographic foundations for regulatory pathway navigation.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| F. Hoffmann-La Roche Ltd |
| Cardinal Health Inc. |
| Abbott Laboratories |
| Danaher Corporation |
| Sysmex Corporation |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories Inc. |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap reagent strip manufacturers anchor the supply base for cellulose matrix production, connecting concentrated specialty dye sourcing in China to pricing discipline enforced by German hospital procurement cooperatives and United States urgent care volume buyers.
Pricing Analysis
Bundled instrument-and-consumable leasing arrangements dominate automated analyzer procurement, while unbundled per-strip transactional pricing prevails in point-of-care settings. Three-tier pricing structure across premium flow cytometry platforms, standard photometric systems, and economy-grade dipsticks reflects certification grade and after-sales service bundling. Cost compression in the economy strip tier is intensifying because Chinese dye export licensing delays squeeze contract manufacturers. Physician offices and retail clinics exhibit the highest price sensitivity, whereas Japanese hospital laboratories absorbing Ministry of Health reimbursement rates show the least.
Supply Chain Analysis
Single-source vulnerability sits with specialty indicator dye production concentrated in the Yangtze River Delta region of China. Raw material procurement draws from Chinese cellulose matrix suppliers, German optical component manufacturers, and Japanese precision electronics fabricators. Tariff exposure on reagent-grade chemicals creates margin volatility for strip assemblers. Distribution runs through Cardinal Health and regional medtech distributors serving hospital procurement cooperatives in Germany and GPO-contracted health systems in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urinalysis test market functions as a stable compounder, with chronic disease screening mandates in Japan and Germany generating predictable reagent consumption regardless of economic cycles.
For Market Incumbents: Anticipate smartphone-based dipstick reader entrants eroding point-of-care instrument margins by accelerating CLIA-waived protocol adoption in United States urgent care chains. Defensive consolidation should emphasize backward integration into specialty dye sourcing to offset Chinese supply volatility, paired with AI-assisted sediment classification R&D to maintain laboratory workflow platform differentiation against modular competitors. For New Entrants and Emerging Players: Enter via direct-to-consumer home monitoring channels for diabetes self-management in the United States, where reimbursement traction bypasses traditional hospital procurement entirely. White-space targets include smartphone-connected microalbumin readers for Japan's mandated diabetic screening population and cloud-hosted sediment analysis software for point-of-care sites lacking trained technologists. A software-centric go-to-market angle with minimal hardware capital requirements offers the most penetrable entry path. For Investors and Strategic Acquirers: Diagnostic conglomerates with established FDA predicate device portfolios are the most active acquirers in this space, seeking CLIA-waived platform capabilities to complete decentralized testing portfolios. The long-term viability window favors targets with consumable recurring revenue models over capital-intensive analyzer manufacturers. Watch FDA streamlined categorization expansion into over-the-counter home testing as the signal indicating inflection toward consumer-channel revenue pools.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-waived Device Expansion | FDA streamlined pathways accelerate deployment in United States retail health networks. |
| Backward Integration into Dye Sourcing | Captive supply of Chinese specialty indicators mitigates export licensing margin volatility. |
| AI-assisted Sediment Classification | Machine learning algorithms enable laboratory-grade interpretation at technologist-scarce sites. |
| Subscription Reagent Provisioning | German hospital cooperatives favor multi-year consumable commitments over capital purchase. |
| Direct-to-Consumer Channel Development | Reimbursement traction for diabetes self-management bypasses traditional clinical procurement. |
Research Methodology
Multiple input streams — hospital purchasing committee interviews, GPO contracts database analysis, regulatory filing review, and trade flow reconciliation — were reconciled to construct market estimates. Primary discussions with biomedical engineers, clinical laboratory directors, GPO contracts managers, and FDA regulatory affairs specialists were validated against secondary sources including FDA 510(k) clearances, EU MDR technical file databases, CMS Medicare reimbursement schedules, and import-export customs records. Bottom-up instrument installation counts and top-down healthcare expenditure allocation were triangulated for consistency.
Data-stream reconciliation across product type, application, end user, technology, and regional regulatory cluster dimensions informed the analytical framework across the projection horizon. CAGRs were derived from segmented volume trajectory modeling incorporating chronic disease prevalence trends, CLIA-waived protocol expansion rates, and reimbursement policy evolution. Industry-specific inputs included Japanese Ministry of Health screening mandate compliance rates and German hospital procurement cooperative leasing contract renewal patterns.
Inputs from FDA premarket notification databases and EU MDR notified body technical file registries were available through the study window; gaps in private-label reagent strip manufacturer financial disclosures introduce uncertainty bands around mid-tier laboratory consumable estimates. Forecasts reflect assumptions regarding regulatory pathway continuity and chronic disease screening protocol stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Endocrine Peptides Test Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
Asia-Pacific Newborn Screening Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
Platelet Function Test Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
South America Endotoxin and Pyrogen Testing Market
Testing Services
Host Cell Protein Testing Market
Testing Services
Cannabis Testing Services Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
Urine Testing Cups Market