
 Pathology Services Market | 2026-2036
Pathology Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pathology Services Market Analytics
CLIA certification is reorganizing competitive tiers in the Pathology Services Market by mandating rigorous personnel qualifications, equipment validation, and quality management systems that smaller independent labs struggle to sustain. Quest Diagnostics leverages its national laboratory network to anchor high-volume clinical pathology operations across multiple states. Sonic Healthcare competes through its integrated model combining anatomic pathology with outpatient clinic partnerships in Australia and Europe. Mayo Clinic Laboratories differentiates on subspecialty expertise, drawing complex case referrals from academic medical centers worldwide.
Pathology services encompass the laboratory analysis of tissue, cell, and fluid specimens to diagnose disease, guide treatment selection, and monitor therapeutic response, utilizing techniques ranging from conventional histology with hematoxylin and eosin staining to multiplex immunofluorescence and nucleic acid amplification. The primary commercial purpose centers on generating actionable diagnostic reports that inform clinical decision-making across oncology, infectious disease, and inherited disorder management. Molecular pathology commands expanding margin pools as next-generation sequencing panels replace single-gene assays in cancer diagnosis, while digital pathology infrastructure investments reshape workflow economics for anatomic pathology services. Diagnostic laboratories represent the fastest-growing end-user channel as hospital outsourcing accelerates and independent reference labs capture volume from health system consolidation.
CLIA, CAP accreditation standards, and FDA oversight of laboratory-developed tests collectively shape market access, reimbursement eligibility, and operational compliance burdens for service providers. The EU In Vitro Diagnostic Regulation introduces new conformity assessment requirements that European operators must navigate for molecular pathology assays. Stakeholders must monitor evolving payer coverage policies for advanced diagnostic testing and assess whether platform investments in digital pathology and artificial intelligence-assisted image analysis align with emerging quality-based reimbursement frameworks.
Market Dynamics
Digital pathology platforms are compressing turnaround times for anatomic pathology services while CLIA certification requirements filter out smaller independent laboratories unable to sustain quality management infrastructure.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage decisions for molecular diagnostic panels redirect hospital capital toward next-generation sequencing capabilities in oncology workflows.
- Artificial intelligence-assisted image analysis:FDA-cleared algorithms for prostate cancer and lymphoma detection accelerate diagnostic throughput in high-volume anatomic pathology laboratories.
- Hospital system consolidation:Merged health networks centralize laboratory procurement, favoring reference laboratories with multi-state CLIA licenses and subspecialty pathologist coverage.
Market Restraints
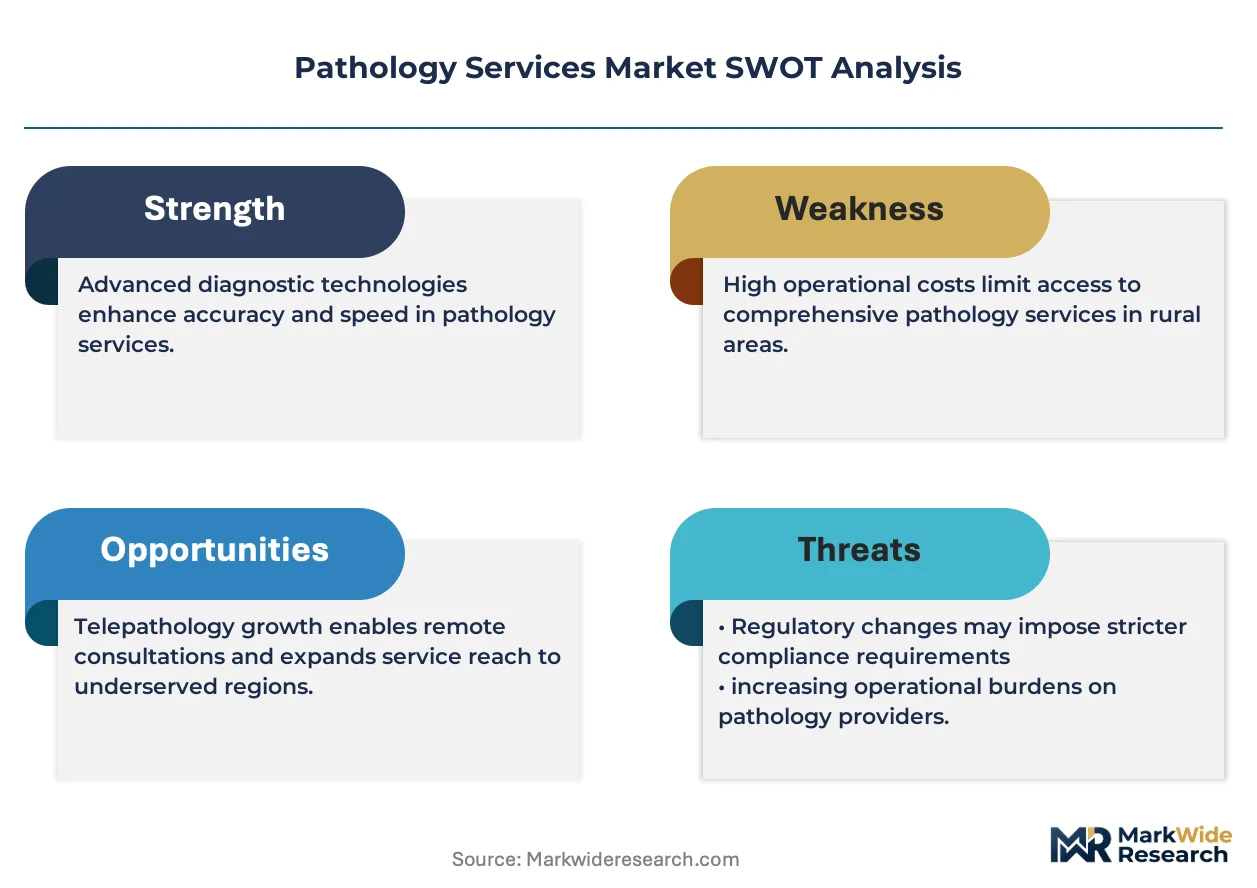
- Whole slide scanner capital intensity:Digital pathology infrastructure demands seven-figure equipment investments plus five-year IT integration timelines that constrain mid-sized laboratory expansion.
- Laboratory-developed test regulatory uncertainty:FDA draft guidance on LDT oversight creates compliance timeline ambiguity, freezing assay development budgets at academic medical centers.
- Pathologist workforce constraints:Fellowship-trained subspecialists concentrate in metropolitan academic centers, creating diagnostic capacity bottlenecks for rural and community hospital systems.
Strategic Opportunities
- Remote pathology services in underserved states:Telepathology platforms enable board-certified subspecialists to cover low-volume markets across Montana, Wyoming, and North Dakota without physical relocation.
- Companion diagnostic co-development:Pharmaceutical manufacturers seek integrated pathology partners for biomarker validation during Phase II oncology trials, creating sticky revenue relationships.
- EU In Vitro Diagnostic Regulation implementation:European laboratories face 2027 conformity assessment deadlines for molecular assays, opening consulting and validation service contracts for US-based reference laboratories with prior MDR experience.
Industry Challenges
- Laboratory information system interoperability:Proprietary data formats from Leica, Philips, and Hamamatsu scanners block seamless image exchange between health systems, forcing expensive middleware investments.
- CLIA personnel qualification maintenance:High-complexity testing directors must document continuing education credits and competency assessments across expanding test menus, consuming administrative bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pathology Services Market |
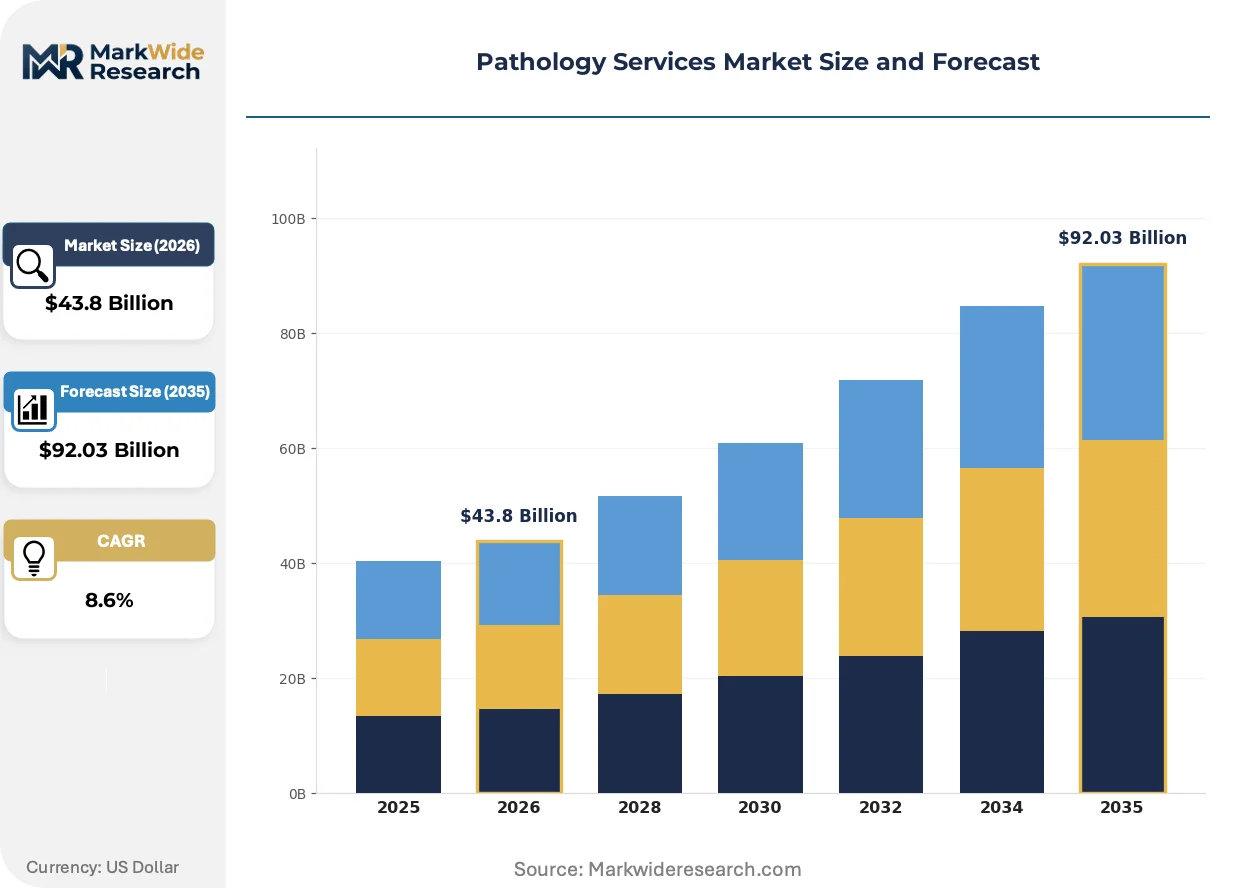
| Market Size in 2026 | $43.8 Billion |
| Market Size in 2035 | $92.03 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Anatomic Pathology, Clinical Pathology, Forensic Pathology, Molecular Pathology End User: Hospitals, Diagnostic Laboratories, Research Institutions, Outpatient Clinics Technology: Immunohistochemistry, Digital Pathology, Flow Cytometry, Next-Generation Sequencing Application: Cancer Diagnosis, Infectious Disease Testing, Genetic Testing, Blood Banking |
| Companies Covered | Eurofins Scientific, Mayo Clinic Laboratories, Labcorp, PathGroup, ARUP Laboratories, Quest Diagnostics, BioReference Laboratories, Dr. Lal PathLabs, Sonic Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pathology Services Market Evolving Landscape
Computational pathology is restructuring diagnostic economics by shifting value capture from manual slide interpretation to algorithm-augmented workflow automation and predictive biomarker quantification.
Multiplex immunofluorescence panels are displacing sequential single-marker immunohistochemistry in immuno-oncology diagnostics, enabling simultaneous quantification of PD-L1, tumor-infiltrating lymphocytes, and stromal markers from single tissue sections. Academic medical centers in Boston and San Francisco have adopted these platforms for clinical trials, compressing biomarker turnaround from weeks to days while reducing tissue consumption for precious biopsy specimens.
The FDA's evolving oversight framework for laboratory-developed tests is forcing diagnostic developers toward premarket submission pathways previously reserved for commercial IVD manufacturers. High-complexity molecular pathology laboratories now face validation documentation requirements that extend launch timelines by 12-18 months, particularly affecting oncology panels with novel biomarker claims.
Hospital procurement committees are consolidating pathology contracts under enterprise laboratory agreements rather than maintaining departmental purchasing autonomy. Health systems in Texas and Florida now mandate centralized bidding for anatomic pathology services, displacing long-standing relationships between individual pathologists and clinical departments while favoring national reference laboratories with standardized pricing and quality metrics.
Pathology Services Market Segmentation
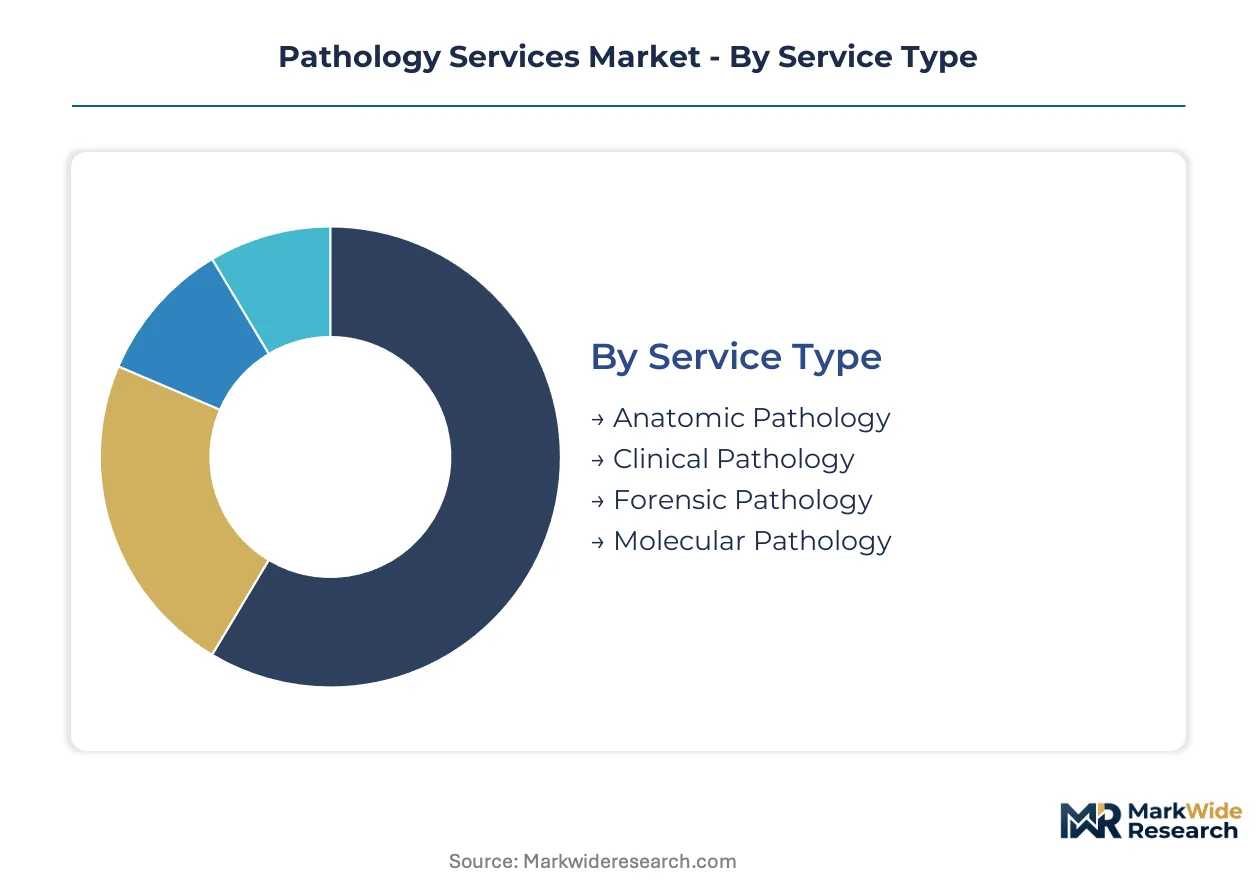
Segmentation in pathology services reveals how diagnostic workflows fragment across technical capabilities, institutional purchasing power, and regulatory compliance tiers. Service providers configure their offerings around whether clients demand high-volume screening, complex subspecialty interpretation, or research-grade biomarker validation.
Service Type:
Anatomic pathology and clinical pathology flow through distinct commercial channels, with hospital laboratories capturing routine clinical work while reference laboratories dominate complex case outsourcing and forensic contracts.
- Anatomic Pathology:Tissue-based diagnosis through histology, cytology, and immunohistochemistry constitutes the procedural backbone of surgical pathology. Demand concentrates in integrated health networks across Texas and Florida, where hospital procurement committees now mandate centralized bidding that favors multi-state reference laboratories with standardized quality metrics.
- Molecular Pathology:Nucleic acid-based testing for somatic mutations, fusion transcripts, and microsatellite instability guides precision oncology treatment selection. Academic medical centers in Boston and San Francisco drive adoption of multiplex panels, compressing biomarker turnaround from weeks to days while reducing tissue consumption for precious biopsy specimens.
- Clinical Pathology:Automated analysis of blood chemistry, hematology, and coagulation parameters supports routine disease monitoring and medication management.
- Forensic Pathology:Medicolegal autopsy services and toxicology screening serve coroner offices, law enforcement agencies, and insurance investigators.
Anatomic pathology dominates installed base. Molecular pathology is where expansion concentrates.
End User:
Customer type determines contract structure, with hospitals demanding capitated pricing for high-volume routine testing while research institutions negotiate project-based fees for protocol development.
- Diagnostic Laboratories:Independent reference labs and hospital-affiliated laboratories process specimens from multiple collection sites, requiring CLIA certification across multiple complexity levels. Sonic Healthcare leverages its integrated model combining anatomic pathology with outpatient clinic partnerships in Australia and Europe.
- Hospitals:Inpatient and surgical pathology services demand rapid turnaround for intraoperative consultation and post-surgical staging. Medicare reimbursement policies direct capital allocation toward molecular and anatomic pathology capabilities in US health systems.
- Research Institutions:Academic medical centers require assay development support, biomarker validation, and clinical trial specimen processing.
- Outpatient Clinics:Physician office laboratories perform limited waived testing, referring complex cases to reference laboratories.
Hospitals anchor volume throughput. Diagnostic laboratories are climbing the fastest.
Technology:
Platform selection drives capital allocation cycles, with digital infrastructure requiring seven-figure investments while conventional methods sustain margin in low-complexity testing.
- Digital Pathology:Whole-slide imaging and artificial intelligence-assisted analysis enable remote diagnosis and algorithm-augmented workflow automation. FDA-cleared algorithms for prostate cancer and lymphoma detection accelerate diagnostic throughput in high-volume anatomic pathology laboratories.
- Next-Generation Sequencing:Massively parallel sequencing of tumor and germline DNA supports comprehensive genomic profiling for therapy selection. CMS coverage decisions for molecular diagnostic panels redirect hospital capital toward NGS capabilities in oncology workflows.
- Immunohistochemistry:Antibody-based protein detection on tissue sections remains the standard for diagnostic classification and predictive biomarker assessment.
- Flow Cytometry:Laser-based cellular analysis enables rapid immunophenotyping for hematologic malignancy diagnosis and minimal residual disease monitoring.
Immunohistochemistry sustains broadest deployment. Digital pathology shows steepest expansion trajectory.
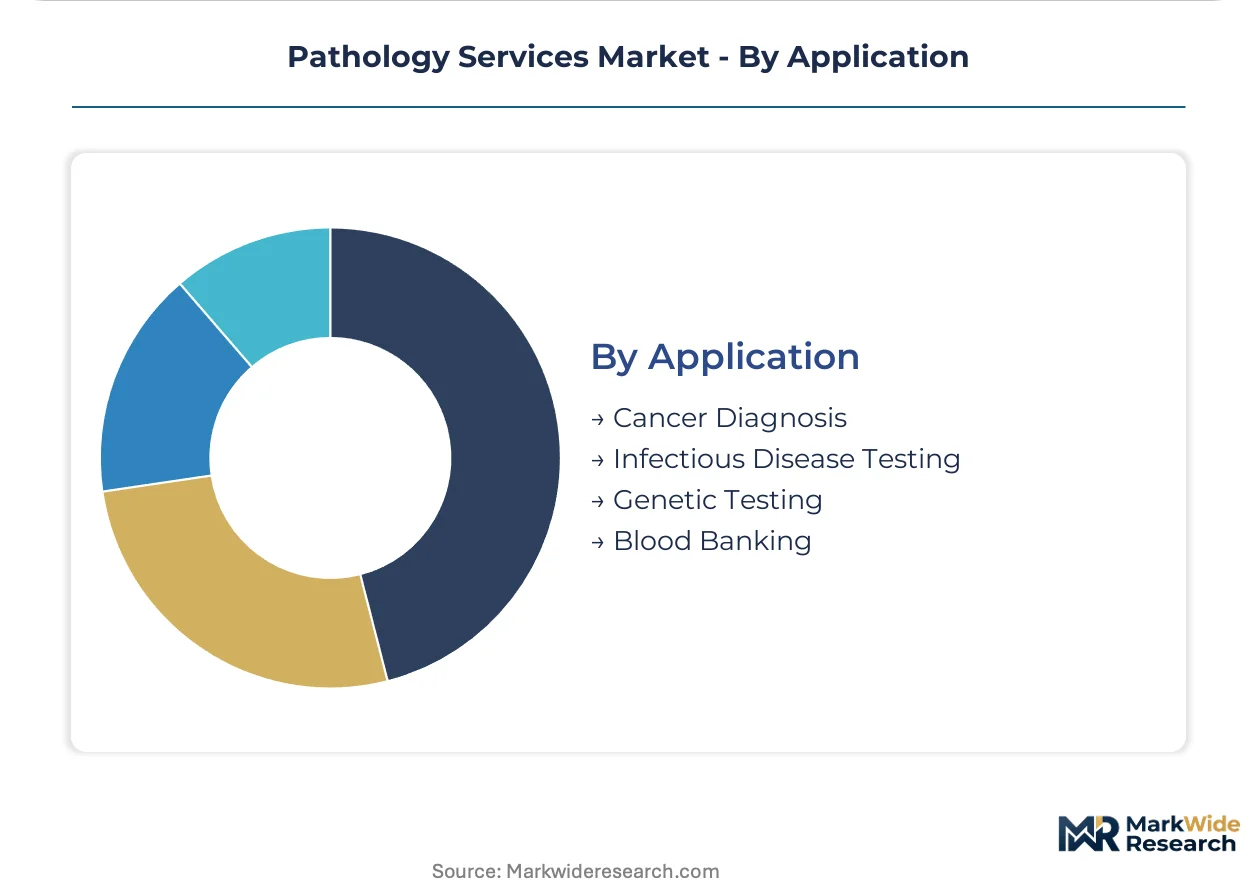
Application:
Disease area focus determines reimbursement coding, pathologist subspecialty requirements, and pharmaceutical co-development opportunities.
- Cancer Diagnosis:Histopathologic staging, biomarker profiling, and molecular subtyping guide surgical planning and systemic therapy selection. Oncology departments in hospital systems are expanding outsourced diagnostic volumes as digital pathology platforms gain traction.
- Infectious Disease Testing:Microbiologic culture, molecular detection, and antimicrobial susceptibility testing support sepsis management and outbreak investigation.
- Genetic Testing:Constitutional variant analysis for hereditary cancer syndromes, pharmacogenomics, and carrier screening serves preventive medicine programs.
- Blood Banking:Immunohematology testing, crossmatching, and transfusion reaction investigation support surgical and oncology transfusion services.
Cancer diagnosis commands premium pricing. Infectious disease testing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement expansion for molecular diagnostic panels redirects hospital capital toward next-generation sequencing capabilities in the United States. Health systems in Germany and Australia accelerate digital pathology adoption under national digital health frameworks. Academic medical centers in India and Brazil scale outsourced reference laboratory partnerships to address pathologist workforce gaps.
United States
Hospital procurement committees in Texas and Florida now mandate centralized bidding for anatomic pathology services, displacing long-standing relationships between individual pathologists and clinical departments. FDA oversight of laboratory-developed tests shapes service expansion timelines for US operators, freezing assay development budgets at academic medical centers. The Greater Boston and San Francisco Bay Area clusters drive adoption of multiplex immunofluorescence panels for clinical trials, compressing biomarker turnaround from weeks to days.
Germany
Integrated health networks leverage the EU In Vitro Diagnostic Regulation implementation to consolidate molecular pathology contracts under enterprise laboratory agreements. The country's national pharmaceutical regulator enforces 2027 conformity assessment deadlines for molecular assays, opening consulting and validation service contracts for US-based reference laboratories. The Baden-Württemberg industrial corridor anchors precision medicine initiatives combining academic pathology with pharmaceutical biomarker co-development.
Australia
Outpatient clinic partnerships with diagnostic laboratories expand across Sydney and Melbourne as Sonic Healthcare deploys its integrated model combining anatomic pathology with primary care networks. The Therapeutic Goods Administration oversees IVD conformity assessments that align with EU MDR timelines, creating regulatory harmonization opportunities for multinational operators. Rural telepathology platforms enable board-certified subspecialists to cover low-volume markets across Queensland and Western Australia without physical relocation.
India
Dr. Lal PathLabs and domestic reference laboratories capture volume from health system consolidation as hospital outsourcing accelerates in Delhi-NCR and Maharashtra. The Central Drugs Standard Control Organization regulates laboratory-developed tests with evolving oversight frameworks that extend validation documentation requirements. The Bangalore and Hyderabad clusters concentrate molecular pathology capabilities serving pharmaceutical clinical trials and precision oncology programs.
Brazil
Diagnostic laboratories represent the fastest-growing end-user channel as hospital outsourcing accelerates in São Paulo and Rio de Janeiro metropolitan regions. The national health surveillance agency enforces IVD registration requirements that filter smaller independent laboratories unable to sustain quality management infrastructure. Academic medical centers in São Paulo state scale companion diagnostic partnerships with pharmaceutical manufacturers during Phase II oncology trials.
Pathology Services Market Competitive Landscape
Player mix skews toward national reference laboratories with multi-state CLIA licenses and subspecialty pathologist coverage. Consolidation pressure intensifies as merged health networks centralize laboratory procurement, favoring operators with standardized pricing and quality metrics. Three archetypes dominate: integrated health system laboratories, independent reference laboratories with national networks, and academic medical center spin-outs with subspecialty expertise. M&A activity concentrates on digital pathology platform acquisitions and regional laboratory roll-ups in underserved states.
Within the integrated reference laboratory tier, Quest Diagnostics and Sonic Healthcare exemplify scale-driven operators with multi-continental footprints. Quest Diagnostics leverages its national laboratory network to anchor high-volume clinical pathology operations, while Sonic Healthcare competes through integrated models combining anatomic pathology with outpatient clinic partnerships. Mayo Clinic Laboratories occupies a distinct position as an academic spin-out drawing complex case referrals from medical centers worldwide. Eurofins Scientific and Labcorp sit within the diversified testing conglomerate archetype, cross-leveraging pathology capabilities with broader clinical and environmental testing portfolios.
| Leading Market Players |
|---|
| Eurofins Scientific |
| Mayo Clinic Laboratories |
| Labcorp |
| PathGroup |
| ARUP Laboratories |
| Quest Diagnostics |
| BioReference Laboratories |
| Dr. Lal PathLabs |
| Sonic Healthcare |
| Others |
Value Network & Pricing Analysis
High-volume reference laboratories achieve 40-50% cost advantages on per-specimen processing through automated histology lines and consolidated procurement, compressing price floors for mid-tier independent operators while concentrating supply relationships with dominant scanner manufacturers in Germany and Japan. This scale dynamic forces smaller laboratories toward niche subspecialty positioning or outright exit as CLIA compliance costs escalate.
Pricing Analysis
Certification level creates the primary spread between premium CAP-accredited academic centers and economy-tier independent laboratories, with three-tier pricing structure across premium, standard, and economy levels reflecting quality validation depth and subspecialty pathologist coverage. Price differentiation hinges on turnaround time guarantees and digital pathology enablement, with hospital procurement committees in consolidated Texas and Florida health systems driving aggressive contract compression through centralized bidding. Margins are tightening due to Medicare reimbursement stagnation for conventional anatomic pathology services, while molecular oncology panels retain pricing power. Community hospital systems exhibit highest price sensitivity, whereas academic medical centers prioritize biomarker validation capability over unit cost.
Supply Chain Analysis
Port congestion on trans-Pacific routes from Yokohama and Hamburg delays whole-slide scanner deliveries by 6-10 weeks, inflating equipment installation timelines for US laboratories expanding digital pathology capacity. Manufacturing concentrates in Germany, Japan, and the United States, with Leica Biosystems, Philips, and Hamamatsu anchoring scanner production. Supply draws from precision optical components, high-resolution camera sensors, and specialized staining reagents sourced from Switzerland and the Netherlands. Single-source vulnerability persists for proprietary image file formats that block interoperability between health systems. Distribution runs through manufacturer-direct sales teams for enterprise health systems and regional distributors serving independent laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward consolidated hospital procurement committees, with merged health networks in Texas and Florida now mandating centralized laboratory bidding that displaces fragmented departmental purchasing.
For Market Incumbents: Compound CLIA certification advantages by acquiring distressed independent laboratories in Montana, Wyoming, and North Dakota to capture telepathology referral flows before regional competitors consolidate. Deepen backward integration into AI algorithm development through partnerships with FDA-cleared diagnostic software developers, defending against margin erosion from automated image analysis. Prioritize companion diagnostic co-development contracts with pharmaceutical manufacturers during Phase II oncology trials to create sticky revenue relationships resistant to price compression. For New Entrants and Emerging Players: Differentiate on rapid biomarker turnaround for immuno-oncology clinical trials, targeting academic medical centers in Boston and San Francisco that demand multiplex immunofluorescence panels with sub-week delivery. Penetrate EU In Vitro Diagnostic Regulation consulting services for European laboratories facing 2027 conformity assessment deadlines, leveraging prior FDA premarket submission experience. Deploy cloud-native laboratory information systems that circumvent proprietary scanner format lock-in through middleware-agnostic architectures. For Investors and Strategic Acquirers: Regional laboratory roll-ups in underserved Mountain and Plains states present acquisition targets with embedded telepathology infrastructure and established CLIA licenses. Digital pathology platform developers with FDA-cleared algorithms for prostate cancer and lymphoma detection offer defensive technology positions as AI-assisted diagnosis becomes table stakes. Watch Medicare coverage determinations for novel molecular diagnostic panels as the inflection signal for hospital capital reallocation toward next-generation sequencing capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Multi-State License Expansion | Enables reference laboratories to capture consolidated hospital procurement contracts across merged health networks in Texas and Florida. |
| FDA Premarket Submission Pathway Investment | Positions molecular pathology laboratories for laboratory-developed test oversight requirements extending validation timelines. |
| Companion Diagnostic Co-Development Partnership | Creates sticky revenue relationships with pharmaceutical manufacturers during Phase II oncology biomarker validation. |
| Telepathology Platform Deployment | Extends subspecialty pathologist coverage to low-volume rural markets across Montana, Wyoming, and North Dakota. |
| EU IVD Regulation Consulting Service Launch | Captures validation and conformity assessment contracts from European laboratories facing 2027 deadlines. |
Research Methodology
Initial hypotheses were tested against primary input from pathology laboratory directors, hospital procurement executives, CLIA compliance officers, and pharmaceutical biomarker development leads and refined through secondary validation against FDA 510(k) filings, CMS Medicare coverage determinations, CAP laboratory accreditation records, and EU MDR implementation guidance documents. Bottom-up triangulation across service type, end user, technology platform, and application segmentation dimensions anchored volume estimates, while top-down cross-checks against national health expenditure data ensured consistency.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with analytical frameworks modeling service type splits between anatomic, molecular, clinical, and forensic pathology alongside technology adoption curves for digital pathology and next-generation sequencing. CAGRs derive from segmented growth rate blending weighted by base-year revenue contribution, incorporating pathologist workforce constraint elasticities and Medicare reimbursement policy scenario inputs specific to molecular diagnostic panel coverage expansion.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement support for advanced diagnostics, CLIA regulatory stability, and pharmaceutical clinical trial volume growth would require recalibration. Forecasts reflect documented assumptions regarding digital pathology adoption timelines and AI algorithm regulatory clearance trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Myoglobin Reagents Market
Laboratory Services
UAE Clinical Laboratory Services Market
Laboratory Services
Autosampler Vials Market
Laboratory Services
Assessment Services Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Histopathology Services Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Sera and Reagents Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market