
 Global Lab Consumables Market | 2026-2036
Global Lab Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lab Consumables Market Outlook
Multi-source procurement for sterile plasticware is decoupling from long-term sole-supplier contracts in large pharmaceutical QC labs. Thermo Fisher Scientific leverages its vertically integrated resin-to-finished-goods network to secure supply continuity for high-volume clients. Danaher Corporation anchors its position through intensive R&D spending on automation-compatible consumables formats. Greiner Bio-One International GmbH specializes in thin-wall polymer engineering for cell culture applications, differentiating on lot-to-lot consistency rather than price.
Lab consumables comprise single-use and limited-reuse articles—pipette tips, microplates, centrifuge tubes, gloves, and cell culture vessels—typically molded from medical-grade polypropylene, polystyrene, or nitrile elastomers to meet sterility and chemical resistance specifications. These items function as the sterile interface between analytical instruments, biological samples, and human operators across research, clinical, and industrial testing workflows. The plastics segment dominates absolute volume due to disposability economics, yet glass pipettes and metal accessories retain durable positions in high-precision analytical chemistry where thermal stability and solvent compatibility matter. Among end users, pharmaceutical and biotech operations command the deepest consumables budgets per seat, while academic institutions represent the broadest installed base with higher price sensitivity and fragmented purchasing authority.
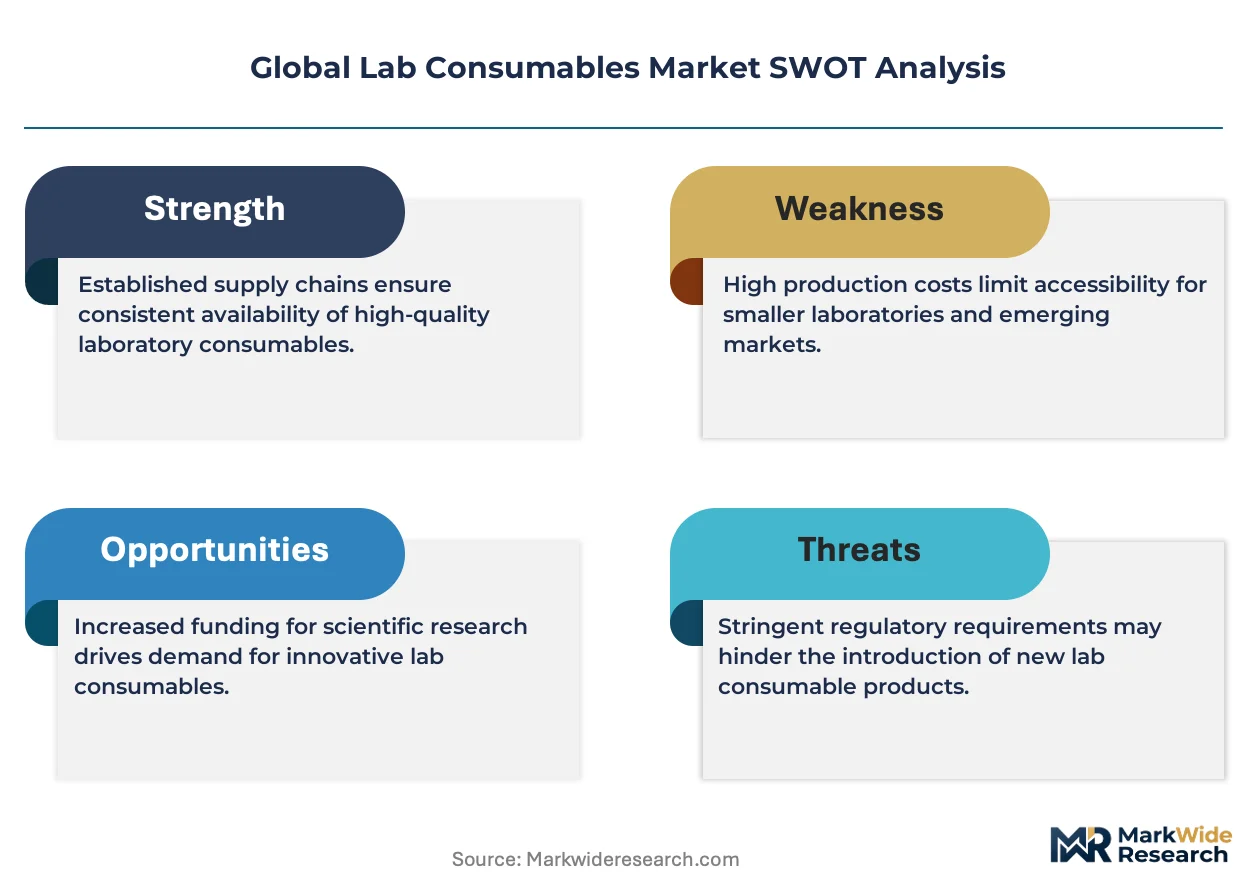
US FDA cGMP rules and EU MDR frameworks enforce stringent extractables-and-leachables testing for consumables contacting drug substances or diagnostic specimens, effectively raising barriers for uncertified suppliers. ISO 9001 and ISO 13485 certifications have become baseline qualifications for vendor qualification programs at tier-one buyers, compressing margins for manufacturers lacking accredited quality systems. Stakeholders must monitor evolving ECHA REACH restrictions on phthalate plasticizers and perfluorinated compounds, as material reformulation timelines could disrupt established supply agreements without advance chemical inventory planning.
Market Dynamics
Single-use sterile plasticware is absorbing procurement authority from capital equipment budgets, forcing manufacturers to certify consumables as drug-contact materials under tightening extractables-and-leachables protocols.
Growth Catalysts
- Biologics manufacturing expansion:Cell therapy facilities in Germany and Switzerland are scaling single-use bioreactor systems, creating pull-through demand for matched sterile tubing and bag assemblies.
- ISO 13485 certification mandates:Tier-one pharmaceutical QC labs now require accredited quality systems for vendor qualification, compressing the supplier base toward certified molders.
- Automation-compatible formats:High-throughput screening operations are standardizing ANSI/SLAS microplate footprints, rewarding consumables engineered for robotic gripper compatibility.
Market Restraints
- Medical-grade polypropylene supply concentration:LyondellBasell and Borealis control over 60% of European resin supply for clarified random copolymers, creating price volatility exposure.
- ECHA REACH substance restrictions:Pending limitations on perfluorinated compounds threaten non-stick surface treatments for cell culture vessels, requiring material reformulation timelines.
- Glass retention in analytical chemistry:Thermal stability requirements for aggressive solvent handling preserve glass pipette demand, capping polymer substitution in precision segments.
Strategic Opportunities
- India biopharma manufacturing:CDSCO-aligned facilities are adopting single-use systems faster than domestic resin supply can match, creating import substitution openings for certified exporters.
- EU MDR diagnostic specimen handling:In-vitro device reclassification is forcing diagnostic labs to upgrade consumables traceability, expanding the certified supplier addressable market.
- Closed-system aseptic processing:Convergence of isolator technology with pre-sterilized single-use assemblies is enabling modular cleanroom-free manufacturing in secondary geographies.
Industry Challenges
- Extractables validation timelines:US FDA cGMP drug master file submissions for novel polymer grades require 18-24 month qualification cycles, delaying product commercialization.
- Automation integration complexity:Legacy liquid handling platforms from Tecan and Hamilton operate on proprietary consumables geometries, locking buyers into format-specific supply agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lab Consumables Market |
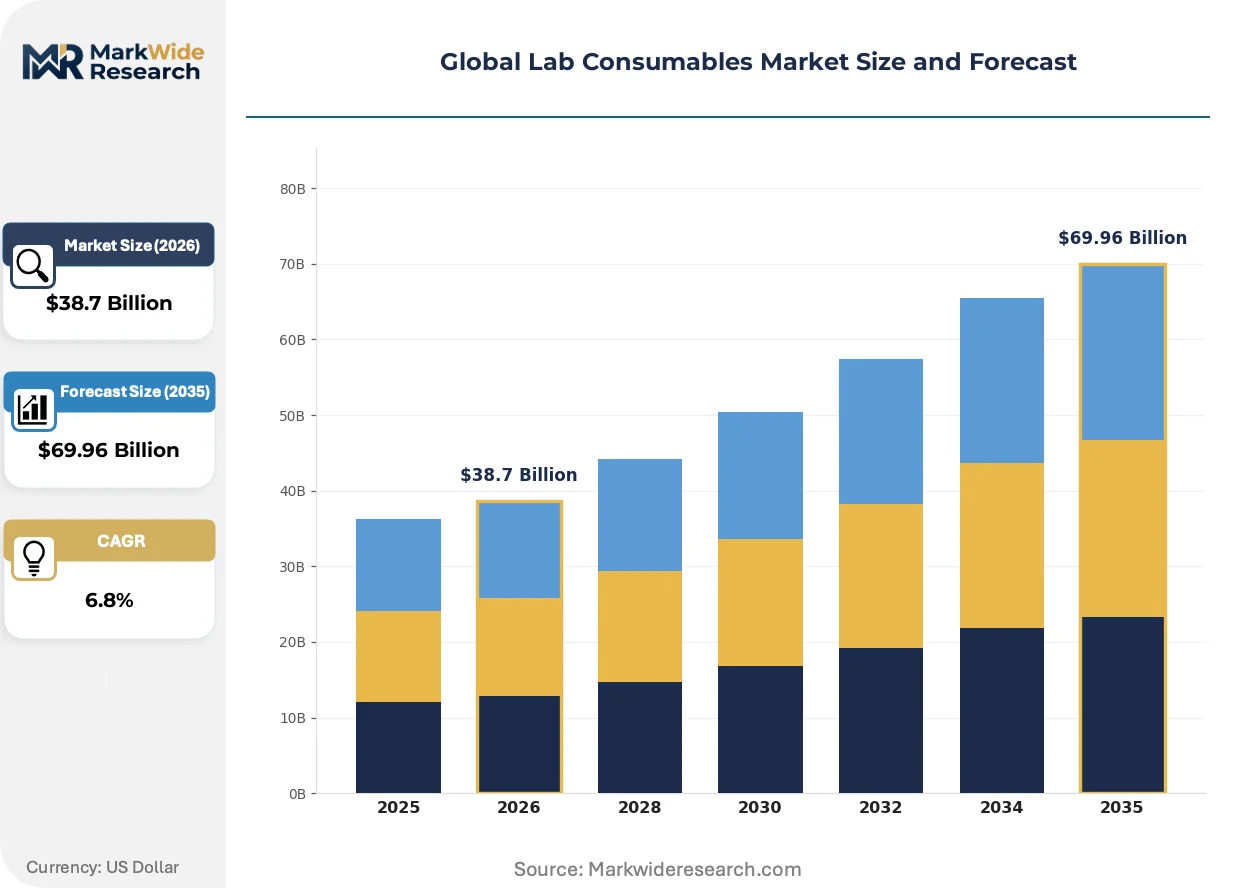
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Pipettes, Plates, Tubes Material: Plastic, Glass, Metal, Rubber Application: Clinical, Research, Quality Control, Diagnostics End User: Pharmaceuticals, Biotech, Academic Institutions, Hospitals |
| Companies Covered | Thermo Fisher Scientific, Inc., Merck KGaA, Danaher Corporation, Corning Incorporated, Greiner Bio-One International GmbH, Eppendorf SE, Bio-Rad Laboratories, Inc., Agilent Technologies, Inc., Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lab Consumables Market Strategic Shifts
Bioabsorbable polymers and closed-system processing architectures are redrawing the boundary between consumables and process equipment, collapsing traditional category distinctions.
Plant-derived polylactic acid blends are absorbing interest from cell culture vessel manufacturers seeking to reduce petroleum dependency. European biotech contract manufacturers are piloting these materials in non-critical fluid handling steps. The structural consequence is that resin suppliers with fermentation-derived feedstocks are capturing specification authority previously held by petrochemical polymer houses.
ECHA REACH Annex XVII restrictions on phthalate plasticizers are compelling reformulation of flexible tubing and gasket materials used in peristaltic pump applications. Compounders serving diagnostic instrument OEMs are accelerating bio-based plasticizer validation to maintain EU market access. Diagnostic reagent kit manufacturers face the steepest compliance timelines, as their consumables contact analytes subject to leachable interference testing.
Consolidated procurement consortia at multi-site pharmaceutical operators are compressing vendor panels to three approved suppliers per consumables category. Group purchasing organizations are displacing site-level purchasing autonomy with centralized tender processes that prioritize supply continuity metrics over unit price. This concentration is most visible in Germany's dense pharmaceutical manufacturing corridor, where Merck KGaA and Boehringer Ingelheim have harmonized sterile plasticware specifications across their respective networks.
Global Lab Consumables Market Segmentation
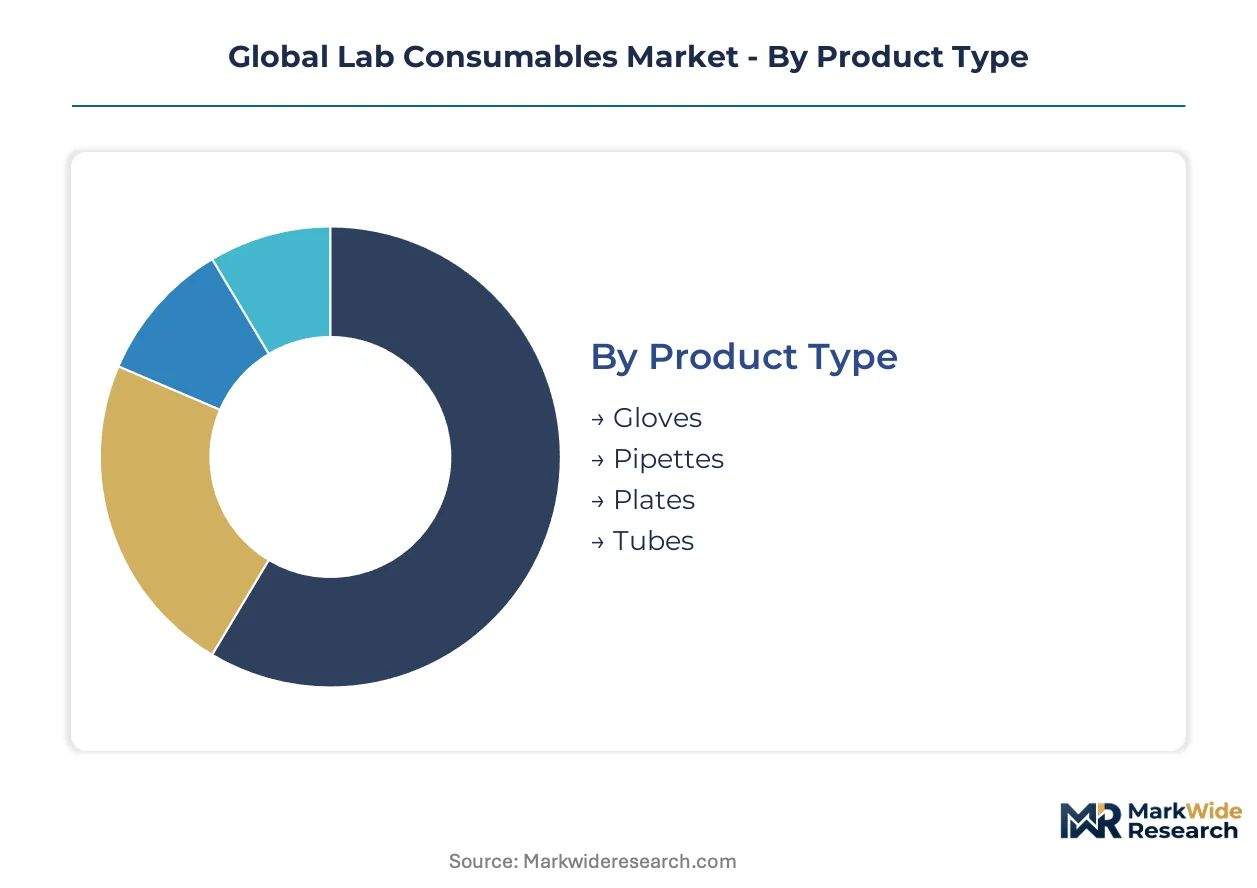
Consumables segmentation reveals how material specifications, sterility grades, and automation compatibility reshape procurement patterns across divergent end-use workflows. Product format and polymer composition together determine vendor qualification status and pricing tier placement.
Product Type:
Technical specifications for liquid handling precision and barrier protection define competitive positioning across disposable formats.
- Gloves:Nitrile elastomer formulations dominate pharmaceutical aseptic suites due to chemical permeation resistance and tactile sensitivity requirements. Demand concentrates in German biologics manufacturing where Merck KGaA and Boehringer Ingelheim enforce ISO 13485-certified glove supply for all drug-contact operations.
- Pipettes:Single-channel and multichannel air-displacement systems require certified accuracy tolerances for GLP compliance. Academic institutions in the United States represent the broadest installed base, though price sensitivity drives private-label procurement over branded instruments.
- Plates:ANSI/SLAS standard microplates enable robotic gripper compatibility across high-throughput screening platforms.
- Tubes:Centrifuge and cryogenic vial formats prioritize seal integrity and thermal cycling durability for biobanking applications.
Gloves lead on scale; plates lead on momentum.
Material:
Cost tiers separate certified medical-grade polymers from commodity alternatives in regulated applications.
- Plastic:Medical-grade polypropylene and polystyrene dominate sterile disposables through disposability economics and moldability for complex geometries. Pharmaceutical QC labs in Switzerland and Germany absorb premium pricing for clarified random copolymers with documented extractables profiles.
- Glass:Borosilicate formulations retain analytical chemistry positions where thermal stability and solvent compatibility outweigh breakage risks. High-precision titration workflows in Japanese pharmaceutical R&D facilities preserve glass pipette demand despite polymer substitution pressure.
- Metal:Stainless steel accessories serve reusable instrument frames and heating blocks.
- Rubber:Elastomer gaskets and septa provide seal elasticity for cryogenic and vacuum applications.
Plastic commands absolute volume; glass defends premium analytical niches.
Application:
Volume concentration and margin structure diverge sharply between regulated manufacturing and exploratory research environments.
- Clinical:Diagnostic specimen handling requires consumables traceability under EU MDR and US FDA oversight. CDSCO-aligned facilities in India are upgrading consumables specifications faster than domestic supply can match, creating import substitution openings.
- Research:Academic laboratories prioritize unit cost over certification depth, fragmenting purchasing authority across principal investigators. Fragmented procurement in United States research universities limits vendor consolidation compared to pharmaceutical networks.
- Quality Control:Pharmaceutical release testing mandates ISO 13485-certified consumables with validated extractables data.
- Diagnostics:Reagent kit manufacturing demands leachable-tested materials to prevent assay interference.
Clinical leads on regulatory rigor; research leads on addressable site count.
End User:
Customer type determines procurement centralization, technical specification depth, and supplier relationship duration.
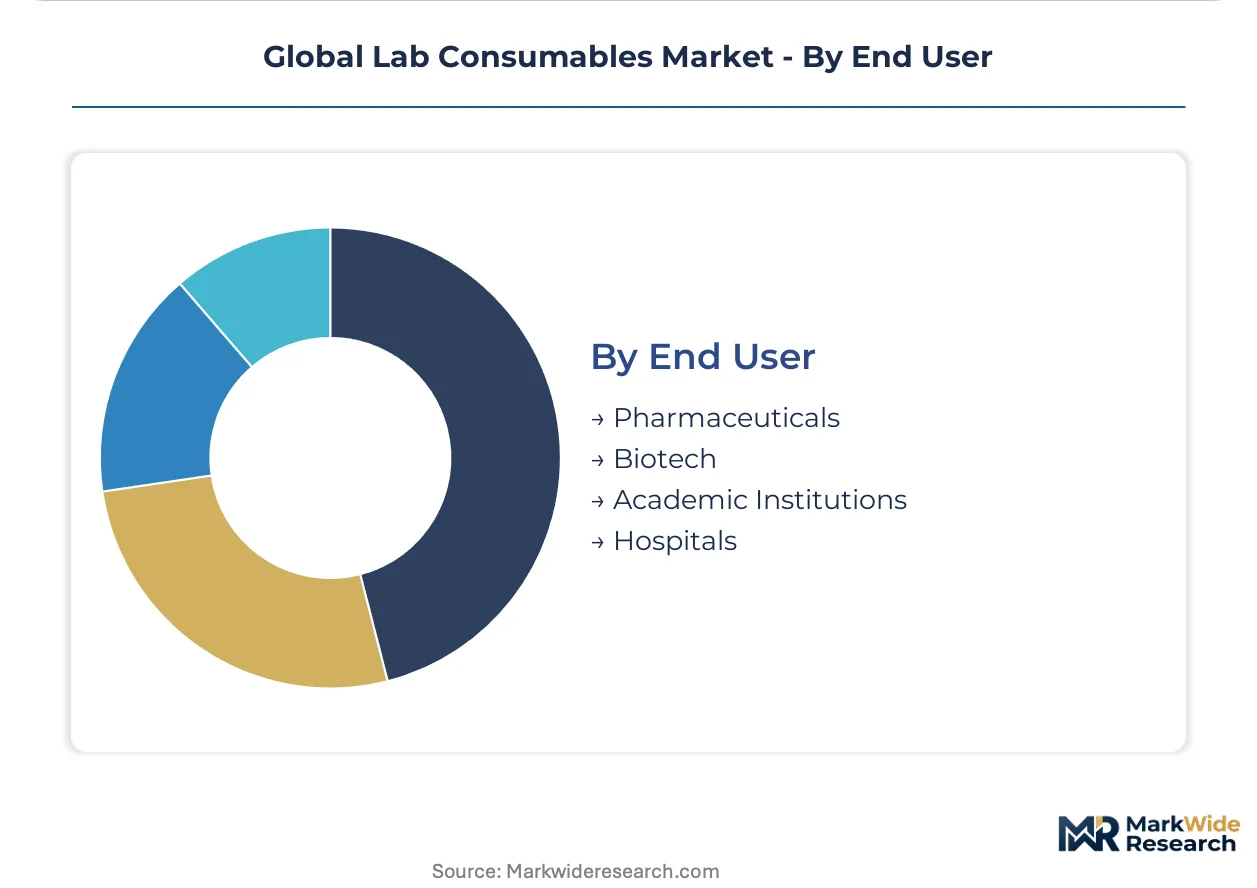
- Pharmaceuticals:Consolidated procurement consortia at multi-site operators compress vendor panels to three approved suppliers per category. Group purchasing organizations in Germany's pharmaceutical corridor have harmonized sterile plasticware specifications across manufacturing networks.
- Biotech:Cell therapy facilities scale single-use bioreactor systems, creating pull-through demand for matched sterile tubing and bag assemblies. Swiss contract manufacturers pilot plant-derived polylactic acid blends in non-critical fluid handling steps.
- Academic Institutions:Distributed purchasing authority and grant-funded budgets sustain higher price sensitivity than industrial buyers.
- Hospitals:Clinical laboratories face diagnostic reclassification pressures under EU MDR frameworks.
Pharmaceuticals lead on spend per seat; biotech leads on specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting sterile plasticware production toward jurisdictions where ISO 13485 compliance costs diverge from end-market pricing power. Manufacturers in lower-cost certification environments export into German and Swiss pharmaceutical networks, while domestic molders in high-wage economies defend position through automation and extractables-documentation depth.
Germany
Merck KGaA and Boehringer Ingelheim anchor demand for single-use bioreactor assemblies in the Rhine-Main and Upper Bavaria clusters. ECHA REACH Annex XVII restrictions on perfluorinated compounds are accelerating material reformulation timelines for cell culture vessel suppliers. The Tübingen-Reutlingen precision molding corridor concentrates engineering expertise for automation-compatible microplate formats.
United States
FDA cGMP extractables-and-leachables protocols drive vendor consolidation among pharmaceutical QC labs in Greater Boston and the Research Triangle. Academic procurement fragmentation across NIH-funded institutions sustains price-competitive private-label channels. California's cell therapy manufacturing expansion in South San Francisco creates pull-through demand for closed-system aseptic processing consumables.
Switzerland
Swissmedic oversight of diagnostic specimen handling enforces traceability standards that compress approved vendor panels for Basel-area contract manufacturers. Lonza and other CDMOs pilot plant-derived polylactic acid blends in non-critical fluid handling steps. The Zürich-Schaffhausen polymer engineering cluster specializes in thin-wall molding for high-value cell culture applications.
India
CDSCO-aligned biopharma facilities in Hyderabad and Bengaluru adopt single-use systems faster than domestic resin supply can match, creating import substitution openings for certified exporters. The country's national pharmaceutical regulator is tightening material traceability requirements for plastic labware contacting drug substances. Maharashtra's Pune-Ahmednagar industrial belt hosts emerging molders seeking ISO 13485 accreditation for export qualification.
China
NMPA oversight of in-vitro diagnostic reagent kits is forcing consumables suppliers to upgrade extractables documentation for Shanghai and Suzhou diagnostic manufacturers. Yangtze River Delta biopharma clusters are scaling single-use bioreactor adoption, though medical-grade polypropylene supply remains import-dependent. The Beijing-Tianjin-Hebei corridor concentrates state-backed research procurement with fragmented purchasing authority across CAS institutes.
Global Lab Consumables Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in bioabsorbable polymers and closed-system processing architectures. The vendor base stratifies across three tiers: vertically integrated resin-to-finished-goods networks, specialized precision molders, and regional distributors with private-label assembly capacity. Two strategic archetypes dominate—automation-format specialists and extractables-documentation leaders. Competitive intensity centers on M&A for quality-system accreditation and strategic partnerships for resin supply security.
Among vertically integrated networks, Thermo Fisher Scientific, Inc. and Danaher Corporation exemplify the scale-driven archetype through captive control over polymer supply chains and finished-goods distribution. Greiner Bio-One International GmbH occupies a position within the precision-molding specialist tier, differentiated on thin-wall engineering and lot-to-lot consistency rather than price competition. These three entities represent contrasting strategic postures: backward integration for supply continuity, intensive R&D spending for automation compatibility, and polymer engineering specialization for cell culture applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Merck KGaA |
| Danaher Corporation |
| Corning Incorporated |
| Greiner Bio-One International GmbH |
| Eppendorf SE |
| Bio-Rad Laboratories, Inc. |
| Agilent Technologies, Inc. |
| Sartorius AG |
| Others |
Value Chain & Pricing Dynamics
Precision molding engineers in the Tübingen-Reutlingen corridor command wage premiums that widen spreads between certified premium tiers and economy-grade imports. Labor-cost differentials between German specialist molders and emerging ISO 13485-accredited facilities in Maharashtra's Pune-Ahmednagar belt stratify pricing across three distinct certification-grade tiers.
Pricing Analysis
Distributor markups of 15-25 percent separate direct-to-pharma contract pricing from catalog-channel transactions for identical ANSI/SLAS microplate formats. Three-tier pricing structure across premium, standard, and economy levels reflects extractables-documentation depth and automation-compatibility certification. Cost compression in economy-grade pipette tips is intensifying because Indian and Chinese molders are achieving ISO 13485 accreditation at lower compliance-cost bases. Academic institutions in the United States exhibit the highest price sensitivity, while Swiss and German biologics manufacturers absorb premiums for validated drug-contact materials.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and remanufacturing remain minimal in single-use sterile plasticware due to disposability economics, though glass pipette return programs persist in Japanese pharmaceutical R&D facilities. Medical-grade polypropylene supply concentrates in Germany, Belgium, and the United States, with LyondellBasell and Borealis controlling clarified random copolymer feedstocks. Raw material dependencies rest on petroleum-derived propylene monomers, phthalate-free plasticizers, and perfluorinated surface treatments now threatened by ECHA REACH restrictions. Single-source vulnerability in European resin supply creates price volatility exposure during force majeure events. Distribution runs through authorized distributor networks for regulated pharmaceutical buyers and direct OEM supply agreements for diagnostic instrument manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Lab Consumables Market functions as a stable compounder anchored by irreversible biologics manufacturing expansion and tightening extractables-and-leachables mandates that perpetually refresh certification requirements.
For Market Incumbents: Extend extractables-documentation depth to defend against emerging plant-derived polymer specialists capturing specification authority in cell culture applications. Deepen backward integration into medical-grade resin supply through strategic partnerships with fermentation-derived feedstock producers. Prioritize automation-format engineering investments that lock high-throughput screening platforms into proprietary consumables geometries resistant to price competition. For New Entrants and Emerging Players: Contract research organization procurement teams represent the most accessible channel partner type for bypassing consolidated vendor panels at tier-one pharmaceutical operators. Target CDSCO-aligned biopharma facilities in Hyderabad and Bengaluru where single-use system adoption outpaces domestic resin supply maturity. Pursue private-label assembly partnerships with Maharashtra molders seeking ISO 13485 accreditation for export qualification. For Investors and Strategic Acquirers: Precision molding specialists with validated extractables profiles and thin-wall engineering capabilities are the most active acquirer targets in this space for diagnostic instrument OEMs seeking consumables supply security. Long-term viability centers on regulatory-documentation depth rather than manufacturing scale alone. Monitor ECHA REACH substance restriction timelines as the critical inflection indicator for material reformulation capex cycles and incumbent vulnerability windows.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Accredited quality systems unlock vendor qualification at Merck KGaA and Boehringer Ingelheim procurement panels. |
| Backward Integration into Resin Supply | Captive polymer feedstocks insulate Thermo Fisher Scientific from LyondellBasell supply concentration risks. |
| Automation-Compatible Format Development | ANSI/SLAS microplate engineering secures robotic gripper compatibility across Tecan and Hamilton platforms. |
| Plant-Derived Polymer Pilot Programs | Polylactic acid validation at Swiss CDMOs captures specification authority from petrochemical polymer houses. |
| Closed-System Aseptic Processing Partnerships | Pre-sterilized single-use assemblies enable modular cleanroom-free manufacturing in secondary geographies. |
Study Parameters
Coverage spans Germany, the United States, Switzerland, India, and China, with primary inputs from each market cluster through structured interviews. Procurement directors at pharmaceutical QC labs, regulatory affairs leads at diagnostic instrument OEMs, polymer engineers at resin compounders, and GPO contracts managers at academic medical centers provided demand-side intelligence. Secondary validation drew from FDA cGMP guidance documents, ECHA REACH substance restriction filings, CDSCO manufacturing facility inspection reports, and SEC 10-K disclosures from vertically integrated consumables producers. Bottom-up unit economics and top-down market sizing underwent iterative triangulation.
Granularity-level modeling operated at product-format, material-grade, and end-user-type dimensions with geographic production-cluster overlays. Segment-level CAGRs derived from regression analysis against biologics manufacturing capacity expansion, ISO 13485 certification penetration curves, and automation adoption rates across high-throughput screening operations. Industry-specific forecast inputs incorporated extractables-validation timeline data and ECHA REACH substance restriction implementation schedules.
Revisions become necessary when ECHA REACH substance restrictions accelerate material reformulation timelines or when medical-grade polypropylene supply disruptions exceed 90-day continuity thresholds. Forecasts reflect documented assumptions regarding certification-cost trajectories and resin supply concentration stability. Practitioners should monitor CDSCO inspection regime tightening and NMPA extractables-documentation upgrades for early signals of regulatory-compression effects on vendor panel composition.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Assessment Services Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
Clinical Laboratory Services Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Pathology Services Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
LIMS Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
Autosampler Vials Market