
 Serum Separation Gel Market | 2026-2036
Serum Separation Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Serum Separation Gel Market Analytics
The serum separation gel market is restructuring around a widening gap between premium polymer formulations and commodity silica alternatives. Greiner Bio-One International GmbH leverages its European manufacturing footprint to dominate high-specification hydrogel supply for automated analyzers. Becton Dickinson & Company sustains channel control through direct hospital contracts in North America. Sekisui Diagnostics, LLC specializes in latex-based chemistries that serve niche research applications where lot-to-lot consistency commands price premiums.
Serum separation gel comprises a thixotropic barrier material—typically silica particles suspended in polyester or acrylic resin with a specific gravity of 1.04–1.06 g/cm³—that forms a stable partition between serum and clot phases following centrifugation at 1,000–3,000 × g for 10 minutes. This separation enables clean serum extraction for downstream clinical chemistry, immunoassay, and molecular diagnostic testing without red cell contamination. Polymer gel variants now lead value generation due to their chemical inertness and compatibility with therapeutic drug monitoring, while silica gel retains volume dominance in price-sensitive blood bank and clinic segments. Diagnostic labs represent the fastest-growing end user channel as centralized laboratories automate pre-analytical processing at scale.
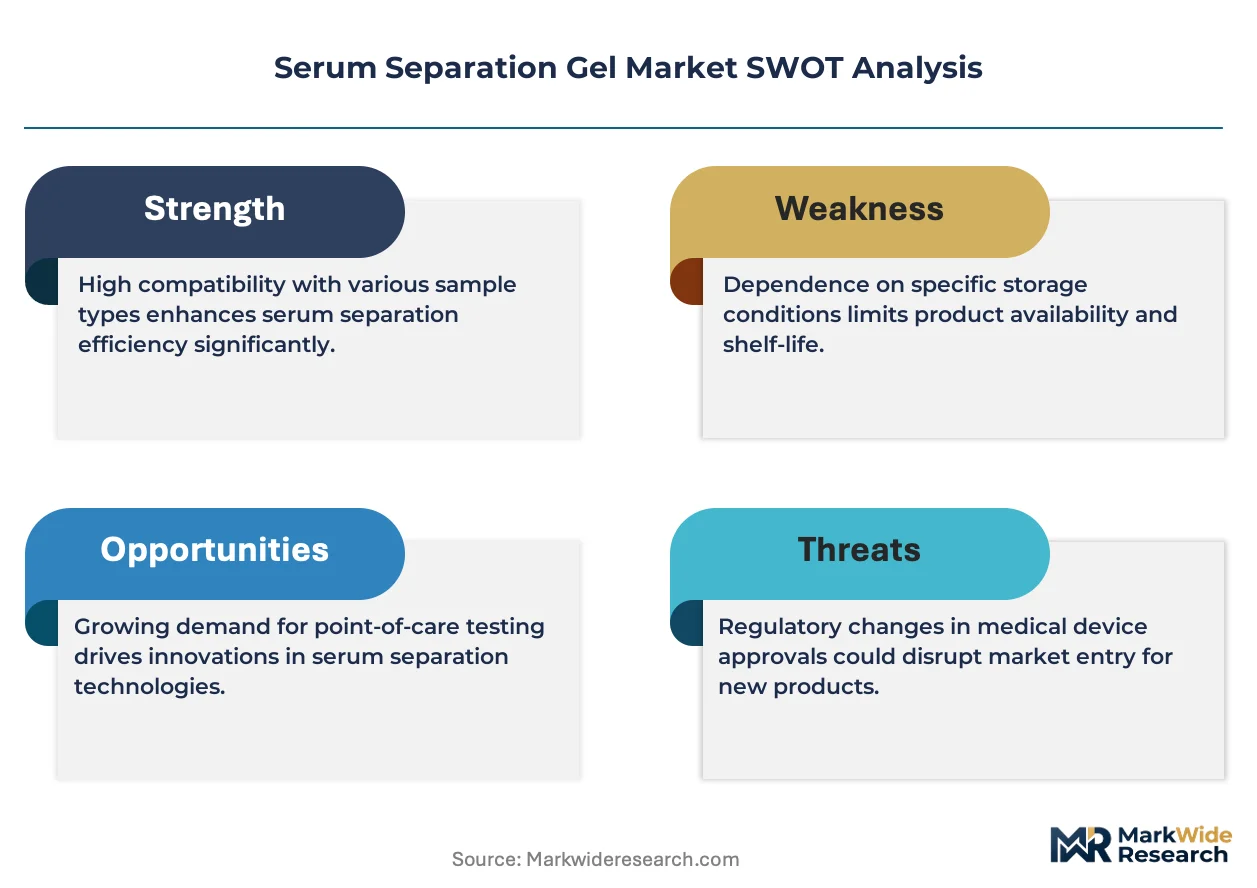
FDA quality system regulations and EMA in vitro diagnostic device standards enforce stringent biocompatibility and extractable testing protocols that elevate barriers for uncertified suppliers. ISO 13485 compliance has become a baseline requirement for contract eligibility with major health systems and group purchasing organizations. Stakeholders must monitor evolving EPA and REACH chemical substance restrictions on resin precursors, as these could force reformulation cycles and reshape supplier qualification timelines.
Market Dynamics
Automated pre-analytical workflows in diagnostic laboratories are compressing turnaround times and forcing gel suppliers to reformulate for compatibility with high-throughput centrifugation systems. This equipment-driven standardization is consolidating procurement around polymer formulations that withstand repeated freeze-thaw cycles without barrier degradation.
Growth Catalysts
- ISO 13485 certification mandates:Group purchasing organizations in the United States now require documented quality management systems for contract eligibility, filtering out uncertified resin compounders.
- Therapeutic drug monitoring expansion:Oncology and immunosuppression protocols demand chemically inert barriers that prevent drug adsorption, elevating polymer gel specifications in hospital networks.
- Central laboratory automation:Reference labs in Germany and Switzerland are retrofitting lines for 10-minute centrifugation cycles, creating pull for thixotropic formulations with rapid gelation kinetics.
Market Restraints
- Petrochemical resin volatility:Acrylic and polyester precursor costs fluctuate with crude oil derivatives, compressing margins for compounders without backward integration into monomer supply.
- Supplier concentration in Western Europe:Three specialized hydrogel manufacturers control high-purity polymer supply, creating single-source risk for North American diagnostic OEMs.
- Silica gel substitution in price-sensitive segments:Blood banks and rural clinics continue specifying lower-cost silica particulate barriers despite inferior chemical inertness.
Strategic Opportunities
- Point-of-care testing expansion:Brazil and Mexico are deploying decentralized clinical chemistry analyzers in regional hospitals, generating demand for pre-filled gel tubes that eliminate manual pipetting.
- EU MDR harmonization:The Medical Device Regulation's 2027 enforcement timeline creates a certification window for polymer formulations with documented biocompatibility profiles.
- Integration with closed-vacuum systems:Converging gel chemistry with evacuated tube manufacturing enables single-source supply contracts for integrated blood collection systems.
Industry Challenges
- Extractables testing capacity:FDA biocompatibility protocols require specialized chromatography facilities that few compounders maintain in-house, extending qualification timelines.
- Legacy analyzer compatibility:Hospital networks running 15-year-old centrifugation equipment cannot process next-generation low-density gels without rotor recalibration.
- Cross-functional formulation expertise:Few chemists combine polymer rheology knowledge with diagnostic regulatory filing experience, constraining R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serum Separation Gel Market |
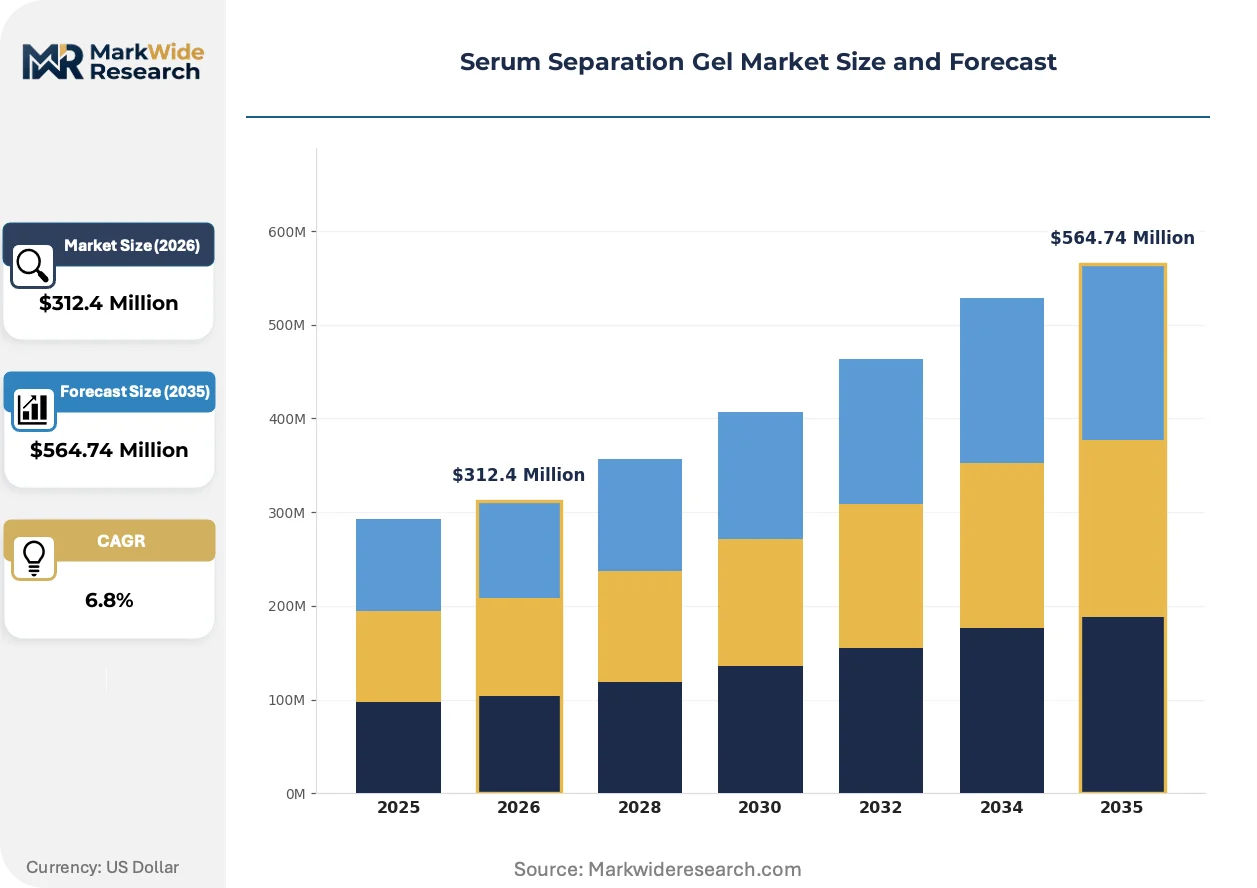
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica Gel, Polymer Gel, Latex Gel, Hydrogel End User: Clinics, Hospitals, Diagnostic Labs, Blood Banks Application: Blood Collection, Serum Analysis, Clinical Diagnostics, Research Distribution Channel: Direct Sales, Distributors, Online Retail, Medical Supply Stores |
| Companies Covered | Cardinal Health, Inc., Becton Dickinson & Company, Greiner Bio-One International GmbH, Sekisui Diagnostics, LLC, Thermo Fisher Scientific, Sarstedt AG & Co. KG, Terumo Corporation, Bio-Rad Laboratories, Qiagen N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serum Separation Gel Market Evolving Landscape
Reformulation around density-modified resins is enabling faster barrier formation without compromising chemical stability, while regulatory pressure on extractable compounds is accelerating substitution of legacy silica matrices. These parallel developments are compressing the technology lifecycle for incumbent suppliers.
Thixotropic polyester-acrylic copolymers with tuned specific gravity of 1.04–1.06 g/cm³ are decentralizing serum processing from centralized reference laboratories toward regional hospital labs. Mid-sized diagnostic centers in France and Japan are adopting these formulations to run chemistry panels on-site rather than outsourcing to national hubs. This geographic redistribution of testing capacity is fragmenting procurement patterns and creating demand for smaller batch sizes with documented lot-to-lot consistency.
REACH restrictions on residual monomer content in polymer resins are forcing compounders to shift from bulk synthesis to controlled radical polymerization methods. The ECHA regulatory pressure elevates capital requirements for European manufacturers while creating competitive openings for suppliers with advanced purification capabilities. Diagnostic OEMs sourcing from Asia-Pacific are now demanding equivalent extractables documentation to preempt future regulatory alignment.
Consolidated procurement through group purchasing organizations is compressing supplier margins and privileging multi-year framework agreements over spot purchasing. Hospital networks in the United States are bundling gel tube contracts with broader blood collection system agreements, displacing standalone gel suppliers. This channel concentration is most visible in integrated delivery networks across Texas and California, where procurement committees now prioritize total cost of ownership over unit pricing.
Serum Separation Gel Market Segmentation
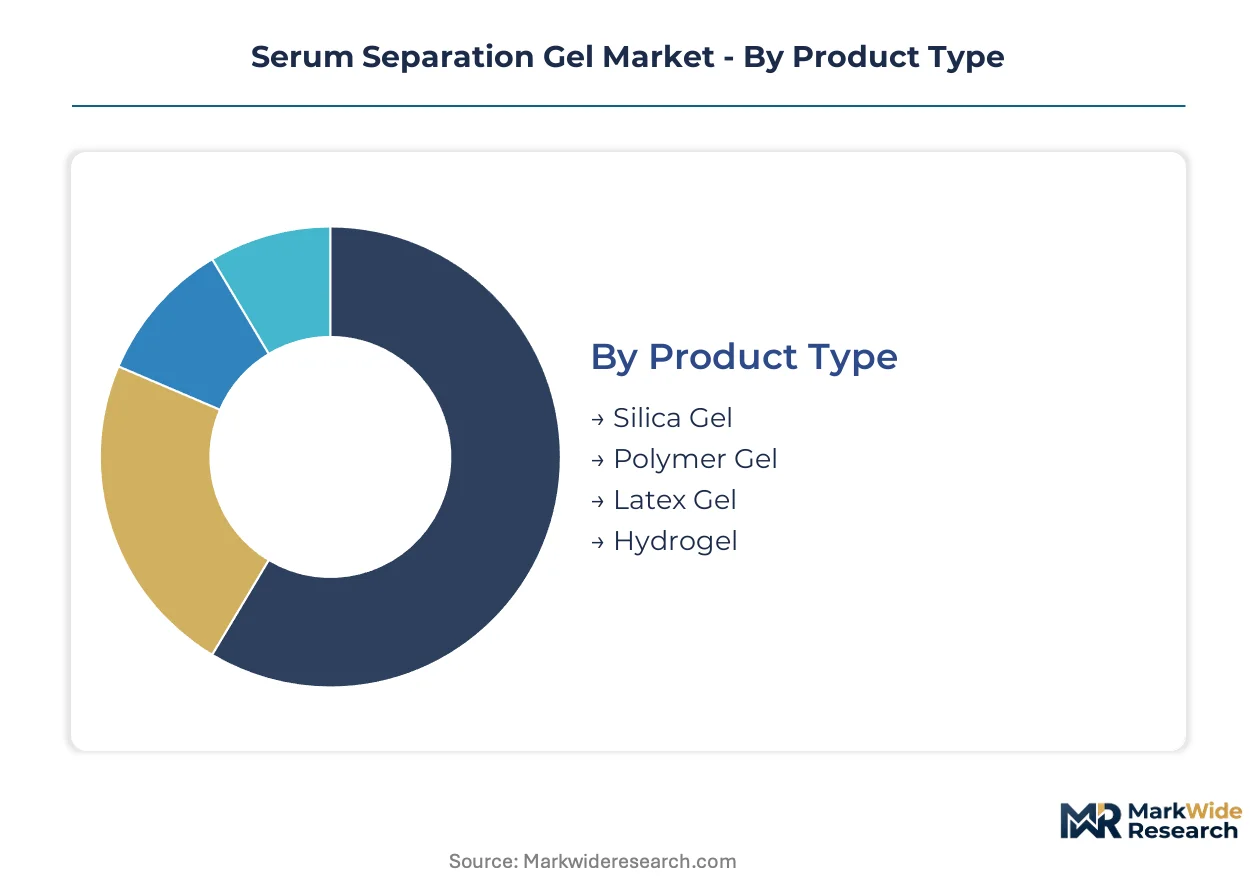
Serum separation gel segmentation reveals how formulation chemistry, procurement scale, and testing workflow complexity fragment demand across healthcare systems. Each dimension carries distinct margin profiles and regulatory qualification barriers that reshape supplier positioning.
Product Type:
Cost tier separates commodity silica from premium polymer variants, with purity grades determining contract eligibility for automated analyzers versus manual processing.
- Silica Gel:Silica particulate suspended in inert carriers delivers the lowest unit cost for high-volume blood bank operations. Rural clinics and donation centers across India and Brazil specify this formulation despite inferior chemical stability during freeze-thaw cycles.
- Polymer Gel:Thixotropic polyester-acrylic copolymers with tuned specific gravity of 1.04–1.06 g/cm³ dominate reference laboratory procurement in Germany, Switzerland, and the United States. ISO 13485 certification has become mandatory for polymer suppliers seeking contracts with American group purchasing organizations.
- Latex Gel:Specialized chemistries serve niche research applications where lot-to-lot consistency commands price premiums in academic medical centers.
- Hydrogel:High-purity formulations from Western European manufacturers supply automated pre-analytical lines requiring rapid gelation kinetics under 10-minute centrifugation protocols.
Silica gel leads volumes today; polymer gel is gaining share fastest.
End User:
Volume scale and processing sophistication divide procurement patterns, with centralized automation favoring certified polymer suppliers while decentralized sites prioritize cost flexibility.
- Diagnostic Labs:Centralized reference laboratories in France and Japan are retrofitting lines for high-throughput centrifugation, creating concentrated demand for thixotropic formulations with documented extractables profiles. FDA biocompatibility protocols and EMA in vitro diagnostic standards enforce stringent qualification timelines that filter out uncertified resin compounders.
- Hospitals:Integrated delivery networks in Texas and California bundle gel tube contracts with broader blood collection system agreements, displacing standalone suppliers. Therapeutic drug monitoring expansion in oncology and immunosuppression protocols demands chemically inert barriers that prevent drug adsorption.
- Clinics:Smaller batch procurement with spot purchasing patterns persists in price-sensitive segments.
- Blood Banks:High-volume, low-margin operations continue specifying silica particulate barriers despite inferior chemical inertness.
Hospitals dominate current procurement value; diagnostic labs are expanding most quickly.
Application:
Maturity of testing protocol determines formulation specification, with established chemistry panels tolerating legacy silica while emerging molecular diagnostics mandate polymer purity.
- Clinical Diagnostics:Automated chemistry and immunoassay platforms in German and Swiss reference laboratories require polymer gel compatibility with 1,000–3,000 × g centrifugation cycles. REACH restrictions on residual monomer content in polymer resins are forcing compounders to shift from bulk synthesis to controlled radical polymerization methods.
- Serum Analysis:Clean serum extraction for downstream testing without red cell contamination drives specification of density-modified resins with rapid barrier formation kinetics.
- Blood Collection:Integration with closed-vacuum evacuated tube manufacturing enables single-source supply contracts for integrated systems.
- Research:Academic and pharmaceutical R&D applications demand lot-to-lot consistency documentation that commands price premiums.
Clinical diagnostics anchors current revenue; serum analysis shows the steepest expansion trajectory.
Distribution Channel:
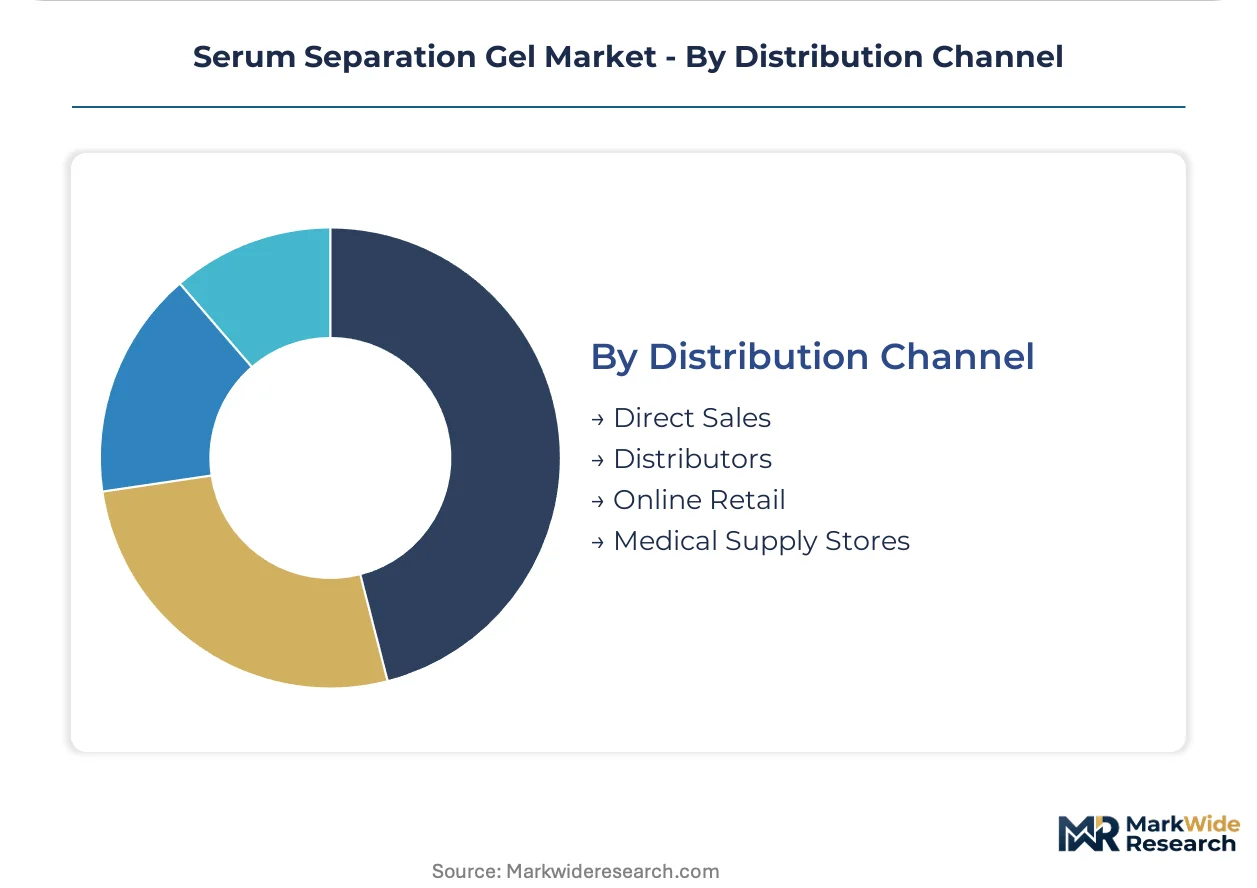
Supply concentration shapes channel strategy, with direct contracts capturing integrated networks while distributors serve fragmented regional demand.
- Direct Sales:Hospital networks running 15-year-old centrifugation equipment require technical support for rotor recalibration when adopting next-generation low-density gels. Direct contracts with North American hospital systems privilege multi-year framework agreements over spot purchasing.
- Distributors:Regional medical supply distributors in Brazil and Mexico are deploying decentralized clinical chemistry analyzers, generating demand for pre-filled gel tubes that eliminate manual pipetting.
- Medical Supply Stores:Local procurement for smaller clinics and rural facilities with limited automation requirements.
- Online Retail:Emerging channel for research-grade products and smaller batch sizes with documented lot-to-lot consistency.
Direct sales commands the largest contract value; distributors are capturing regional expansion fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and diagnostic regulatory specialists concentrate in Germany, Switzerland, and the northeastern United States, anchoring high-purity gel formulation capabilities. These talent clusters shape regional supply patterns and qualification timelines for automated blood processing systems.
United States
Reference laboratories in Texas and California are consolidating procurement through group purchasing organizations that mandate ISO 13485 certification for contract eligibility. FDA quality system regulations enforce stringent biocompatibility testing protocols that extend supplier qualification timelines. The Research Triangle Park cluster in North Carolina hosts contract manufacturers serving diagnostic OEMs with documented extractables profiles.
Germany
Central laboratories in Bavaria and Baden-Württemberg are retrofitting automation lines for 10-minute centrifugation cycles, pulling thixotropic formulations with rapid gelation kinetics. REACH restrictions on residual monomer content in polymer resins force compounders toward controlled radical polymerization methods. The Stuttgart industrial corridor concentrates high-purity hydrogel manufacturing for automated pre-analytical systems.
Switzerland
Diagnostic networks in Basel and Zurich demand chemically inert barriers for therapeutic drug monitoring in oncology and immunosuppression protocols. Swissmedic enforces medical device standards that align with EMA in vitro diagnostic requirements, elevating documentation burdens. The Basel pharmaceutical cluster drives specification of polymer formulations with lot-to-lot consistency documentation.
Japan
Mid-sized diagnostic centers in Kansai and Chubu regions are adopting density-modified resins to run chemistry panels on-site rather than outsourcing to Tokyo hubs. PMDA oversight of in vitro diagnostic consumables requires biocompatibility profiles equivalent to EU MDR standards. The Nagoya medical device corridor hosts compounders serving regional hospital automation retrofits.
Brazil
Regional hospitals in São Paulo and Minas Gerais are deploying decentralized clinical chemistry analyzers, generating demand for pre-filled gel tubes that eliminate manual pipetting. ANVISA pharmaceutical regulator oversight of diagnostic consumables is tightening import documentation requirements. The São Paulo metropolitan area concentrates distribution infrastructure for Latin American diagnostic supply chains.
Serum Separation Gel Market Competitive Landscape
Top-tier vendors anchor polymer formulation supply for automated analyzers, while mid-tier compounders serve price-sensitive blood bank segments with silica alternatives. The vendor base spans three strategic tiers: European hydrogel specialists with backward integration into monomer supply, North American diversified diagnostic conglomerates with direct hospital contracts, and Asia-Pacific latex chemistry specialists serving research niches. Capacity expansion and strategic partnerships represent the dominant competitive moves, as compounders seek to secure resin precursor supply and expand extractables testing capabilities.
Among diversified diagnostic conglomerates, Becton Dickinson & Company and Thermo Fisher Scientific exemplify the North American tier with channel control through integrated blood collection system contracts. Greiner Bio-One International GmbH represents the European specialist archetype, while Sekisui Diagnostics, LLC occupies a position within the latex chemistry niche serving research applications where consistency documentation commands price premiums. These three anchors illustrate how geographic origin and company structure correlate with strategic positioning across certification-driven and price-sensitive market segments.
| Leading Market Players |
|---|
| Cardinal Health, Inc. |
| Becton Dickinson & Company |
| Greiner Bio-One International GmbH |
| Sekisui Diagnostics, LLC |
| Thermo Fisher Scientific |
| Sarstedt AG & Co. KG |
| Terumo Corporation |
| Bio-Rad Laboratories |
| Qiagen N.V. |
| Others |
Value Network & Pricing Analysis
ISO 13485 certification mandates from American group purchasing organizations are forcing resin compounders to absorb qualification costs or exit contract eligibility, compressing margins for uncertified suppliers while elevating price premiums for documented polymer formulations. This procurement consolidation rewards backward-integrated European manufacturers with captive monomer supply.
Pricing Analysis
Bundled blood collection system contracts versus standalone gel tube supply creates the dominant pricing split in this market. Three-tier pricing structure across premium polymer, certified standard, and economy silica levels separates diagnostic laboratories from blood bank operations. Price differentiation rests on ISO 13485 certification grade and therapeutic drug monitoring compatibility. Pricing pressure stems from petrochemical resin volatility in acrylic and polyester precursors. Blood banks exhibit highest price sensitivity; reference laboratories running automated analyzers show lowest sensitivity due to total cost of ownership calculations.
Supply Chain Analysis
Reverse-logistics flows for expired or non-conforming gel tubes remain minimal given single-use medical device classification, though quality returns from hospital networks trigger supplier chargebacks that reshape batch economics. Manufacturing concentrates in Germany, Switzerland, and the United States where specialized polymer chemists anchor high-purity hydrogel production. Raw material dependencies include acrylic monomers, polyester resins, and silica particulates. Single-source vulnerability pervades the three Western European hydrogel manufacturers controlling premium polymer supply. Distribution runs through direct hospital contracts and regional medical supply distributors serving decentralized clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Western Europe create competitive openings for Asia-Pacific suppliers with advanced purification capabilities targeting export markets.
For Market Incumbents: Anticipate silica gel substitution pressure in price-sensitive blood bank segments by accelerating polymer formulation R&D for point-of-care compatibility. Defensive moves center on securing captive resin precursor supply through backward integration and expanding in-house extractables testing capacity to compress qualification timelines for FDA biocompatibility protocols. For New Entrants and Emerging Players: Begin with regional hospital automation retrofits in Brazil and Mexico where ANVISA documentation requirements remain less stringent than FDA or EMA standards. White-space targets include pre-filled gel tubes for decentralized clinical chemistry analyzers and latex-based chemistries for research applications demanding lot-to-lot consistency documentation. A technical sales partnership with established regional distributors offers the strongest go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier compounders possessing advanced purification capabilities and partial ISO 13485 certification progress rather than fully certified market leaders trading at premium multiples. Long-term viability over a five-to-ten year horizon favors targets with demonstrated polymer rheology expertise and diagnostic regulatory filing experience. Monitor EU MDR harmonization enforcement timelines and EPA precursor restrictions as inflection indicators for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Greiner Bio-One and European specialists secure captive acrylic and polyester precursor supply against petrochemical volatility. |
| ISO 13485 Certification Investment | Compounders unlock group purchasing organization contract eligibility with American hospital networks and integrated delivery systems. |
| Extractables Testing Capacity Expansion | In-house chromatography facilities compress FDA biocompatibility qualification timelines from eighteen to six months. |
| Point-of-Care Gel Tube Development | Pre-filled formats eliminate manual pipetting for regional hospital deployments in Brazil and Mexico. |
| Controlled Radical Polymerization Transition | European manufacturers adapt to REACH residual monomer restrictions while creating barriers for bulk synthesis competitors. |
Research Methodology
Direct dialogue with diagnostic laboratory directors, polymer compounder R&D heads, group purchasing organization contract managers, and regulatory affairs specialists at FDA and EMA informed primary intelligence. Secondary validation drew from FDA 510(k) filings, EMA in vitro diagnostic guidance documents, ISO 13485 certification registries, and petrochemical trade flow data. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, application, and distribution channel dimensions.
Segment-level revenue projections emerged from correlating automation capex cycles with gel tube consumption intensity across reference laboratory, hospital, clinic, and blood bank settings. The analytical framework incorporated formulation chemistry grade, certification tier, and geographic regulatory cluster as core segmentation axes. CAGRs derived from regression analysis of historical procurement volumes against centrifugation equipment installation rates and therapeutic drug monitoring protocol expansion. Key forecast inputs included REACH precursor restriction timelines and EU MDR enforcement windows.
Several conditions sit outside the modeled scope, including sudden petrochemical price shocks, trade restriction impositions on resin imports, and disruptive blood processing technologies eliminating centrifugation requirements. Forecasts assume continuity in current regulatory trajectories and automation adoption patterns. Practitioners should monitor EPA chemical substance restrictions, ANVISA import documentation tightening, and point-of-care analyzer deployment rates for early signals of demand redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
LIMS Market
Laboratory Services
UAE Clinical Laboratory Services Market
Laboratory Services
Histopathology Services Market
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Hematocrit Tests Market