
 LIMS Market | 2026-2036
LIMS Market Size, Share, and Industry Trends Forecast 2026-2036
LIMS Market Outlook
ISO 17025 accreditation for laboratory competence is redrawing competitive boundaries in the LIMS landscape. Thermo Fisher Scientific leverages its instrument-to-software integration to anchor enterprise deployments across multi-site laboratory networks. LabWare sustains dominance in regulated industries through deep configuration capabilities for GxP environments. Autoscribe Informatics differentiates with configurable matrix architecture that navigates diverse laboratory workflows without custom coding.
A Laboratory Information Management System (LIMS) is a software platform that orchestrates sample tracking, protocol execution, and data integrity across laboratory operations, typically integrating barcode-based specimen identification with automated instrument data capture. Its primary industrial purpose is to eliminate transcription errors, enforce standard operating procedures, and maintain audit trails for regulatory submission. Cloud-based deployments are capturing the fastest growth as pharmaceutical and biotechnology end users shift capital expenditure to operational expenditure models. On-premise installations retain margin concentration among clinical laboratories bound by stringent data sovereignty requirements. Sample management features occupy the core value proposition, while workflow automation modules are emerging as the primary upsell pathway for vendors.
The FDA enforces 21 CFR Part 11 requirements for electronic records and signatures, compelling LIMS vendors to embed audit trails, access controls, and data integrity safeguards directly into platform architecture. EPA methodologies for environmental testing laboratories and EMA GxP guidelines for European pharmaceutical manufacturing similarly shape product development roadmaps and customer qualification cycles. Stakeholders must monitor how emerging AI-assisted data interpretation features interact with existing validation frameworks and regulator expectations for algorithmic transparency.
Market Dynamics
Cloud migration pressure from pharmaceutical laboratories is compressing deployment timelines and forcing vendors to rearchitect validation frameworks for hybrid environments. This structural shift is redrawing competitive boundaries between established on-premise incumbents and cloud-native entrants.
Growth Catalysts
- FDA 21 CFR Part 11 mandate:Electronic records requirements compel laboratories to replace paper-based workflows with validated digital systems, creating replacement demand across regulated industries.
- ISO 17025 accreditation expansion:Testing laboratories pursuing international competence certification require audit-ready documentation infrastructure that LIMS platforms provide.
- Multi-site laboratory networks:Centralized quality control needs across distributed pharmaceutical manufacturing sites are driving enterprise-scale deployments with harmonized protocols.
Market Restraints
- Data sovereignty requirements:Clinical diagnostic networks in Germany, France, and Japan face jurisdictional restrictions that block pure public-cloud deployments and prolong sales cycles.
- Validation cost structure:GxP environments require extensive IQ/OQ/PQ documentation that consumes 40-60% of total implementation budgets and extends payback periods.
- Specialized integration labor:Scarce professionals combining laboratory science with software configuration command premium rates that inflate total cost of ownership.
Strategic Opportunities
- AI-assisted data interpretation:Machine learning modules for anomaly detection and predictive quality control represent uncontracted upsell potential within existing customer bases.
- India pharmaceutical manufacturing:CDSCO's tightening data integrity enforcement and PLI scheme capacity expansion create first-time buyer segments in API and formulation facilities.
- Subscription pricing convergence:SaaS models penetrating clinical diagnostics enable vendors to capture recurring revenue streams previously concentrated in perpetual license markets.
Industry Challenges
- Instrument connectivity fragmentation:Proprietary data formats from chromatography, mass spectrometry, and automation equipment require costly custom driver development for seamless integration.
- GxP validation timeline compression:Compressed go-live schedules for manufacturing support systems strain quality assurance resources and elevate defect risk in audit trail configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LIMS Market |
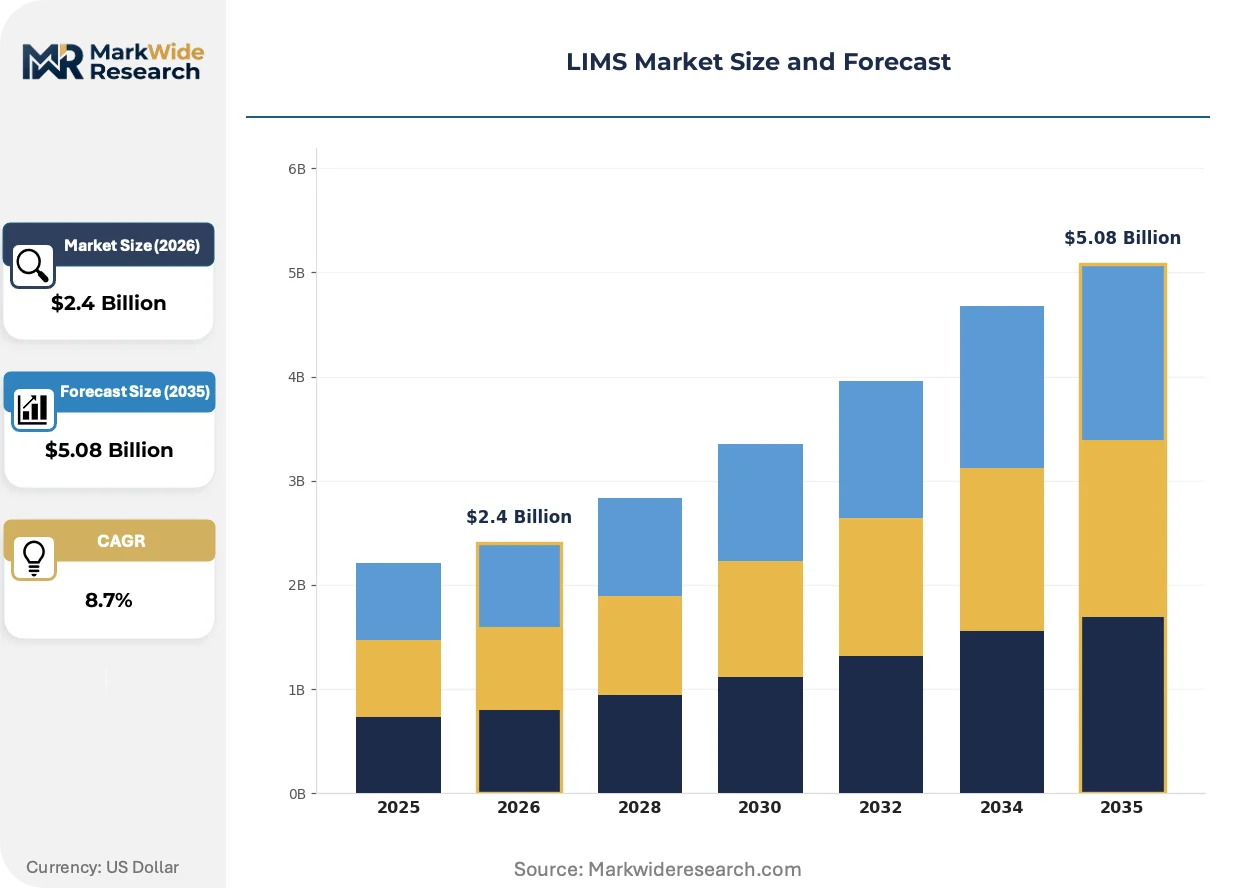
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Enterprise Solutions, Mobile Platforms End User: Pharmaceuticals, Biotechnology, Clinical Laboratories, Research Institutions Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Local Servers Feature: Sample Management, Data Analysis, Compliance Tracking, Workflow Automation |
| Companies Covered | LabWare, Clinisys, Thermo Fisher Scientific, Abbott Laboratories, PerkinElmer, Siemens, Autoscribe Informatics, Orchard Software, LabVantage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LIMS Market Strategic Shifts
Platform architecture decisions are splitting the vendor landscape between configurable codeless environments and traditional customization-dependent systems. This divergence reflects divergent buyer risk tolerances and internal IT capabilities.
Low-code configuration frameworks are bifurcating the competitive landscape. Autoscribe Informatics and similar vendors deploy matrix-based architectures that enable laboratory administrators to modify workflows without software engineering support. Mid-sized contract research organizations are adopting these platforms at twice the pace of large pharmaceutical enterprises, which retain bespoke development preferences. This technology is compressing implementation timelines from 18-24 months toward 6-12 week deployments for standardized protocols.
EMA's GxP data integrity guidelines are tightening audit trail expectations for European pharmaceutical manufacturing. The regulator's 2018 guidance revision and subsequent inspection practices now demand complete reconstruction capabilities for all data modifications, not merely change logs. Small molecule API producers in Ireland, Switzerland, and the Netherlands are retrofitting legacy systems or replacing platforms that cannot demonstrate ALCOA+ principle compliance without manual workarounds.
Outcome-based contracting is displacing traditional perpetual license models in North American clinical diagnostic networks. Laboratory service providers now demand pricing tied to uptime guarantees, regulatory inspection outcomes, and sample throughput metrics rather than seat counts or module fees. This shift concentrates vendor risk but locks in longer contractual relationships with integrated service obligations spanning validation, training, and continuous compliance monitoring.
LIMS Market Segmentation
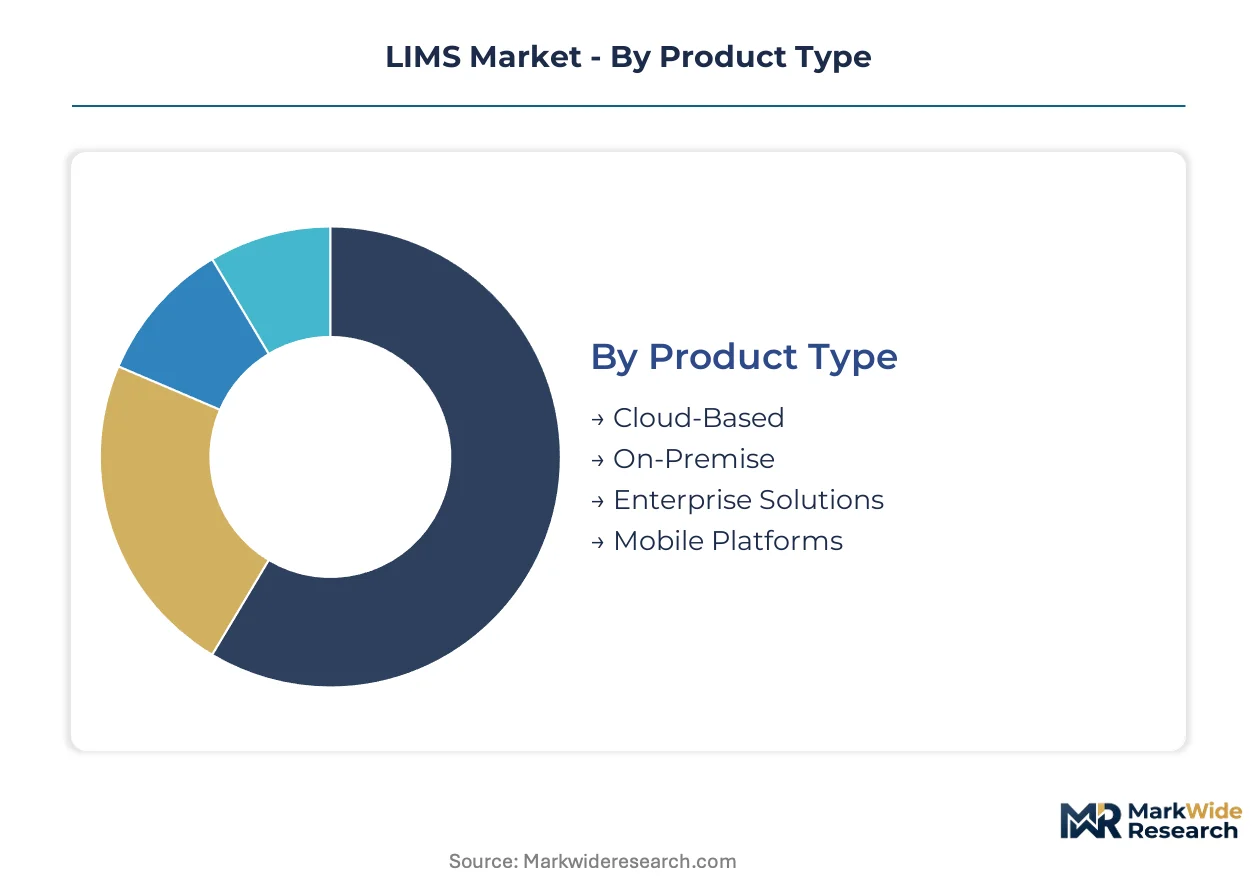
LIMS segmentation reveals divergent growth vectors across deployment architectures and end-use verticals. Pharmaceutical laboratories drive premium-tier demand for validated cloud platforms, while clinical diagnostics sustain on-premise infrastructure investments. Understanding these splits enables targeted product positioning and resource allocation across heterogeneous buyer ecosystems.
Product Type:
Geographic concentration varies sharply: cloud-based solutions serve export-oriented pharmaceutical networks, while on-premise deployments cluster in domestically regulated clinical markets.
- Cloud-Based:Multi-tenant SaaS architectures enable centralized protocol harmonization across distributed manufacturing sites. Demand concentrates in United States pharmaceutical networks responding to FDA 21 CFR Part 11 mandates, with subscription models converting capital expenditure to operational expenditure.
- On-Premise:Single-tenant installations maintain full data sovereignty within facility firewalls. German and French clinical diagnostic networks favor these systems due to national health data localization requirements, extending sales cycles but securing long-term maintenance contracts.
- Enterprise Solutions:Multi-site orchestration platforms integrating instrument fleets, quality systems, and regulatory submission workflows.
- Mobile Platforms:Tablet and smartphone interfaces for sample collection, equipment monitoring, and exception handling at point-of-work.
On-Premise holds the largest share; momentum sits with Cloud-Based.
End User:
Cost tier differentiation separates validated GxP environments from research-grade deployments, with compliance overhead driving 3-5x pricing multiples at the premium end.
- Pharmaceuticals:Commercial manufacturing and quality control operations requiring audit-ready documentation for FDA, EMA, and national regulator inspections. United States and European Union facilities dominate procurement volumes, with India emerging as a first-time buyer segment under CDSCO enforcement tightening.
- Biotechnology:Cell therapy, gene editing, and bioprocess development workflows with evolving protocol requirements. These organizations prioritize configurable platforms that accommodate rapid methodological iteration without revalidation penalties.
- Clinical Laboratories:Diagnostic testing networks processing patient specimens under HIPAA, GDPR, or equivalent national privacy frameworks.
- Research Institutions:Academic and government laboratories with flexible funding cycles and lower compliance burdens.
Pharmaceuticals commands the revenue concentration; biotechnology is climbing the fastest.
Deployment:
Application context determines architecture selection, with manufacturing support systems favoring isolation and collaborative research favoring accessibility.
- Public Cloud:Shared infrastructure with vendor-managed security patches and scalability. Adoption concentrates in United States contract research organizations lacking internal IT security resources.
- Private Cloud:Dedicated single-tenant environments hosted in third-party data centers. Japanese pharmaceutical manufacturers prefer these configurations under METI guidance on commercial data protection.
- Hybrid Cloud:Workload splitting between on-premise core systems and cloud burst capacity for analytics or archival.
- Local Servers:Air-gapped or facility-bound hardware with no external connectivity.
Hybrid Cloud captures the steepest expansion trajectory as risk-averse organizations test cloud migration boundaries.
Feature:
Customer type segmentation shows enterprise buyers purchasing integrated suites while mid-market organizations prioritize standalone modules with clear ROI demonstration.
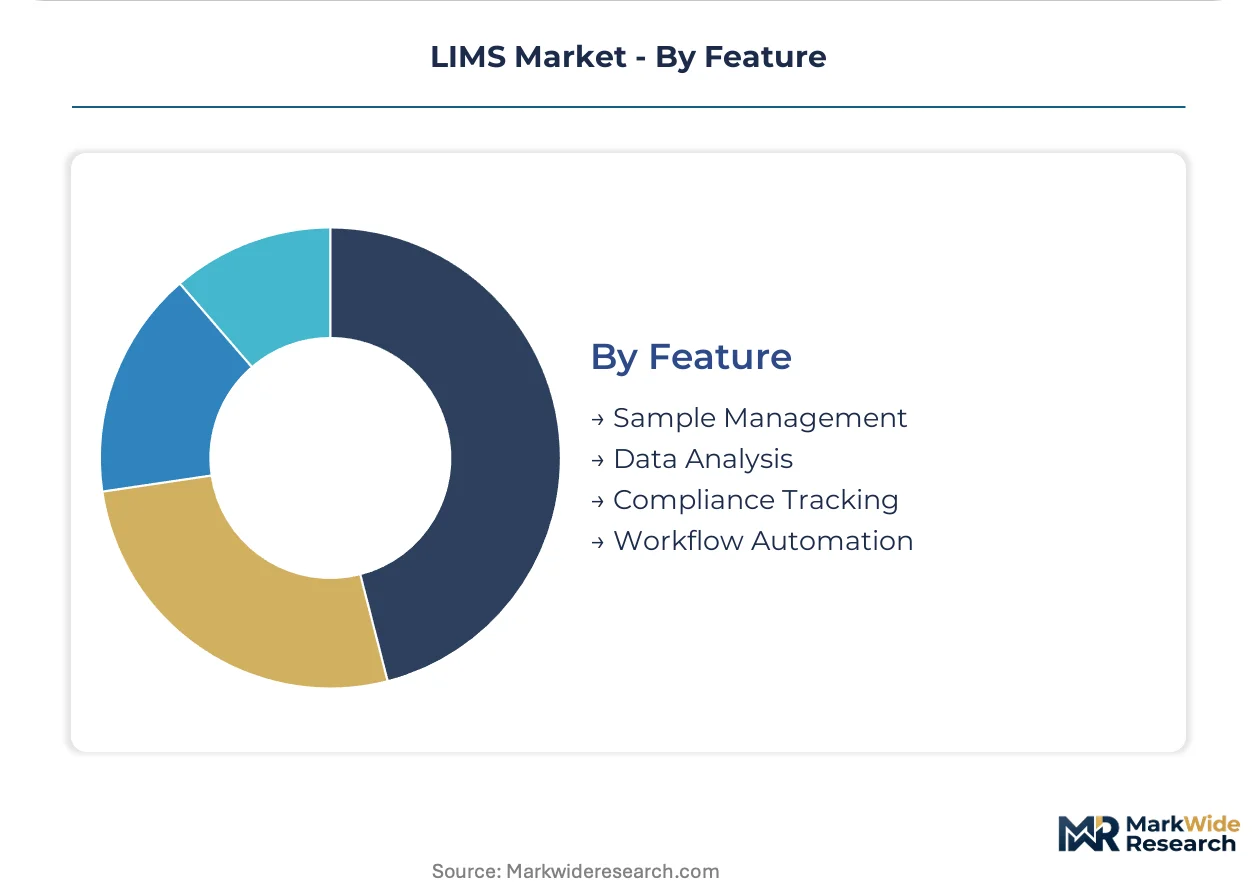
- Sample Management:Barcode tracking, chain-of-custody documentation, and storage location mapping. This capability anchors virtually all LIMS implementations, with demand universal across end-use verticals and geographies.
- Data Analysis:Statistical process control, trend detection, and instrument data visualization. Biotechnology end users in Switzerland and the Netherlands are retrofitting legacy systems to incorporate these capabilities under EMA ALCOA+ compliance expectations.
- Compliance Tracking:Audit trail generation, electronic signature workflows, and deviation management.
- Workflow Automation:Protocol-driven task routing, instrument integration, and exception escalation.
Sample Management holds the largest share; Workflow Automation is gaining share fastest as labor cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO's tightening data integrity enforcement and India's PLI scheme are accelerating first-time LIMS procurement across API and formulation facilities. National regulators in Germany, Japan, and the United States are enforcing divergent data sovereignty requirements that fragment deployment architectures.
United States
FDA's 21 CFR Part 11 mandate compels pharmaceutical laboratories to replace paper-based workflows with validated digital systems. Clinical diagnostic networks in Texas and California are converting capital expenditure to operational expenditure through SaaS subscription models. The Boston-Cambridge biotechnology corridor drives demand for configurable platforms that accommodate rapid methodological iteration.
Germany
ANSM and federal data protection authorities enforce stringent health data localization requirements that block pure public-cloud deployments. Clinical diagnostic networks in Bavaria and North Rhine-Westphalia favor on-premise installations with full facility firewall isolation. German pharmaceutical manufacturers are retrofitting legacy systems to demonstrate ALCOA+ principle compliance under EMA inspection practices.
India
CDSCO's data integrity enforcement and the PLI scheme's capacity expansion create first-time buyer segments in API and formulation facilities. Maharashtra and Gujarat host concentrated pharmaceutical manufacturing clusters where harmonized multi-site quality control drives enterprise-scale deployments. Domestic contract research organizations are adopting cloud-native platforms at twice the pace of large multinational enterprises.
Japan
METI guidance on commercial data protection steers pharmaceutical manufacturers toward private cloud configurations. PMDA inspection practices demand complete reconstruction capabilities for all data modifications, elevating platform replacement cycles. The Kanto region around Tokyo anchors domestic demand for instrument-to-software integration across distributed manufacturing sites.
Switzerland
Swissmedic's alignment with EMA GxP guidelines tightens audit trail expectations for small molecule API producers. Basel and the greater Zurich area concentrate biotechnology end users prioritizing statistical process control retrofits. Swiss facilities are retrofitting legacy systems to incorporate predictive quality control capabilities under tightening European regulatory frameworks.
LIMS Market Competitive Environment
Player mix skews toward instrument-integrated conglomerates and configurable software specialists. The vendor base concentrates around three strategic archetypes: laboratory equipment manufacturers bundling proprietary software, pure-play LIMS developers emphasizing codeless configuration, and diagnostic conglomerates leveraging installed instrument bases. Consolidation pressure is accelerating through strategic partnerships between cloud infrastructure providers and validation specialists, while geographic expansion into India's pharmaceutical corridor represents the dominant competitive move.
Within the instrument-integrated tier, Thermo Fisher Scientific and PerkinElmer exemplify conglomerates leveraging hardware-to-software pipelines. LabWare and Autoscribe Informatics occupy positions among pure-play specialists emphasizing deep configuration capabilities. Among diagnostic-focused vendors, Abbott Laboratories and Siemens represent conglomerates with captive laboratory service networks. Orchard Software and LabVantage sit within the mid-market configurable tier serving clinical diagnostic networks with accelerated deployment timelines.
| Leading Market Players |
|---|
| LabWare |
| Clinisys |
| Thermo Fisher Scientific |
| Abbott Laboratories |
| PerkinElmer |
| Siemens |
| Autoscribe Informatics |
| Orchard Software |
| LabVantage |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation agreements spanning three-to-five-year terms lock in cloud infrastructure access and flatten operational expenditure volatility for pharmaceutical laboratories migrating from perpetual licenses. These contract structures tether vendor revenue streams to validated uptime guarantees while compressing buyer switching costs through embedded professional services.
Pricing Analysis
Certification level creates the primary spread between GxP-validated enterprise tiers and research-grade deployments. Subscription SaaS models dominate pharmaceutical networks converting capital expenditure, with pricing stratifying across premium validated tiers, standard compliance-ready tiers, and economy research-grade tiers. Cost compression in mid-market clinical diagnostics intensifies because cloud-native entrants undercut legacy perpetual-license incumbents. Contract research organizations exhibit highest price sensitivity; multi-site pharmaceutical manufacturers with FDA inspection exposure demonstrate lowest sensitivity due to revalidation switching costs.
Supply Chain Analysis
Port congestion across Asia-Pacific trade lanes elevates lead times for on-premise server hardware destined for German and Japanese data sovereignty installations. Software development concentrates in the United States, Ireland, and India; cloud infrastructure draws from hyperscaler facilities in Virginia, Frankfurt, and Singapore. Single-source vulnerability sits with proprietary instrument driver libraries controlled by chromatography and mass spectrometry equipment manufacturers. Distribution runs through direct enterprise sales teams for validated deployments and channel partners for mid-market clinical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical capital expenditure cycles are recovering from post-pandemic retrenchment, with laboratory automation budgets expanding under FDA 21 CFR Part 11 enforcement pressure.
For Market Incumbents: Compound defensive moats by embedding AI-assisted data interpretation modules into existing validated installations before cloud-native entrants achieve GxP qualification. Prioritize backward integration into instrument driver development to neutralize connectivity fragmentation threats from competing hardware vendors. Extend certification maintenance contracts for legacy on-premise deployments to capture recurring revenue during hybrid-cloud transition periods. For New Entrants and Emerging Players: ISO 17025 fast-track partnerships with accreditation bodies accelerate market entry for configurable matrix-architecture platforms. White-space concentrates in India's API manufacturing corridor under CDSCO data integrity tightening, and in Swiss biotechnology statistical process control retrofits. Lead with six-to-twelve-week deployment guarantees against incumbent eighteen-month implementation timelines to penetrate mid-sized contract research organizations. For Investors and Strategic Acquirers: Cloud-native validation specialists with pre-built FDA 21 CFR Part 11 documentation packages represent the most defensible acquisition archetype. Long-term viability hinges on recurring revenue mix exceeding perpetual-license dependency. Monitor EMA inspection practice shifts toward ALCOA+ complete reconstruction requirements as the inflection signal for legacy system replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| AI Module Integration | FDA-validated machine learning for anomaly detection captures upsell revenue within existing pharmaceutical customer bases. |
| India Geographic Expansion | CDSCO enforcement tightening and PLI scheme capacity expansion create first-time buyer segments in Maharashtra and Gujarat. |
| Hybrid Cloud Certification | Pre-validated hybrid architectures reduce GxP documentation burden for risk-averse clinical diagnostic networks. |
| Instrument Driver Acquisition | Captive connectivity libraries neutralize fragmentation risk from competing chromatography and mass spectrometry vendors. |
| Outcome-Based Contracting | Uptime-guarantee pricing locks in longer relationships with North American clinical laboratory service providers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory information system directors, quality assurance leads at pharmaceutical manufacturers, regulatory affairs specialists, and clinical diagnostic network procurement officers. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA GxP data integrity guidelines, ISO 17025 accreditation standards, and CDSCO enforcement circulars. Bottom-up deployment counts across end-use verticals were triangulated against top-down vendor revenue estimates.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning deployment architecture, end-use vertical, organization size tier, and regional regulatory cluster. CAGRs were derived from installation base expansion rates and pricing trajectory assumptions. Industry-specific inputs included pharmaceutical manufacturing capital expenditure cycles, clinical diagnostic network consolidation patterns, and cloud infrastructure hyperscaler capacity expansion disclosures.
Underlying assumptions cover sustained FDA 21 CFR Part 11 enforcement intensity and stable cloud infrastructure cost curves, with deviation risk concentrated in data sovereignty regulatory fragmentation and AI validation framework uncertainty. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Cytotoxicity Assays Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Myoglobin Reagents Market
Laboratory Services
Assessment Services Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Autosampler Vials Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Sera and Reagents Market
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
Pathology Services Market
Laboratory Services
Pathology Laboratories Market