
 Colony Counters Market | 2026-2036
Colony Counters Market Size, Share, and Industry Trends Forecast 2026-2036
Colony Counters Market Analysis
Aftermarket service revenue for calibration and software updates is fragmenting as instrument vendors and third-party service providers compete for recurring contracts. Molecular Devices LLC leverages its image analysis expertise to sustain premium positioning in high-content screening labs. bioMérieux anchors its installed base through integrated consumable workflows that tie hardware to reagent revenue. Interscience competes on portable digital counter designs for field microbiology applications.
Colony counters are laboratory instruments that enumerate bacterial and fungal colonies on solid culture media through manual scoring, digital imaging, or automated machine-vision algorithms with detection thresholds typically below 0.1 millimeter. These devices serve pharmaceutical quality control, food safety testing, and clinical microbiology by replacing subjective human counts with reproducible quantitative data. Automated counters and image analysis systems command the highest margin pools as pharmaceutical labs prioritize 21 CFR Part 11-compliant documentation and AI-assisted colony classification. Manual counters retain share in educational institutions and resource-constrained settings where capital budgets limit digital adoption. Digital counters occupy a transitional tier, growing fastest among small quality control labs seeking middle-ground throughput without full automation infrastructure.
FDA pharmacopeial standards and EMA microbial limits guidance shape instrument validation requirements and drive replacement cycles in regulated pharmaceutical environments. ISO 11133 and ISO 17025 accreditation frameworks compel labs to demonstrate measurement traceability, favoring vendors with certified calibration protocols and audit-ready software. Stakeholders must weigh capital intensity against regulatory risk as microbiology labs face escalating pressure to demonstrate data integrity across every counting workflow.
Market Dynamics
Machine-vision algorithms are compressing detection thresholds below 0.1 millimeter while FDA sterility testing mandates force pharmaceutical labs to replace subjective manual counts with reproducible automated workflows. This dual pressure is restructuring competitive positioning around 21 CFR Part 11-compliant documentation systems.
Growth Catalysts
- FDA pharmacopeial enforcement:Tightening microbial limits thresholds in sterile manufacturing compel replacement cycles for non-validated counting equipment across US pharmaceutical quality control labs.
- AI-assisted classification:Deep learning models trained on colony morphology datasets reduce enumeration variance to sub-5% coefficients, accelerating adoption in high-throughput screening facilities.
- Germany's biopharmaceutical corridor:Concentrated vaccine and cell therapy manufacturing in the Rhine-Main-Neckar cluster sustains demand for integrated colony counting workflows tied to reagent supply contracts.
Market Restraints
- Capital intensity of full automation:Pharmaceutical-grade automated counters require six-figure USD investments that exclude resource-constrained clinical microbiology labs and educational institutions.
- Consumable lock-in economics:Integrated reagent workflows from dominant vendors create switching costs that fragment the installed base and limit price competition.
- Validation timeline friction:ISO 17025 accreditation and 21 CFR Part 11 software validation extend procurement cycles to 12-18 months, delaying revenue recognition for instrument suppliers.
Strategic Opportunities
- Portable digital counters for field microbiology:Battery-powered imaging systems with offline analysis capabilities address environmental monitoring and food safety testing outside centralized lab infrastructure.
- EMA microbial limits alignment:Harmonization between FDA and European pharmacopeial standards creates dual-certification pathways that reduce validation burden for vendors serving transatlantic pharmaceutical clients.
- Cloud-connected instrument fleets:Remote calibration monitoring and predictive maintenance contracts convert capital sales into recurring revenue streams while reducing downtime for multi-site quality control networks.
Industry Challenges
- Image analysis expertise scarcity:Shortage of computational biologists capable of training and validating machine-vision models for novel colony morphologies limits product development velocity.
- Legacy LIMS integration complexity:Proprietary data formats from established counters require custom middleware development to connect with modern laboratory information management systems.
- Measurement traceability demonstration:ISO 11133 compliance demands documented calibration chains that many third-party service providers cannot certify, narrowing vendor selection for accredited labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colony Counters Market |
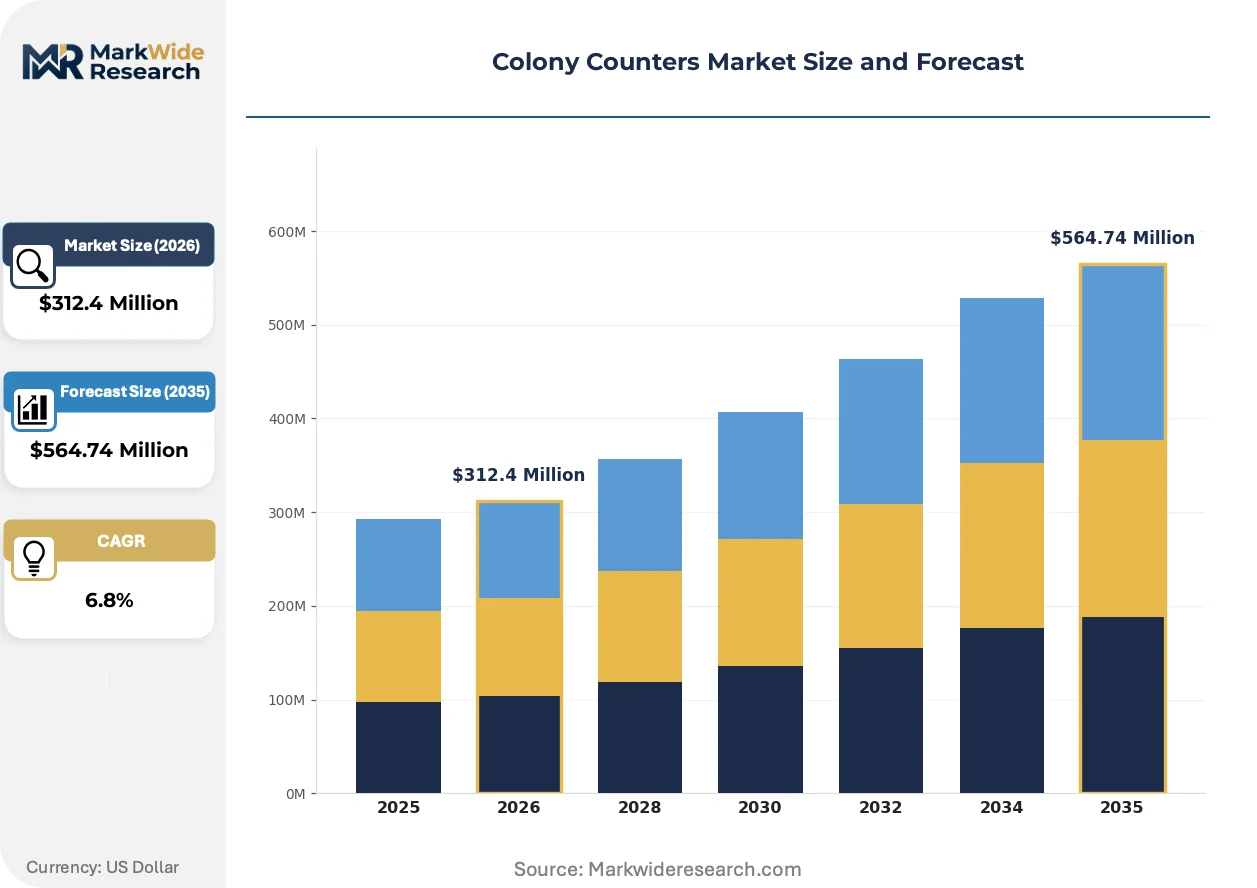
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Manual Counters, Digital Counters, Automated Counters, Image Analysis Systems Application: Microbiology, Food Safety, Clinical Diagnostics, Environmental Monitoring End User: Pharmaceutical Labs, Research Institutes, Quality Control Labs, Educational Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Cole-Parmer Instrument Company LLC, Molecular Devices LLC, Singer Instrument Company Limited, Oxford Optronix Ltd, Synbiosis, Topac Inc., Interscience, Analytik Jena, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colony Counters Market Emerging Trajectories
Colony counting instrumentation is bifurcating between premium automated systems and accessible digital platforms, with software capabilities becoming the primary differentiation vector over hardware specifications. This shift elevates image analysis algorithms and regulatory compliance features above optical resolution in purchasing decisions.
Machine-vision colony counters is hybridizing fluorescence detection with brightfield imaging to enumerate stressed or viable-but-non-culturable cells that conventional methods miss. Contract research organizations running antimicrobial susceptibility testing are adopting these multimodal systems to capture viability data in single-pass workflows. The convergence is compressing demand for standalone viability stains and secondary confirmation assays.
EMA's tightened interpretation of microbial limits guidance is forcing pharmaceutical manufacturers to demonstrate environmental monitoring data integrity across extended batch records. This regulatory pressure is accelerating replacement of manual counters with audit-trail-equipped automated systems in European sterile manufacturing facilities. German and Swiss quality control labs are prioritizing vendors with pre-validated software packages to compress qualification timelines.
Aftermarket service unbundling is fragmenting the traditional vendor-captive model as third-party calibration specialists capture recurring contracts from cost-conscious quality control departments. Small-to-mid pharmaceutical labs in the Boston-Cambridge cluster are separating instrument purchase decisions from service agreements, pressuring OEMs to compete on discrete software update and validation support pricing. This behavioral shift is most pronounced among biotech startups lacking capital to commit to multi-year comprehensive service contracts.
Colony Counters Market Segmentation
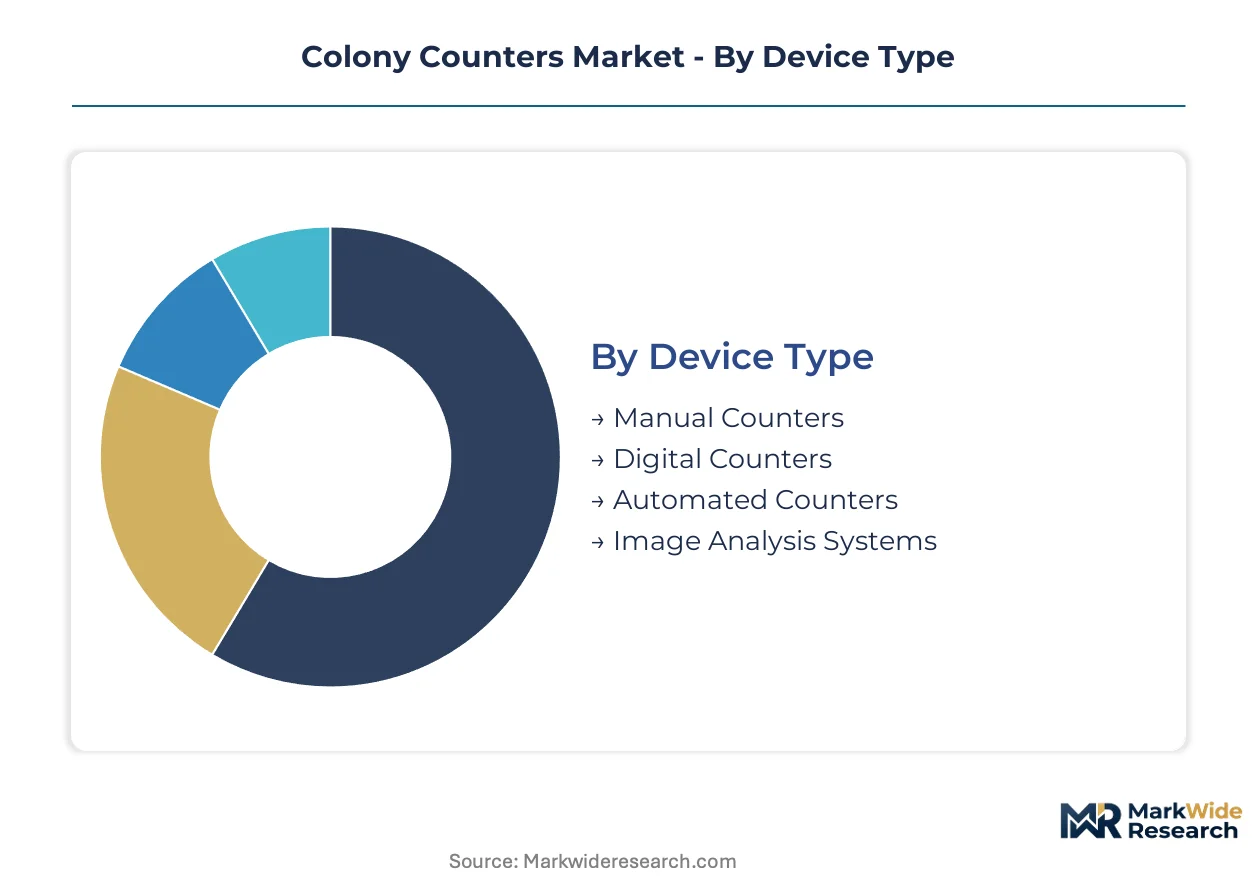
Segmentation in the colony counters market reveals how regulatory pressure, throughput requirements, and capital constraints fragment purchasing behavior across laboratories. Device type and end-user alignment determine margin capture, while application-specific validation needs shape vendor selection criteria.
Device Type:
Pharmaceutical quality control demands reproducible enumeration with audit trails, while educational budgets prioritize accessibility over automation depth.
- Manual Counters:Simple mechanical or illuminated counting grids requiring operator visual scoring without digital capture. Educational institutions in resource-constrained markets sustain demand where capital budgets exclude electronic systems.
- Digital Counters:Camera-equipped units with basic image storage and manual confirmation interfaces. Small quality control labs in Germany's biopharmaceutical corridor adopt these as stepping stones toward full automation without six-figure capital commitments.
- Automated Counters:Machine-vision systems with colony classification algorithms and 21 CFR Part 11-compliant software documentation. FDA sterility testing mandates in US pharmaceutical manufacturing drive replacement cycles for validated automated workflows.
- Image Analysis Systems:High-content screening platforms integrating multimodal detection with AI-assisted morphology classification. Contract research organizations running antimicrobial susceptibility testing concentrate demand for viability-integrated enumeration.
The dominant share belongs to Automated Counters, while Image Analysis Systems are gaining share fastest.
Application:
Regulatory frameworks diverge sharply across application areas, with pharmaceutical compliance costs far exceeding food safety or environmental monitoring thresholds.
- Microbiology:Core bacterial and fungal enumeration on solid culture media for research and clinical purposes. Research institutes in the Boston-Cambridge cluster deploy high-throughput systems for strain characterization and antimicrobial resistance surveillance.
- Food Safety:Pathogen detection and spoilage organism quantification in production environments. Environmental monitoring programs at dairy and meat processing facilities in Switzerland drive portable digital counter adoption for on-site testing.
- Clinical Diagnostics:Patient sample processing for infection identification and treatment guidance. Hospital laboratories facing staffing shortages prioritize automated systems to reduce technician time per specimen.
- Environmental Monitoring:Air, water, and surface contamination assessment outside controlled manufacturing settings. Field microbiology teams in France utilize battery-powered imaging systems with offline analysis for remote site surveys.
Microbiology commands the largest installed base, though Food Safety applications are expanding most quickly.
End User:
Capital availability and regulatory exposure create distinct purchasing profiles across laboratory types, from validation-heavy pharmaceutical operations to budget-driven academic settings.
- Pharmaceutical Labs:GMP-compliant quality control facilities subject to FDA and EMA microbial limits enforcement. Sterile manufacturing sites in Germany and Switzerland prioritize pre-validated software packages to compress qualification timelines.
- Research Institutes:Academic and government facilities pursuing basic microbiology and antimicrobial discovery. NIH-funded laboratories in the US sustain demand for high-content screening platforms with open data formats.
- Quality Control Labs:Third-party testing providers serving food, cosmetic, and environmental clients. ISO 17025 accreditation requirements favor vendors with certified calibration protocols and measurement traceability documentation.
- Educational Institutions:University teaching laboratories and technical training centers. Manual counters retain substantial share here where pedagogical emphasis on direct observation outweighs throughput needs.
Pharmaceutical Labs dominate revenue contribution, while Quality Control Labs are climbing the fastest.
Distribution Channel:
Instrument complexity and service bundling requirements shape channel selection, with direct relationships preferred for validated systems and third-party channels serving price-sensitive segments.
- Online Retail:E-commerce platforms serving manual and entry-level digital counter segments. Educational buyers and small clinical labs in the US leverage transparent pricing and rapid delivery for non-validated equipment.
- Direct Sales:Manufacturer-led engagement for automated counters and image analysis systems. Pharmaceutical clients in Germany demand direct technical support for installation qualification and operational qualification protocols.
- Distributors:Regional intermediaries with local service capabilities and existing laboratory relationships. French and Swiss quality control labs rely on distributors for multilingual support and rapid spare parts availability.
- Specialty Stores:Niche laboratory supply retailers with consultative sales approaches. Smaller research institutes value hands-on demonstration access before committing to capital equipment purchases.
Direct Sales captures the premium tier, though Online Retail is expanding fastest at the entry level.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Educational buyers in India and Southeast Asia prioritize manual counters, while German and Swiss pharmaceutical facilities absorb six-figure automation premiums without procurement friction.
United States
FDA sterility testing mandates and 21 CFR Part 11 enforcement drive replacement cycles in pharmaceutical quality control labs. The Boston-Cambridge research cluster sustains demand for high-content screening platforms with AI-assisted colony classification. Biotech startups here unbundle service contracts from hardware purchases to preserve capital.
Germany
The Rhine-Main-Neckar biopharmaceutical corridor concentrates vaccine and cell therapy manufacturing demand. EMA microbial limits guidance tightens validation requirements for environmental monitoring workflows. Heidelberg and Mannheim quality control labs prioritize pre-validated software packages to compress 12-18 month qualification timelines.
Switzerland
Swissmedic oversight of sterile manufacturing elevates audit-trail requirements for colony counting documentation. Basel's pharmaceutical headquarters cluster drives premium automated system adoption with integrated consumable workflows. Swiss quality control departments favor vendors offering certified calibration protocols under ISO 17025 frameworks.
France
ANSM enforcement of pharmacopeial standards shapes instrument validation protocols in pharmaceutical manufacturing. The Paris-Saclay research cluster deploys digital counters for antimicrobial susceptibility testing. Field microbiology teams utilize portable battery-powered imaging systems for remote environmental monitoring surveys.
United Kingdom
MHRA alignment with EMA microbial limits guidance post-Brexit maintains regulatory pressure on sterile manufacturing facilities. The Cambridge-London biotech corridor sustains demand for cloud-connected instrument fleets with predictive maintenance contracts. Academic institutions in Oxford and Edinburgh retain manual counter share for pedagogical microbiology training.
Colony Counters Market Vendor Landscape
Integrated-system specialists and modular-platform providers split the market along automation-depth lines. The vendor base concentrates around three strategic archetypes: pharmaceutical-grade automation vendors with captive reagent workflows, image-analysis software specialists licensing algorithms across hardware platforms, and portable-equipment fabricators serving field microbiology applications. Competitive moves center on unbundling service contracts from hardware sales and cloud-enabling instrument fleets for recurring revenue conversion.
Within the integrated-system tier, bioMérieux and Molecular Devices LLC exemplify contrasting approaches to sustaining installed-base loyalty. Interscience occupies a position among portable-digital specialists addressing environmental monitoring outside centralized laboratory infrastructure. Oxford Optronix Ltd and Synbiosis sit within the mid-tier digital counter segment where small quality control labs seek throughput gains without full automation capital commitments.
| Leading Market Players |
|---|
| Cole-Parmer Instrument Company LLC |
| Molecular Devices LLC |
| Singer Instrument Company Limited |
| Oxford Optronix Ltd |
| Synbiosis |
| Topac Inc. |
| Interscience |
| Analytik Jena |
| bioMérieux |
| Others |
Supply Flow & Price Mechanics
Rhine-Main-Neckar logistics corridors carry optical sensor modules and precision imaging components from German fabrication centers to assembly facilities across Switzerland and France, with freight cost volatility directly amplifying margin compression at the premium automated counter tier while reinforcing price stratification between validated pharmaceutical-grade systems and accessible digital platforms.
Pricing Analysis
Aftermarket service revenue streams—spanning calibration protocols, software validation updates, and predictive maintenance contracts—now constitute the dominant lifetime value driver for instrument vendors, with premium-mid-economy pricing differentiation anchored in 21 CFR Part 11 certification depth and ISO 17025 traceability documentation. Pricing pressure stems from third-party calibration specialists unbundling service contracts and capturing recurring revenue from cost-conscious quality control departments. Educational institutions exhibit highest price sensitivity due to capital budget constraints, while Swiss pharmaceutical manufacturing sites absorb automation premiums without procurement friction.
Supply Chain Analysis
Tariff exposure between Chinese optical component suppliers and German assembly facilities dominates supply chain risk assessment for imaging sensor arrays and machine-vision processing modules. Manufacturing concentration rests in Germany, Switzerland, and the United States for precision optical assemblies and regulatory-compliant software development. Critical dependencies include CMOS sensors, fluorescence filter sets, and aluminum precision housings. Single-source vulnerability persists for AI training datasets and proprietary morphology classification algorithms. Distribution runs through direct sales channels for validated pharmaceutical systems and regional distributors for portable digital counters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colony counters demand follows pharmaceutical capital expenditure cycles, with replacement waves triggered by FDA and EMA enforcement tightening creating predictable recovery intervals across sterile manufacturing quality control budgets.
For Market Incumbents: Entrench installed-base loyalty through captive consumable workflows that tie reagent revenue to hardware platforms, while accelerating cloud-connected instrument fleet deployments to convert capital sales into recurring predictive maintenance contracts. Deepen backward integration into optical sensor calibration protocols to defend against third-party service unbundling. Prioritize pre-validated software packages that compress 12-18 month qualification timelines for EMA microbial limits compliance. For New Entrants and Emerging Players: Build out portable digital counter portfolios targeting field microbiology applications in environmental monitoring and food safety testing outside centralized laboratory infrastructure. France's ANSM-regulated environmental survey programs and Swiss dairy processing facilities represent penetrable white-space segments lacking incumbent lock-in. Pursue distributor partnerships with regional laboratory supply networks offering multilingual technical support and rapid spare parts availability. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates with underoptimized microbiology instrumentation divisions lacking dedicated software development resources. Five-to-ten year viability hinges on AI-assisted classification capability and regulatory compliance automation rather than hardware specifications alone. Monitor FDA warning letter issuance rates for sterility testing violations as the inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Instrument Fleet Deployment | Enables predictive maintenance contracts that convert capital sales into recurring revenue streams for multi-site pharmaceutical quality control networks. |
| Pre-Validated Software Package Development | Compresses ISO 17025 and 21 CFR Part 11 qualification timelines from 18 months to under 12 months for EMA microbial limits compliance. |
| Portable Digital Counter Platform Launch | Addresses battery-powered imaging demand from ANSM-regulated environmental monitoring teams conducting remote site surveys outside laboratory infrastructure. |
| Backward Integration into Optical Sensor Calibration | Defends service revenue capture against third-party calibration specialists unbundling aftermarket contracts from hardware sales. |
| AI-Assisted Morphology Classification Licensing | Leverages deep learning expertise to reduce enumeration variance below 5% coefficients in high-throughput antimicrobial susceptibility testing workflows. |
Methodological Framework
Initial hypotheses were tested against primary input from pharmaceutical quality control managers, regulatory affairs specialists at sterile manufacturing facilities, laboratory information management system integrators, and aftermarket service procurement leads, then refined through secondary validation against FDA 483 observation databases, EMA inspection findings, ISO 11133 accreditation registries, and SEC 10-K instrument vendor disclosures. Bottom-up enumeration of installed base by device type and end-user segment was cross-checked against top-down pharmaceutical capital expenditure tracking across the analysis window.
Demand-supply balance modeling incorporated device type segmentation across manual, digital, automated, and image analysis systems; application splits between microbiology, food safety, clinical diagnostics, and environmental monitoring; and end-user differentiation by regulatory exposure and capital availability. CAGRs were derived from replacement cycle analysis tied to FDA and EMA enforcement tightening patterns, with sensitivity testing around validation timeline friction and third-party service unbundling velocity. Forecast inputs included pharmacopeial standard revision schedules and AI classification algorithm development trajectories.
Practitioners should monitor FDA sterility testing guidance revisions, EMA microbial limits interpretation shifts, and ISO 17025 accreditation expansion rates for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
US Cath Labs Market
Laboratory Equipment
Latin America Laboratory Equipment and Disposables Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Laboratory Rockers and Shakers Market