
 Hematocrit Tests Market | 2026-2036
Hematocrit Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Hematocrit Tests Market Intelligence
The distinction between centralized laboratory technicians and point-of-care operators is collapsing as automation simplifies testing protocols and reduces manual intervention. This shift benefits companies with strong automation portfolios. Sysmex Corporation dominates high-throughput environments with its advanced hematology analyzers. Abbott Laboratories leverages its extensive point-of-care diagnostic lineup to capture decentralized testing opportunities in emergency rooms and clinics.
A hematocrit test measures the proportion of red blood cells in blood, expressed as a packed cell volume (PCV). This test is a fundamental component of a complete blood count (CBC) used to diagnose conditions like anemia, polycythemia, and dehydration. Automated hematology analyzers constitute the largest product segment, driven by needs in high-volume clinical laboratories. Meanwhile, point-of-care devices represent the fastest-growing category, expanding into smaller clinics and diagnostic centers.
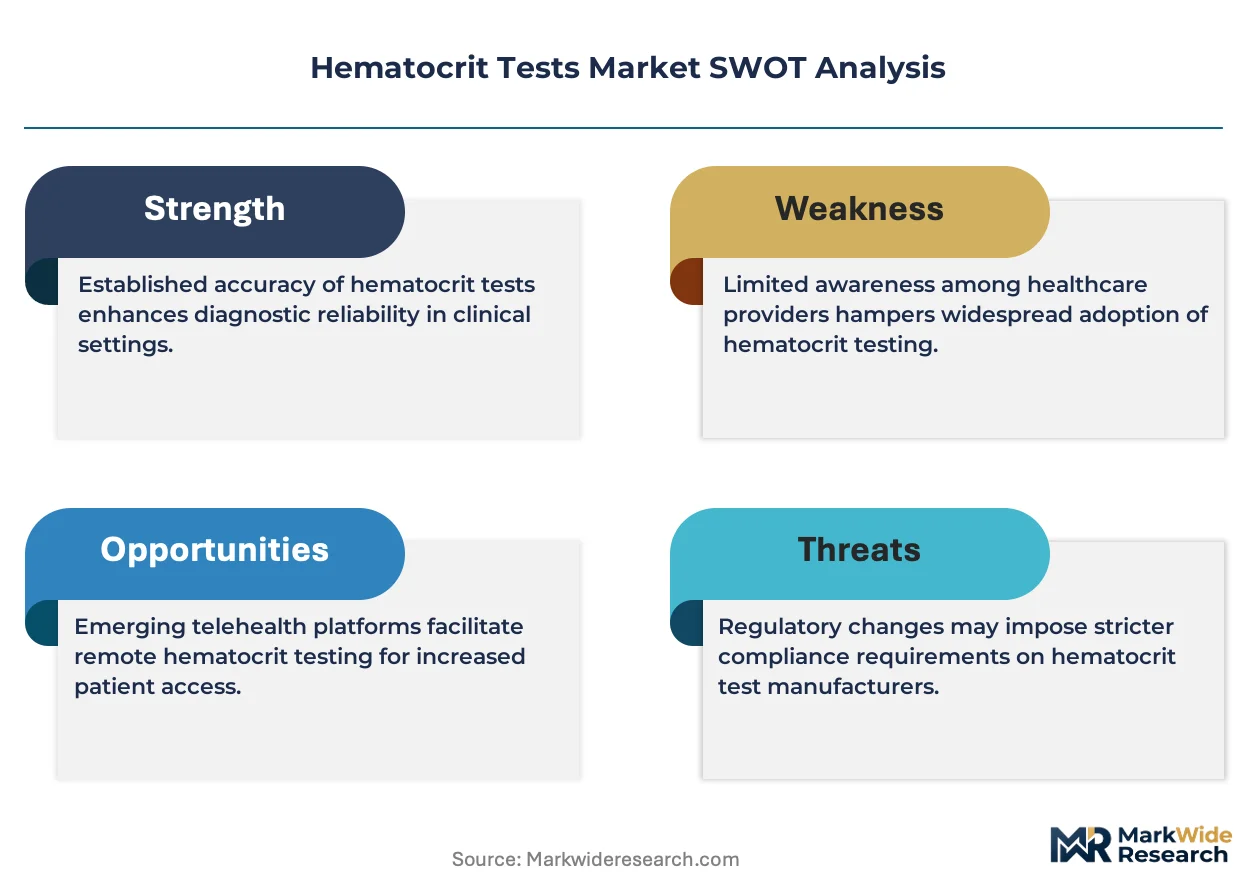
Device approval and quality standards are governed by bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA. These regulations, including the EU's In Vitro Diagnostic Regulation (IVDR), mandate stringent validation for analytical performance and clinical accuracy. Vendor selection will increasingly depend on a device's ability to integrate with digital health records and hospital information systems for seamless data flow.
Market Dynamics
The hematocrit tests market is defined by a fundamental bifurcation in diagnostic strategy. This division pits high-throughput, centralized laboratory automation against the rapid, decentralized results of point-of-care testing, forcing vendors to serve two distinct operational models.
Growth Catalysts
- Public Health Programs:Government-led initiatives in countries like China to expand primary healthcare and chronic disease screening are increasing the volume of routine blood tests, including hematocrit measurements.
- Point-of-Care Expansion:The adoption of portable hematocrit devices is accelerating in emergency rooms, critical care units, and ambulatory clinics, where immediate results are necessary for clinical decision-making.
- Preventive Medicine Focus:A growing emphasis on preventive health and wellness, particularly within aging populations in developed nations, drives demand for complete blood counts as a standard component of health screenings.
Market Restraints
- High Capital Costs:The significant upfront investment required for high-throughput automated hematology analyzers remains a substantial barrier for small independent laboratories and clinics in developing economies.
- Regulatory Scrutiny:Stringent validation requirements under frameworks like the EU's In Vitro Diagnostic Regulation (IVDR) increase development timelines and compliance costs for new device approvals.
- Test Consolidation:Integrated diagnostic platforms that perform multiple tests from a single sample present a substitution threat, potentially diminishing the market for standalone hematocrit-only devices.
Strategic Opportunities
- Digital Health Integration:Developing devices with seamless connectivity to Electronic Health Records (EHR) and Hospital Information Systems (HIS) offers a significant competitive advantage by improving clinical workflow and data management.
- Emerging Market Penetration:Expanding distribution networks into under-served regions in Latin America and Southeast Asia, where healthcare infrastructure is being modernized, presents a major growth frontier.
- Niche Application Development:Targeting specialized applications such as sports medicine for athlete monitoring or veterinary diagnostics for animal health provides opportunities for product differentiation and market expansion.
Industry Challenges
- Data Interoperability:A lack of universal communication protocols across different manufacturers' analyzers creates significant challenges in integrating data from diverse systems into a unified patient record.
- Operator Training:Ensuring consistent and accurate results from point-of-care devices requires extensive training and quality control protocols for non-laboratory personnel who perform the tests.
- Cybersecurity Risks:As diagnostic devices become more connected, ensuring the security of patient data and protecting instruments from cyber threats becomes a critical operational challenge for both vendors and healthcare providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hematocrit Tests Market |
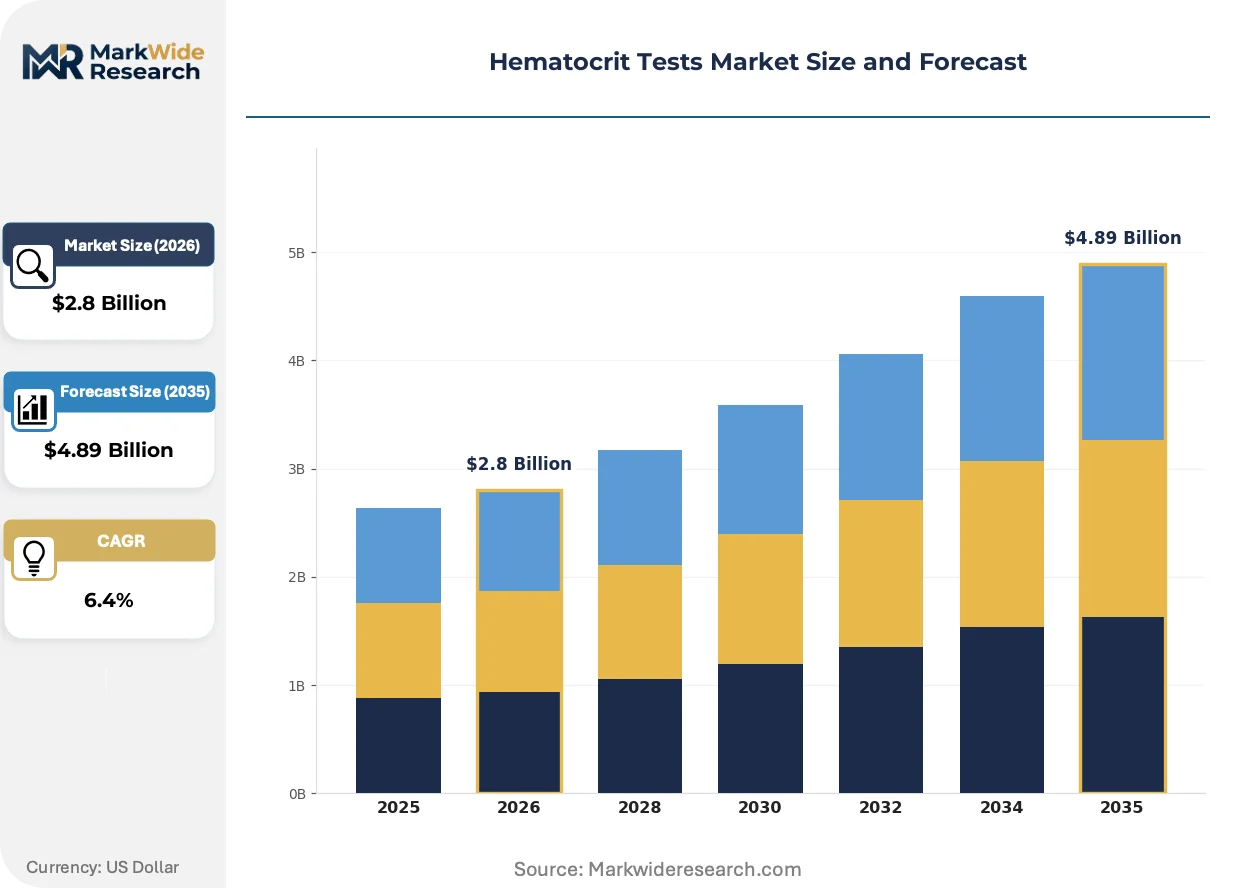
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Hematology Analyzers, Manual Microhematocrit Centrifuges, Point of Care Devices, Digital Hematocrit Readers Application: Blood Disorder Diagnosis, Anemia Screening, Monitoring Hydration Levels, Evaluating Bone Marrow Function End User: Clinical Laboratories, Diagnostic Centers, Blood Banks, Research Institutions Technology: Microcentrifugation, Conductivity-Based Measurement, Optical Detection, Flow Cytometry |
| Companies Covered | Danaher, Sysmex Corporation, Abbott Laboratories, Siemens Healthineers, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Beckman Coulter, Nova Biomedical, Mindray Medical International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hematocrit Tests Market Strategic Shifts & Innovations
The evolution of testing technology is creating a dual-track market. One track prioritizes massive economies of scale in centralized labs, while the other focuses on delivering diagnostic capabilities directly to the patient's side, reshaping service models and data flow.
Microfluidic technology enables the creation of compact, portable hematocrit meters that require only a small drop of blood. Emergency departments and outpatient clinics are adopting these devices for rapid diagnostics at the patient's bedside. This technological shift is fragmenting the traditional, centralized laboratory testing model by moving diagnostic capabilities closer to the point of clinical intervention.
Regulations from bodies like China's National Medical Products Administration (NMPA) are prioritizing domestic innovation and creating fast-track approval pathways for locally manufactured medical devices. This policy directly stimulates the growth of Chinese hematology analyzer manufacturers, intensifying competition within the domestic market. International vendors must now navigate this new landscape, often by forming local partnerships or adapting their pricing strategies to compete effectively.
A notable behavioral change is the shift in procurement from outright capital equipment purchases to reagent rental or managed service agreements. This model allows laboratories to avoid large upfront costs by paying on a per-test basis, which includes the instrument, reagents, and service. This trend is most prominent in large hospital systems in North America and Europe seeking to convert capital expenditures into predictable operational budgets.
Hematocrit Tests Market Segmentation
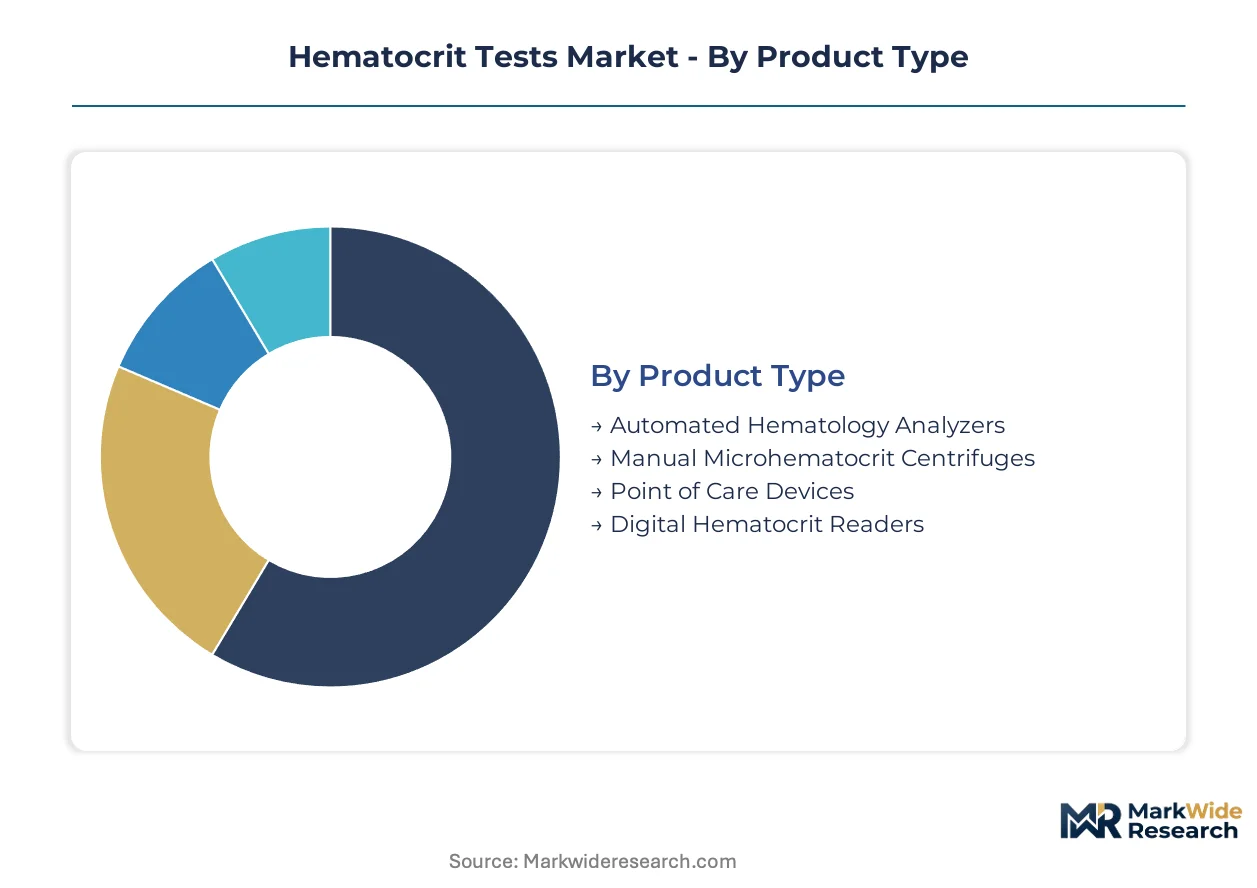
Understanding the hematocrit tests market through its segmentation reveals distinct operational models and technological preferences. This granular view highlights where investment is concentrating and which diagnostic approaches are gaining traction. Analyzing these segments helps stakeholders identify opportunities and competitive pressures across the diagnostic landscape.
Product Type:
The product type segment faces significant substitution pressure from integrated diagnostic platforms that offer broader test panels from a single sample. This threat particularly impacts standalone hematocrit-only devices, pushing manufacturers towards multi-parameter solutions.
- Automated Hematology Analyzers:High-throughput instruments performing complete blood counts, including hematocrit, with minimal manual intervention. Demand concentrates in large clinical laboratories in Germany and Japan, driven by the need for efficiency and standardization in routine screenings.
- Point of Care Devices:Portable instruments designed for rapid hematocrit measurement outside traditional laboratory settings. Their demand is accelerating in emergency rooms and critical care units in the United States, enabling immediate clinical decisions at the patient's bedside.
- Manual Microhematocrit Centrifuges:These devices separate blood components to measure packed cell volume manually. They are common in smaller clinics and developing economies due to lower capital costs.
- Digital Hematocrit Readers:Digital readers provide automated interpretation of microhematocrit tubes, improving accuracy and reducing human error.
Automated Hematology Analyzers retain volume leadership; Point of Care Devices hold the steepest expansion curve.
Application:
Application segments are largely driven by the volume of routine health screenings and chronic disease management protocols. The diagnostic utility of hematocrit tests spans a range of clinical needs, from acute conditions to long-term patient monitoring.
- Anemia Screening:This application involves widespread testing to identify deficiencies in red blood cells, a common global health issue. Demand is particularly high in public health programs across China and India, focusing on maternal and child health.
- Blood Disorder Diagnosis:This segment covers the identification of various hematological conditions, including polycythemia and thalassemia. Clinical laboratories in France and Canada prioritize these tests for specialized patient care and treatment planning.
- Monitoring Hydration Levels:Hematocrit levels can indicate dehydration or overhydration, especially in critical care settings. Emergency departments frequently utilize these measurements for rapid patient assessment.
- Evaluating Bone Marrow Function:Hematocrit tests contribute to the broader assessment of bone marrow health, often alongside other blood parameters.
The largest application area is Anemia Screening, while Monitoring Hydration Levels is gaining traction fastest.
End User:
The end-user segmentation reflects varying operational scales and capital expenditure capacities across different healthcare settings. This diversity influences procurement patterns and technology adoption rates for hematocrit testing solutions.
- Clinical Laboratories:These centralized facilities handle high volumes of patient samples and prioritize automated, high-throughput analyzers. Major hospital systems in the United States and the United Kingdom represent a significant portion of this segment's demand.
- Diagnostic Centers:These independent or network-affiliated centers provide specialized testing services, often focusing on efficiency and rapid turnaround times. Their demand for integrated diagnostic platforms is increasing in urban centers across Brazil and South Africa.
- Blood Banks:Blood banks use hematocrit tests for donor screening and quality control of blood products. Ensuring donor health and product safety are primary drivers for their testing protocols.
- Research Institutions:Academic and pharmaceutical research institutions utilize hematocrit tests in clinical trials and studies of blood-related conditions.
Demand from Clinical Laboratories remains dominant, but Diagnostic Centers show the most dynamic expansion.
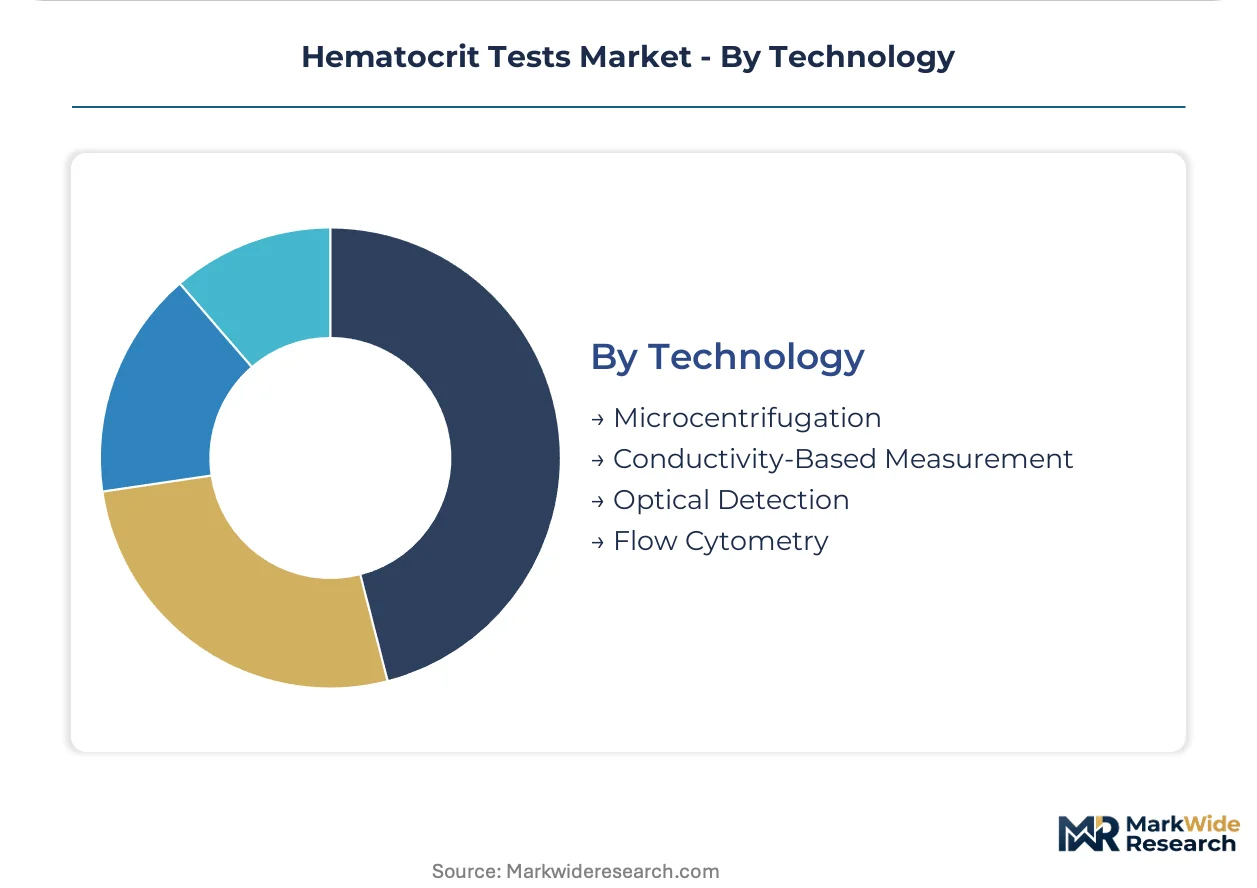
Technology:
Technology segments are influenced by the concentration of specialized manufacturing capabilities and intellectual property. Innovation in this area drives advancements in accuracy, speed, and portability of hematocrit measurement devices.
- Flow Cytometry:This advanced technology measures various cell characteristics, including red blood cell volume, with high precision and speed. Large instrument manufacturers in Germany and Japan are leading its development for comprehensive hematology analysis.
- Microcentrifugation:This traditional method separates blood components using centrifugal force to determine packed cell volume. It remains widely adopted in cost-sensitive markets and smaller diagnostic settings in Mexico and Indonesia due to its simplicity and reliability.
- Conductivity-Based Measurement:This method determines hematocrit by measuring the electrical resistance of a blood sample. It is commonly integrated into point-of-care devices for rapid results.
- Optical Detection:Optical detection technologies use light absorption or scattering to quantify red blood cells. These are often found in automated analyzers for efficiency.
The foundational technology remains Microcentrifugation, while Flow Cytometry is shaping future capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA regulations, prioritizing domestic innovation and fast-track approvals, significantly influence the hematocrit tests market. This policy environment stimulates local manufacturing and intensifies competition within the country. The global market bifurcates between high-throughput centralized laboratories and rapid point-of-care testing, with regional dynamics shaping adoption patterns.
China
Public health programs and chronic disease screening initiatives are driving substantial demand for routine hematocrit tests in China. The NMPA's supportive policies for local manufacturers foster a competitive environment. Major diagnostic instrument production and innovation hubs are emerging in cities like Beijing and Shanghai.
United States
Demand for point-of-care hematocrit devices is accelerating in emergency rooms and critical care units across the United States. US FDA device approval processes ensure stringent quality standards for all diagnostic instruments. Biotech and medical device clusters in regions like Boston and California drive innovation in rapid diagnostic solutions.
Germany
Germany's clinical laboratories prioritize high-throughput automated hematology analyzers for efficiency and standardization in routine screenings. The EU's In Vitro Diagnostic Regulation (IVDR) imposes strict validation requirements for analytical performance. Advanced instrument manufacturing and research facilities are concentrated in Bavaria and North Rhine-Westphalia.
Japan
Japanese clinical laboratories and research institutions demand advanced hematology analysis, particularly flow cytometry technology, for comprehensive diagnostics. The PMDA ensures rigorous quality and safety standards for medical devices. Major R&D centers for diagnostic equipment are located in Tokyo and Osaka, driving technological advancements.
India
Anemia screening, particularly within maternal and child health programs, represents a significant application area in India. The CDSCO regulates medical device approvals, influencing market access for new diagnostic technologies. Growing diagnostic center networks in cities like Hyderabad and Bengaluru increase demand for affordable testing solutions.
Hematocrit Tests Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the market structure for hematocrit tests. This tiered landscape includes diversified diagnostic solution providers, specialized point-of-care device manufacturers, and traditional laboratory instrument companies. Key archetypes include global diagnostic conglomerates and agile technology innovators. Digital health integration and emerging market penetration represent dominant competitive moves for market participants.
On the integrated solutions tier, Sysmex Corporation and Abbott Laboratories exemplify companies with extensive portfolios. Sysmex Corporation anchors high-throughput laboratory environments with its advanced hematology analyzers. Abbott Laboratories occupies a position in decentralized testing, leveraging its broad point-of-care diagnostic lineup. Siemens Healthineers also sits within the integrated solutions archetype, offering comprehensive diagnostic platforms for clinical laboratories globally.
| Leading Market Players |
|---|
| Danaher |
| Sysmex Corporation |
| Abbott Laboratories |
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Beckman Coulter |
| Nova Biomedical |
| Mindray Medical International Limited |
| Others |
Cost & Logistics Intelligence
Average lead times for advanced hematology analyzers, often exceeding 6-8 months, directly influence procurement strategies and vendor pricing power across global healthcare systems.
Pricing Analysis
Price variations across Germany and India reflect differing healthcare budgets and technology adoption rates. Pricing models increasingly shift towards reagent rental or managed service agreements, especially for high-throughput automated analyzers in North America and Europe. Price differentiation stems from automation level, digital integration capabilities, and regulatory compliance with standards like the EU IVDR. Substitution pressure from integrated diagnostic platforms creates downward pricing pressure on standalone hematocrit-only devices. Smaller clinics and developing economies remain highly price-sensitive, often opting for manual microhematocrit centrifuges.
Supply Chain Analysis
Inventory buffers for critical components like microfluidic chips are strategically maintained by major manufacturers in Germany and Japan. Geographic supply concentration centers on manufacturing hubs in China, Germany, and Japan for various device types. Raw material dependencies include specialized optical sensors, microfluidic components, and diagnostic reagents. Single-source vulnerability for advanced sensor technology poses a structural risk to device production. Distribution runs through direct sales teams for large hospital systems and regional distributor networks for smaller diagnostic centers in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hematocrit tests market is undergoing high-growth disruption, driven by the rapid expansion of point-of-care diagnostics.
For Market Incumbents: Secure existing market share by aggressively investing in digital health integration capabilities for seamless EHR/HIS connectivity. Expand automation portfolios to counter the threat of test consolidation from integrated diagnostic platforms. Prioritize R&D into AI-powered diagnostic algorithms to enhance accuracy and reduce operator intervention. Form strategic partnerships to navigate complex regulatory landscapes, especially NMPA policies in China.
For New Entrants and Emerging Players: Lead with niche application development, targeting specialized segments like sports medicine or veterinary diagnostics. Focus on cost-effective, portable microfluidic devices to penetrate underserved regions in Latin America and Southeast Asia. Emphasize simplified operator training and robust quality control protocols for non-laboratory personnel. Leverage rapid approval pathways for innovative point-of-care solutions in specific geographies.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger diagnostic conglomerates seeking to divest non-core traditional laboratory instrument lines. Long-term viability is supported by sustained demand from preventive medicine and chronic disease management over the next decade. Identify agile point-of-care device manufacturers with strong intellectual property in microfluidics or advanced connectivity solutions. The signal to watch is increased M&A activity for companies demonstrating robust digital integration and NMPA approvals.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch | Introduces next-generation microfluidic POC device with enhanced connectivity for US emergency rooms. |
| Strategic Partnership | Collaborates with local Chinese manufacturers for NMPA-approved products, intensifying domestic competition. |
| Platform Integration | Develops seamless data integration with Electronic Health Records, improving clinical workflow for hospitals. |
| Geographic Expansion | Establishes distribution networks in Latin America and Southeast Asia, penetrating emerging markets. |
| Service Model Shift | Offers reagent rental agreements, reducing capital expenditure for large hospital systems in Europe. |
Research Approach
Operator-level perspectives from clinical laboratory directors, emergency room physicians, diagnostic center managers, and medical device engineers anchored the qualitative base. Primary interviews were combined with extensive secondary validation from sources including FDA approval databases, EMA guidelines, NMPA policy documents, and industry association reports. This approach facilitated both bottom-up market sizing and top-down validation against established industry benchmarks.
Sensitivity analysis evaluated the impact of varying regulatory approval timelines and healthcare expenditure trends on market trajectory. The analytical framework modeled market dynamics across the analysis window, segmenting by product type, application, end user, technology, and regional healthcare spending. Compound annual growth rates were derived from historical growth rates and projected technological advancements, with point-of-care device adoption rates serving as key forecast inputs.
Underlying assumptions cover stable regulatory environments and consistent healthcare policy, with deviation risk concentrated in unforeseen technological breakthroughs or major public health crises. Forecasts reflect these assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
UAE Clinical Laboratory Services Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Pathology Services Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
Clinical Laboratory Services Market
Laboratory Services
Autosampler Vials Market