
 Global Medical Laboratories Market | 2026-2036
Global Medical Laboratories Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Laboratories Market Foresight
The direct-to-physician distribution channel is narrowing as hospital systems and integrated delivery networks consolidate purchasing power across broader geographic footprints. Quest Diagnostics leverages its national logistics network to sustain same-day turnaround in metropolitan hubs. Laboratory Corporation of America anchors its position through specialized oncology and companion diagnostic portfolios. Siemens Healthineers competes by bundling imaging and laboratory informatics into unified enterprise contracts.
Medical laboratories comprise facilities and equipment dedicated to analyzing biological specimens through chemical, hematological, microbiological, and molecular methods, typically processing samples at throughput rates exceeding 1,000 tests per hour on automated analyzer platforms to inform clinical diagnosis and treatment selection. The primary commercial purpose centers on converting raw biological material into standardized, reproducible diagnostic data that physicians use to triage patients, monitor chronic conditions, and guide therapeutic decisions. Molecular diagnostics equipment commands premium positioning as oncology and genetic testing applications expand, while clinical chemistry analyzers represent the mature volume base where margin compression is most acute. Immunoassay analyzers occupy the fastest-growing intermediate tier, driven by infectious disease surveillance and endocrinology panels in both public health labs and private diagnostic centers.
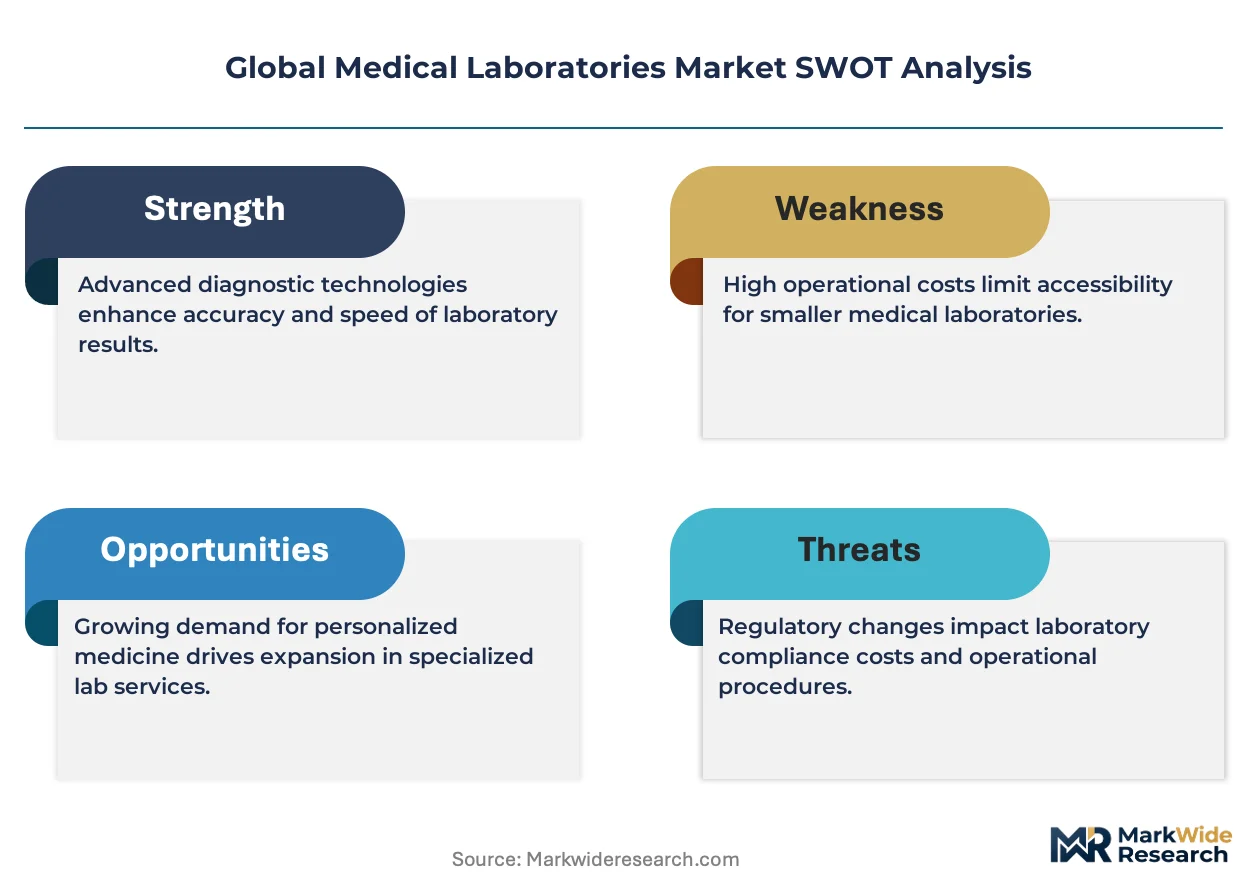
FDA oversight through CLIA and the evolving LDT framework shapes capital allocation toward validated, high-complexity testing platforms, while the EU In Vitro Diagnostic Regulation is forcing manufacturers to resubmit technical documentation for CE-marked devices sold across European member states. The EMA's parallel engagement with companion diagnostic co-development requirements is tightening the linkage between pharmaceutical trials and laboratory assay qualification. Stakeholders must monitor how reimbursement policy for next-generation sequencing panels evolves relative to traditional single-analyte testing, as this divergence will determine which technology segments attract sustained instrumentation investment.
Market Dynamics
Hospital system consolidation is compressing the number of independent purchasing entities while simultaneously expanding the minimum service-menu breadth required to win network contracts, fundamentally restructuring how laboratory vendors compete for volume.
Growth Catalysts
- CLIA High-Complexity Certification:The FDA's tightening quality benchmarks for molecular diagnostics are accelerating capital flows toward validated testing platforms that can process oncology and genetic panels at scale.
- Companion Diagnostic Co-Development:The EMA's parallel engagement with pharmaceutical trials is tightening assay qualification requirements, creating dedicated revenue streams for laboratories positioned early in drug development pipelines.
- Outpatient Diagnostic Migration:United States health systems are centralizing laboratory infrastructure to capture diagnostic volume shifting from inpatient to ambulatory settings, driving equipment refresh cycles.
Market Restraints
- Reagent Supply Concentration:Critical consumables for immunoassay and molecular platforms originate from a narrow supplier base concentrated in Germany and the United States, exposing operations to single-source disruption risk.
- EU IVDR Technical Documentation Resubmission:European manufacturers face extended validation timelines and elevated compliance costs as previously CE-marked devices require renewed conformity assessment under the 2017 regulation.
- Margin Compression in Clinical Chemistry:Automated analyzers for routine biochemistry panels operate in oversaturated segments where pricing power has eroded due to commoditized test menus and excess installed base capacity.
Strategic Opportunities
- India's Diagnostic Network Expansion:Tier-2 and tier-3 cities present underpenetrated demand for standardized laboratory services as CDSCO streamlines IVD import registration and domestic manufacturing incentives deepen.
- Next-Generation Sequencing Reimbursement Divergence:Laboratories that secure favorable coverage determination for multi-gene oncology panels will capture instrumentation investment migrating away from single-analyte platforms.
- AI-Assisted Pathology Integration:Convergence of digital slide scanning and machine learning classification is opening service-line extensions in histopathology where manual review bottlenecks constrain throughput.
Industry Challenges
- Molecular Diagnostics Talent Scarcity:Qualified personnel for complex assay validation and quality control remain concentrated in metropolitan hubs, limiting expansion into secondary markets.
- Legacy LIS Integration Complexity:Hospital laboratories face prolonged implementation timelines when connecting new analyzer platforms to entrenched laboratory information systems lacking modern interoperability architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Laboratories Market |
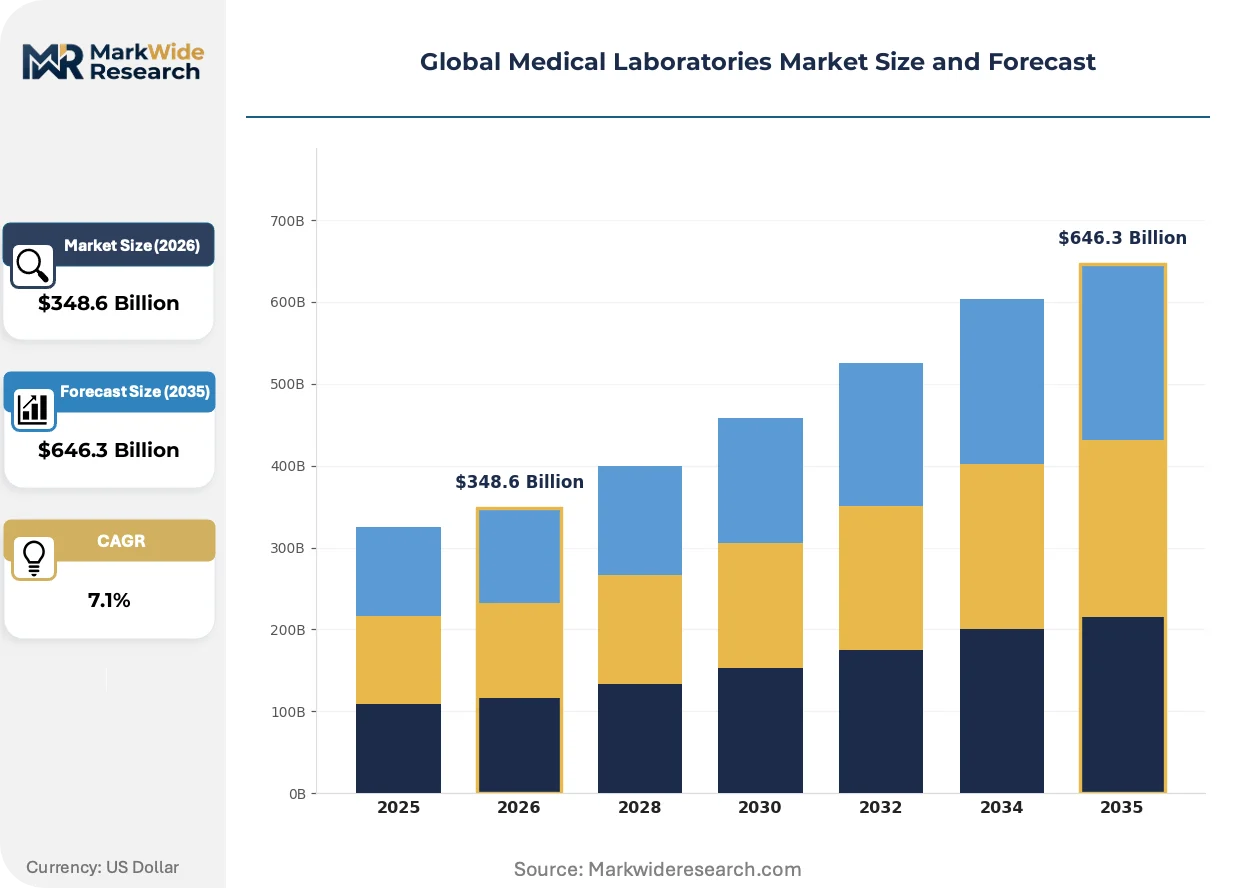
| Market Size in 2026 | $348.6 Billion |
| Market Size in 2035 | $646.3 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Chemistry Analyzers, Hematology Analyzers, Immunoassay Analyzers, Molecular Diagnostics Equipment, Microbiology Testing Devices Therapy Area: Oncology, Infectious Diseases, Cardiovascular Disorders, Endocrinology, Genetic Testing End User: Public Health Labs, Private Diagnostic Centers, Research Institutes, Blood Banks, Forensic Labs Technology: Automation Systems, Point-of-Care Testing, Next-Generation Sequencing, Polymerase Chain Reaction, Mass Spectrometry |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers, Danaher Corporation, Thermo Fisher Scientific, Becton Dickinson and Company, GE HealthCare, Quest Diagnostics, Laboratory Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Laboratories Market Shifts & Advancements
Automation architectures and regulatory frameworks are simultaneously evolving, forcing laboratories to synchronize capital planning with compliance roadmaps rather than treating these as sequential decisions.
Random-access immunoassay analyzers with continuous loading capability are migrating from batch-processing reference laboratories into mid-volume hospital settings previously served by discrete systems. Community health systems in the United States are adopting these platforms to consolidate infectious disease and endocrinology testing that previously required send-out arrangements. The shift is compressing turnaround times for STAT panels while reducing per-test labor allocation.
The EU In Vitro Diagnostic Regulation is mandating clinical evidence requirements and post-market surveillance protocols that exceed predecessor directive standards. Manufacturers must now submit performance evaluation reports with patient-level data, extending time-to-market for novel biomarker assays. Oncology companion diagnostics face the steepest compliance burden, with notified bodies prioritizing reviews for tests linked to approved therapeutics.
Integrated delivery networks are consolidating purchasing decisions across multi-state footprints, displacing the traditional direct-to-physician distribution channel. Hospital systems now negotiate enterprise contracts covering chemistry, immunoassay, and molecular platforms simultaneously, bundling instrumentation, consumables, and informatics into multi-year agreements. This concentration is most pronounced in the United States, where the largest fifteen health systems control an expanding share of total diagnostic spend.
Global Medical Laboratories Market Segmentation
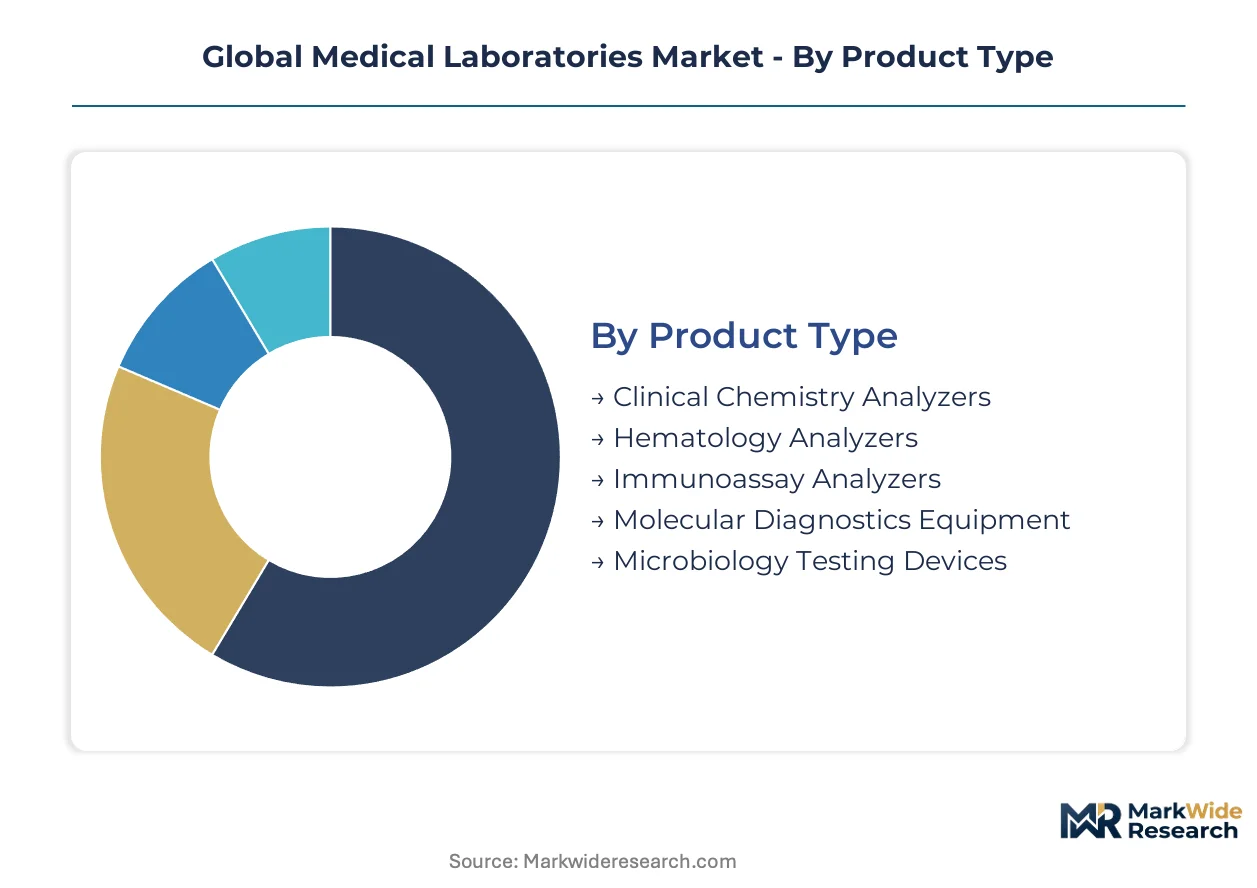
Laboratory equipment purchasing decisions stratify across technology maturity, therapeutic specialization, and operational scale, with each dimension commanding distinct vendor engagement models and capital deployment cycles. Understanding these segment boundaries clarifies where margin compression intensifies versus where premium positioning persists.
Product Type:
Mature automated platforms anchor routine diagnostic throughput while emerging molecular systems capture oncology and genetic testing expansion.
- Clinical Chemistry Analyzers:These high-throughput systems process electrolyte, enzyme, and metabolite panels at rates exceeding 1,000 tests per hour on discrete or integrated modular architectures. Demand concentrates in United States hospital consolidation projects where health systems standardize biochemistry infrastructure across merged facilities, though reimbursement pressure on routine panels constrains pricing power.
- Molecular Diagnostics Equipment:Platforms for nucleic acid amplification, hybridization, and sequencing support oncology companion diagnostics and hereditary disease screening with complex assay menus requiring CLIA high-complexity certification. United States academic medical centers and integrated delivery networks drive capital allocation here as FDA-validated panels expand coverage determinations for precision oncology.
- Hematology Analyzers:Automated cell counters and coagulation systems deliver complete blood count and differential diagnostics for emergency departments and outpatient clinics.
- Immunoassay Analyzers:Random-access systems with continuous loading capability migrate from reference laboratories into mid-volume hospital settings for infectious disease and endocrinology surveillance.
- Microbiology Testing Devices:Automated culture systems and antimicrobial susceptibility platforms accelerate pathogen identification in public health surveillance networks.
Clinical chemistry analyzers retain volume leadership; molecular diagnostics equipment holds the steepest expansion curve.
Therapy Area:
Oncology and infectious disease applications concentrate instrumentation investment where reimbursement and public health funding diverge most sharply.
- Oncology:Companion diagnostic development pipelines require laboratories to qualify assays alongside pharmaceutical trials, creating dedicated revenue streams for high-complexity molecular platforms. United States integrated delivery networks prioritize oncology menu breadth when consolidating laboratory contracts, as precision therapeutic selection depends on timely biomarker turnaround.
- Infectious Diseases:Respiratory, sexually transmitted, and hospital-acquired infection panels drive immunoassay and PCR platform utilization across emergency departments and ambulatory settings. Public health laboratories in Germany and the United States anchor demand here as surveillance mandates expand pathogen genomic tracking capabilities.
- Cardiovascular Disorders:Lipid panels, troponin assays, and coagulation monitoring support emergency department triage and chronic disease management in hospital-based laboratories.
- Endocrinology:Thyroid, diabetes, and reproductive hormone testing migrates from send-out reference laboratories into integrated hospital platforms with random-access immunoassay capability.
- Genetic Testing:Carrier screening, prenatal diagnostics, and pharmacogenomic panels require sequencing infrastructure with specialized variant interpretation workflows.
Infectious diseases commands installed base scale; oncology captures the fastest-growing trajectory.
End User:
Consolidated hospital systems and independent diagnostic chains operate on divergent procurement timelines and service-menu requirements.
- Public Health Labs:Government-funded facilities prioritize surveillance infrastructure for infectious disease and environmental monitoring with extended equipment depreciation schedules. India's tier-2 and tier-3 city network expansion under CDSCO streamlined registration is opening procurement opportunities for standardized analyzer platforms.
- Private Diagnostic Centers:Profit-oriented chains compete on turnaround time and specialized menu breadth, driving refresh cycles for automation systems that reduce labor cost per test. United States metropolitan hubs concentrate multi-site purchasing power as regional chains consolidate.
- Research Institutes:Academic and translational research facilities require flexible platforms supporting protocol development and biomarker discovery with less emphasis on regulatory validation.
- Blood Banks:Transfusion medicine and donor screening operations demand high-reliability immunohematology and infectious disease testing with continuous throughput.
- Forensic Labs:DNA profiling and toxicology applications require specialized sample handling and chain-of-custody documentation systems with extended analytical timelines.
Private diagnostic centers retain volume leadership; public health labs hold the steepest expansion curve.
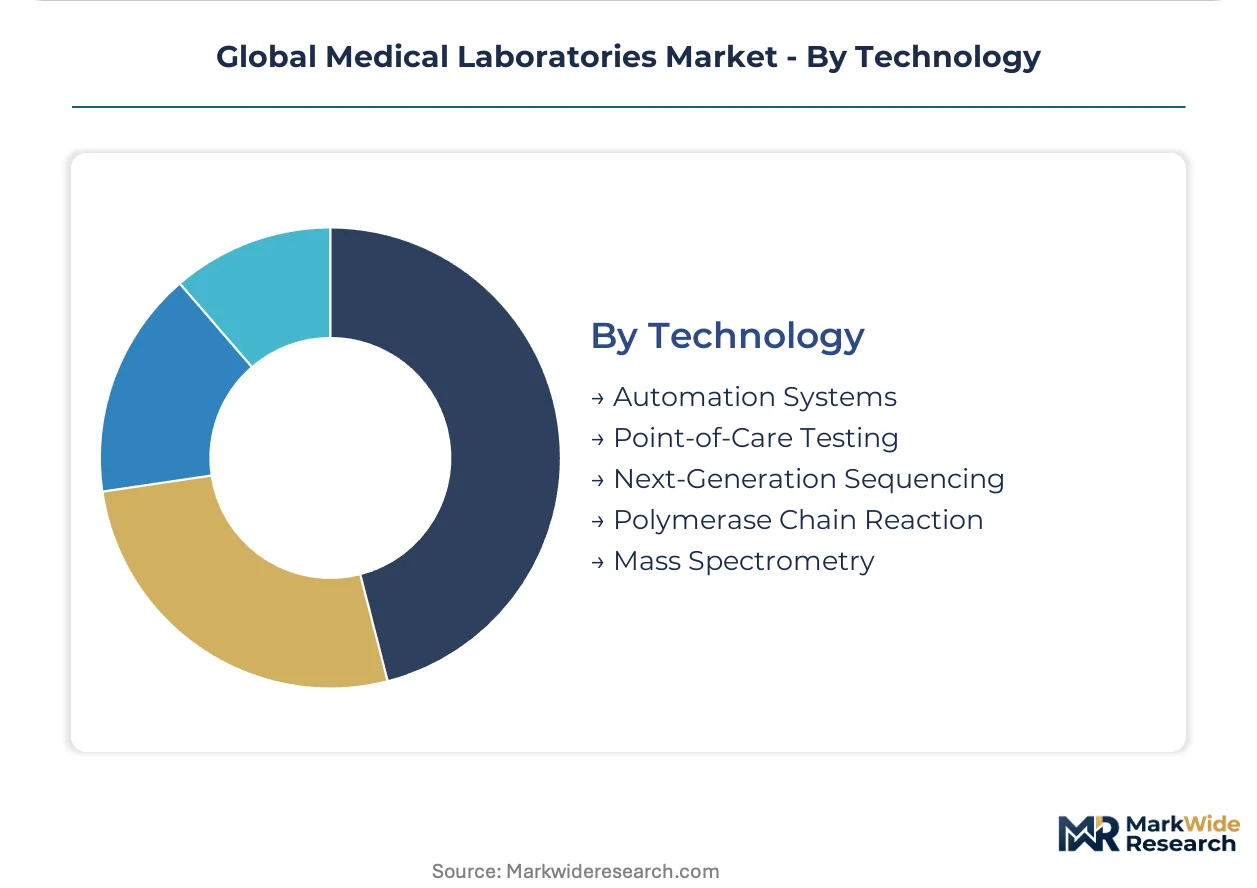
Technology:
Automation density and decentralization potential determine where capital flows concentrate across laboratory and near-patient settings.
- Automation Systems:Total laboratory automation encompassing pre-analytical processing, analytical platforms, and post-analytical storage reduces manual touchpoints and error rates in high-volume hospital laboratories. United States health system consolidation projects drive enterprise contracts bundling chemistry, immunoassay, and hematology modules with unified informatics.
- Next-Generation Sequencing:Massively parallel sequencing platforms enable multi-gene oncology panels and rare disease screening with throughput scaling from targeted panels to whole exomes. Reimbursement divergence between NGS and single-analyte testing is determining where instrumentation investment migrates in United States and European markets.
- Point-of-Care Testing:Decentralized devices for glucose, cardiac markers, and infectious disease antigens enable bedside and clinic-based diagnostics with immediate result availability.
- Polymerase Chain Reaction:Established nucleic acid amplification technology supports infectious disease and genetic testing with moderate capital requirements and established regulatory pathways.
- Mass Spectrometry:High-sensitivity platforms for therapeutic drug monitoring, toxicology, and newborn screening require specialized operator expertise and maintenance infrastructure.
Automation systems retain volume leadership; next-generation sequencing holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European laboratory equipment import flows, while the Trans-Siberian rail corridor links Asian manufacturing clusters to distribution hubs across Eurasia.
United States
Integrated delivery networks consolidate purchasing across multi-state footprints, driving enterprise contracts for chemistry and molecular platforms. FDA CLIA high-complexity certification requirements shape capital allocation toward validated oncology testing systems. The Boston-Cambridge corridor concentrates companion diagnostic development alongside pharmaceutical trial pipelines.
Germany
Public health laboratories anchor infectious disease surveillance infrastructure with extended equipment depreciation schedules. EU IVDR technical documentation resubmission mandates extend validation timelines for previously CE-marked devices. The Rhine-Ruhr metropolitan region hosts centralized diagnostic processing for health system networks.
India
Tier-2 and tier-3 cities present underpenetrated demand for standardized laboratory services as outpatient diagnostic migration accelerates. CDSCO streamlines IVD import registration while domestic manufacturing incentives deepen under PLI scheme provisions. Hyderabad and Bengaluru clusters concentrate molecular diagnostics talent and assay development capabilities.
China
Hospital system consolidation drives centralized laboratory infrastructure investment across provincial health networks. NMPA oversight of high-complexity testing platforms tightens quality benchmarks for genetic and oncology panels. The Yangtze River Delta anchors automated analyzer manufacturing and consumables production.
Japan
Aging demographics expand chronic disease monitoring demand through hospital-based and clinic laboratory networks. PMDA engagement with companion diagnostic co-development tightens assay qualification alongside pharmaceutical trials. The Kanto region around Tokyo concentrates reference laboratory capacity and specialized testing menus.
Global Medical Laboratories Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagents and consumables. The vendor base stratifies between multinational conglomerates bundling instrumentation, informatics, and service contracts and mid-scale regional chains competing on turnaround time. Three archetypes dominate: diversified healthcare conglomerates with imaging-laboratory convergence strategies; pure-play diagnostic service networks leveraging national logistics footprints; and specialized oncology-focused laboratories anchoring companion diagnostic pipelines. M&A activity concentrates on consolidating regional service networks, while strategic partnerships link assay developers to pharmaceutical trial sponsors.
Among United States-based service networks, Quest Diagnostics and Laboratory Corporation of America occupy positions as scale-driven anchors for outpatient diagnostic volume. Siemens Healthineers represents the diversified conglomerate archetype with unified enterprise contracting models. These three entities exemplify distinct competitive vectors: logistics density, specialized menu breadth, and cross-modality bundling respectively.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Becton Dickinson and Company |
| GE HealthCare |
| Quest Diagnostics |
| Laboratory Corporation of America |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta anchors global automated analyzer manufacturing capacity, and its scale dynamics translate directly into downstream pricing leverage for mid-tier clinical chemistry platforms. Reagent suppliers in Germany and the United States extract premium positioning through proprietary consumable lock-in, while hospital system consolidation compresses vendor pricing power through enterprise volume aggregation.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with three-tier pricing separating CLIA high-complexity molecular platforms from standard immunoassay systems and economy-grade chemistry analyzers. Certification grade and volume scale drive price differentiation, with FDA-validated oncology panels commanding substantial premiums over research-use-only alternatives. Pricing pressure stems from commoditized biochemistry menus where excess installed base capacity erodes margins. Independent diagnostic centers exhibit highest price sensitivity, while integrated delivery networks leverage multi-year enterprise contracts to secure favorable terms.
Supply Chain Analysis
Upstream feedstock dependencies center on precision optical components from Germany, semiconductor-grade sensors from Taiwan, and specialty reagent chemistries from the United States. Critical consumables for PCR and immunoassay platforms draw from concentrated supplier bases concentrated in Bavaria and Massachusetts manufacturing clusters. Single-source vulnerability for proprietary reagent cartridges poses structural risk to operational continuity. Distribution runs through regional logistics hubs serving consolidated hospital networks, with same-day metropolitan coverage becoming table stakes for vendor selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, propelled by outpatient diagnostic migration from inpatient settings into ambulatory networks. Precision oncology and companion diagnostic co-development pipelines are accelerating capital deployment toward validated molecular platforms.
For Market Incumbents: Harden CLIA high-complexity certification moats through accelerated assay validation pipelines for oncology companion diagnostics. Consolidate reagent supply security through captive manufacturing partnerships in Germany or backward integration into specialty chemistry production. Emerging platform competitors and FDA LDT framework evolution threaten established margin structures.
For New Entrants and Emerging Players: India's tier-2 and tier-3 cities present underpenetrated demand for standardized laboratory infrastructure as CDSCO streamlines IVD import pathways. Target public health laboratory contracts in secondary municipalities where molecular diagnostics talent scarcity has limited incumbent penetration. Pursue asset-light distribution partnerships with domestic diagnostic chains rather than capital-intensive direct sales buildout.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital system purchasing concentration will favor scaled service networks with national logistics density. Acquisition targets should exhibit specialized oncology menu breadth or established companion diagnostic pharmaceutical partnerships. Monitor NGS reimbursement divergence signals as the inflection indicator for instrumentation investment migration.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Certification Investment | FDA validation unlocks precision oncology reimbursement and pharmaceutical trial partnerships. |
| Companion Diagnostic Co-Development Agreement | EMA and PMDA alignment tightens assay qualification alongside therapeutic pipelines. |
| Enterprise Contract Consolidation | Multi-state IDN purchasing concentration favors vendors with unified informatics bundling. |
| Reagent Manufacturing Backward Integration | Proprietary consumable supply reduces single-source disruption exposure from German suppliers. |
| AI-Assisted Pathology Platform Launch | Digital slide scanning convergence addresses histopathology throughput bottlenecks in academic medical centers. |
Research Methodology
Operator-level perspectives from laboratory directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and CDSCO import registration data. Bottom-up equipment shipment analysis and top-down health system capital expenditure tracking provided cross-verification.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing around reimbursement policy evolution and regulatory timeline slippage. Segmentation modeling incorporated product type, therapy area, end user category, and technology platform dimensions throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, health system merger pipeline assessment, and molecular diagnostics adoption curve benchmarking.
Practitioners should monitor FDA LDT framework finalization, EU IVDR notified body capacity constraints, and NGS coverage determination divergence for early signals requiring forecast reassessment. Cross-checking against health system capital expenditure disclosures and pharmaceutical companion diagnostic trial announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Assessment Services Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Pathology Services Market
Laboratory Services
Sera and Reagents Market