
 Microbiological Safety Cabinets Market | 2026-2036
Microbiological Safety Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Microbiological Safety Cabinets Market Outlook
Chinese cabinet producers is realigning output toward HEPA-certified systems for export markets. Thermo Fisher Scientific Inc. leverages its global service network to anchor long-term contracts with academic medical centers. Labconco specializes in custom containment solutions for biodefense applications. Esco Micro Pte. Ltd. dominates Southeast Asian public health procurement through localized manufacturing.
Microbiological safety cabinets are enclosed ventilated workstations that maintain personnel, product, and environmental protection through unidirectional HEPA-filtered airflow at velocities between 0.25 and 0.5 m/s; their primary purpose is to contain biohazardous aerosols during cell culture, pathogen manipulation, and sterile compounding operations. Biosafety cabinets account for the largest installed base due to mandatory BSL-2 and BSL-3 containment protocols, while isolators represent the fastest-expanding segment as pharmaceutical aseptic processing shifts toward absolute barrier technologies. Laminar flow cabinets retain stable demand from hospital pharmacy compounding but face margin compression compared to containment-grade alternatives.
FDA 21 CFR Part 211, OSHA Bloodborne Pathogens Standard, and NSF/ANSI 49 certification requirements collectively shape product specifications and procurement eligibility for cabinet vendors serving the United States market. The EU MDR and EMA Annex 1 revisions on sterile manufacturing push European pharmaceutical buyers toward continuous monitoring and isolator-based containment architectures. Stakeholders must track evolving harmonization gaps between NSF/ANSI 49 and EN 12469 standards as dual-certification burdens reshape supplier competitiveness.
Market Dynamics
HEPA filtration certification requirements and biosafety level containment mandates are compressing procurement cycles while elevating technical barriers to cabinet qualification across pharmaceutical and clinical laboratory end-uses.
Growth Catalysts
- BSL-3 Expansion:National biodefense programs and emerging infectious disease research are accelerating demand for Class III glovebox cabinets with absolute containment.
- EU MDR Sterile Manufacturing:EMA Annex 1 revisions mandate continuous environmental monitoring, forcing pharmaceutical manufacturers toward isolator-based aseptic processing architectures.
- Cell Therapy Manufacturing:Autologous and allogeneic cell therapy production requires ISO 14644-1 Grade A environments, driving specification upgrades in contract development and manufacturing organizations.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 316L stainless steel price swings compress margins for custom containment fabricators serving academic medical centers.
- Certification Bottleneck:NSF/ANSI 49 and EN 12469 dual-certification testing creates 12-18 month qualification timelines that freeze vendor competitive entry.
- Isolator Substitution:Restricted access barrier systems and closed isolator technologies are displacing open-front biosafety cabinets in commercial pharmaceutical aseptic filling lines.
Strategic Opportunities
- India CDMO Buildout:CDSCO manufacturing license expansions and PLI scheme incentives for active pharmaceutical ingredients are creating demand for containment infrastructure in Hyderabad and Ahmedabad clusters.
- Real-Time Monitoring Convergence:Integration of particle counters, pressure differential sensors, and cloud-based compliance dashboards is opening premium pricing tiers for connected cabinet systems.
- Biodefense Procurement Channels:Direct government contracting vehicles outside traditional distribution are enabling margin capture for vendors with security clearance and domestic content certification.
Industry Challenges
- Containment Specialist Shortage:Qualified field service engineers capable of HEPA filter certification, airflow velocity mapping, and smoke pattern testing are concentrated among aging technician cohorts in North America and Western Europe.
- Legacy Building Integration:Retrofitting BSL-3 suites into existing hospital infrastructure requires structural reinforcement, dedicated HVAC plant expansion, and redundant power systems that extend project timelines.
- Cross-Border Spare Parts Logistics:Customs delays for critical components including HEPA filter media, sash motors, and pressure sensors disrupt preventive maintenance schedules in import-dependent markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbiological Safety Cabinets Market |
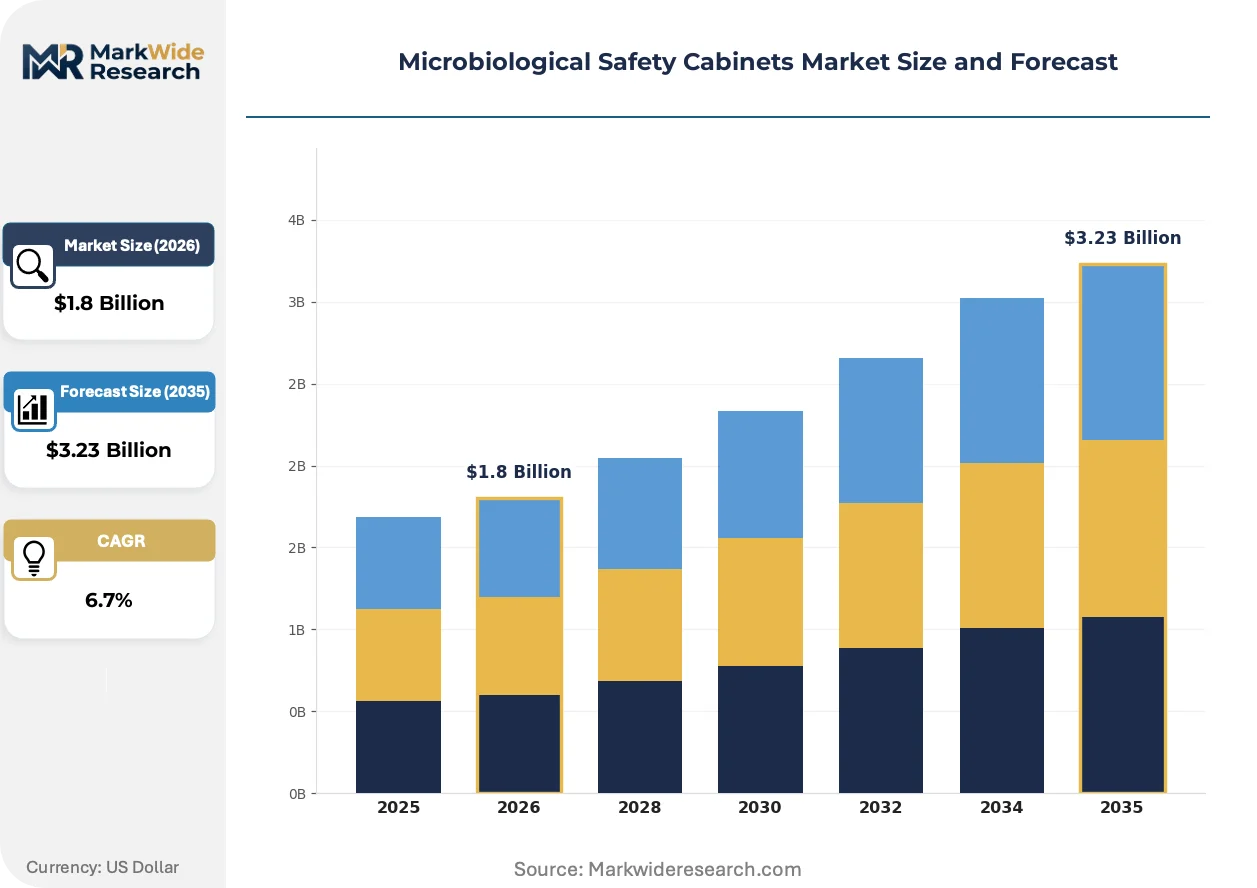
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biosafety Cabinets, Laminar Flow Cabinets, Clean Rooms, Isolators End User: Research Laboratories, Pharmaceutical Companies, Clinical Diagnostics, Biotechnology Firms Technology: HEPA Filters, Ultraviolet Light, Airflow Systems, Containment Features Application: Microbiology Research, Pharmaceutical Development, Pathogen Handling, Tissue Culture |
| Companies Covered | Thermo Fisher Scientific Inc., Labconco, Esco Micro Pte. Ltd., The Baker Company, Kewaunee Scientific, NuAire, Haier Biomedical, Germfree Laboratories, Biobase Biodusty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbiological Safety Cabinets Market Strategic Shifts
Active containment architectures are displacing passive airflow systems as pharmaceutical manufacturers pursue absolute barrier separation and regulatory audit readiness.
Variable air volume sash control systems are absorbing demand from traditional constant-volume designs in high-throughput pharmaceutical quality control laboratories. Merck and Lonza manufacturing sites are specifying these systems to reduce energy consumption and extend HEPA filter service intervals. The technology is absorbing capital allocation that previously funded conventional fixed-speed blower cabinets, compressing the addressable market for entry-level containment products.
EMA Annex 1 2022 revisions on sterile manufacturing are mandating continuous viable and non-viable particle monitoring for Grade A and Grade B environments. Pharmaceutical buyers are retrofitting existing cabinets with integrated environmental monitoring systems or specifying new builds with factory-installed sensor arrays. European contract manufacturing organizations in Germany and Switzerland are responding fastest, with Italian and Spanish facilities trailing by 18-24 months in compliance readiness.
Service contract unbundling is fragmenting traditional equipment-vendor relationships as hospital pharmacy directors separately source HEPA certification, airflow calibration, and decontamination services. Third-party accredited service providers are capturing aftermarket revenue that previously flowed to original equipment manufacturers. This pattern is most visible in United States academic medical centers where procurement departments enforce vendor-neutral maintenance specifications.
Microbiological Safety Cabinets Market Segmentation
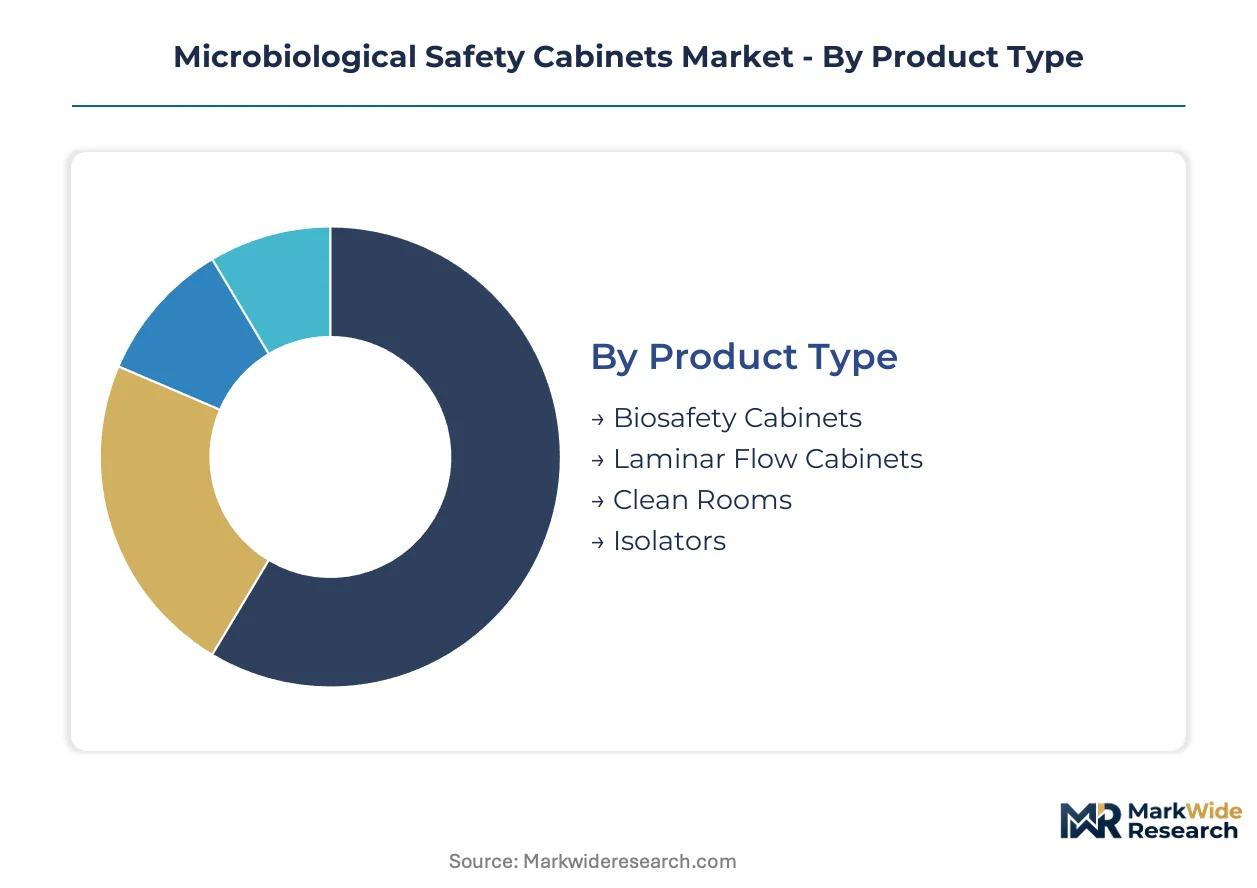
Segmentation in microbiological safety cabinets reflects divergent containment philosophies across research and manufacturing environments. Product specifications, end-user workflows, and regulatory exposure levels create distinct procurement patterns that vendors must address through differentiated positioning.
Product Type:
Buyers in this category select based on containment stringency versus operational accessibility trade-offs.
- Biosafety Cabinets:Enclosed ventilated workstations deploying unidirectional HEPA-filtered airflow at 0.25-0.5 m/s velocities to protect personnel, product, and environment simultaneously. Pharmaceutical manufacturers in Germany and the United States specify Class II Type A2 and B2 configurations under EMA Annex 1 and FDA 21 CFR Part 211 mandates for BSL-2 and BSL-3 protocols.
- Isolators:Absolute barrier systems providing hermetic separation between operator and product through glove ports and transfer hatches. Lonza and Merck manufacturing sites in Switzerland and Ireland are specifying these for aseptic filling lines as EMA Annex 1 2022 revisions mandate continuous environmental monitoring.
- Laminar Flow Cabinets:Product-protection devices supplying filtered air across work surfaces without personnel containment features. Hospital pharmacy compounding operations in academic medical centers retain stable demand despite margin compression versus containment-grade alternatives.
- Clean Rooms:Modular architectural systems achieving ISO 14644-1 classified environments through integrated HVAC and filtration infrastructure. Cell therapy CDMOs in Hyderabad and Ahmedabad clusters are specifying Grade A environments for autologous and allogeneic production.
Volume sits with biosafety cabinets; growth tilts toward isolators.
End User:
Procurement authority and compliance exposure determine specification intensity across customer types.
- Pharmaceutical Companies:Commercial manufacturers facing FDA, EMA, and CDSCO inspections specify certified containment systems with documented qualification protocols. Aseptic processing operations in sterile injectables drive demand for isolator-based architectures with continuous particle monitoring.
- Biotechnology Firms:Cell and gene therapy developers require ISO 14644-1 Grade A environments for patient-specific manufacturing. Contract development organizations in Boston and San Francisco clusters are upgrading from open-front cabinets to restricted access barrier systems.
- Research Laboratories:Academic and government facilities performing BSL-2 and BSL-3 research specify Class II and Class III cabinets under NIH and CDC guidelines. National biodefense programs are accelerating demand for glovebox cabinets with absolute containment.
- Clinical Diagnostics:Hospital laboratories and reference testing facilities process patient specimens under OSHA Bloodborne Pathogens Standard requirements. High-throughput molecular diagnostics operations are specifying variable air volume sash control to reduce energy consumption.
Pharmaceutical companies command the largest contract values; biotechnology firms are expanding most quickly.
Technology:
Performance differentiation concentrates in filtration efficiency and airflow management architectures.
- HEPA Filters:High-efficiency particulate air media rated at 99.97% retention for 0.3 micron particles constitute the core containment mechanism. NSF/ANSI 49 and EN 12469 dual-certification requirements for filter integrity testing create 12-18 month vendor qualification timelines.
- Airflow Systems:Variable air volume designs with sash-position sensors and variable-frequency drive blowers reduce energy consumption and extend filter service intervals. Merck and Lonza quality control laboratories are specifying these over constant-volume alternatives.
- Containment Features:Sash interlocks, negative pressure alarms, and redundant exhaust systems address personnel protection requirements. BSL-3 facilities in national laboratory networks require glove ports and bag-out systems for absolute containment.
- Ultraviolet Light:Germicidal irradiation systems for surface decontamination supplement primary containment in research applications. Integration with programmable cycle controllers supports documented decontamination protocols for regulatory audit readiness.
HEPA filtration anchors installed base; airflow system intelligence is gaining share fastest.
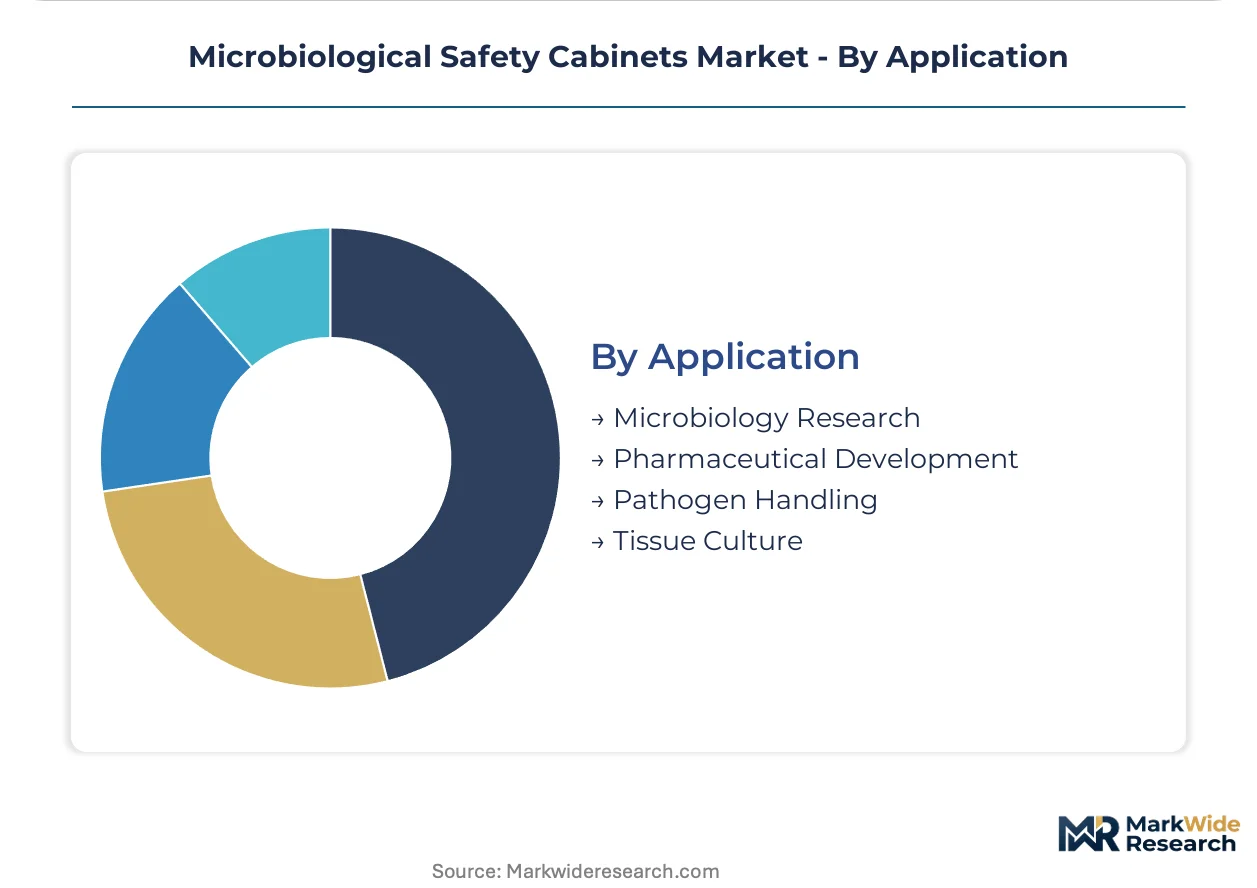
Application:
Biological risk level and sterility requirements dictate cabinet class selection and operational protocols.
- Pharmaceutical Development:Aseptic processing of sterile drug products requires isolator or restricted access barrier system architectures. EMA Annex 1 revisions on continuous monitoring are forcing European manufacturers toward retrofit or replacement cycles.
- Pathogen Handling:Manipulation of Risk Group 2 and 3 microorganisms mandates Class II or Class III biosafety cabinet configurations. Emerging infectious disease research programs are accelerating procurement of absolute containment systems.
- Microbiology Research:General bacteriology and virology operations in academic settings utilize Class II Type A2 cabinets for routine containment. NSF/ANSI 49 certification remains mandatory for federal funding eligibility in United States institutions.
- Tissue Culture:Mammalian cell propagation requires product protection through HEPA-filtered laminar airflow. Stem cell and primary culture applications are driving specification upgrades toward ISO 14644-1 aligned environments.
Microbiology research holds the broadest installed base; pharmaceutical development shows the steepest specification upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grade 304 and 316L stainless steel from Chinese and Indian mills anchors cabinet fabrication costs, with procurement patterns concentrating demand in pharmaceutical manufacturing clusters across five major economies.
United States
FDA 21 CFR Part 211 and OSHA Bloodborne Pathogens Standard mandate NSF/ANSI 49 certification for federal funding eligibility. Thermo Fisher Scientific leverages its domestic service network to anchor long-term contracts with academic medical centers in Boston and San Francisco. National biodefense programs accelerate demand for Class III glovebox cabinets with absolute containment.
Germany
EMA Annex 1 revisions on sterile manufacturing push pharmaceutical manufacturers toward continuous monitoring and isolator-based containment architectures. GMP-aligned requirements concentrate procurement authority in Baden-Württemberg and Bavaria pharmaceutical clusters. Merck and Lonza manufacturing sites specify variable air volume systems to reduce energy consumption.
China
Domestic producers realign output toward HEPA-certified systems for export markets under NMPA quality system regulations. Yangtze River Delta and Pearl River Delta clusters concentrate fabrication capacity for biosafety infrastructure. CDSCO-aligned export specifications drive dual-certification investments for Indian and Southeast Asian market access.
India
CDSCO manufacturing license expansions and PLI scheme incentives for active pharmaceutical ingredients create demand for containment infrastructure. Hyderabad and Ahmedabad CDMO clusters specify ISO 14644-1 Grade A environments for autologous cell therapy production. Localized stainless steel fabrication reduces import dependency for cabinet housings.
Switzerland
Swissmedic sterile manufacturing guidelines and EMA-aligned GMP requirements drive specification intensity in Basel and Zurich pharmaceutical corridors. Lonza manufacturing sites specify isolator-based aseptic processing architectures with continuous particle monitoring. Precision engineering traditions support custom containment fabrication for niche biologics applications.
Microbiological Safety Cabinets Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue connected monitoring and service contract unbundling. The vendor base spans multinational laboratory equipment conglomerates, regional containment specialists, and domestic fabricators serving price-sensitive procurement. Three archetypes dominate: premium-tier integrated system providers, mid-market certification-focused suppliers, and emerging connected-cabinet specialists. Competitive moves concentrate on geographic expansion through localized manufacturing and vertical integration into HEPA filter media production.
Among United States-based laboratory equipment conglomerates, Thermo Fisher Scientific Inc. exemplifies the premium-tier integrated provider archetype through its global service network positioning. Labconco represents the mid-market specialist segment with custom containment capabilities. Esco Micro Pte. Ltd. anchors the emerging-market localization archetype through Southeast Asian manufacturing presence. These three occupy distinct competitive vectors without direct overlap in procurement channels.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Labconco |
| Esco Micro Pte. Ltd. |
| The Baker Company |
| Kewaunee Scientific |
| NuAire |
| Haier Biomedical |
| Germfree Laboratories |
| Biobase Biodusty |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators in Germany and Switzerland anchor premium-tier pricing discipline through captive stainless steel machining capabilities and long-term service bundling. Their ownership structure insulates margin targets from quarterly earnings pressure, reinforcing supply stability for pharmaceutical buyers facing EMA Annex 1 compliance deadlines.
Pricing Analysis
Warranty and service-bundling configurations split sharply between OEM-integrated packages and third-party unbundled offerings. Three-tier pricing structure across premium, standard, and economy levels reflects NSF/ANSI 49 certification grade and HEPA filter integrity testing depth. Pricing pressure stems from stainless steel input volatility compressing margins for custom containment fabricators. Academic medical centers exhibit highest price sensitivity due to grant-funded procurement constraints, while pharmaceutical manufacturers prioritize qualification speed over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from FDA-inspected pharmaceutical buyers require qualified HEPA filter media from both Chinese and German suppliers. Grade 304 and 316L stainless steel draws from Chinese and Indian mills, while sash motors and pressure sensors rest on Taiwanese and Japanese component specialists. Single-source vulnerability concentrates in specialized HEPA glass fiber media production. Distribution runs through regional equipment distributors with field service capabilities, bypassing direct manufacturer relationships in price-sensitive procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification bottleneck pressures and 12-18 month dual-qualification timelines are forcing sub-scale fabricators toward distressed exit scenarios, creating consolidation runway for well-capitalized incumbents.
For Market Incumbents: Hedge against isolator substitution by acquiring real-time monitoring software capabilities and expanding variable air volume system portfolios. Lock in multi-year service contracts with academic medical centers before third-party accredited providers capture aftermarket revenue. Backward integration into HEPA filter media production reduces exposure to cross-border spare parts logistics disruptions.
For New Entrants and Emerging Players: Cloud-connected environmental monitoring dashboards offer the clearest technology-first wedge into European contract manufacturing organizations trailing EMA Annex 1 compliance readiness. Target Italian and Spanish pharmaceutical facilities with retrofit sensor arrays and factory-installed connected cabinet systems. Pursue direct government biodefense contracting channels outside traditional distribution to bypass incumbent service network advantages.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market certification-focused suppliers in Germany and Switzerland with existing EN 12469 qualification infrastructure. Long-term viability centers on vendors capable of spanning both open-front biosafety cabinet replacement cycles and isolator-based aseptic processing migration. Watch for CDSCO manufacturing license expansion announcements in Hyderabad and Ahmedabad as inflection indicators for Indian CDMO containment infrastructure buildout.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Monitoring Integration | Cloud-based compliance dashboards command premium pricing from EMA-aligned pharmaceutical manufacturers. |
| HEPA Filter Media Backward Integration | In-house production of glass fiber media reduces customs delay exposure for preventive maintenance schedules. |
| Biodefense Direct Contracting | Security clearance and domestic content certification unlock government procurement vehicles outside distributor channels. |
| Variable Air Volume System Expansion | Merck and Lonza specifications absorb capital allocation from fixed-speed blower cabinet alternatives. |
| Indian CDMO Localization | Hyderabad and Ahmedabad manufacturing presence captures PLI scheme-driven containment infrastructure demand. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with containment equipment procurement managers, biomedical engineering directors, field service technicians, and GPO contracts specialists combined with FDA 510(k) databases, EMA GMP inspection records, NSF/ANSI certification listings, and import-export trade statistics. Bottom-up vendor shipment tracking and top-down pharmaceutical capital expenditure analysis provided triangulation validation across the analysis window.
Granularity-level modeling deployed product-type, end-user, technology, and application dimensions at country-level resolution throughout the forecast period. CAGRs derived from weighted average of historical shipment growth, regulatory mandate implementation timelines, and replacement cycle assumptions. Cell therapy manufacturing expansion and BSL-3 biodefense program acceleration served as industry-specific demand inputs alongside stainless steel price index trajectories.
Several conditions sit outside the modeled scope, including unannounced regulatory harmonization between NSF/ANSI 49 and EN 12469 standards, and sovereign biodefense budget reallocation events. Forecasts reflect documented assumptions regarding EMA Annex 1 compliance adoption curves and CDSCO manufacturing license expansion velocity. A model refresh is warranted upon material change in HEPA filter media trade flow patterns or stainless steel input cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Medical Cold Storage Market
Healthcare Equipment
Specialty Medical Chairs Market
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
Emergency Hospital Beds Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Medical Waste Supervision Solution Market
Healthcare Equipment
Medical Chairs Market
Healthcare Equipment
US Medical Cold Storage Market