
 Central Lab Market | 2026-2036
Central Lab Market Size, Share, and Industry Trends Forecast 2026-2036
Central Lab Market Intelligence
EU MDR is pivoting the cost-of-entry calculus for central labs serving European trial sponsors, as notified body scrutiny of diagnostic device conformity intensifies. Labcorp leverages its captive courier network to sustain same-day specimen integrity across North American investigator sites. Eurofins Scientific anchors its competitive position through specialized bioanalytical capabilities in complex biologics testing. ICON plc differentiates by integrating central lab data directly into its clinical trial management platforms.
A central lab functions as a dedicated testing facility that standardizes biomarker analysis, clinical chemistry, and pathology services across geographically dispersed clinical trial sites, typically operating under GLP and GCLP protocols with temperature-controlled logistics chains maintaining specimen stability from collection through analytical reporting. Its primary commercial purpose is to eliminate inter-site analytical variability that would otherwise compromise regulatory submission data integrity. Immunoassay analyzers occupy the largest installed base among product categories, though next-generation sequencing represents the fastest-expanding technology segment as precision medicine protocols proliferate. Contract research organizations now represent the most concentrated end-user channel, driven by sponsor preferences for bundled trial execution.
FDA bioresearch monitoring inspections, EMA good clinical laboratory practice guidelines, and ISO 15189 medical laboratory accreditation collectively determine which central labs qualify for multinational trial participation, with regulatory non-conformance triggering immediate site disqualification and protocol amendment costs. The FDA's risk-based inspection scheduling prioritizes labs supporting pivotal registration studies, concentrating compliance investment among vendors pursuing late-phase sponsor contracts. Stakeholders must monitor evolving regional requirements for direct-to-patient testing models, as decentralized trial architectures challenge traditional hub-and-spoke central lab economics.
Market Dynamics
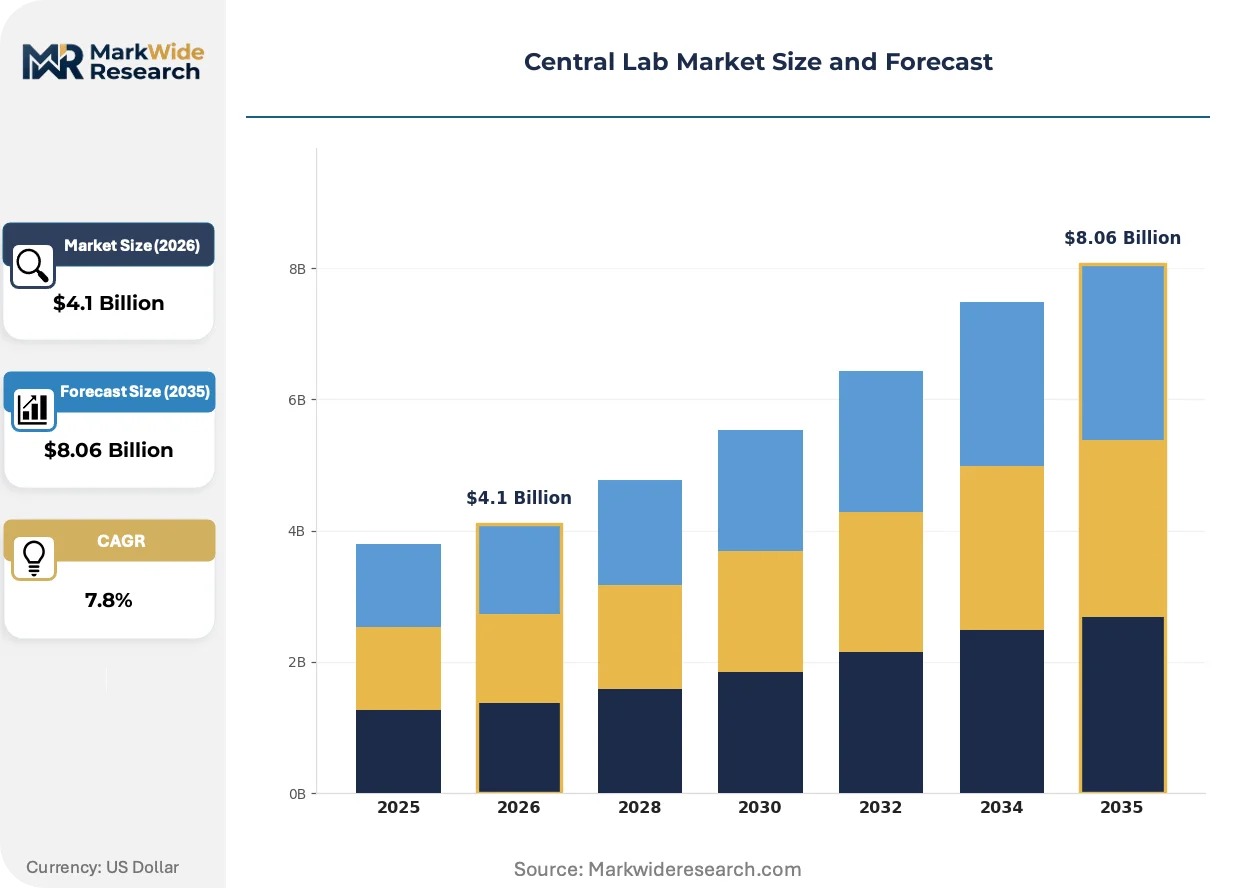
Pharmaceutical sponsors now mandate specimen standardization across dispersed Phase III sites, forcing central labs to absorb compliance costs from intensified FDA Bioresearch Monitoring inspections while maintaining analytical uniformity.
Growth Catalysts
- EU MDR conformity requirements:Notified body scrutiny of diagnostic devices under the Medical Device Regulation compels sponsors to consolidate testing through accredited central labs with established quality management systems.
- Precision medicine protocols:Next-generation sequencing demand from oncology and rare disease trials requires specialized bioanalytical infrastructure that investigator sites cannot replicate locally.
- Phase III trial concentration in the United States:The largest share of pivotal registration studies routes specimens through reference labs to satisfy FDA risk-based inspection priorities.
Market Restraints
- Temperature-controlled logistics costs:Cold chain integrity requirements for biologics specimens impose fixed cost burdens that compress margins on smaller-volume protocols.
- Supply concentration in North American courier networks:Dependence on specialized clinical logistics providers creates vulnerability to capacity constraints during peak trial enrollment periods.
- GLP-GCLP protocol incompatibility:Divergent documentation standards between Good Laboratory Practice and Good Clinical Laboratory Practice frameworks force redundant quality system investments.
Strategic Opportunities
- Direct-to-patient testing models:Decentralized trial architectures enable home-based specimen collection that bypasses traditional investigator site logistics.
- ISO 15189 accreditation expansion:Medical laboratory quality standards adoption in Asia-Pacific jurisdictions opens qualification pathways for multinational study participation.
- Complex biologics bioanalysis:Immunogenicity and cell-based assay demand from gene therapy trials creates service differentiation potential beyond standard clinical chemistry.
Industry Challenges
- GCLP auditor scarcity:Qualified personnel capable of conducting multi-site laboratory qualification audits command premium compensation that strains mid-tier operators.
- Legacy CTMS integration:Central lab data platforms require costly middleware development to synchronize with sponsor clinical trial management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Lab Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biochemistry Analyzers, Hematology Analyzers, Immunoassay Analyzers, Microbiology Analyzers Technology: Mass Spectrometry, Polymerase Chain Reaction, Flow Cytometry, Next-Generation Sequencing End User: Hospitals, Diagnostic Laboratories, Research Institutions, Contract Research Organizations Application: Clinical Diagnostics, Drug Development, Disease Research, Environmental Testing |
| Companies Covered | ACM Global Laboratories, LabConnect, Cerba Research, Eurofins Scientific, Cirion Biopharma Research Inc., ICON plc, Labcorp, Medpace, Frontage Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Lab Market Strategic Shifts & Innovations
Digital specimen tracking and point-of-care analytics are compressing the traditional hub-and-spoke model, redistributing analytical capacity toward patient proximity while preserving regulatory data integrity.
Next-generation sequencing platforms are decentralizing biomarker analysis from core facilities to regional satellite labs. Oncology sponsors adopting companion diagnostic protocols now demand localized turnaround for mutation profiling. This capability dispersion is compressing the traditional specimen consolidation model while maintaining CLIA-equivalent analytical standards.
FDA risk-based inspection scheduling now prioritizes central labs supporting pivotal registration studies. The Bioresearch Monitoring Program's intensified audit frequency forces vendors to pre-position compliance documentation and investigator training records. Late-phase service providers absorb disproportionate regulatory investment compared to early-phase operators.
Sponsor procurement of bundled trial execution services now subordinates standalone central lab contracts to full-service CRO arrangements. Pharmaceutical companies consolidating vendor relationships favor integrated data platforms over discrete analytical outsourcing. This preference shift concentrates volume among operators with captive clinical trial management capabilities.
Central Lab Market Segmentation
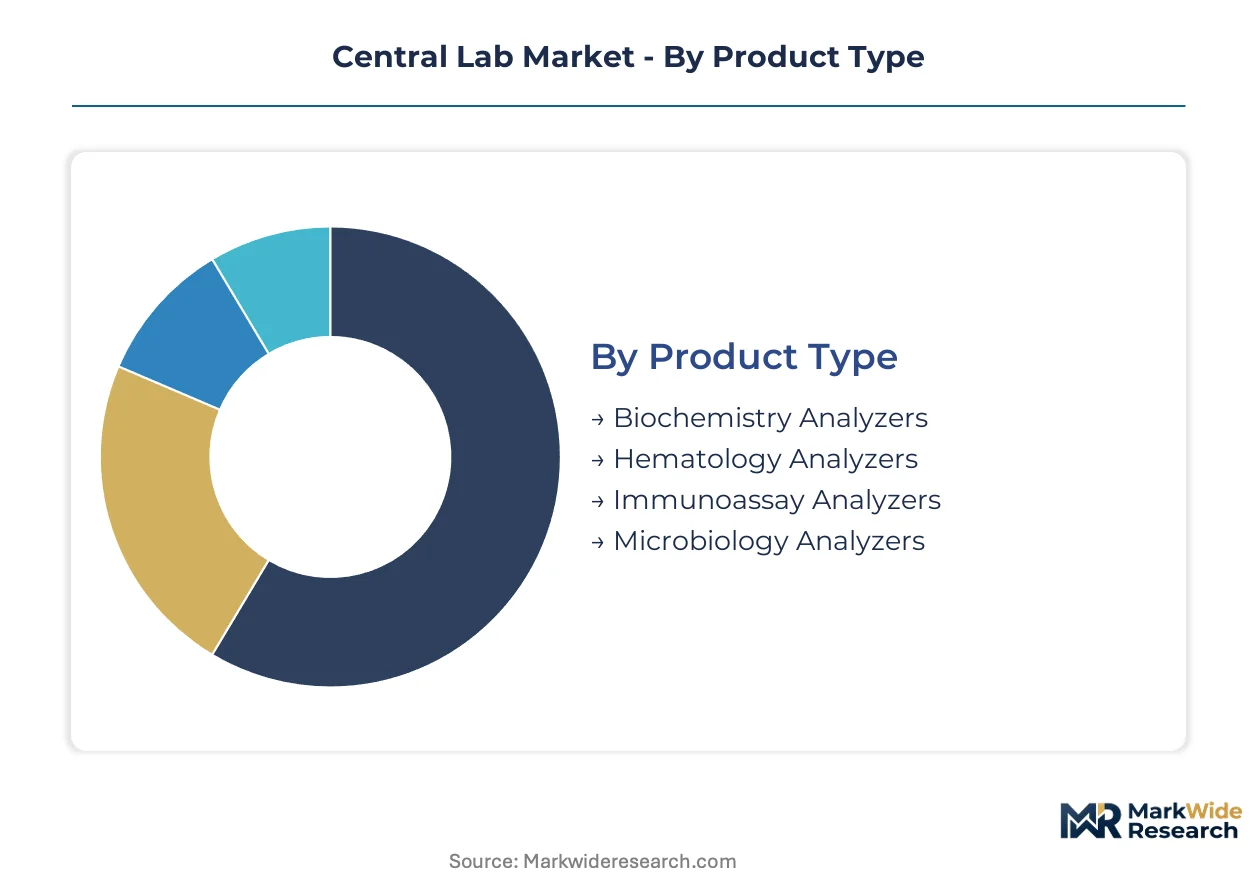
Central lab procurement decisions hinge on analytical throughput requirements, regulatory qualification status, and integration complexity with sponsor data systems. Segmentation reveals where equipment investments concentrate versus where service outsourcing dominates.
Product Type:
Equipment selection tracks specimen volume throughput and biomarker complexity demands from late-phase trials.
- Immunoassay Analyzers:These systems quantify protein biomarkers, hormones, and therapeutic antibodies using antibody-antigen binding detection. Sponsors running Phase III immunogenicity studies in the United States drive installed base expansion, though reagent cost inflation pressures per-test economics.
- Hematology Analyzers:Automated cell counters and differentiators process complete blood count panels for safety monitoring. Demand clusters at high-enrollment oncology sites where cytopenia surveillance requires rapid turnaround, with FDA risk-based inspection priorities favoring validated instrument platforms.
- Biochemistry Analyzers:Clinical chemistry systems measuring electrolytes, enzymes, and metabolites support routine safety panels.
- Microbiology Analyzers:Automated culture and identification systems address infectious disease protocol requirements.
Volume sits with immunoassay platforms; growth tilts toward hematology systems as immuno-oncology protocols proliferate.
Technology:
Technology adoption curves diverge between established analytical methods and emerging precision medicine platforms.
- Next-Generation Sequencing:High-throughput nucleic acid sequencing enables mutation profiling and companion diagnostic validation. Oncology sponsors in the United States require localized turnaround capabilities that regional satellite labs now provide, compressing traditional specimen consolidation timelines while maintaining CLIA-equivalent standards.
- Mass Spectrometry:These systems deliver quantitative bioanalysis of small molecules and peptides with high specificity. Complex biologics development from gene therapy trials creates service differentiation potential as immunogenicity and cell-based assay demand outstrips standard clinical chemistry capacity.
- Polymerase Chain Reaction:Amplification-based nucleic acid detection supports infectious disease and genetic testing protocols.
- Flow Cytometry:Cell sorting and immunophenotyping platforms address hematological malignancy monitoring requirements.
Revenue concentrates in mass spectrometry services; next-generation sequencing platforms are gaining share fastest as precision medicine protocols expand.
End User:
Customer concentration reflects sponsor preferences for bundled trial execution versus discrete analytical outsourcing.
- Contract Research Organizations:Full-service trial operators now subordinate standalone central lab contracts to integrated execution packages. Pharmaceutical companies consolidating vendor relationships favor captive data platforms, concentrating volume among operators with in-house clinical trial management capabilities.
- Diagnostic Laboratories:Reference labs with established quality management systems capture EU MDR-driven consolidation as notified body scrutiny intensifies. These facilities absorb compliance costs from intensified regulatory inspection frequencies while maintaining analytical uniformity across dispersed sites.
- Hospitals:Academic medical centers with investigator-initiated studies require flexible specimen processing arrangements.
- Research Institutions:Early-phase exploratory studies generate demand for specialized bioanalytical capabilities beyond routine clinical chemistry.
Procurement volume flows through CRO channels; qualification pathways are expanding fastest among diagnostic laboratories pursuing ISO 15189 accreditation.
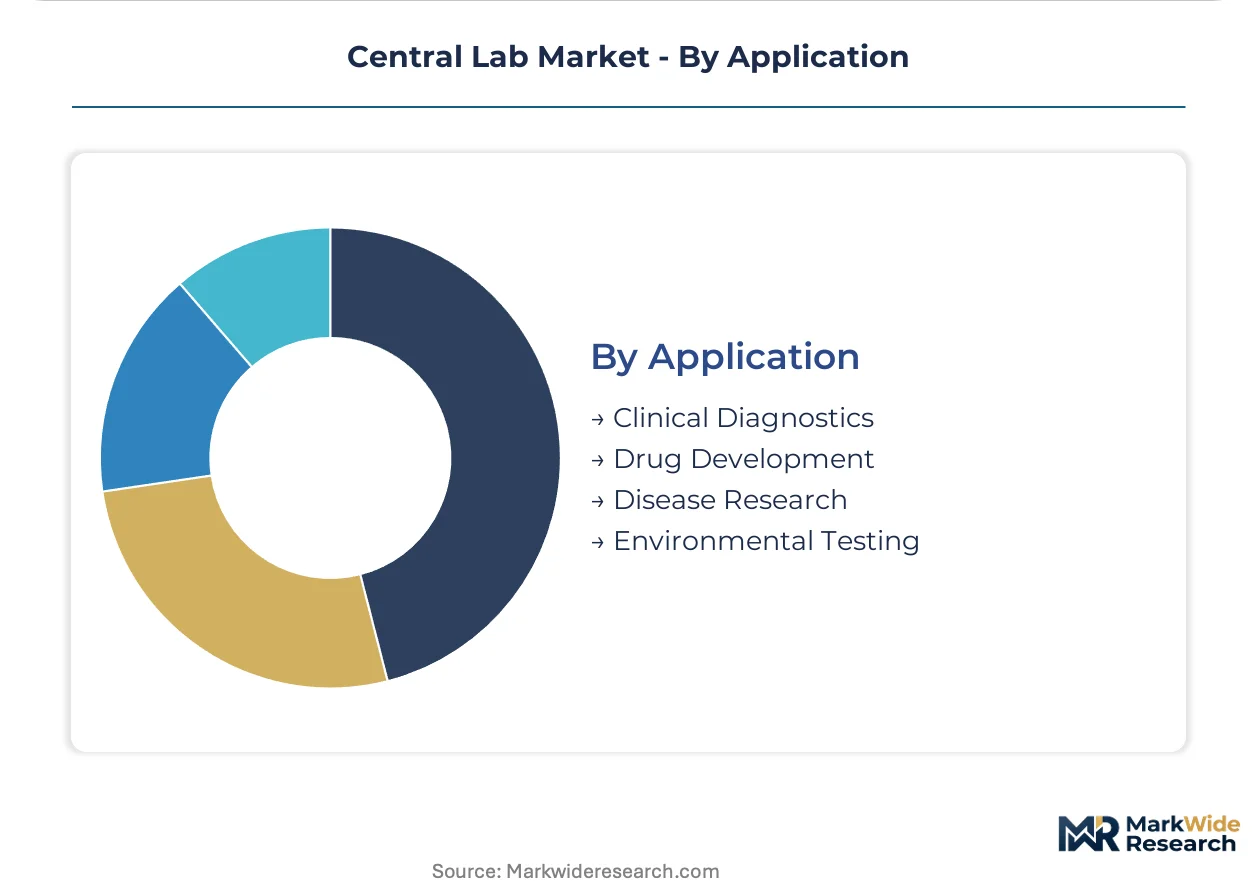
Application:
Application mix shifts with therapeutic area pipelines and regulatory submission timelines.
- Drug Development:Pivotal registration studies mandate standardized biomarker analysis across geographically dispersed Phase III sites. The FDA's Bioresearch Monitoring Program prioritizes labs supporting these trials, forcing vendors to pre-position compliance documentation and absorb disproportionate regulatory investment.
- Clinical Diagnostics:Safety monitoring and efficacy endpoint validation for approved therapeutics generates recurring specimen volumes. Temperature-controlled logistics requirements for biologics specimens impose fixed cost burdens that compress margins on smaller-volume protocols in this segment.
- Disease Research:Exploratory biomarker studies and mechanistic understanding projects require flexible analytical menus.
- Environmental Testing:Bioanalytical support for exposure assessment and toxicology protocols addresses specialized sponsor requirements.
Revenue weight rests with drug development applications; disease research represents the steepest expansion trajectory as decentralized trial architectures enable new specimen collection models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and the Boston-Cambridge corridor concentrate Phase III trial infrastructure that draws specimen volumes from investigator sites nationwide. These zones offer tax incentives for clinical research facilities that standardize biomarker analysis under FDA Bioresearch Monitoring protocols.
United States
Phase III registration studies generate the largest specimen volumes requiring standardized immunoassay and hematology panels. FDA risk-based inspection scheduling prioritizes labs supporting pivotal trials, forcing compliance investment in documentation systems and investigator training. The Research Triangle Park corridor anchors reference lab capacity that serves dispersed multi-site oncology protocols.
Germany
Notified body scrutiny under EU MDR drives sponsor consolidation through accredited diagnostic laboratories with established quality management systems. The country's national pharmaceutical regulator enforces GCLP alignment with EMA guidelines for multinational study participation. The Munich-Frankfurt corridor hosts bioanalytical facilities specializing in complex biologics testing for gene therapy trials.
Switzerland
Precision medicine protocols from oncology sponsors demand specialized next-generation sequencing infrastructure that regional satellite labs now provide. Swissmedic maintains CLIA-equivalent standards for mutation profiling turnaround times that compress traditional specimen consolidation models. The Basel-Zurich corridor concentrates immunogenicity testing capacity for therapeutic antibody development.
United Kingdom
Post-Brexit regulatory divergence forces central labs to maintain dual qualification pathways for EU and UK trial participation. The Medicines and Healthcare products Regulatory Agency enforces distinct GCLP documentation standards that add compliance overhead. The Cambridge-Oxford-London triangle anchors academic medical center networks running investigator-initiated studies with flexible specimen processing needs.
India
ISO 15189 accreditation expansion opens qualification pathways for multinational study participation from Asia-Pacific sponsors. The Central Drugs Standard Control Organization harmonizes laboratory quality standards with ICH guidelines for export-oriented clinical trials. The Hyderabad-Bengaluru corridor hosts diagnostic facilities capturing outsourced safety monitoring from Western pharmaceutical sponsors.
Central Lab Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates volume among operators with integrated clinical trial management capabilities. Tier-one vendors absorb disproportionate regulatory investment to qualify for FDA risk-based inspection priorities on pivotal registration studies. Three archetypes dominate: full-service CROs with captive central lab assets, standalone reference laboratories with specialized bioanalytical capabilities, and academic medical center networks serving investigator-initiated protocols. Competitive moves center on strategic partnerships for temperature-controlled logistics and portfolio diversification into complex biologics testing.
Within the full-service CRO tier, ICON plc and Medpace exemplify operators bundling central lab data directly into clinical trial management platforms. Eurofins Scientific anchors the specialized reference laboratory archetype through its established quality management systems serving European trial sponsors under intensified EU MDR notified body scrutiny. Labcorp occupies a position at the diversified health services end, leveraging captive courier networks to sustain specimen integrity across North American investigator sites.
| Leading Market Players |
|---|
| ACM Global Laboratories |
| LabConnect |
| Cerba Research |
| Eurofins Scientific |
| Cirion Biopharma Research Inc. |
| ICON plc |
| Labcorp |
| Medpace |
| Frontage Laboratories |
| Others |
Cost & Logistics Intelligence
Reagent price inflation for immunoassay consumables cascades through central lab economics, compressing per-test margins at mid-tier operators while Tier-one vendors with captive supply agreements maintain pricing power across premium, standard, and economy service tiers.
Pricing Analysis
Short lead-time premiums for same-day specimen processing command 15-25% markups over standard turnaround contracts, while spot inventory discounts attract smaller sponsors with flexible enrollment timelines. Pricing stratifies across FDA-inspected, ISO 15189-accredited, and non-accredited service tiers, with certification grade driving the primary differentiation. Cost compression in routine clinical chemistry panels is intensifying because sponsor procurement teams now mandate bundled CRO packages that subordinate standalone lab fees. Academic medical centers and investigator-initiated studies exhibit the highest price sensitivity, whereas Phase III registration sponsors prioritize compliance qualification over unit cost.
Supply Chain Analysis
CLIA and CAP certification gating restricts specimen processing capacity to qualified facilities, concentrating analytical equipment manufacturing in the United States, Germany, and Japan. Cold chain logistics draws from specialized clinical courier networks, temperature-controlled packaging systems, and real-time monitoring sensors. Single-source vulnerability in North American courier capacity creates bottlenecks during peak oncology enrollment periods. Distribution runs through hub-and-spoke models anchored at Research Triangle Park and Boston-Cambridge corridors, with regional satellite labs compressing last-mile delivery timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The central lab market functions as a cost-of-compliance story where FDA Bioresearch Monitoring Program intensification erects a barrier-to-entry moat that rewards pre-qualified incumbents while disqualifying undercapitalized challengers.
For Market Incumbents: Hedge against sponsor consolidation into bundled CRO arrangements by deepening bioanalytical capabilities in complex biologics and immunogenicity testing. Acquire regional satellite labs in Switzerland and Germany to capture EU MDR-driven sponsor demand for localized next-generation sequencing turnaround. Vertical integration into temperature-controlled logistics insulates margin pressure from third-party courier rate volatility. For New Entrants and Emerging Players: Launch via ISO 15189 accreditation pathways in India and Southeast Asia to capture Asia-Pacific sponsor demand for multinational study participation. Target investigator-initiated studies at academic medical centers in the United Kingdom and United States where flexible procurement tolerates newer market entrants. Differentiate through specialized cell-based assays for gene therapy protocols that outstrip standard clinical chemistry capacity at established reference labs. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier diagnostic laboratories with established quality management systems in Germany and Switzerland, where EU MDR compliance costs strain undercapitalized operators. Long-term viability over a five-to-ten year window rests on captive integration with clinical trial management platforms rather than standalone analytical service provision. Watch FDA inspection priority shifts toward decentralized trial architectures as the signal indicating hub-and-spoke model disruption.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Accreditation Investment | Notified body conformity assessment opens qualification pathways for European oncology sponsor contracts. |
| Next-Generation Sequencing Satellite Deployment | Regional mutation profiling capability compresses specimen consolidation timelines while maintaining CLIA-equivalent standards. |
| Cold Chain Logistics Integration | Captive courier networks insulate specimen integrity from third-party capacity constraints during peak enrollment. |
| Complex Biologics Bioanalysis Expansion | Immunogenicity and cell-based assay capacity captures gene therapy trial demand beyond routine clinical chemistry. |
| CTMS Platform Data Integration | Direct central lab data synchronization with sponsor clinical trial management systems enables bundled service procurement. |
Research Approach
Multi-period observation of FDA Bioresearch Monitoring inspection frequencies, EU MDR notified body issuance timelines, and sponsor procurement consolidation patterns anchored the trend analysis, supplemented by interviews with central lab operations directors, regulatory affairs leads at pharmaceutical sponsors, CRO procurement executives, diagnostic laboratory quality managers, and clinical logistics coordinators. Secondary validation drew from FDA warning letter databases, EMA GCLP guideline publications, ClinicalTrials.gov protocol specifications, and ISO 15189 accreditation registries. Bottom-up service revenue estimates triangulated against top-down pharmaceutical R&D outsourcing expenditure trends.
Segment-weighting across product type, technology platform, end-user channel, and application area informed the analytical framework across the projection horizon. Treatment phase, biomarker complexity tier, and regional regulatory cluster provided additional segmentation dimensions specific to clinical trial outsourcing economics. CAGRs were derived from regression analysis of historical specimen volume growth against sponsor pipeline expansion, with inputs including Phase III trial initiation rates and precision medicine protocol adoption curves.
Regulatory inspection frequency shifts, decentralized trial architecture adoption, and cold chain logistics cost inflation are the dominant revision risks to modeled outcomes. A model refresh is warranted upon material change in FDA risk-based inspection scheduling priorities or EU MDR notified body capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
LIMS Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
UAE Clinical Laboratory Services Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
Clinical Laboratory Services Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
Histopathology Services Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Global Lab Consumables Market